
 Bahrain Cybersecurity Market | 2026-2036
Bahrain Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Cybersecurity Market Insights
The gap between premium integrated security platforms and commodity point solutions is broadening in Bahrain. Cisco Systems Inc. leverages its global threat intelligence infrastructure to anchor high-end enterprise contracts. Fortinet Inc. competes on consolidated networking-security bundles that reduce operational complexity for mid-market buyers. Beyon Cyber differentiates through localized incident response capabilities tied to Bahrain's telecommunications backbone.
Cybersecurity encompasses technologies, processes, and practices designed to protect networks, devices, programs, and data from attack, damage, or unauthorized access, with next-generation firewalls inspecting traffic at application-layer granularity and encryption standards such as AES-256 securing data in transit and at rest. Managed Security Services dominate current spending as banks and government entities outsource continuous monitoring to address skill shortages. Cloud-Based deployment is expanding fastest among retail and healthcare end users migrating legacy systems. Hybrid architectures sustain margin pools where organizations stricter regulatory requirements with operational flexibility.
The National Cybersecurity Centre and the Central Bank of Bahrain shape procurement through mandatory incident reporting and baseline controls for financial institutions. SAMR-aligned standards and ISO 27001 certifications increasingly gate vendor eligibility in public sector tenders. Stakeholders must weigh sovereign data residency commitments against the scalability of regional cloud security operations.
Market Dynamics
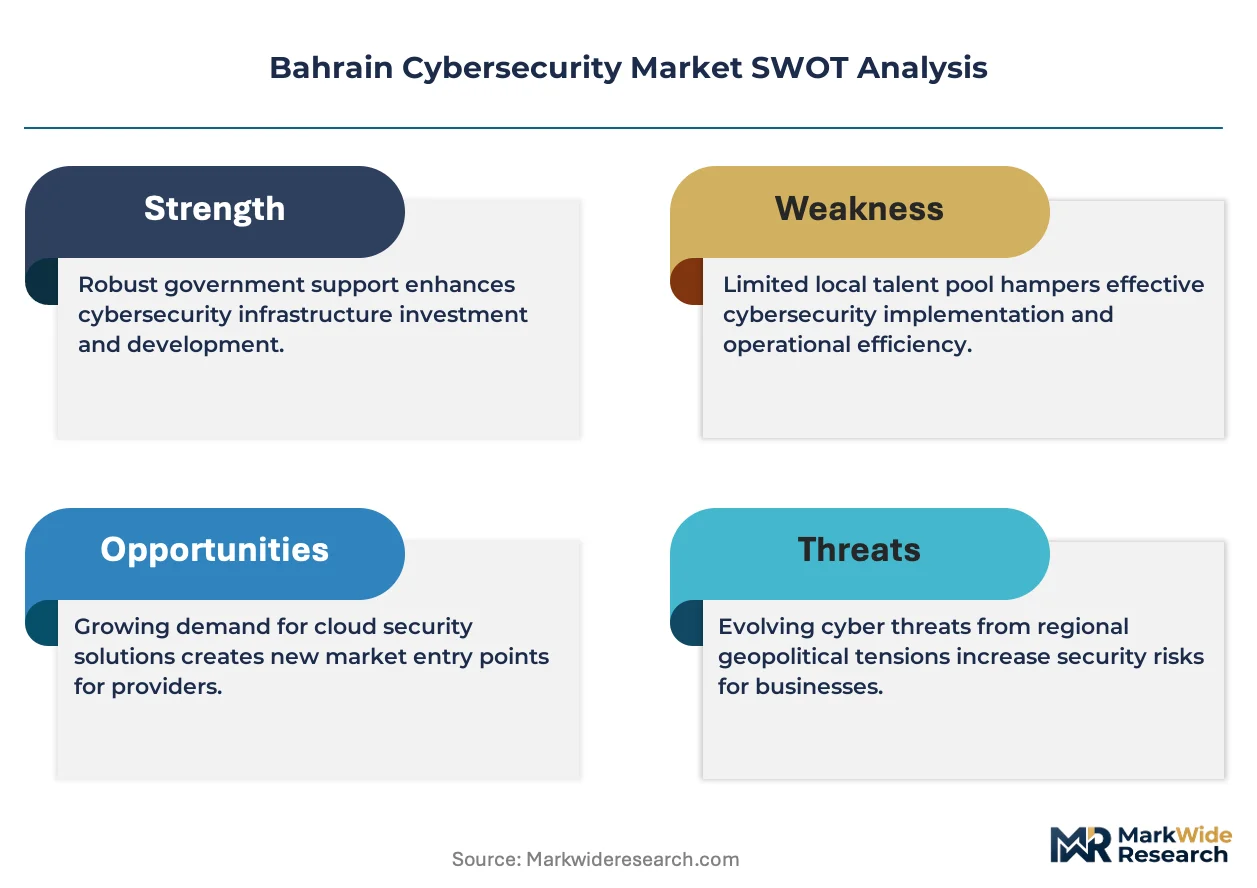
The National Cybersecurity Centre's mandatory incident reporting framework is compressing procurement cycles and forcing critical infrastructure operators toward continuous compliance architectures rather than periodic audits.
Growth Catalysts
- Financial sector outsourcing:Bahrain's banking institutions are delegating security operations to managed service providers to address persistent talent shortages in threat detection and response functions.
- Cloud migration mandates:The Central Bank of Bahrain's baseline control requirements for financial institutions are accelerating displacement of on-premise security stacks with cloud-native alternatives.
- Critical infrastructure protection:The National Cybersecurity Centre's stricter compliance frameworks for operators of essential services are mandating investment in integrated security platforms.
Market Restraints
- Specialized talent scarcity:The shallow pool of certified security architects and incident responders in Manama and the Bahrain Financial Harbour constrains service provider scaling.
- Sovereign data requirements:Data residency commitments for government and banking clients limit utilization of regional cloud security operations without local infrastructure.
- Integration complexity:Legacy banking core systems resist seamless incorporation of modern zero-trust architectures without substantial middleware investment.
Strategic Opportunities
- Healthcare sector penetration:Hospitals and clinics migrating electronic health records present underexposed demand for cloud-based security services outside financial services dominance.
- Retail digitalization:Point-of-sale modernization and e-commerce platform expansion among Bahraini retailers creates demand for payment security and fraud prevention tools.
- Telecom-anchored response:Beyon Cyber's localized incident response capabilities tied to Bahrain's telecommunications backbone demonstrate a replicable model for sovereign security service delivery.
Industry Challenges
- Certification bottlenecks:ISO 27001 and SAMR-aligned standards increasingly gate vendor eligibility in public sector tenders, extending sales cycles for uncertified providers.
- Legacy system coexistence:Hybrid architectures sustaining regulatory compliance with operational flexibility require complex orchestration between on-premise and cloud security controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Cybersecurity Market |
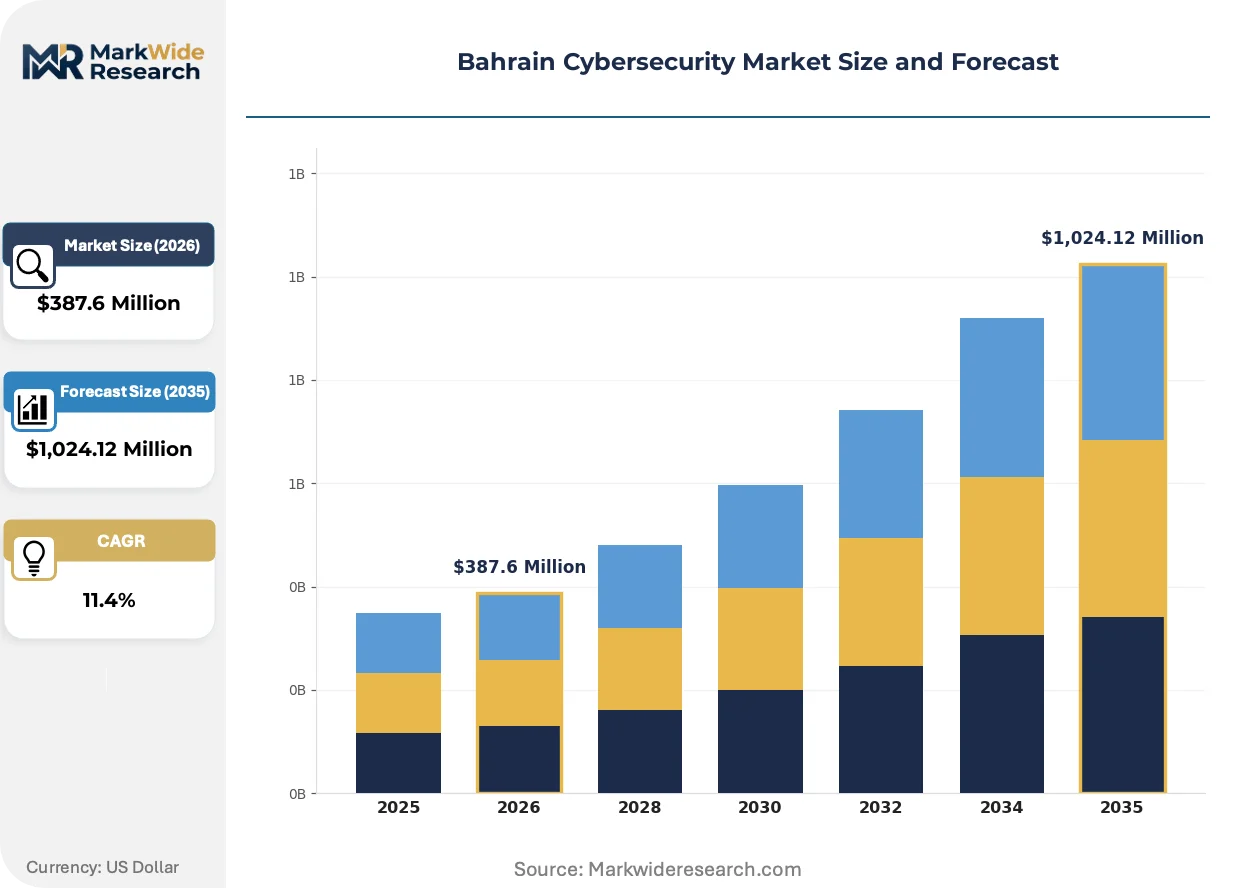
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Security Service, Consulting, Incident Response, Risk Assessment Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Banking, Government, Healthcare, Retail Solution Type: Firewall, Antivirus, Encryption, IDS/IPS |
| Companies Covered | Cisco Systems Inc., Fortinet Inc., Check Point Software Technologies Ltd., IBM Corporation, Microsoft Corporation, Beyon Cyber, Palo Alto Networks, Trend Micro, stc Bahrain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Cybersecurity Market Trends and Innovations
Security architecture in Bahrain is pivoting from perimeter defense to identity-centric models, with artificial intelligence and sovereign cloud infrastructure reshaping procurement priorities across regulated sectors.
Zero-trust network architecture is expanding into Bahraini financial institutions as the dominant security posture. The Central Bank of Bahrain's baseline controls are accelerating adoption among retail banks and investment houses. This shift is compressing demand for traditional perimeter firewalls while expanding requirements for continuous authentication and micro-segmentation.
National Cybersecurity Centre mandates on incident reporting and critical infrastructure protection are tightening operational requirements for operators. Financial institutions and government entities must now maintain continuous monitoring capabilities rather than periodic compliance assessments. Banking sector procurement teams are restructuring vendor evaluation criteria to prioritize real-time threat visibility and automated response.
Buyer preference for consolidated security stacks is displacing point-solution procurement in mid-market segments. Banking and retail entities are favoring integrated platforms that reduce vendor management overhead and interoperability complexity. This concentration is most visible among institutions in Manama seeking to streamline security operations center staffing.
Bahrain Cybersecurity Market Segmentation
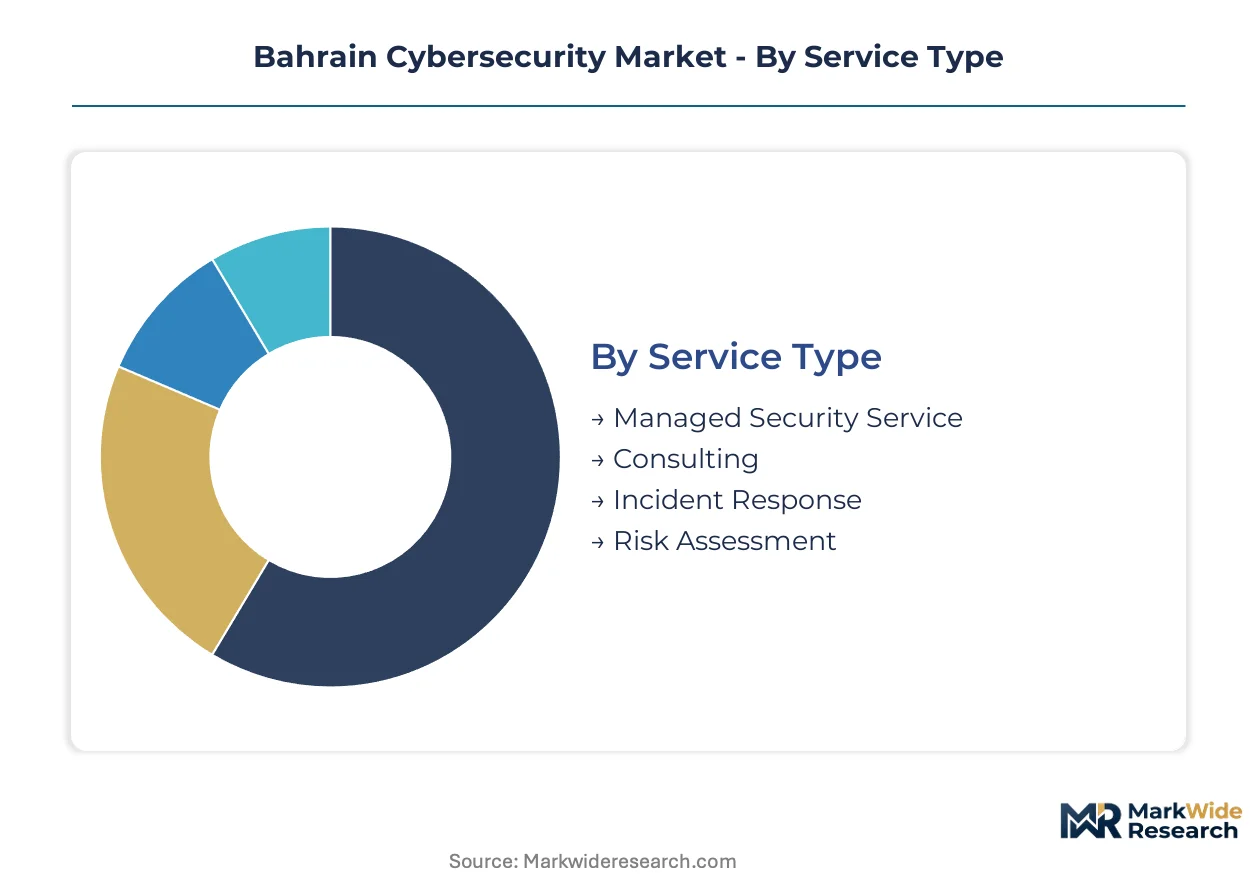
Cybersecurity procurement in Bahrain diverges sharply between standardized commodity offerings and deeply customized sovereign-grade architectures. The National Cybersecurity Centre's compliance mandates fragment demand across four critical dimensions: service delivery models, infrastructure deployment, sector-specific requirements, and technical solution stacks.
Service Type:
Standardized subscription offerings occupy the low end of this spectrum while bespoke sovereign-managed services command premium positioning at the apex.
- Managed Security Service:Continuous threat monitoring and security operations center functions delivered under long-term contracts. Bahrain's banking institutions concentrate demand here, driven by persistent shortages of certified threat hunters and incident responders in Manama.
- Consulting:Advisory engagements spanning security architecture design, compliance roadmap development, and zero-trust transformation planning. The Central Bank of Bahrain's baseline control requirements accelerate procurement from financial institutions undergoing digital infrastructure modernization.
- Incident Response:Retained and emergency breach containment services with localized Bahraini presence.
- Risk Assessment:Periodic vulnerability evaluations and penetration testing against SAMR-aligned standards.
Leading the category by volume: Managed Security Service. Growing fastest: Consulting.
Deployment Model:
Cost tiering separates capital-intensive on-premise builds from operational-expense cloud alternatives, with hybrid architectures capturing margin in regulated environments.
- Cloud-Based:Native security controls delivered through hyperscale infrastructure with elastic capacity scaling. Healthcare providers and retail chains migrating electronic health records and e-commerce platforms drive steepest expansion trajectory here.
- Hybrid:Orchestrated security stacks spanning sovereign on-premise assets and regional cloud capacity. Bahrain's banking sector sustains this segment through data residency requirements that prohibit pure cloud deployment for core transaction systems.
- On-Premises:Dedicated hardware appliances and software licenses deployed within customer-controlled facilities.
- SaaS:Lightweight subscription security tools targeting mid-market buyers with limited internal security operations capabilities.
Deployment gravity centers on Hybrid for financial services. Cloud-Based climbs fastest among non-banking verticals.
End User:
Application criticality stratifies this category from payment system operators through to emerging digital commerce platforms.
- Banking:Retail banks, investment houses, and Islamic finance institutions operating under Central Bank of Bahrain supervision. This segment concentrates the highest security spending per entity, driven by mandatory incident reporting and baseline control frameworks.
- Government:Ministries and critical infrastructure operators falling under National Cybersecurity Centre jurisdiction. Compliance mandates here prioritize sovereign data residency and localized incident response capabilities.
- Healthcare:Hospitals and clinics migrating electronic health records to digital platforms.
- Retail:Point-of-sale modernization and e-commerce security for Bahraini merchants.
Banking dominates absolute spending. Healthcare represents the fastest-climbing opportunity as digitalization accelerates.
Solution Type:
Technology maturity separates legacy perimeter defenses from identity-centric and encryption-heavy modern stacks.
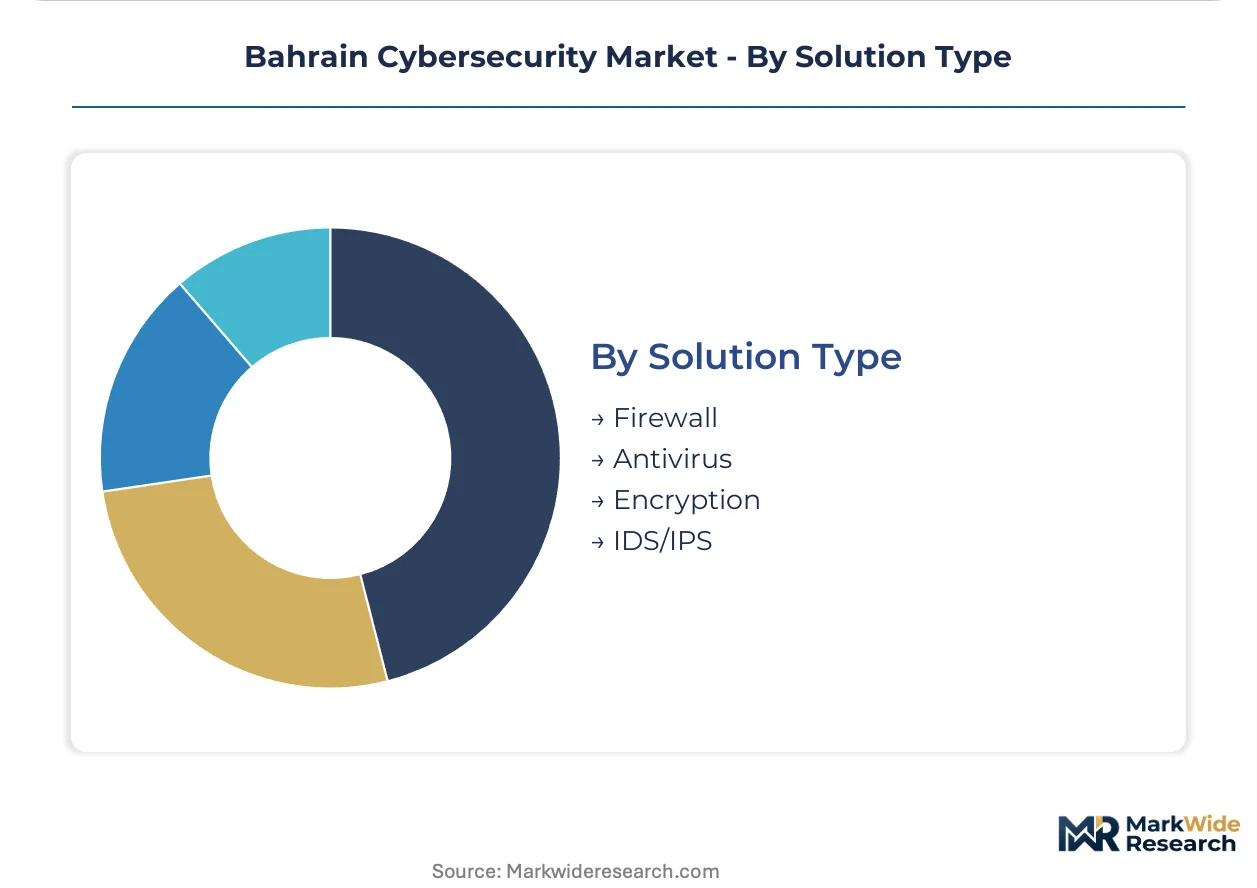
- Firewall:Next-generation appliances with application-layer inspection and micro-segmentation capabilities. Demand compresses here as zero-trust architectures displace traditional perimeter-centric procurement in Manama financial institutions.
- Encryption:Data protection standards including AES-256 for transit and at-rest security. Regulatory mandates from the National Cybersecurity Centre and Central Bank of Bahrain sustain investment despite commoditization pressures.
- Antivirus:Endpoint detection and response tools with behavioral analysis capabilities.
- IDS/IPS:Network intrusion detection and prevention systems for traffic monitoring.
Encryption leads by procurement volume. Firewall contracts face displacement pressure from integrated platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manama and the Bahrain Financial Harbour concentrate the kingdom's cybersecurity procurement, with banking institutions and government entities driving demand for sovereign-grade security architectures.
Capital Governorate
The Capital Governorate hosts the densest concentration of financial institutions requiring managed security services. The National Cybersecurity Centre mandates continuous compliance monitoring for operators of essential services headquartered here. Beyon Cyber anchors localized incident response capabilities through infrastructure tied to Bahrain's telecommunications backbone.
Muharraq Governorate
Muharraq's healthcare facilities are accelerating electronic health record migration, creating underexposed demand for cloud-based security services. The Central Bank of Bahrain's baseline controls extend to medical payment systems processing insurance claims. Hospitals in this governorate prioritize encryption standards and data residency commitments for patient records.
Northern Governorate
The Northern Governorate's retail and logistics corridors are digitizing point-of-sale systems and e-commerce platforms. Retailers here face payment security requirements under SAMR-aligned standards for consumer data protection. Shopping complexes and distribution centers are consolidating vendor management through integrated security stacks.
Southern Governorate
The Southern Governorate's industrial zones and port facilities fall under critical infrastructure protection mandates. The National Cybersecurity Centre's stricter compliance frameworks apply to logistics operators and energy facilities in this region. Industrial control system security and supply chain monitoring dominate procurement priorities.
Bahrain Cybersecurity Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the service delivery spectrum, with sovereign-managed capabilities commanding pricing power over standardized subscription offerings. The vendor base stratifies into three tiers: global platform providers with threat intelligence infrastructure, regional specialists with localized response capabilities, and commodity point-solution vendors facing consolidation pressure. Strategic moves concentrate on portfolio consolidation to reduce buyer vendor management overhead, and sovereign data residency commitments to satisfy government and banking procurement requirements.
Within the global platform tier, Cisco Systems Inc. and Fortinet Inc. occupy positions defined by their infrastructure scale and consolidated networking-security bundles. Beyon Cyber anchors the sovereign-specialist segment, exemplifying the telecommunications-anchored response model that satisfies National Cybersecurity Centre mandates for localized incident handling. These three entities represent the competitive archetypes reshaping vendor selection criteria among Bahraini financial institutions and critical infrastructure operators.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Fortinet Inc. |
| Check Point Software Technologies Ltd. |
| IBM Corporation |
| Microsoft Corporation |
| Beyon Cyber |
| Palo Alto Networks |
| Trend Micro |
| stc Bahrain |
| Others |
Pricing and Supply Chain Analysis
National Cybersecurity Centre data residency mandates gate both qualified supply and premium-tier pricing access for vendors serving Bahrain's banking and government sectors. Sovereign cloud infrastructure commitments compress vendor eligibility while sustaining margin premiums for localized service delivery.
Pricing Analysis
Value-based pricing anchored to threat containment outcomes and system uptime guarantees dominates managed security service contracts. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-grade incident response from commodity monitoring subscriptions. Price differentiation hinges on ISO 27001 certification status and localized Bahraini response team presence. Cost compression in the standard tier is intensifying because regional cloud providers are expanding footprint without sovereign data commitments. Mid-market retail buyers exhibit highest price sensitivity; Central Bank of Bahrain-supervised institutions show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale financial institution demand, while tier-two system integrators serve mid-market healthcare and retail buyers. Hardware appliance supply concentrates in Taiwan, the United States, and Israel for next-generation firewall and encryption modules. Software-defined security controls draw from development centers in India, Ireland, and Singapore. Single-source vulnerability in specialized threat intelligence feeds creates supply chain risk. Distribution runs through Bahrain's telecommunications backbone operators for sovereign-compliant service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's cybersecurity market operates as a vertical-integration race, with players pursuing downstream control over localized incident response capabilities to satisfy National Cybersecurity Centre mandates.
For Market Incumbents: Extend sovereign data infrastructure investments to defend against hyperscale cloud entrants lacking Bahraini residency commitments. Deepen integration with the national telecommunications backbone to harden localized response advantages. Certification maintenance in SAMR-aligned standards preserves eligibility for government tenders. For New Entrants and Emerging Players: Healthcare sector channel partners represent the most penetrable entry vector, with hospitals accelerating electronic health record migration underexposed to financial services-dominated vendor relationships. Target Muharraq Governorate healthcare clusters with cloud-native encryption and data residency bundles. Position through medical device distributors already embedded in hospital procurement workflows. For Investors and Strategic Acquirers: Central Bank of Bahrain baseline control enforcement acceleration is the leading indicator that compliance automation platforms will command premium valuations. Sovereign-managed service providers with existing National Cybersecurity Centre relationships represent the preferred acquisition archetype. Watch for mandatory incident reporting threshold reductions as the inflection signal for continuous monitoring demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Buildout | Local data residency satisfies National Cybersecurity Centre mandates for banking and government clients. |
| Managed Security Service Expansion | Continuous monitoring contracts address certified talent shortages in Manama and Bahrain Financial Harbour. |
| Certification Investment in SAMR Standards | ISO 27001 and aligned credentials gate vendor eligibility in public sector procurement cycles. |
| Healthcare Sector Partnership Development | Electronic health record migration creates underexposed demand outside financial services dominance. |
| Telecom-Anchored Response Capability | Beyon Cyber's infrastructure-tied model demonstrates replicable sovereign service delivery architecture. |
Research Methodology
Central Bank of Bahrain regulatory filings, National Cybersecurity Centre compliance circulars, and SAMR-aligned standards documentation formed the secondary backbone for market sizing and mandate tracking. Primary interviews with CISOs at retail banks, government procurement officers, healthcare IT directors, and managed security service executives validated demand patterns and vendor selection criteria. Bottom-up contract value analysis triangulated against top-down sector spending estimates derived from banking IT disclosure patterns.
Historical trendline analysis of managed security service contract values and cloud security deployment ratios informed projection modeling across the analysis window. Segmentation dimensions included service delivery model, deployment architecture, end-user vertical, and solution technology stack. CAGRs were derived from regression analysis of banking sector outsourcing intensity and healthcare digitalization pace. Forecast inputs incorporated Central Bank baseline control enforcement timelines and National Cybersecurity Centre critical infrastructure designation expansions.
Several conditions sit outside the modeled scope, including cyberattack frequency scenarios, regional geopolitical disruptions affecting data routing, and sovereign cloud infrastructure investment delays. Forecasts reflect assumptions about regulatory enforcement consistency and talent pipeline development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Education Data Security Market
Cybersecurity
Global Breach and Attack Simulation Market
Cybersecurity
Saudi Arabia Cybersecurity Market
Cybersecurity
Data Protection Market
Cybersecurity
Greece Cybersecurity Market
Cybersecurity
Enterprise Firewall Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
V2X Cybersecurity Market
Cybersecurity
IoT Security Market
Cybersecurity
Global Quantum Cryptography Solutions Market
Cybersecurity
Asia Pacific Data Exfiltration Market
Cybersecurity
Global Sensitive Data Discovery Market
Cybersecurity
Cloud Network Security Market
Cybersecurity
Big Data Security Market