
 Passenger Ticket Vending Machine Market | 2026-2036
Passenger Ticket Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Ticket Vending Machine Market Analytics
Multi-source component procurement is consolidating around fewer certified subsystem vendors. Siemens leverages its rail signaling heritage to anchor integrated TVM deployments across European networks. Cubic Corporation competes through transit payment platform convergence, while Scheidt & Bachmann specializes in modular hardware architectures that simplify field upgrades.
A passenger ticket vending machine is an electromechanical self-service terminal that dispenses travel credentials, processes fare payments, and validates entry through integrated readers, barcode printers, and secure cash handling modules. These machines operate in high-throughput environments where mean time between failures must exceed 50,000 cycles to maintain transit schedule integrity. Smart kiosk configurations incorporating biometric verification are capturing margin pools as operators prioritize fraud reduction over basic touchscreen models. Contactless payment technology leads transaction volume growth, while QR code scanning sustains relevance in cost-sensitive deployments across emerging transit networks.
FCC certification governs wireless payment modules in US installations, while EBA and national rail safety bodies enforce electromagnetic compatibility standards across European deployments. CE marking requirements for outdoor installations shape enclosure design and thermal management specifications. Stakeholders must monitor how open-loop payment standards from EMVCo and local transit authorities reshape hardware authentication requirements and software certification timelines.
Market Dynamics
Contactless payment mandates from transit authorities are compressing hardware refresh cycles and forcing operators to retire legacy cash-heavy terminals before end-of-life. This regulatory pressure concentrates procurement among subsystem vendors certified for EMVCo open-loop standards.
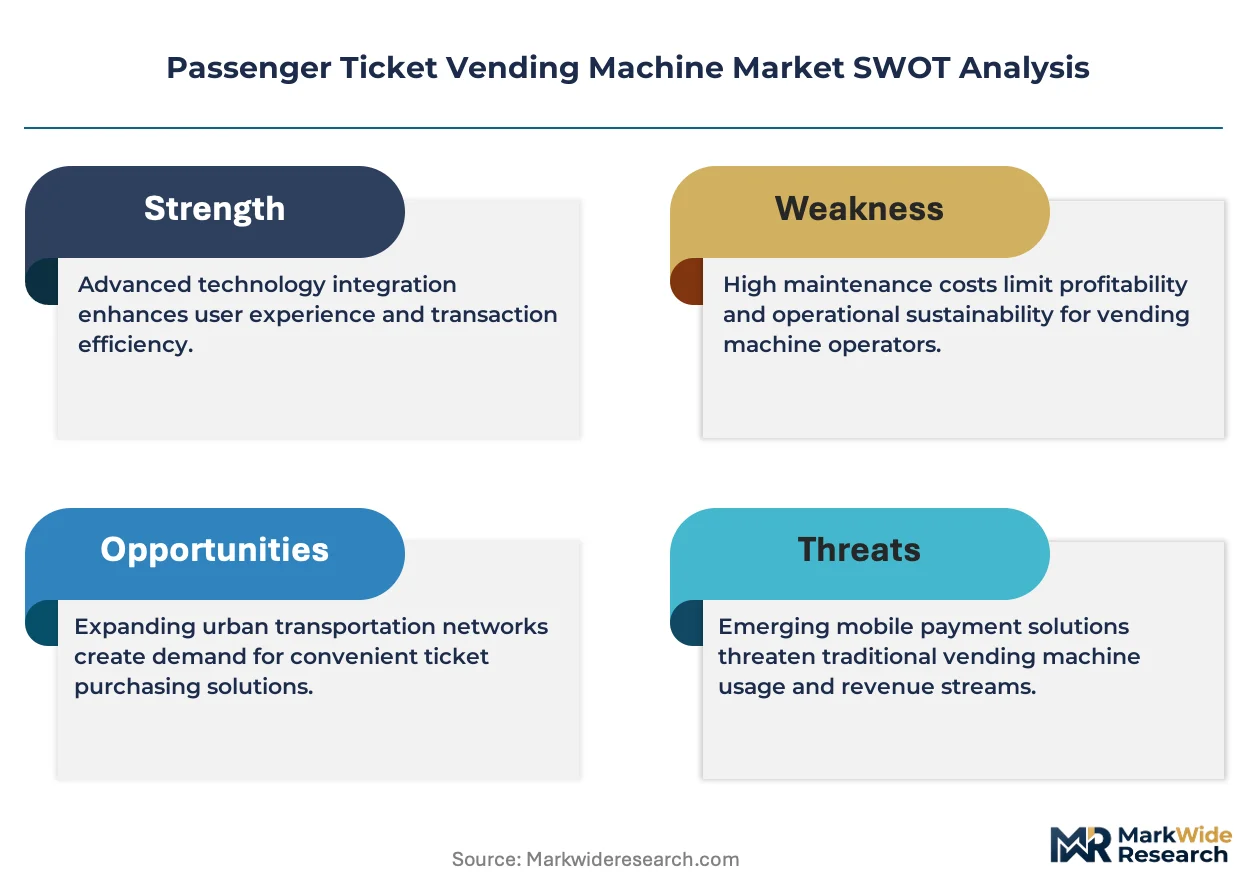
Growth Catalysts
- EMVCo Contactless Mandates:Transit authorities in France, Germany, and the United Kingdom now require open-loop payment acceptance, forcing station upgrades.
- Urban Rail Expansion:Metro operators in China's tier-one cities are adding self-service infrastructure to accommodate passenger volume growth.
- Biometric Verification Modules:Fingerprint and facial recognition hardware is reducing fare evasion rates in high-throughput environments.
Market Restraints
- Semiconductor Supply Concentration:Secure element chips for payment modules source primarily from Taiwanese foundries, creating single-point vulnerability.
- CE Marking Complexity:Outdoor enclosure thermal management requirements extend certification timelines for European deployments.
- Mobile App Substitution:Smartphone-based ticketing platforms bypass physical TVM infrastructure entirely in younger demographics.
Strategic Opportunities
- India's Station Modernization:The PLI scheme for electronics manufacturing incentivizes local assembly of payment terminals for Indian Railways.
- Platform-as-a-Service Models:Operators in Japan are leasing integrated TVM systems rather than capital purchase, shifting revenue to recurring service fees.
- 5G-Enabled Remote Diagnostics:South Korean transit networks are deploying cellular-connected units that enable predictive maintenance and reduce field service costs.
Industry Challenges
- FCC Certification Backlogs:Wireless payment module approvals in the United States currently exceed 180 days, delaying deployment schedules.
- Legacy System Integration:Proprietary fare collection protocols from 1990s-era installations require expensive middleware development for new hardware compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Ticket Vending Machine Market |
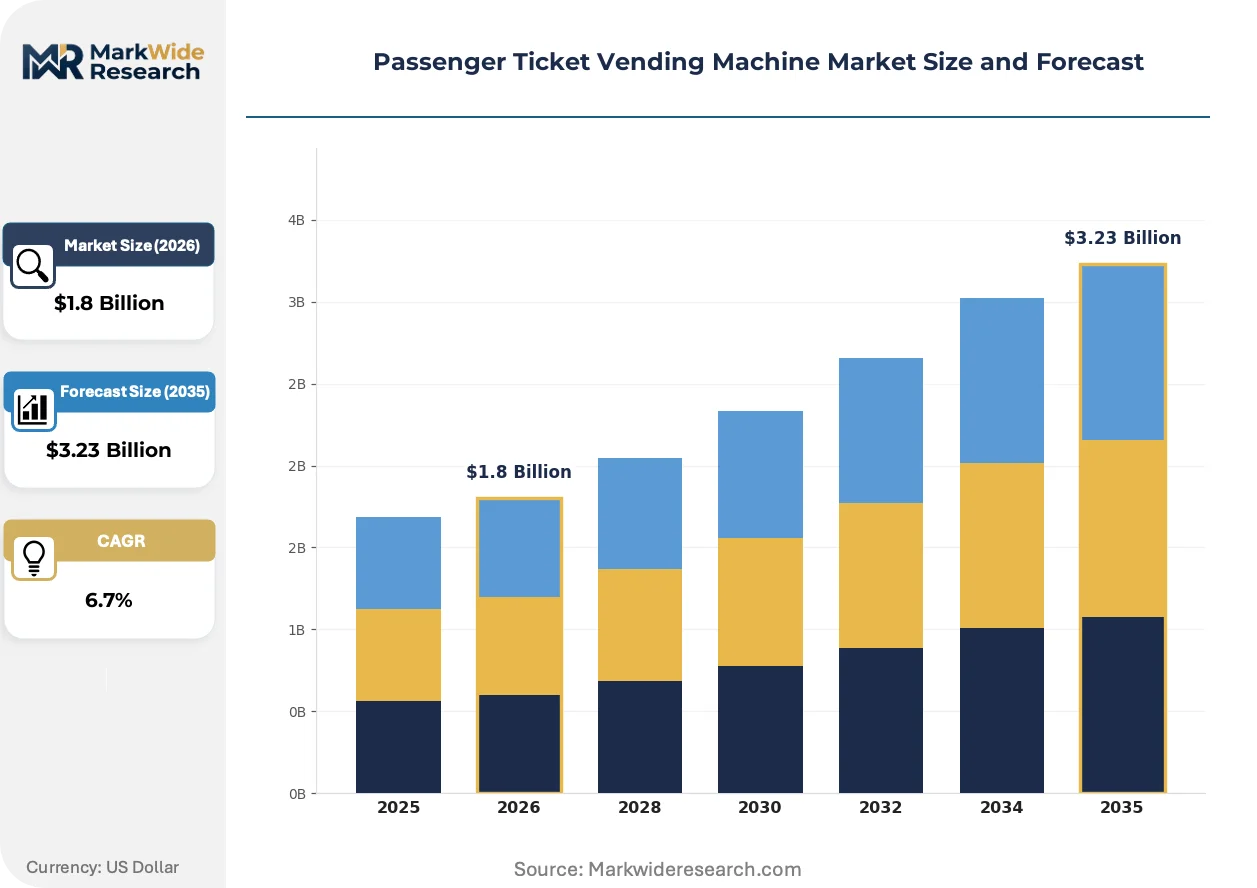
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Machines, Integrated Systems, Mobile Kiosks, Smart Kiosks Technology: Touchscreen, Contactless Payment, QR Code Scanning, Biometric Verification End User: Rail Operators, Airports, Public Transit Systems, Event Venues Installation: Indoor, Outdoor, Stationary, Mobile |
| Companies Covered | Nabtesco Corporation, Integra Dbs, Omron Corporation, Scheidt & Bachmann, Siemens, Apex Transit Technologies, Parkeon, Cubic Corporation, Genfare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Ticket Vending Machine Market Evolving Landscape
Hardware architectures are converging around modular subsystems that separate payment processing, credential printing, and cash handling into field-replaceable units. This shift reduces mean time to repair and extends operational life cycles.
Computer vision-based passenger flow analytics is automating real-time capacity management at TVM clusters. Singapore's Land Transport Authority deploys camera arrays that detect queue lengths and dynamically redirect passengers to underutilized terminals. The technology is automating labor-intensive station monitoring functions previously performed by platform staff.
Europe's EBA electromagnetic compatibility standards now mandate shielding specifications for contactless payment antennas in rail environments. Manufacturers must redesign RF modules to prevent interference with train control systems. German KBA certification requirements are driving enclosure redesigns that add cost but enable cross-border deployment acceptance.
Buyer procurement patterns are consolidating around framework agreements that bundle hardware, software, and maintenance across multi-year terms. French RATP and London's TfL now issue single-source contracts covering entire station networks. This shift favors vendors with integrated service capabilities over component specialists in Western European markets.
Passenger Ticket Vending Machine Market Segmentation
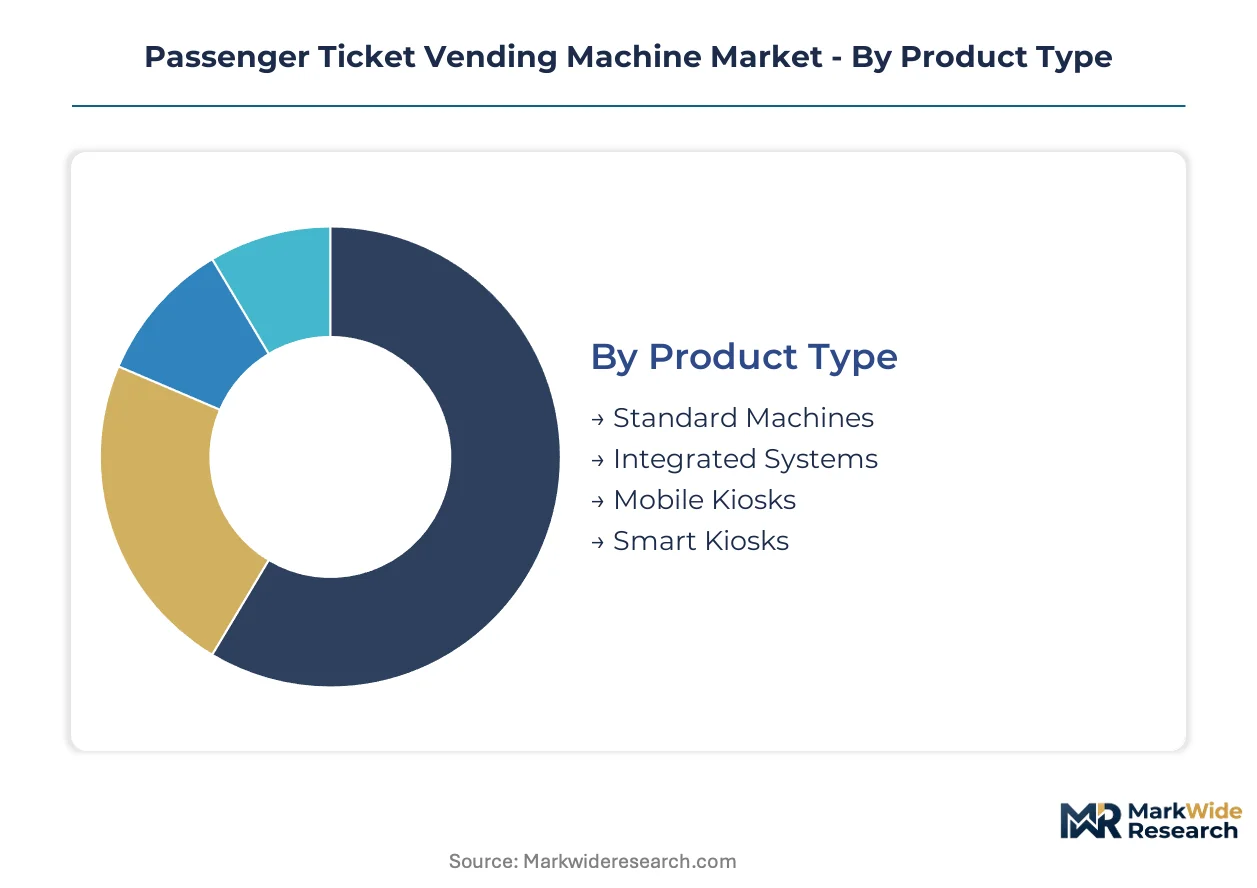
TVM procurement patterns diver sharply between operators seeking standalone terminals versus those embedding machines within broader station automation ecosystems. Segmentation reveals how hardware specifications, payment modalities, and deployment environments reshape vendor competitive position.
Product Type:
Standalone units dominate low-complexity deployments where retrofit compatibility outweighs integration depth; embedded configurations anchor new-build stations with unified control systems.
- Standard Machines:Electromechanical terminals with cash handling, card readers, and thermal printers housed in steel enclosures rated for 100,000+ duty cycles. Demand clusters in India's tier-two railway stations where the PLI scheme for electronics manufacturing incentivizes local assembly over imported alternatives.
- Integrated Systems:TVM modules fused with gate-line controllers, passenger information displays, and central station management platforms through Ethernet backbones. London's TfL and Paris RATP procure these exclusively, bundling hardware, software, and maintenance across multi-year framework agreements.
- Mobile Kiosks:Battery-powered units on wheeled bases for temporary deployment during construction or special events. Deployed at Munich's Oktoberfest and Tokyo's seasonal festival corridors.
- Smart Kiosks:AI-enabled terminals with computer vision queue detection and predictive maintenance telemetry. Singapore's Land Transport Authority deploys camera arrays that redirect passengers to underutilized terminals.
Volume placements concentrate in Standard Machines; the faster expansion belongs to Integrated Systems.
Technology:
Payment interface selection directly determines hardware refresh timing and regulatory certification burden across operator fleets.
- Touchscreen:Resistive or projected capacitive displays with anti-vandal glass rated for 50,000+ activation cycles. Remains prevalent in cost-sensitive emerging networks across Southeast Asia.
- Contactless Payment:NFC readers certified to EMVCo open-loop standards with secure element chips sourced primarily from Taiwanese foundries. France, Germany, and the United Kingdom now mandate this capability, compressing hardware replacement cycles for legacy cash-heavy terminals.
- QR Code Scanning:2D barcode imagers supporting proprietary transit apps and third-party payment platforms. Sustains relevance in China's tier-one cities where station modernization programs are most advanced.
- Biometric Verification:Fingerprint sensors and facial recognition cameras with liveness detection reducing fare evasion in high-throughput environments. South Korean transit networks deploy these for account-based ticketing linked to national ID systems.
Contactless Payment captures the largest installed base; Biometric Verification is climbing the fastest as fraud reduction priorities reshape procurement criteria.
End User:
Operational environment dictates enclosure specifications, transaction velocity requirements, and integration complexity with existing infrastructure.
- Rail Operators:Heavy-duty terminals with banknote recyclers and coin hoppers processing 300+ transactions hourly. European deployments must satisfy EBA electromagnetic compatibility standards and German KBA certification for cross-border acceptance.
- Airports:Multilingual interfaces with passport scanner integration and baggage allowance calculators. Dubai International and Changi Singapore specify these for seamless ground transport connections.
- Public Transit Systems:Bus and metro-integrated units with ruggedized casings for high-vibration environments. FCC certification for wireless payment modules in US installations currently exceeds 180 days.
- Event Venues:Temporary-deployment kiosks with rapid-configuration software for single-day sporting or concert events. Wembley Stadium and Melbourne Cricket Ground lease these under platform-as-a-service arrangements.
Procurement volume favors Rail Operators; Airports show the steepest expansion trajectory as multimodal connectivity investments accelerate.
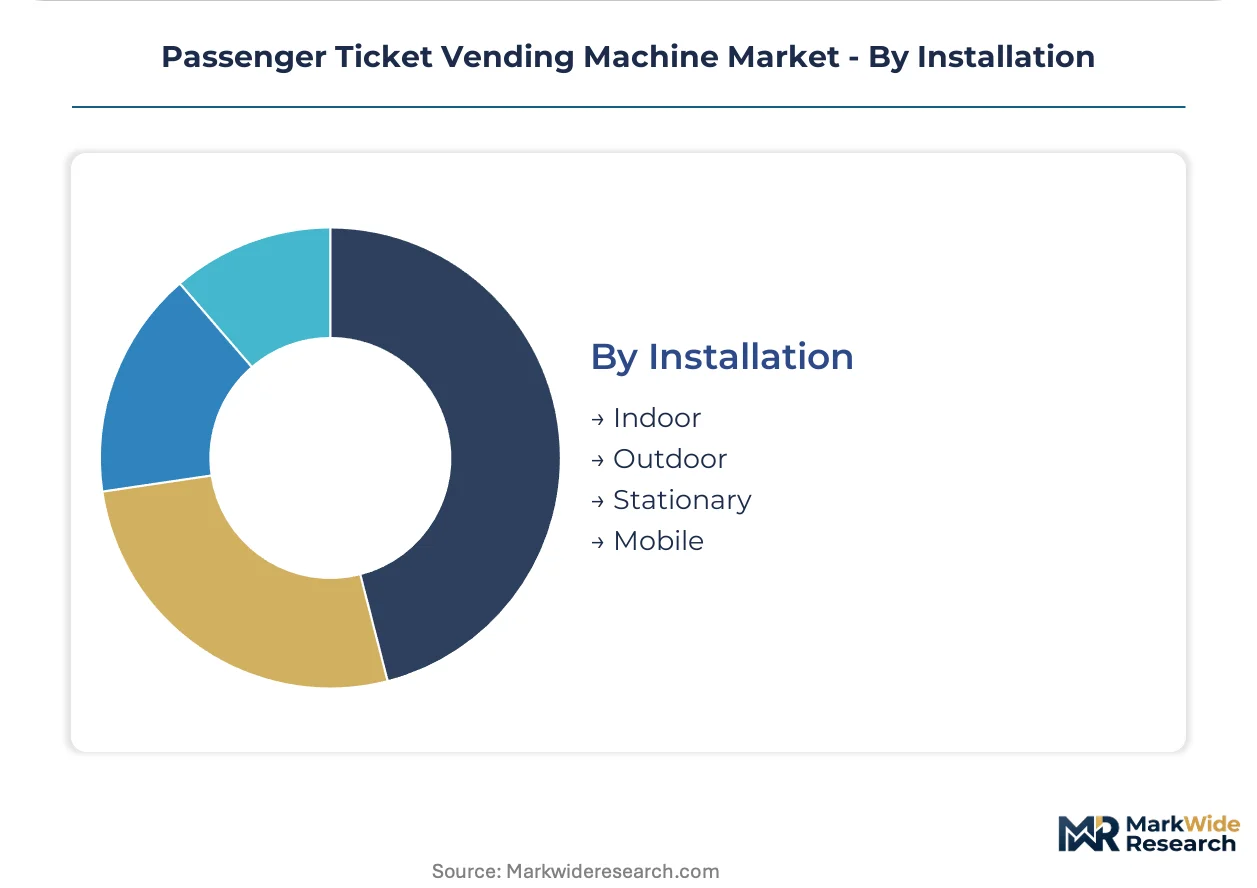
Installation:
Environmental exposure determines thermal management, ingress protection ratings, and structural mounting requirements.
- Indoor:Climate-controlled deployments with IP54-rated enclosures sufficient for concourse humidity and dust. CE marking requirements for European indoor installations are streamlined relative to outdoor variants.
- Outdoor:IP65+ sealed units with heater elements for sub-zero operation and sun-readable displays for direct exposure. Extended certification timelines in Europe shape vendor delivery schedules.
- Stationary:Permanent concrete-anchored installations with hardwired power and fiber connectivity. Dominates urban metro expansions in China's tier-one cities.
- Mobile:Trailer-mounted or skid-based units repositioned across construction phases or seasonal demand patterns. Japan's operators increasingly lease these under recurring service fee structures rather than capital purchase.
Stationary configurations hold the majority position; Mobile installations are gaining share fastest as Japanese leasing models diffuse to Australian and Canadian operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban metro expansion concentrates procurement in China's tier-one cities, where station modernization programs advance fastest. Transit authorities in France, Germany, and the United Kingdom now mandate EMVCo open-loop payment acceptance. India's PLI scheme for electronics manufacturing is reshaping regional supply chains for railway infrastructure.
China
Beijing and Shanghai metro operators are deploying integrated TVM systems with unified control platforms across new-build stations. MIIT certification requirements govern wireless payment module specifications for rail environments. The Yangtze River Delta cluster anchors procurement volume as Hangzhou and Nanjing expand self-service infrastructure.
Germany
KBA certification requirements for cross-border deployment acceptance are driving enclosure redesigns that add manufacturing cost. EBA electromagnetic compatibility standards mandate shielding specifications for contactless payment antennas in Deutsche Bahn installations. Bavaria's Munich transit network exemplifies framework agreements bundling hardware, software, and maintenance.
United States
FCC certification for wireless payment modules currently exceeds 180 days, compressing deployment schedules for transit agencies. Legacy proprietary fare collection protocols from 1990s-era installations require expensive middleware development. New York MTA and Chicago CTA concentrate procurement among subsystem vendors certified for open-loop standards.
India
The PLI scheme for electronics manufacturing incentivizes local assembly of payment terminals for Indian Railways. BIS standards govern enclosure durability specifications for high-vibration environments. Maharashtra's Mumbai Metro and Delhi-NCR networks are prioritizing biometric verification modules to reduce fare evasion.
Japan
METI guidelines encourage platform-as-a-service leasing models that shift operator expenditure from capital purchase to recurring service fees. JIS standards shape thermal management specifications for outdoor installations. Tokyo's JR East and Osaka Metro are deploying 5G-enabled units with predictive maintenance telemetry.
Passenger Ticket Vending Machine Market Competitive Landscape
Framework agreement consolidation dominates the current landscape as procurement shifts toward multi-year bundled contracts. The vendor base separates into three tiers: integrated platform providers with rail signaling heritage, modular hardware specialists, and regional payment terminal fabricators. Siemens leverages its European rail infrastructure presence to anchor integrated deployments. Cubic Corporation competes through transit payment platform convergence. Scheidt & Bachmann occupies the modular architecture segment with field-upgradeable subsystem designs.
Within the integrated platform tier, Siemens and Cubic Corporation exemplify vendors bundling hardware, software, and maintenance across entire station networks. Scheidt & Bachmann represents the modular specialist archetype, occupying a position where field-replaceable units reduce mean time to repair. Nabtesco Corporation and Omron Corporation sit within the precision electromechanical component layer, supplying certified subsystems to larger integrators. Apex Transit Technologies and Genfare occupy positions in the North American transit payment terminal segment. Parkeon represents the European kiosk and parking payment heritage that extends into rail TVM deployments.
| Leading Market Players |
|---|
| Nabtesco Corporation |
| Integra Dbs |
| Omron Corporation |
| Scheidt & Bachmann |
| Siemens |
| Apex Transit Technologies |
| Parkeon |
| Cubic Corporation |
| Genfare |
| Others |
Value Network & Pricing Analysis
Captive integration into secure element chip sourcing anchors both supply security and pricing power for TVM manufacturers serving EMVCo-mandated deployments. Siemens and Cubic Corporation leverage backward control over payment module certification to command premium positioning in framework agreements with European rail operators.
Pricing Analysis
Warranty and field service bundling separates premium-tier vendors from unbundled hardware suppliers in procurement negotiations. Three-tier pricing structure across integrated platform providers, modular specialists, and regional fabricators reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from semiconductor supply concentration as Taiwanese foundry allocation constraints tighten payment module availability. Municipal transit authorities in Southeast Asia exhibit highest price sensitivity, while China's tier-one metro operators prioritize fraud reduction capabilities over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Bahn and London TfL mandate multi-supplier qualification for secure element chips, thermal printers, and cash handling modules. Manufacturing concentrates in Germany, China, and Japan, with component sourcing drawing from Taiwanese foundries for NFC payment modules and Japanese precision electromechanical suppliers for banknote recyclers. Single-source vulnerability in secure element chip supply creates exposure to foundry allocation decisions. Distribution runs through subsystem integrators who bundle hardware with software certification and maintenance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with integrated service capabilities as framework agreement mandates force component specialists into acquisition or exit. EMVCo certification timelines and multi-year bundled procurement terms are accelerating this concentration.
For Market Incumbents: Deepen backward integration into payment module certification to reduce dependency on Taiwanese foundry allocation. Secure framework agreement renewals with preemptive 5G-enabled remote diagnostics deployment, as South Korean transit networks demonstrate predictive maintenance telemetry reduces field service costs and locks in recurring revenue streams against mobile app substitution threats.
For New Entrants and Emerging Players: Biometric verification hardware offers a technology-first wedge into India's station modernization programs where PLI scheme incentives reduce import dependency and BIS standards create qualification barriers for established foreign vendors. Target Maharashtra's Mumbai Metro and Delhi-NCR networks with fingerprint sensor modules priced below integrated platform alternatives, leveraging local assembly partnerships to satisfy domestic content requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated platform providers seeking modular hardware capabilities to complete service bundling offers. Long-term viability favors vendors with EMVCo certification and multi-country regulatory clearance spanning FCC, CE marking, and MIIT specifications. Watch for FCC certification backlog resolution as inflection indicator for US deployment acceleration and corresponding hardware demand recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Investment | Enables open-loop payment acceptance mandated by French, German, and UK transit authorities. |
| 5G-Enabled Remote Diagnostics Deployment | Matches South Korean transit network standards for predictive maintenance and reduced field service costs. |
| Biometric Module Integration | Addresses fare evasion priorities in Indian Railways and South Korean account-based ticketing systems. |
| Local Assembly Partnership | Satisfies India's PLI scheme incentives and BIS durability standards for high-vibration rail environments. |
| Framework Agreement Positioning | Aligns with London TfL and Paris RATP procurement consolidation toward multi-year bundled contracts. |
Research Methodology
Multi-period observation of hardware refresh cycles, certification backlog durations, and framework agreement award patterns anchored the trend analysis, supplemented by interviews with transit authority procurement directors, rail operator maintenance heads, payment module certification engineers, and subsystem vendor sales executives. Secondary validation drew from FCC equipment authorization databases, EMVCo product approval registries, EBA electromagnetic compatibility filings, and customs records for TVM component trade flows. Bottom-up unit deployment estimates triangulated against top-down transit infrastructure investment data.
Segment-weighting across product type, payment technology, end-user environment, and installation configuration shaped the analytical framework. CAGRs were derived from regression analysis of historical replacement rates against regulatory mandate timelines, with biometric verification adoption curves and 5G module penetration serving as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including tariff regime changes affecting Taiwanese chip sourcing, force majeure disruptions to foundry capacity, and unilateral transit authority decisions to accelerate mobile-only ticketing. Deviation in EMVCo certification timeline compression or relaxation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Europe ICT Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Online Home Service Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Context Rich Systems Market