
 Oman Cybersecurity Market | 2026-2036
Oman Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Cybersecurity Market Insights
Buyer concentration across Oman's banking and government sectors is restructuring procurement patterns for cybersecurity vendors. Tatweer Cybersecurity leverages deep local relationships to dominate public-sector contracts. Bahwan CyberTek anchors enterprise demand through its integrated IT services footprint. Cisco Systems competes on advanced threat detection hardware deployed across critical infrastructure.
Cybersecurity encompasses technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with specifications including AES-256 encryption standards and sub-100-millisecond threat response latency. Its primary purpose is ensuring confidentiality, integrity, and availability of information assets across commercial and governmental operations. Managed Security Services captures the largest revenue share as organizations outsource round-the-clock monitoring. Cloud-Based deployment expands fastest as Omani enterprises migrate workloads from legacy data centers. Government end users sustain premium pricing through sovereign security requirements.
Oman's national cyber defense regulator enforces mandatory incident reporting timelines that shape vendor selection criteria. The country's central bank issues cybersecurity directives binding on all licensed financial institutions, elevating demand for compliance-aligned consulting and audit services. Stakeholders must monitor evolving certification requirements for cloud service providers seeking access to sensitive government systems.
Market Dynamics
Oman's banking sector faces mandatory incident reporting timelines enforced by the national cyber defense authority, forcing institutions toward outsourced security operations and reshaping how vendors compete for public-sector contracts.
Growth Catalysts
- Mandatory Compliance Frameworks:The national cyber defense authority's binding reporting requirements push financial institutions toward managed security services that guarantee 24/7 monitoring and rapid response capabilities.
- Digital Transaction Surge:Oman's banking sector processes escalating electronic payment volumes, creating persistent demand for encryption standards and sub-100-millisecond threat detection latency.
- Muscat Cluster Concentration:Government data centers and financial headquarters concentrate procurement power in the capital, enabling vendors to achieve scale through single-location deployment.
Market Restraints
- Specialized Talent Scarcity:Domestic cybersecurity expertise remains concentrated in Muscat, forcing institutions in peripheral governorates to pay premium wages or accept remote service limitations.
- Hardware Import Dependence:Advanced threat detection appliances rely on semiconductor components sourced from East Asian manufacturing hubs, exposing buyers to supply volatility and extended lead times.
- Sovereign Data Localization:Government cloud procurement rules mandate domestic data residency, restricting foreign platform providers from competing for sensitive workloads without local infrastructure investment.
Strategic Opportunities
- Dhofar and Al Batinah Expansion:Industrial zones outside Muscat remain underserved by managed security providers, offering first-mover advantages to vendors establishing regional operations centers.
- Zero Trust Architecture Convergence:The integration of identity verification with network segmentation creates new service categories for consultancies capable of redesigning legacy access frameworks.
- Central Bank Audit Mandates:Periodic cybersecurity assessments required of all licensed financial institutions generate recurring revenue streams for compliance-aligned consulting practices.
Industry Challenges
- Certification Timeline Compression:Cloud service providers seeking government access must navigate evolving sovereign security certifications that lack standardized approval pathways, delaying contract awards.
- Legacy System Integration:Financial institutions operate heterogeneous technology stacks accumulated over decades, complicating unified security orchestration and driving up implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Cybersecurity Market |
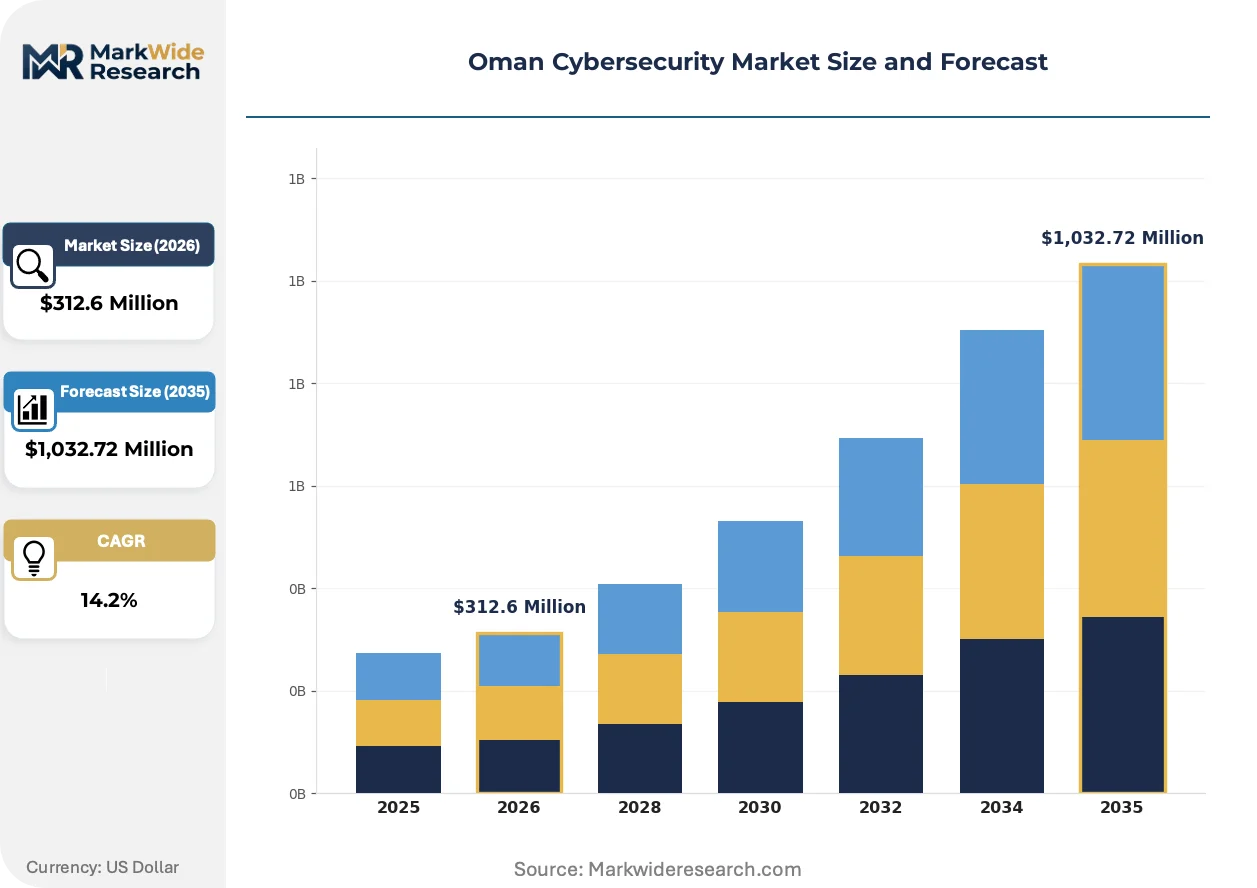
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,032.72 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Security Services, Incident Response, Consulting Services, Security Audits Deployment Model: On-Premises, Cloud-Based, Hybrid, Distributed End User: Government, BFSI, Healthcare, Retail Solution: Firewall, Antivirus, Intrusion Detection Systems, Encryption |
| Companies Covered | Oman Data Park, National Security Services Group (NSSG), Tatweer Cybersecurity, Gulfcybertech E-Solutions, Bahwan CyberTek, Injazat, Cisco Systems, IBM Corporation, Fortinet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Cybersecurity Market Trends and Innovations
Artificial intelligence and machine learning capabilities are penetrating threat detection systems across Omani critical infrastructure, compressing response windows and redefining service-level expectations for security vendors.
Extended detection and response platforms aggregate telemetry across endpoints, networks, and cloud workloads to identify anomalous patterns. Omani banks and government agencies deploy these systems to satisfy central bank directives on comprehensive monitoring coverage. This capability is converging with managed security service delivery, enabling vendors to offer automated remediation without on-site personnel.
The national cyber defense authority periodically updates mandatory incident reporting timelines that reshape vendor selection criteria. Financial institutions must demonstrate sub-hour breach notification capabilities, elevating demand for real-time analytics and dedicated security operations centers. Compliance-aligned consulting services capture premium pricing as institutions seek external validation of their reporting infrastructure.
Security service purchasing is consolidating under multi-year managed service agreements that bundle monitoring, response, and compliance reporting. Large Omani banks and government entities displace point-product procurement in favor of integrated partnerships with single vendors. This pattern concentrates contract value in Muscat, where established providers maintain dedicated security operations facilities.
Oman Cybersecurity Market Segmentation
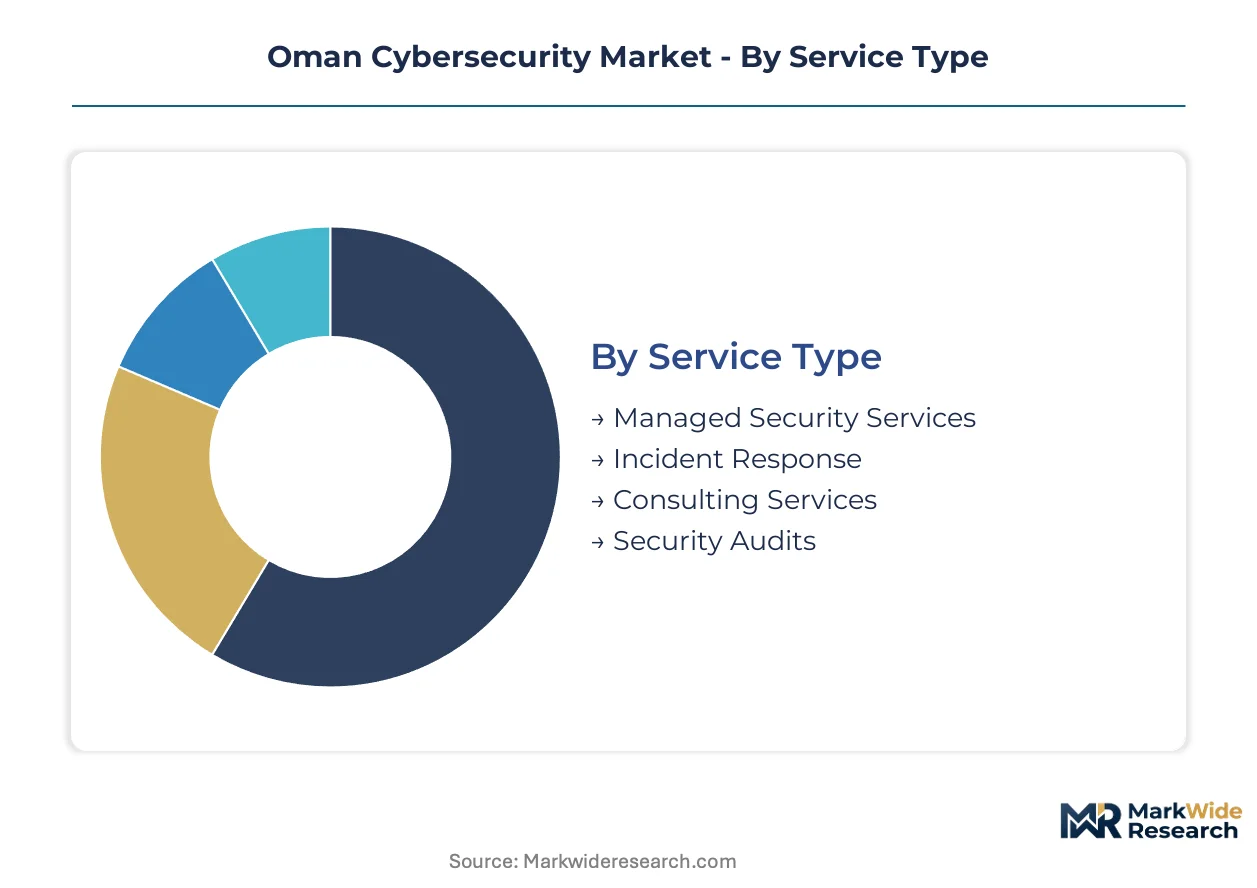
Cybersecurity procurement in Oman fragments across service delivery modes, infrastructure architectures, and sector-specific compliance burdens. Understanding these divisions reveals where certification requirements concentrate and which deployment patterns attract premium investment.
Service Type:
Certification burdens vary sharply across service categories, with sovereign security mandates driving divergent approval pathways for government-facing versus commercial offerings.
- Managed Security Services:Continuous monitoring and threat response delivered through dedicated security operations centers. Omani banks in Muscat contract these services to satisfy the national cyber defense authority's mandatory reporting timelines, outsourcing 24/7 coverage rather than building domestic capability.
- Incident Response:Rapid containment and forensic investigation following security breaches. Demand clusters among financial institutions facing compressed notification deadlines, with vendors guaranteeing sub-hour breach reporting to maintain regulatory standing.
- Consulting Services:Advisory support for security architecture design and compliance alignment.
- Security Audits:Periodic assessment and certification validation mandated by sector regulators.
Managed Security Services sits at the top of the volume ranking, with Incident Response climbing the fastest.
Deployment Model:
Cost tiers separate segments, with capital-intensive on-premises installations demanding upfront hardware investment against subscription-based cloud alternatives.
- Cloud-Based:Scalable security functions delivered through remote infrastructure with pay-as-you-consume economics. Omani enterprises migrating from legacy data centers favor this model for its elimination of physical appliance procurement and reduced dependence on scarce domestic technical talent.
- Hybrid:Blended architecture preserving sensitive workloads on local infrastructure while pushing routine monitoring to cloud platforms. Government agencies adopt this pattern to satisfy data localization mandates while accessing advanced analytics capabilities.
- On-Premises:Hardware and software installed within buyer-controlled facilities.
- Distributed:Security controls deployed across multiple geographic nodes.
Cloud-Based deployment commands the largest addressable market, with Hybrid gaining share fastest among regulated entities.
End User:
Application intensity varies by sector exposure, with financial transaction volumes and sovereign data sensitivity creating divergent threat profiles.
- Government:National security and citizen data protection requirements with mandatory domestic data residency. Muscat-based ministries and agencies sustain premium pricing for sovereign-grade solutions, with procurement concentrated in purpose-built data centers.
- BFSI:Banking, financial services, and insurance institutions subject to central bank cybersecurity directives. Electronic payment acceleration across Oman's retail and corporate banking segments generates persistent demand for encryption and real-time monitoring.
- Healthcare:Patient data protection and medical system integrity requirements.
- Retail:Point-of-sale and e-commerce transaction security for consumer-facing merchants.
Government end users anchor premium contract values, with BFSI expanding most quickly through compliance-driven procurement.
Solution:
Technology maturity separates established perimeter defenses from emerging integrated platforms, with integration complexity driving implementation cost variation.
- Firewall:Network perimeter access control with deep packet inspection capabilities. Critical infrastructure operators in Oman's oil and gas sector deploy next-generation appliances to segment operational technology from enterprise networks.
- Intrusion Detection Systems:Automated monitoring for unauthorized access attempts and anomalous traffic patterns. Financial institutions integrate these with central bank-mandated reporting infrastructure to achieve real-time breach notification.
- Antivirus:Endpoint malware prevention through signature and behavioral analysis.
- Encryption:Data protection through cryptographic transformation with AES-256 standards.
Firewall solutions maintain the deepest installed base, with Intrusion Detection Systems showing the steepest expansion trajectory as institutions automate compliance reporting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's cybersecurity procurement outpaces Oman in absolute contract value, yet Oman compresses vendor selection timelines more aggressively through sovereign certification mandates. The Gulf Cooperation Council states collectively drive regional demand, though each market structures procurement through distinct regulatory pathways.
Muscat Governorate
Oman's capital concentrates government data centers and financial headquarters, generating premium demand for managed security services. The national cyber defense authority mandates sub-hour breach notification from institutions headquartered here, compressing procurement cycles for 24/7 monitoring contracts. Ministries cluster in purpose-built facilities along Sultan Qaboos Highway, enabling single-location deployment economies for security vendors.
Dhofar Governorate
Industrial zones around Salalah remain underserved by cybersecurity providers despite expanding port and logistics operations. The central bank's cybersecurity directives apply equally to branch operations here, forcing regional banks toward remote managed services. Free zone enterprises at Salalah Port generate nascent demand for cloud-based security as they migrate from legacy data center architectures.
Al Batinah Region
Manufacturing and fisheries processing operations across Sohar and Rustaq create fragmented endpoint protection demand. Domestic cybersecurity expertise scarcity forces processors here to pay premium wages or accept Muscat-based remote monitoring limitations. The region's industrial city authority has initiated talks with managed service providers to establish a local security operations presence.
Ad Dakhiliyah Governorate
Educational institutions and healthcare facilities in Nizwa generate compliance-driven procurement for patient and student data protection. The national cyber defense authority's mandatory reporting timelines apply to regional hospital networks, elevating demand for incident response retainers. University research centers here pilot zero-trust architecture implementations for sensitive academic data.
Ash Sharqiyah Region
Oil and gas operational technology networks across the interior drive specialized demand for industrial control system security. Critical infrastructure operators deploy next-generation firewalls to segment enterprise from operational networks per sector-specific guidelines. The region's remote field locations complicate physical security appliance maintenance, pushing toward hybrid cloud-local deployment models.
Oman Cybersecurity Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Oman's cybersecurity procurement landscape. The vendor base stratifies into three tiers: local system integrators with government relationships, regional IT services conglomerates with enterprise footprints, and global hardware-software vendors with advanced threat detection platforms. Market structure favors providers bundling compliance consulting with managed services. Dominant competitive moves include local security operations center establishment and sovereign certification acquisition.
Within the local specialist tier, Tatweer Cybersecurity and Gulfcybertech E-Solutions exemplify providers leveraging domestic regulatory knowledge to anchor public-sector positioning. Bahwan CyberTek occupies a position representing the integrated conglomerate archetype, extending existing IT services relationships into security mandates. Cisco Systems and Fortinet sit within the global platform tier, supplying hardware-anchored threat detection to critical infrastructure operators. Oman Data Park represents the data center operator archetype, bundling co-location with sovereign-compliant security services.
| Leading Market Players |
|---|
| Oman Data Park |
| National Security Services Group (NSSG) |
| Tatweer Cybersecurity |
| Gulfcybertech E-Solutions |
| Bahwan CyberTek |
| Injazat |
| Cisco Systems |
| IBM Corporation |
| Fortinet |
| Others |
Pricing and Supply Chain Analysis
Mandatory sovereign certification requirements for cloud service providers seeking government contracts in Oman are compressing vendor selection timelines and forcing supply chain reconfiguration toward local infrastructure partnerships, elevating pricing for compliant offerings while creating tiered cost structures based on certification status.
Pricing Analysis
Capacity additions in the UAE and Saudi Arabia are reshaping price floors for managed security services across the Gulf, with subscription-based SaaS-tiered pricing now dominating procurement in Oman's banking sector. Three-tier pricing structure across premium sovereign-certified, standard enterprise, and economy commercial levels separates vendors based on domestic data residency compliance and response latency guarantees. Pricing pressure stems from regional competition as Saudi-based providers extend service coverage southward. Government end users show lowest price sensitivity due to mandatory compliance requirements, while retail and mid-market enterprises negotiate aggressively on per-seat monitoring costs.
Supply Chain Analysis
Oman's data localization mandates are reshaping sourcing patterns for foreign cybersecurity platforms, requiring local infrastructure investment that alters traditional hardware-software distribution economics. Advanced threat detection appliances draw from semiconductor manufacturing concentrated in Taiwan, South Korea, and mainland China, with next-generation firewalls and intrusion detection systems resting on specialized chipset architectures. Single-source vulnerability characterizes the hardware layer, as no domestic fabrication capacity exists for cryptographic processing modules. Distribution runs through Muscat-based system integrators who bundle compliance consulting with hardware procurement, creating captive channels for government and critical infrastructure verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's cybersecurity market functions as a geographic-arbitrage opportunity where regional providers from the UAE and Saudi Arabia leverage lower fixed-cost bases to undercut Muscat-incumbent pricing, while Oman's stricter sovereign certification requirements create defensive moats for local specialists willing to absorb compliance investment.
For Market Incumbents: Anchor market position through exclusive security operations center accreditation from the national cyber defense authority, creating non-replicable certification assets that foreign competitors cannot easily replicate. Deepen backward integration into local data center infrastructure to satisfy data residency mandates while controlling cost structures against regional competitors expanding from lower-cost bases. The threat of Saudi-based managed service providers extending southward with standardized offerings demands differentiation through sovereign-grade compliance capabilities rather than price competition. For New Entrants and Emerging Players: Capture the Dhofar and Al Batinah industrial corridors where security operations coverage remains thin and regional banks operate under the same central bank directives as Muscat headquarters but with limited local support options. The most penetrable segment lies among free zone enterprises at Salalah Port migrating from legacy architectures and lacking established vendor relationships. A compliance-first go-to-market approach emphasizing rapid certification acquisition for government-adjacent contracts creates entry pathways that bypass entrenched Muscat competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale managed security providers possessing active national cyber defense authority certification pipelines but limited geographic footprint, offering acquisition platforms for regional consolidation plays. Long-term viability hinges on the ability to anchor recurring revenue through multi-year government and banking contracts rather than project-based consulting. The signal to watch is central bank directive expansion requiring sub-hour breach notification from smaller financial institutions, which would force regional bank procurement toward professionalized managed services and accelerate market formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Local Security Operations Center Establishment | Muscat-based facilities satisfy data residency mandates while enabling 24/7 sovereign-grade monitoring for government clients. |
| Sovereign Certification Acquisition | National cyber defense authority accreditation creates procurement eligibility barriers that foreign competitors cannot bypass without domestic investment. |
| Regional Expansion to Underserved Governorates | Dhofar and Al Batinah operations capture industrial zone demand currently served through remote Muscat-based monitoring with latency limitations. |
| Zero Trust Architecture Service Development | Identity-network convergence consulting addresses legacy system transformation needs among banks with decades of accumulated technology debt. |
| Multi-Year Managed Service Agreement Consolidation | Integrated partnerships displace point-product procurement, concentrating contract value and reducing customer acquisition costs for established providers. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with chief information security officers at Omani banks, government agency IT directors, procurement leads at critical infrastructure operators, and managed security service provider executives supplied operational validation. Secondary sources included central bank cybersecurity directive filings, national cyber defense authority certification registries, customs import records for network security appliances, and hyperscaler regional capex disclosures. Triangulation across these channels calibrated segment-level penetration rates and service pricing benchmarks.
Historical trendline analysis of banking sector IT security spending and government digital transformation budgets established baseline growth patterns across the projection horizon. The forecast framework models deployment mode segmentation across cloud-based, hybrid, and on-premises architectures alongside end-user verticals spanning BFSI, government, healthcare, and industrial applications. CAGRs derive from regression analysis against digital transaction volume growth, regulatory mandate expansion timelines, and cloud migration velocity indicators specific to Omani enterprise technology refresh cycles.
Regulatory timeline acceleration, cloud service provider certification delays, and regional geopolitical disruptions affecting semiconductor supply chains are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding central bank directive enforcement consistency and sovereign data localization rule stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Email Encryption Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Enterprise Network Firewall Market
Cybersecurity
Hong Kong Cybersecurity Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Global Mobile Data Protection Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Switzerland Cybersecurity Market
Cybersecurity
Japan Ransomware Protection Market
Cybersecurity
Cloud Firewalls Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
North America Cyber Security Market
Cybersecurity
Europe SOC As a Service Market
Cybersecurity
Asia Pacific Digital Forensics Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Europe Mobile Security Market