
 Transportation Sensors Market | 2026-2036
Transportation Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Sensors Market Analytics
Aftermarket service revenue is fragmenting across hardware calibration, data analytics subscriptions, and predictive maintenance contracts. TE Connectivity leverages its connector and sensor portfolio to anchor aftermarket service contracts for fleet operators. Infineon Technologies sustains R&D intensity in radar and LiDAR semiconductor solutions for tier-one automotive suppliers. Siemens dominates intelligent traffic infrastructure projects across European urban corridors.
Transportation sensors are electromechanical or solid-state devices that detect, measure, and transmit physical parameters including proximity, speed, temperature, and optical reflectance, typically operating across frequency bands from 24 GHz to 77 GHz for radar applications and 905 nm to 1550 nm for LiDAR systems, with primary purpose of enabling real-time decision-making in vehicle control systems and traffic management networks. Camera sensors lead installed base in traffic monitoring applications due to mature image processing pipelines and lower unit costs, while LiDAR represents the fastest-expanding category within autonomous driving segments as resolution and all-weather reliability improve. GPS technology occupies established positions in fleet management, whereas V2X network-based architectures are capturing incremental investment as municipalities deploy connected infrastructure.
NHTSA and EPA standards in the United States, alongside EU Green Deal and CE marking requirements in Europe, mandate minimum sensor performance thresholds for emissions monitoring and collision avoidance systems, directly shaping product development roadmaps and market access conditions for non-compliant suppliers. Japan's METI and JIS standards further define interoperability protocols for intelligent transport systems across Asian supply chains. Stakeholders must monitor evolving V2X spectrum allocation decisions and cybersecurity certification timelines to align capital deployment with regulatory enforcement schedules.
Market Dynamics
Autonomous driving platform deployment by automotive OEMs is compressing development cycles and forcing tier-one suppliers to consolidate radar, LiDAR, and camera architectures into unified perception stacks.
Growth Catalysts
- NHTSA collision-avoidance mandates:United States safety regulations mandate minimum sensor performance thresholds for automatic emergency braking and pedestrian detection, compelling OEMs to expand sensor suites across vehicle classes.
- EU Green Deal emissions monitoring:European performance standards require real-time exhaust and thermal management sensors, creating hardware pull from powertrain and battery thermal systems.
- Stuttgart-Munich R&D clustering:Germany's automotive sensor development corridors concentrate engineering talent and testing infrastructure, accelerating prototype-to-production timelines for tier-one suppliers.
Market Restraints
- Silicon carbide substrate shortages:Power semiconductor material constraints limit radar frontend module output, creating allocation bottlenecks for 77 GHz automotive radar chipsets.
- LiDAR unit cost structures:Mechanical scanning assemblies and 1550 nm fiber laser components maintain price floors above solid-state alternatives, delaying mass-market vehicle integration.
- Spectrum allocation uncertainty:FCC and European Commission deliberations over 5.9 GHz V2X band reallocation create regulatory friction for connected infrastructure deployment timelines.
Strategic Opportunities
- V2X municipal infrastructure:United States Department of Transportation grants for connected intersection deployments create demand for roadside units integrating radar, camera, and DSRC/C-V2X modules.
- Predictive maintenance analytics:Fleet operators are unbundling sensor calibration and health-monitoring services from hardware sales, opening recurring revenue streams for component suppliers.
- Camera-LiDAR fusion architectures:Sensor data preprocessing at the edge is converging photonic and computational hardware, enabling lower-latency perception stacks for urban autonomous operation.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D validation for autonomous driving sensors extends development cycles 18-24 months, compressing window for design-win capture.
- Multimodal sensor fusion expertise:Shortage of systems engineers capable of integrating 24-77 GHz radar, 905-1550 nm LiDAR, and CMOS image sensor pipelines constrains tier-one integration capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Sensors Market |
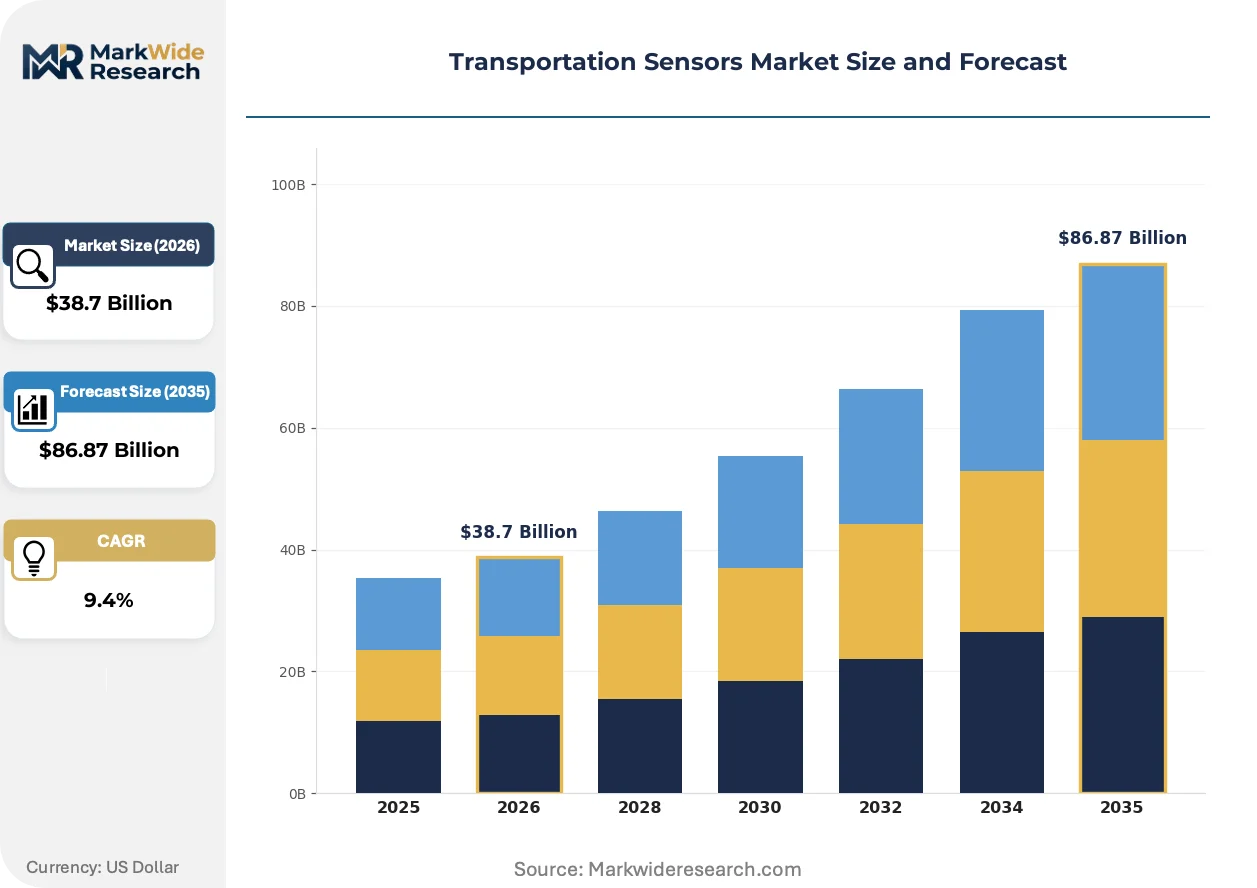
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Radar, LiDAR, Camera, Ultrasonic Application: Fleet Management, Traffic Monitoring, Autonomous Driving, Public Transport End User: OEMs, Government Agencies, Logistics Providers, Ride-Sharing Services Technology: GPS, V2X, Infrared, Network-Based |
| Companies Covered | Kapsch TrafficCom, SWARCO, TE Connectivity, Teledyne FLIR, International Road Dynamics, SICK AG, Infineon Technologies, Siemens, Econolite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Sensors Market Evolving Landscape
Sensor architectures are consolidating from discrete single-function modules toward unified perception platforms, with software-defined parameter tuning displacing hardware-swappable configurations.
Frequency-modulated continuous-wave radar is hybridizing with solid-state beam steering to enable 4D imaging capabilities without mechanical rotating assemblies. Tier-one suppliers are adopting these chipsets for Level 2+ highway assist systems. The technology is compressing cost structures for mid-range autonomous platforms while maintaining all-weather reliability.
EU AI Act risk classification requirements are mandating explainability and traceability for sensor-driven decision systems in vehicles. Automotive OEMs must document training data provenance and model validation for high-risk AI applications. European premium passenger vehicle segments are responding with dedicated sensor validation engineering teams and third-party audit partnerships.
Fleet procurement patterns are fragmenting from bundled hardware-software contracts toward unbundled sensor-as-a-service arrangements. Commercial vehicle operators are subscribing to calibration, over-the-air update, and predictive health monitoring separately from capital equipment acquisition. This unbundling is most visible in United States long-haul trucking and last-mile delivery verticals where asset utilization metrics dominate vendor selection.
Transportation Sensors Market Segmentation
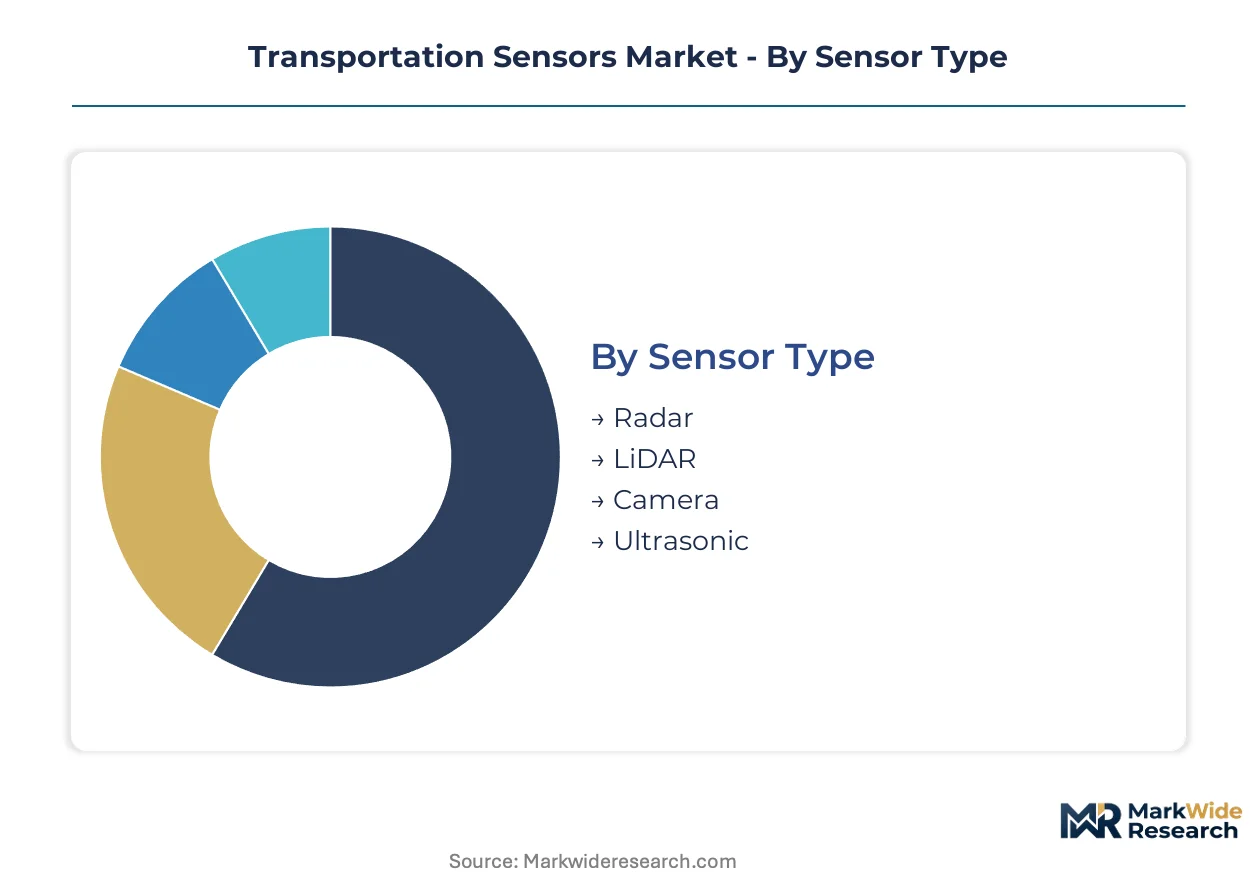
Transportation sensor suppliers structure their service portfolios around calibration frequency and data subscription tiers. Aftermarket revenue streams diverge sharply across hardware-intensive versus analytics-heavy segments, forcing vendors to choose between capital equipment margins and recurring software income.
Sensor Type:
After-sales service intensity peaks with mechanical scanning assemblies and fiber laser calibration cycles, while solid-state alternatives shift revenue toward firmware update subscriptions.
- Radar:Frequency-modulated continuous-wave chipsets operating at 24-77 GHz dominate highway assist deployments. Fleet operators in Germany's Stuttgart-Munich corridor specify radar recalibration intervals below 18 months, tightening vendor service obligations. By volume, radar leads. By growth pace, solid-state beam steering variants are ahead.
- LiDAR:Mechanical scanning units at 905-1550 nm wavelengths deliver centimeter-scale resolution for urban autonomous navigation. NHTSA pedestrian detection mandates are accelerating OEM qualification timelines for 1550 nm fiber laser systems despite unit cost premiums.
- Camera:CMOS image sensors with mature ISP pipelines anchor traffic monitoring infrastructure due to sub-$50 unit economics at volume.
- Ultrasonic:Short-range proximity detection for parking assist carries minimal aftermarket attachment, squeezing supplier margins toward hardware-only transactions.
Camera installations outnumber LiDAR by an order of magnitude, yet LiDAR's service revenue per unit exceeds camera systems by 4-6x.
Application:
Cost tier stratification separates capital-intensive autonomous platforms from operational expenditure models in fleet and traffic management.
- Fleet Management:GPS and telematics integration dominates long-haul trucking and last-mile delivery verticals. United States Department of Transportation grant programs for connected vehicle corridors are expanding roadside unit procurement beyond traditional tolling applications.
- Traffic Monitoring:Camera-radar fusion architectures at urban intersections generate recurring analytics subscriptions for municipal traffic departments. EU Green Deal emissions tracking requirements are mandating real-time sensor density upgrades across European urban corridors.
- Autonomous Driving:Unified perception stacks combining 4D imaging radar, solid-state LiDAR, and multi-camera arrays command the highest engineering service intensity. ISO 26262 ASIL-D certification cycles extend 18-24 months, compressing design-win windows for tier-one integrators.
- Public Transport:Bus rapid transit and rail systems prioritize V2X-enabled collision avoidance over full autonomy, limiting sensor suite complexity to mid-tier radar-camera configurations.
Fleet management generates the largest installed base. Autonomous driving claims the steepest expansion trajectory.
End User:
Customer procurement maturity determines whether contracts bundle hardware with predictive maintenance or separate capital acquisition from service subscriptions.
- OEMs:Automotive manufacturers consolidate tier-one supplier relationships around unified perception platforms, squeezing discrete sensor vendors toward module-level integration partnerships. EU AI Act documentation requirements for high-risk AI systems are adding validation engineering overhead to European premium vehicle programs.
- Government Agencies:Municipal and national transport departments deploy V2X roadside units through multi-year infrastructure grants. FCC spectrum allocation uncertainty over 5.9 GHz band reallocation is delaying committed capital deployment timelines.
- Logistics Providers:Commercial fleet operators unbundle sensor calibration from hardware procurement, subscribing to over-the-air update and health-monitoring services separately. This pattern concentrates in United States long-haul trucking where asset utilization metrics dominate vendor selection.
- Ride-Sharing Services:Urban mobility platforms prioritize rapid sensor refresh cycles over extended durability, accepting higher replacement frequency for access to latest perception capabilities.
OEMs concentrate the highest absolute spending. Logistics providers are shifting fastest toward unbundled service models.
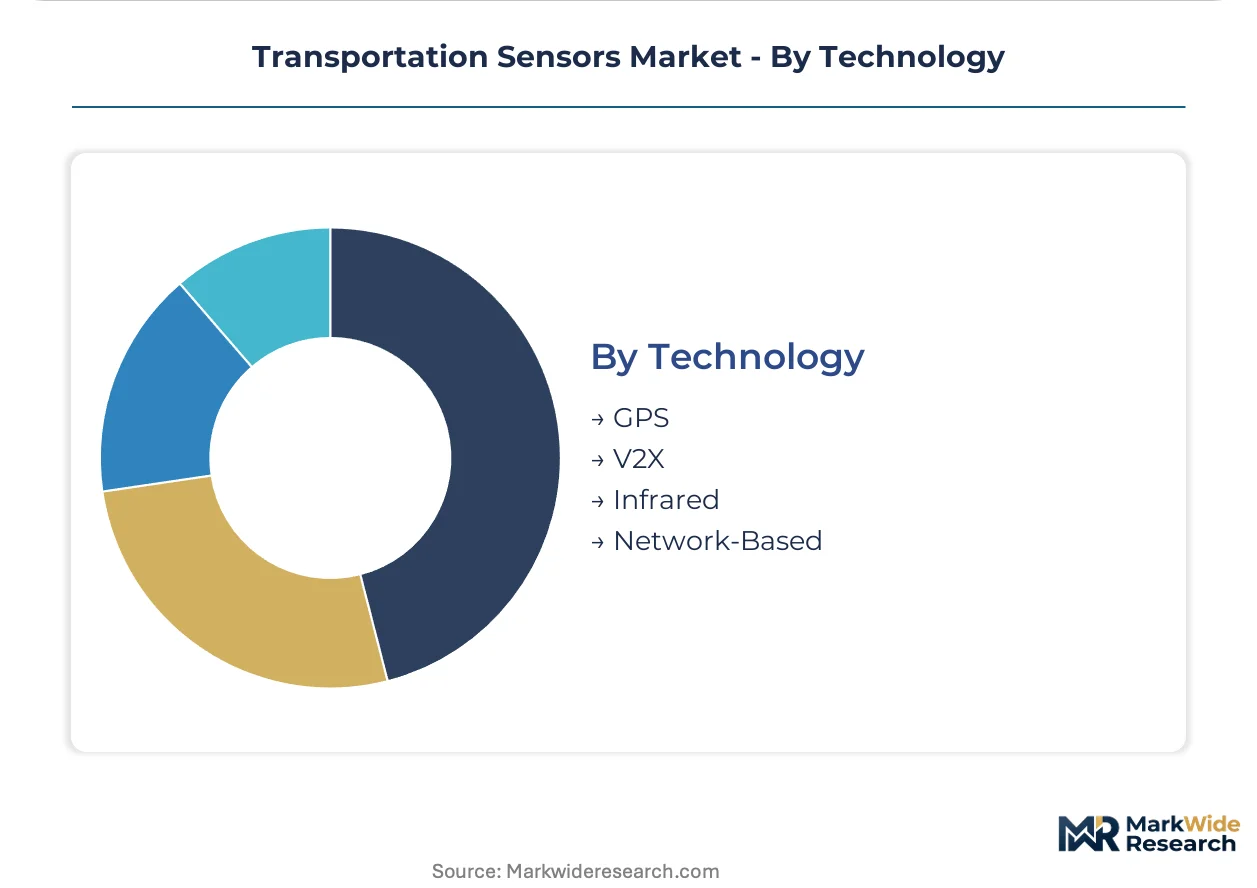
Technology:
Technology maturity curves separate established positioning systems from emerging network architectures requiring municipal infrastructure coordination.
- GPS:Satellite-based positioning maintains installed base dominance in fleet telematics despite urban canyon accuracy limitations. Multi-constellation receivers combining GPS, Galileo, and GLONASS are becoming standard in European commercial vehicle specifications.
- V2X:DSRC and C-V2X protocols enable vehicle-to-infrastructure communication for cooperative perception. United States Department of Transportation connected intersection grants are creating procurement pull for roadside units integrating radar, camera, and V2X modules.
- Infrared:Thermal imaging for pedestrian detection in low-visibility conditions occupies niche applications where LiDAR cost barriers persist.
- Network-Based:Cellular and mesh network triangulation supplements GPS in dense urban environments, though latency constraints limit real-time control applications.
GPS retains volume leadership. V2X is climbing the fastest as municipalities commit to connected corridor deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive sensor R&D clusters anchor supply-side engineering capacity, while regulatory enforcement in the United States and European Union shapes demand trajectories across distinct national corridors.
United States
NHTSA collision-avoidance mandates and Department of Transportation connected vehicle grants drive sensor procurement across automotive OEMs and municipal infrastructure. FCC deliberations over 5.9 GHz V2X spectrum allocation create regulatory uncertainty for roadside unit deployment timelines. Detroit-to-Austin automotive corridors concentrate tier-one supplier engineering centers and testing facilities.
Germany
EU Green Deal emissions monitoring requirements and AI Act documentation rules tighten performance standards for powertrain and autonomous driving sensors. Stuttgart-Munich R&D clusters concentrate radar and LiDAR semiconductor development within tier-one supplier ecosystems. KBA vehicle type approval processes extend validation cycles for high-risk AI perception systems.
China
MIIT intelligent connected vehicle standards and dual carbon goals accelerate domestic sensor deployment across electric vehicle platforms. GB standards define minimum performance thresholds for autonomous driving perception systems. Yangtze River Delta manufacturing bases concentrate solid-state LiDAR module production capacity.
Japan
METI and JIS interoperability protocols standardize intelligent transport system architectures across Asian supply chains. Domestic OEMs consolidate tier-one relationships around unified perception platforms for highway assist systems. Nagoya-Tokyo automotive corridors anchor radar semiconductor R&D and production facilities.
South Korea
Seoul Capital Area automotive clusters drive demand for camera-LiDAR fusion architectures in premium electric vehicle segments. MFDS and national standards bodies coordinate with international regulators on functional safety certification reciprocity. Busan-Ulsan manufacturing regions concentrate sensor module assembly and testing operations.
Transportation Sensors Market Competitive Landscape
Component specialists and integrated platform providers split the market along the hardware-software boundary. Tier-one automotive suppliers consolidate discrete sensor sourcing into unified perception stacks, compressing margins for standalone module vendors. Three archetypes dominate: semiconductor fabricators supplying radar and LiDAR chipsets, connector and electromechanical component specialists anchoring fleet service contracts, and intelligent infrastructure integrators capturing municipal V2X deployments. Competitive moves concentrate on strategic partnerships for sensor fusion software and geographic expansion into connected corridor pilot programs.
Among European automotive suppliers, Infineon Technologies and Siemens exemplify divergent strategic positions within the ecosystem. Infineon Technologies occupies a semiconductor fabricator archetype, supplying radar and LiDAR semiconductor solutions to tier-one integrators. Siemens represents the intelligent infrastructure integrator tier, capturing roadside unit deployments across European urban corridors. TE Connectivity sits within the connector and sensor component specialist category, leveraging hardware portfolios to anchor aftermarket service arrangements for commercial fleet operators.
| Leading Market Players |
|---|
| Kapsch TrafficCom |
| SWARCO |
| TE Connectivity |
| Teledyne FLIR |
| International Road Dynamics |
| SICK AG |
| Infineon Technologies |
| Siemens |
| Econolite |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's congestion-driven cost surges ripple through sensor module logistics, concentrating pricing power among German and Chinese suppliers while forcing tier-one integrators to differentiate through after-sales service bundling versus bare hardware transactions.
Pricing Analysis
Extended calibration and predictive maintenance contracts generate lifetime value multiples exceeding hardware margins by threefold. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified autonomous driving modules from fleet telematics units and basic parking assist sensors. Pricing pressure stems from solid-state LiDAR cost compression as Yangtze River Delta manufacturers scale 905 nm chipsets. Fleet operators in United States long-haul trucking exhibit highest price sensitivity, while European premium OEMs absorb certification premiums for AI Act compliance.
Supply Chain Analysis
Silicon carbide substrate fabrication feeds from facilities concentrated in Germany, Japan, and the United States. Radar frontend modules draw from gallium nitride foundries in Taiwan and South Korea, while 1550 nm fiber laser components source from specialized Japanese and German optics houses. Single-source vulnerability around SiC wafers threatens 77 GHz chipset allocation during automotive platform ramp-ups. Distribution runs through tier-one automotive supplier hubs in Stuttgart, Detroit, and Nagoya before final OEM assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transportation sensors sit in early-cycle expansion as NHTSA and EU mandates force sensor suite proliferation across vehicle classes previously exempt from advanced driver assistance requirements.
For Market Incumbents: Pre-empt margin erosion from solid-state LiDAR commoditization by anchoring fleet service contracts around predictive health monitoring and over-the-air calibration subscriptions. Deepen backward integration into radar semiconductor fabrication through captive SiC substrate agreements with German and Japanese suppliers. Lock tier-one relationships via unified perception stack co-development for Level 2+ highway assist platforms.
For New Entrants and Emerging Players: Mid-tier commercial vehicle segments in Southeast Asia and Latin America represent the most penetrable entry point, as regulatory enforcement lags European and North American mandates while fleet digitization accelerates. Solid-state beam steering radar for bus rapid transit collision avoidance offers lower certification barriers than autonomous passenger vehicle perception. Partner with established telematics providers for channel access rather than building direct OEM sales capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded automotive sensor divisions lacking scale for unified perception platform investments. Long-term viability hinges on software-defined sensor architectures capable of parameter tuning without hardware swaps. Watch FCC 5.9 GHz spectrum reallocation rulings as inflection indicator for V2X infrastructure deployment timelines and connected corridor capital commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies radar, LiDAR, and camera pipelines for tier-one automotive suppliers seeking reduced integration complexity. |
| Backward Integration into SiC Substrates | Captures margin from 77 GHz radar frontend modules amid allocation constraints for power semiconductor materials. |
| Predictive Maintenance Service Launch | Converts hardware transactions into recurring revenue streams with fleet operators prioritizing asset utilization metrics. |
| V2X Roadside Unit Deployment Partnership | Positions vendors for United States Department of Transportation connected intersection grant programs. |
| AI Act Validation Engineering Investment | Enables European premium vehicle program participation through documented training data provenance and model audit capabilities. |
Research Methodology
Desk research of automotive production databases, regulatory filing repositories, and tier-one supplier technical disclosures preceded structured interviews with OEM platform engineers, fleet operations directors, municipal transport procurement officers, and radar semiconductor R&D leads. Secondary validation drew from NHTSA rulemaking dockets, EU Green Deal implementation guidance, and connected vehicle pilot program evaluations. Bottom-up sensor unit shipment estimates triangulated against top-down automotive production forecasts across vehicle class and propulsion architecture segments.
Assumptions around NHTSA mandate enforcement schedules and EU AI Act documentation timelines remained fixed, while V2X spectrum allocation outcomes and SiC substrate supply expansion rates were stress-tested across scenarios. The analytical framework modeled sensor type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from logistic adoption curves fitted to historical ADAS penetration patterns, with content-per-vehicle trajectories for autonomous driving platforms calibrated against tier-one supplier engineering roadmaps.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor capital expenditure cycles, or freight corridor logistics costs would shift the trajectory. Forecasts reflect documented assumptions without claiming predictive certainty. Cross-checking against IHS Markit vehicle registration data and supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Mobile Mapping Systems Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Temperature Data Loggers Market
Sensors
Yield Monitoring Systems Market
Sensors
Barcode Scanner Market
Sensors
Machine Health Monitoring Market
Sensors
RFID Smart Cabinet Market
Sensors
Handheld RFID Readers Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Mobile Lidar Scanner Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Smart Mat Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Data Buoy Market
Sensors
North America Eye Tracking Solutions Market