
 Information Security Products and Services Market | 2026-2036
Information Security Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Information Security Products and Services Market Intelligence
The ISO/IEC 27001 certification standard is redrawing competitive positioning by setting a baseline for enterprise-grade security management systems. This qualification gates entry into large enterprise and government contracts. Microsoft leverages its vast cloud infrastructure to embed security across its ecosystem. Palo Alto Networks specializes in next-generation firewalls and cloud-native security platforms, while Cisco Systems anchors its offerings in network security hardware and integrated threat intelligence services.
Information security products and services encompass technologies and practices designed to protect digital assets from unauthorized access or attack. These solutions, including firewalls with deep packet inspection capabilities, aim to maintain the confidentiality, integrity, and availability of data. Cloud-based deployment models represent the fastest-growing segment, displacing traditional on-premises hardware. Within services, managed security offerings are gaining significant traction over standalone consulting engagements as organizations seek continuous monitoring and threat response.
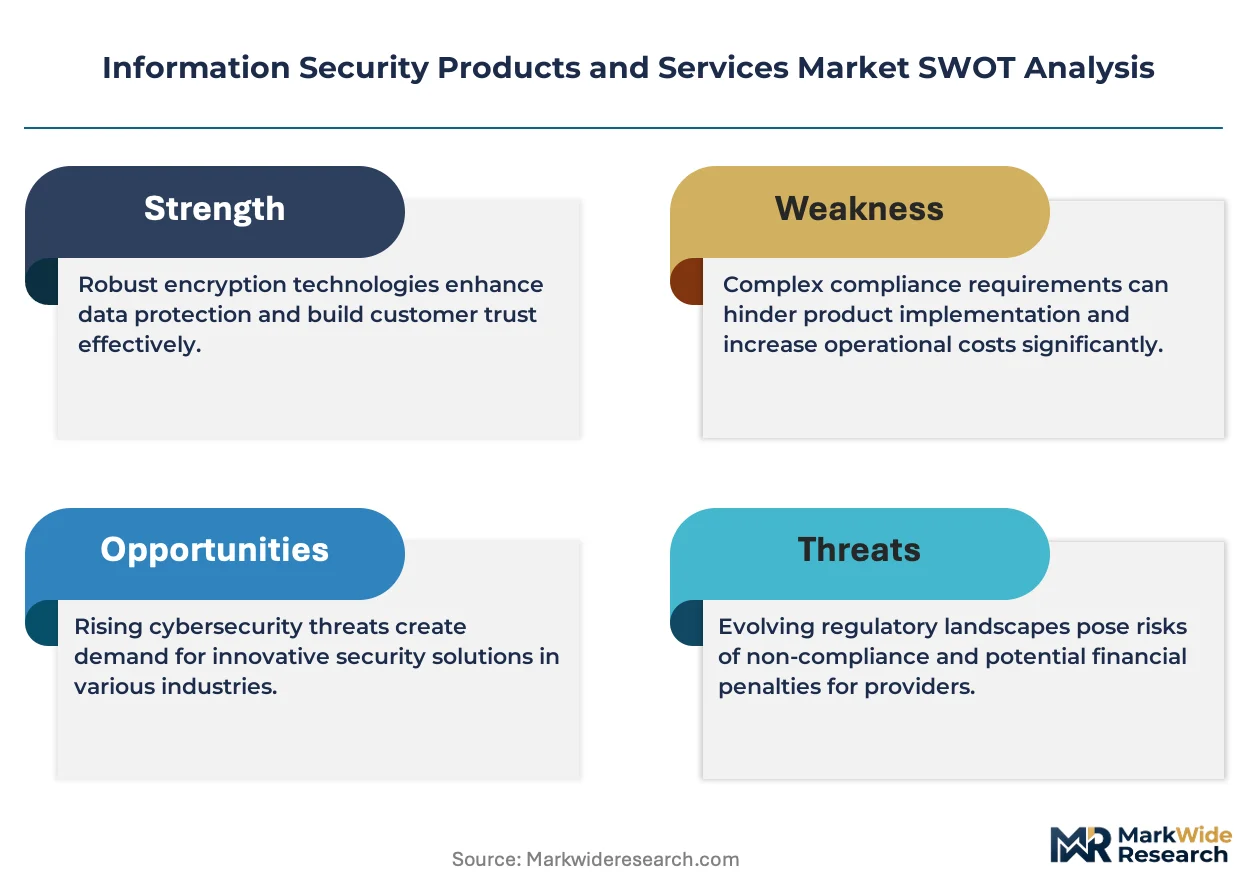
Regulatory frameworks are a primary demand catalyst, with the EU's GDPR, the US's HIPAA, and China's Cybersecurity Law setting stringent data protection requirements. These regulations compel investments in encryption, access controls, and compliance services. The critical decision for enterprises now centers on resource allocation between defending against known threats and preparing for emerging AI-powered attack methodologies. Stakeholders must assess their security posture against this evolving threat landscape.
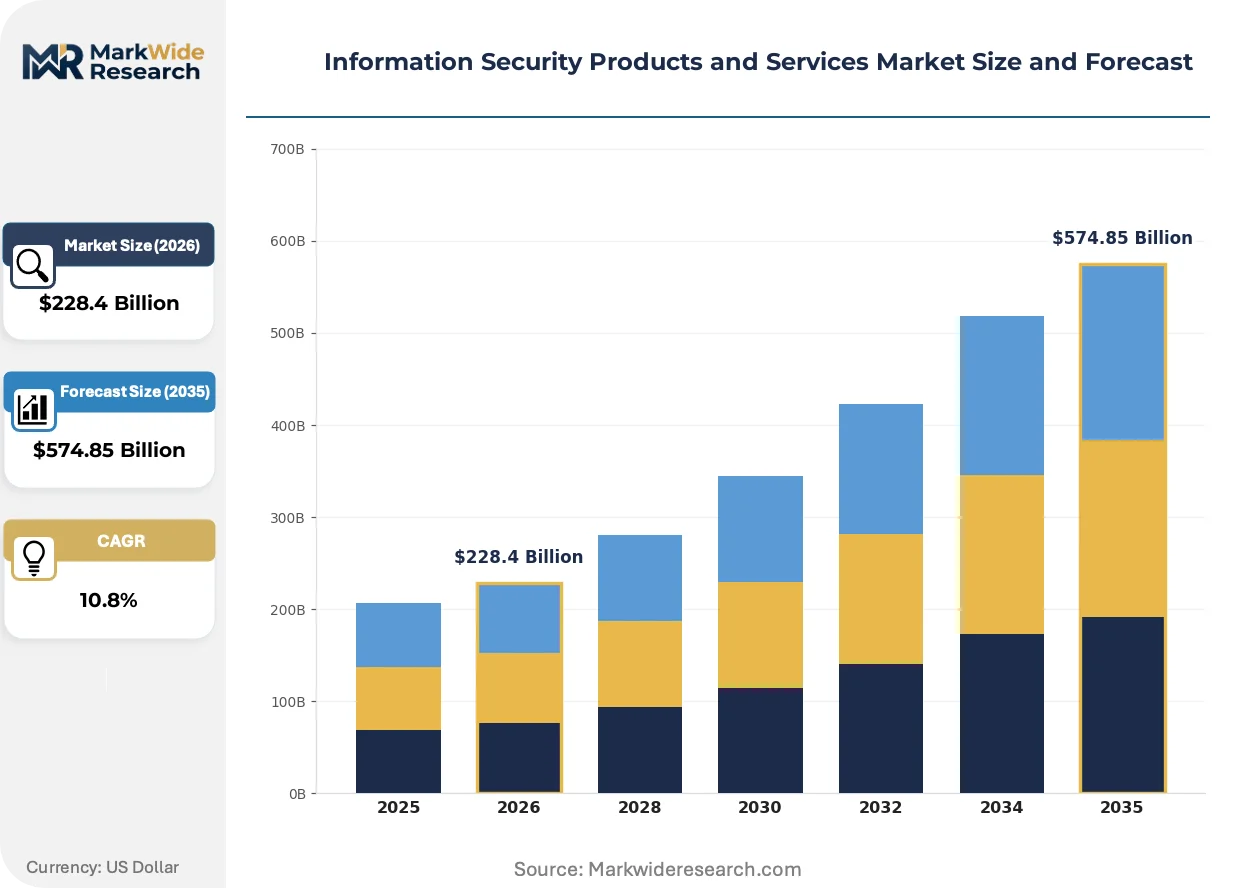
Market Dynamics
The central structural force shaping the market is the dual pressure from increasingly sophisticated, AI-driven cyber threats and a tightening global regulatory net. This environment compels enterprises to adopt auditable, enterprise-grade security controls to protect data and avoid significant financial penalties.
Growth Catalysts
- Regulatory Mandates:Data protection laws like the EU's GDPR and China's Cybersecurity Law create non-negotiable requirements for encryption, access control, and breach reporting, directly compelling investment in compliant security products and services across multiple continents.
- Financial Sector Threats:The financial services industry is accelerating security spending in response to targeted ransomware and nation-state attacks, driving demand for advanced threat intelligence, endpoint security, and managed detection and response services.
- Cloud Service Adoption:Rapid migration to public cloud platforms, especially within the United States, fuels demand for specialized cloud security posture management (CSPM) and cloud access security broker (CASB) solutions to protect distributed assets.
Market Restraints
- High Total Cost of Ownership:The substantial expense associated with licensing, implementing, and staffing advanced security platforms like Security Information and Event Management (SIEM) systems acts as a barrier for many mid-sized organizations.
- Vendor Sprawl and Integration Complexity:Enterprises often struggle with a fragmented portfolio of security tools from dozens of vendors, leading to integration challenges, visibility gaps, and an increased attack surface that is difficult to manage.
- Cybersecurity Talent Scarcity:A persistent global shortage of skilled security professionals, particularly in specialized domains like threat hunting and cloud security architecture, constrains the ability of organizations to effectively operate their security tools.
Strategic Opportunities
- Securing OT and IoT Environments:A significant opportunity exists in providing specialized security solutions for operational technology (OT) in manufacturing and critical infrastructure, as these historically isolated networks become increasingly connected to IT systems.
- Small and Medium-Sized Enterprises:Underpenetrated small and medium-sized enterprises (SMEs), particularly in fast-digitizing economies like Brazil and India, represent a major growth vector for scalable, cloud-based security solutions and managed security services.
- Security and Observability Convergence:The integration of security data with IT observability platforms offers a new frontier for vendors, enabling unified dashboards that correlate security threats with application performance and infrastructure health for faster remediation.
Industry Challenges
- Advanced Skill Gaps:The talent deficit is most acute for roles requiring expertise in DevSecOps, AI-powered threat analysis, and multi-cloud security, which slows the adoption of next-generation security practices and increases reliance on third-party service providers.
- Legacy System Integration:Many large enterprises, especially in banking and government, face significant friction and cost when attempting to integrate modern security tools with decades-old legacy IT systems that were not designed for today's threat landscape.
- Certification and Compliance Timelines:The lengthy and resource-intensive process to achieve critical attestations, such as FedRAMP for US government contracts or ISO/IEC 27001 for enterprise deals, creates a high barrier to entry and can delay revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Information Security Products and Services Market |
| Market Size in 2026 | $228.4 Billion |
| Market Size in 2035 | $574.85 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewall, Antivirus, Intrusion Detection, Encryption Service Type: Consulting, Managed Security, Incident Response, Compliance End User: Healthcare, Financial Services, Government, Retail Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual |
| Companies Covered | IBM, Cisco Systems, Microsoft, Palo Alto Networks, Fortinet, Check Point Software Technologies, Proofpoint, Broadcom, Zscaler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Information Security Products and Services Market Strategic Shifts & Innovations
The market's fundamental architecture is shifting from a focus on perimeter defense toward identity-centric, zero-trust models. This transformation is a direct response to the dissolution of traditional network boundaries caused by widespread cloud adoption and remote work, redefining how trust is established and verified.
Extended Detection and Response (XDR) platforms unify security data from endpoints, networks, cloud workloads, and email into a single coherent system. Large enterprises are adopting XDR to improve threat visibility and reduce analyst fatigue from managing multiple, disconnected tools. This technology is fragmenting the traditional market for standalone security point products by bundling their core functions into a more integrated offering.
New disclosure mandates from regulators like the US Securities and Exchange Commission (SEC) are altering corporate governance around cybersecurity. The rules compel public companies to report material cyber incidents within a short timeframe, increasing executive accountability. Consequently, demand is rising for incident response retainer services, breach simulation exercises, and board-level reporting tools that can quantify cyber risk.
A significant behavioral change is the move away from large, upfront capital expenditures on security hardware and software licenses. Buyers, especially in the technology and retail sectors, increasingly prefer flexible, consumption-based pricing for security services delivered from the cloud. This trend is most visible in North America and Western Europe, where it pressures vendors to adapt their sales and channel strategies toward recurring revenue models.
Information Security Products and Services Market Segmentation
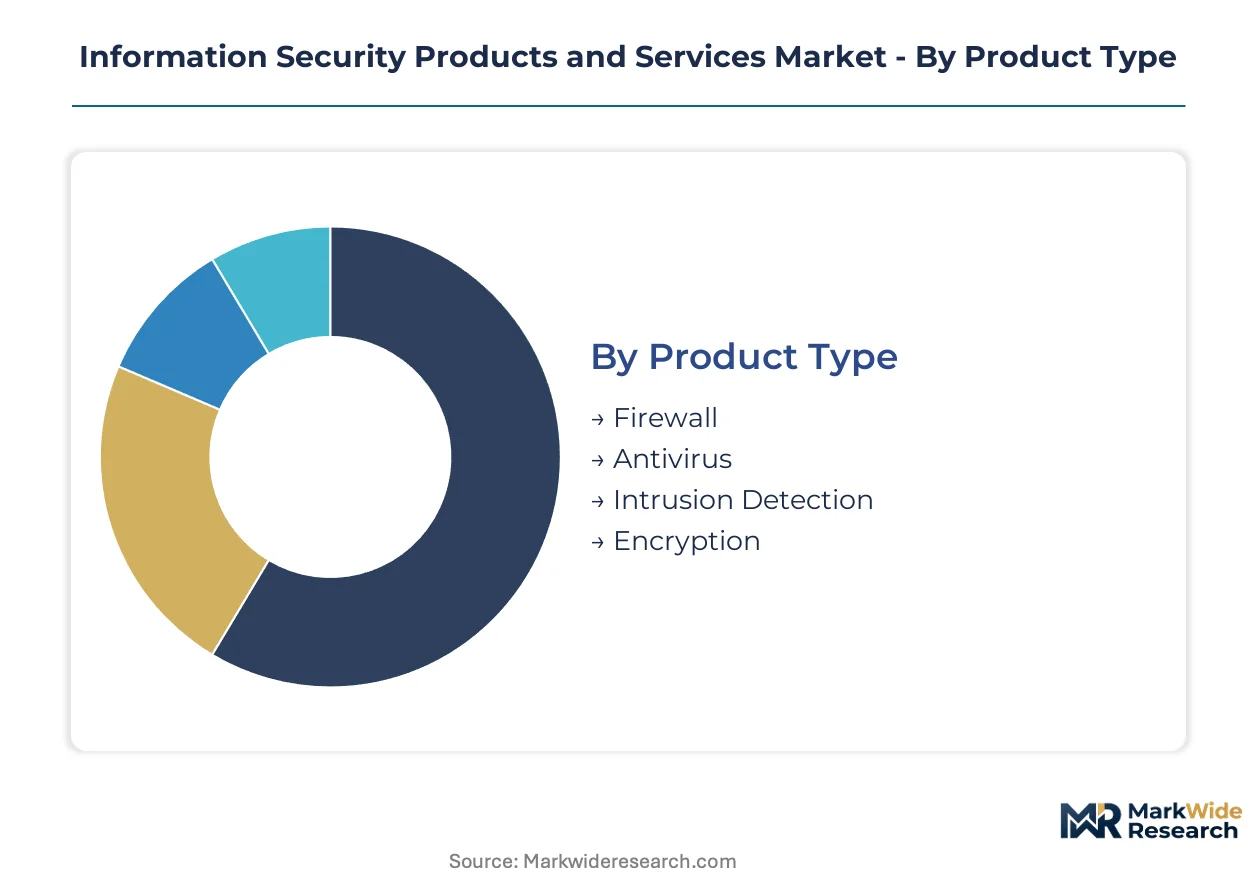
The Information Security Products and Services Market segments across diverse offerings, reflecting the complex and evolving threat landscape. Understanding these distinct categories provides clarity on where enterprise security investments are concentrating and how technological shifts influence purchasing decisions. Each segment addresses specific vulnerabilities and compliance requirements for organizations globally.
Product Type:
The substitution pressure for security product types intensifies as integrated platforms consolidate capabilities, challenging standalone solutions.
- Firewall:These network security devices monitor and filter incoming and outgoing network traffic based on predefined security rules. Demand concentrates in large enterprises and government agencies, driven by the need for robust perimeter defense against sophisticated network intrusions.
- Antivirus:Antivirus software detects, prevents, and removes malicious software, including viruses, worms, and Trojans, from computer systems. Small and medium-sized businesses widely adopt these solutions to protect endpoints, ensuring basic defense against common malware threats.
- Intrusion Detection:Intrusion detection systems (IDS) monitor network or system activities for malicious activity or policy violations, alerting administrators. Financial services organizations extensively deploy IDS for real-time threat detection and rapid response to anomalous behavior.
- Encryption:Encryption products use cryptographic algorithms to transform data into an unreadable format, protecting confidentiality during storage and transmission. Healthcare organizations mandate encryption to comply with data privacy regulations like HIPAA.
Firewall retains volume leadership; Intrusion Detection holds the steepest expansion curve.
Service Type:
Different service types cater to varying organizational capacities and resource availability, from strategic guidance to continuous operational support.
- Consulting:Security consulting services provide expert advice on security strategy, risk assessment, and policy development. Organizations in Europe frequently engage consultants to navigate complex data privacy regulations such as GDPR and CSRD.
- Managed Security:Managed security services outsource security operations, including monitoring, threat detection, and incident response, to third-party providers. Enterprises in North America increasingly adopt these services to address the cybersecurity talent scarcity and ensure 24/7 protection.
- Incident Response:Incident response services help organizations prepare for, detect, contain, and recover from cyberattacks. Financial institutions and critical infrastructure operators prioritize these services to minimize breach impact and maintain operational continuity.
- Compliance:Compliance services assist businesses in meeting regulatory requirements and industry standards, including audits and framework implementation. Government contractors in the US require compliance services to meet stringent standards like FedRAMP.
Managed Security is expanding most quickly; Incident Response secures critical enterprise operations.
End User:
The volume of security investment varies significantly across end-user sectors, dictated by regulatory pressures, data sensitivity, and threat exposure.
- Healthcare:This sector requires stringent security to protect sensitive patient health information, driven by regulations such as HIPAA in the US and GDPR in Europe. Healthcare providers invest in data encryption and access control solutions.
- Financial Services:Financial institutions face constant, sophisticated cyber threats targeting monetary assets and customer data. They drive demand for advanced threat intelligence and fraud detection systems to protect transactions and customer trust.
- Government:Government entities safeguard national security information and citizen data, necessitating high-assurance security solutions. Agencies in the United States prioritize secure cloud deployments and supply chain integrity measures.
- Retail:Retail businesses protect customer payment information and personal data, particularly against point-of-sale malware and e-commerce fraud. They adopt solutions for data loss prevention and secure payment gateways.
Financial services organizations drive substantial investment; government agencies prioritize compliance-driven solutions.
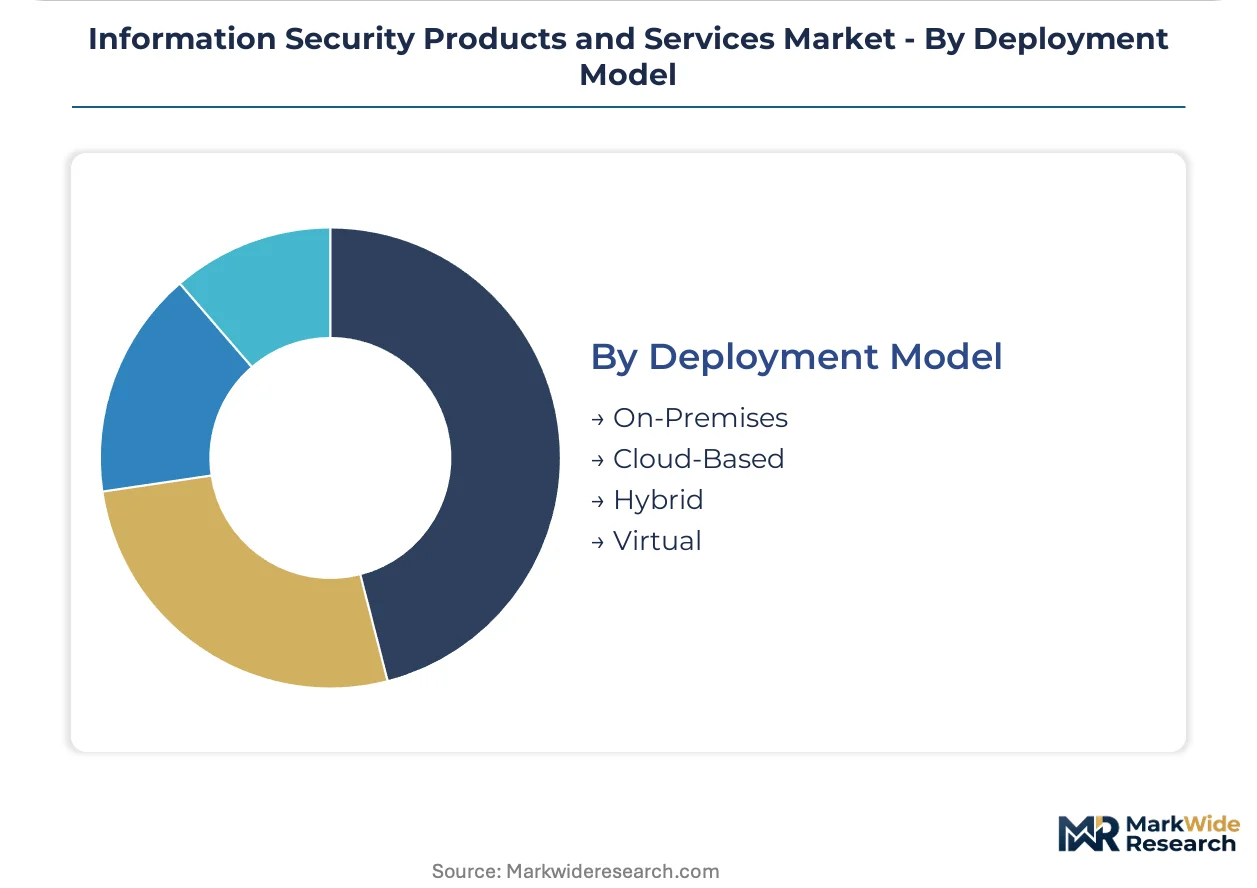
Deployment Model:
The maturity of deployment models ranges from traditional on-premises infrastructure to agile, cloud-native solutions, reflecting the broader IT modernization trend.
- On-Premises:Security solutions are installed and operated within an organization's own infrastructure. Large, legacy enterprises, particularly in banking and government, continue to utilize on-premises deployments for sensitive data control.
- Cloud-Based:Security services are delivered over the internet by a third-party vendor, offering scalability and reduced infrastructure costs. Technology companies in North America rapidly adopt cloud-based security for their distributed operations.
- Hybrid:This model combines on-premises and cloud-based security elements, allowing organizations to leverage both environments. Enterprises with mixed IT environments use hybrid solutions to manage data across various platforms.
- Virtual:Virtual security appliances run on virtualized infrastructure, providing flexible and scalable protection without dedicated hardware. Data centers and service providers implement virtual security for dynamic workload protection.
Cloud-based models capture the largest share of new deployments; hybrid solutions offer transitional flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks globally drive significant investment in information security products and services. These mandates compel organizations to strengthen their digital defenses against a backdrop of escalating cyber threats. Organizations prioritize compliance and data protection across diverse geographical markets.
United States
Demand for advanced cloud security solutions and managed detection and response services is strong. The US's HIPAA and SEC disclosure mandates necessitate robust cybersecurity postures. Technology hubs like Silicon Valley and financial centers in New York City drive innovation and adoption of cutting-edge security technologies.
Germany
Enterprises in Germany focus on data privacy and operational technology security. The EU's GDPR and national cybersecurity laws like the IT-Sicherheitsgesetz compel significant security investments. Industrial centers in Bavaria and North Rhine-Westphalia are implementing specialized solutions for connected manufacturing environments.
China
China's Cybersecurity Law and data localization requirements shape the information security market. Investment focuses on domestic security solutions and compliance services. Major tech companies and government entities in Beijing and Shanghai are building secure digital infrastructures.
India
Underpenetrated small and medium-sized enterprises in India are a major growth vector for scalable, cloud-based security. The country's Personal Data Protection Bill (DPDP Act) is driving new compliance requirements. IT service hubs in Bengaluru and Hyderabad are becoming centers for managed security offerings and cybersecurity talent.
France
French organizations prioritize data protection and incident response capabilities, influenced by GDPR and national security directives. The Agence Nationale de la Sécurité des Systèmes d'Information (ANSSI) sets high standards for government and critical infrastructure. Paris and Lyon host a concentration of cybersecurity startups and consulting firms.
Information Security Products and Services Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of information security offerings. The market structure exhibits a tiered consolidation, with large enterprises dominating foundational security layers while numerous niche players address specific threat vectors. Strategic archetypes include integrated platform providers, specialized point solution vendors, and managed security service providers. Dominant competitive moves involve portfolio diversification and strategic partnerships to offer comprehensive security ecosystems.
Integrated platform providers like Microsoft exemplify the trend toward embedding security across vast cloud infrastructures. Palo Alto Networks anchors the next-generation firewall and cloud-native security platform segment. Cisco Systems, with its strong foundation in network security hardware and integrated threat intelligence, represents another established leader offering broad security portfolios.
| Leading Market Players |
|---|
| IBM |
| Cisco Systems |
| Microsoft |
| Palo Alto Networks |
| Fortinet |
| Check Point Software Technologies |
| Proofpoint |
| Broadcom |
| Zscaler |
| Others |
Cost & Logistics Intelligence
ISO/IEC 27001 certification gates both supplier qualification and influences price differentiation for enterprise-grade security solutions. This standard ensures a baseline of security management, impacting vendor selection and service value for large organizations.
Pricing Analysis
Certification standards like ISO/IEC 27001 create the primary spread in information security pricing. Solutions are typically offered through subscription or SaaS-tiered models, with price differentiation driven by advanced feature sets like XDR capabilities and comprehensive managed services. Pricing pressure stems from increased competition and the shift towards consumption-based cloud models. Small and medium-sized enterprises exhibit higher price sensitivity compared to large government contracts.
Supply Chain Analysis
Strategic stockpiling of cybersecurity talent and intellectual property underpins the information security supply chain. Supply concentration for advanced security solutions centers heavily in the United States, given its innovation hubs and cloud infrastructure, alongside specialized talent pools in India for managed services, and Ireland for data center operations. Key dependencies include skilled professionals and hyperscale cloud platforms. Single-source vulnerability for specialized threat intelligence represents a structural risk. Distribution runs through direct sales and extensive channel partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The information security market represents a high-growth disruption, driven by the proliferation of sophisticated AI-driven cyber threats and evolving global data privacy regulations. This dynamic environment compels continuous adaptation and strategic investment across all market participants.
For Market Incumbents:Shield existing market share by integrating Extended Detection and Response (XDR) platforms to counteract vendor sprawl and reduce attack surface complexity. Acquire niche AI security firms to enhance threat intelligence capabilities against emerging AI-powered attack methodologies. Invest heavily in ISO/IEC 27001 certification processes to maintain competitive positioning for large enterprise and government contracts.
For New Entrants and Emerging Players:Under-served operational technology (OT) security in manufacturing environments represents a significant service-layer gap where new entrants can establish specialized offerings. Target small and medium-sized enterprises (SMEs) in fast-digitizing economies like India with scalable, cloud-based security solutions. A consumption-based pricing model offers a compelling go-to-market angle for these cost-sensitive segments.
For Investors and Strategic Acquirers:New SEC disclosure mandates reshape the acquisition landscape, emphasizing robust governance and incident response capabilities. Long-term viability rests on securing critical digital infrastructure against an ever-evolving threat landscape. Acquisition targets should include specialized AI security startups or managed detection and response (MDR) providers with strong compliance automation platforms. The signal to watch is the continued consolidation of XDR capabilities within larger security ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate XDR Platforms | Unifies threat detection across diverse environments, improving response efficiency for enterprises. |
| Acquire AI Security Specialists | Enhances threat intelligence and automates defense against sophisticated, AI-driven attacks. |
| Expand OT Security Offerings | Addresses a critical vulnerability in industrial control systems and critical infrastructure. |
| Target SME Market with SaaS | Captures underpenetrated segments with scalable, cloud-native security solutions. |
| Invest in Compliance Automation | Streamlines adherence to complex global regulations like GDPR and HIPAA for organizations. |
Research Approach
A spread of perspectives from Chief Information Security Officers (CISOs), security architects, IT procurement managers, and compliance officers converged on the working assumptions for this analysis. This involved combining primary interviews with industry stakeholders and validating insights against secondary sources including SEC filings, government cybersecurity reports, and industry association data, employing both bottom-up and top-down triangulation.
The segmentation dimensions modeled include product type, service type, end-user, deployment model, and regional regulatory adherence, providing a granular view across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical trends, expert projections, and identified market drivers. Key forecast inputs include cybersecurity talent availability and enterprise cloud adoption rates.
Underlying assumptions cover a stable geopolitical climate and continued regulatory enforcement, with deviation risk concentrated in the emergence of unforeseen attack vectors or major shifts in global data sovereignty laws. Revision becomes warranted when significant changes in global cyber warfare or economic downturns cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Application Programming Interface Security Market
Cybersecurity
Greece Cybersecurity Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Wireless Lan Security Market
Cybersecurity
Benelux Cybersecurity Market
Cybersecurity
Enterprise Network Firewall Market
Cybersecurity
Operational Technology Security Market
Cybersecurity
Micro-Segmentation Solutions Market
Cybersecurity
M2M Network Security Market
Cybersecurity
Threat Intelligence Market
Cybersecurity
Cloud Application Security Market