
 E-Mail Security Market | 2026-2036
E-Mail Security Market Size, Share, and Industry Trends Forecast 2026-2036
E-Mail Security Market Foresight
Cloud-native secure email gateway architectures is reconfiguring how threat detection pipelines integrate with enterprise identity systems. Proofpoint Inc. leverages AI-powered behavioral analysis to anchor its position in enterprise email protection. Cisco Systems Inc. competes through deep network security integration across hybrid cloud environments. Fortinet Inc. extends its FortiMail portfolio to dominate mid-market deployments with bundled firewall-email bundles.
E-mail security encompasses technical systems that inspect SMTP traffic, apply TLS encryption protocols, and enforce DMARC authentication standards to prevent business email compromise and data exfiltration. Secure Email Gateway solutions lead product type revenue as organizations replace legacy perimeter appliances, while Cloud-Based deployment models capture the fastest expansion as SaaS email platforms displace on-premises Exchange architectures. Managed Services within the service type dimension concentrate margin pools where providers assume full operational responsibility for threat response and compliance reporting.
The EU AI Act, GDPR, and NIS2 Directive collectively mandate encrypted transmission, audit logging, and incident disclosure for electronic communications across European enterprises. The Federal Trade Commission in the United States enforces Section 5 unfair practices standards against organizations failing to secure consumer email data. Stakeholders must monitor how generative AI-enabled phishing campaigns force continuous recalibration of detection algorithms and staff training protocols.
Market Dynamics
Generative AI-enabled phishing campaigns are collapsing traditional signature-based detection efficacy and forcing enterprises toward continuous behavioral retraining of both algorithms and staff protocols.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident disclosure and encrypted transmission requirements across European critical infrastructure operators are accelerating replacement cycles for legacy email gateways.
- Financial services:Banks and payment processors in Germany, France, and the United Kingdom are deploying advanced threat protection platforms to counter business email compromise attacks targeting wire transfer systems.
- Cloud-native architectures:SaaS email platforms displacing on-premises Exchange installations are creating demand for API-integrated security layers rather than perimeter appliances.
Market Restraints
- Skilled analyst shortage:The scarcity of SOC personnel capable of tuning AI detection models and investigating false positives constrains enterprise adoption velocity.
- Integration complexity:Legacy on-premises email servers in regulated industries resist seamless API connectivity with cloud-native security services, extending deployment timelines.
- Alert fatigue saturation:Overwhelming volumes of low-confidence threat indicators degrade response quality and drive buyer skepticism toward expanded platform licensing.
Strategic Opportunities
- Managed detection and response:Providers assuming full operational responsibility for threat response and compliance reporting capture margin pools unavailable to pure software vendors.
- Mid-market bundling:Firewall-email security bundles address budget-constrained organizations seeking consolidated vendor relationships rather than best-of-breed point solutions.
- DMARC enforcement services:Authentication standard deployment assistance represents an underpenetrated service layer as spoofing attacks proliferate against brand-dependent sectors.
Industry Challenges
- Algorithmic arms race:Adversarial machine learning techniques employed by threat actors force continuous recalibration of detection models, compressing development cycles.
- Cross-border data sovereignty:Conflicting encryption key custody requirements between jurisdictions complicate cloud deployment architectures for multinational enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Mail Security Market |
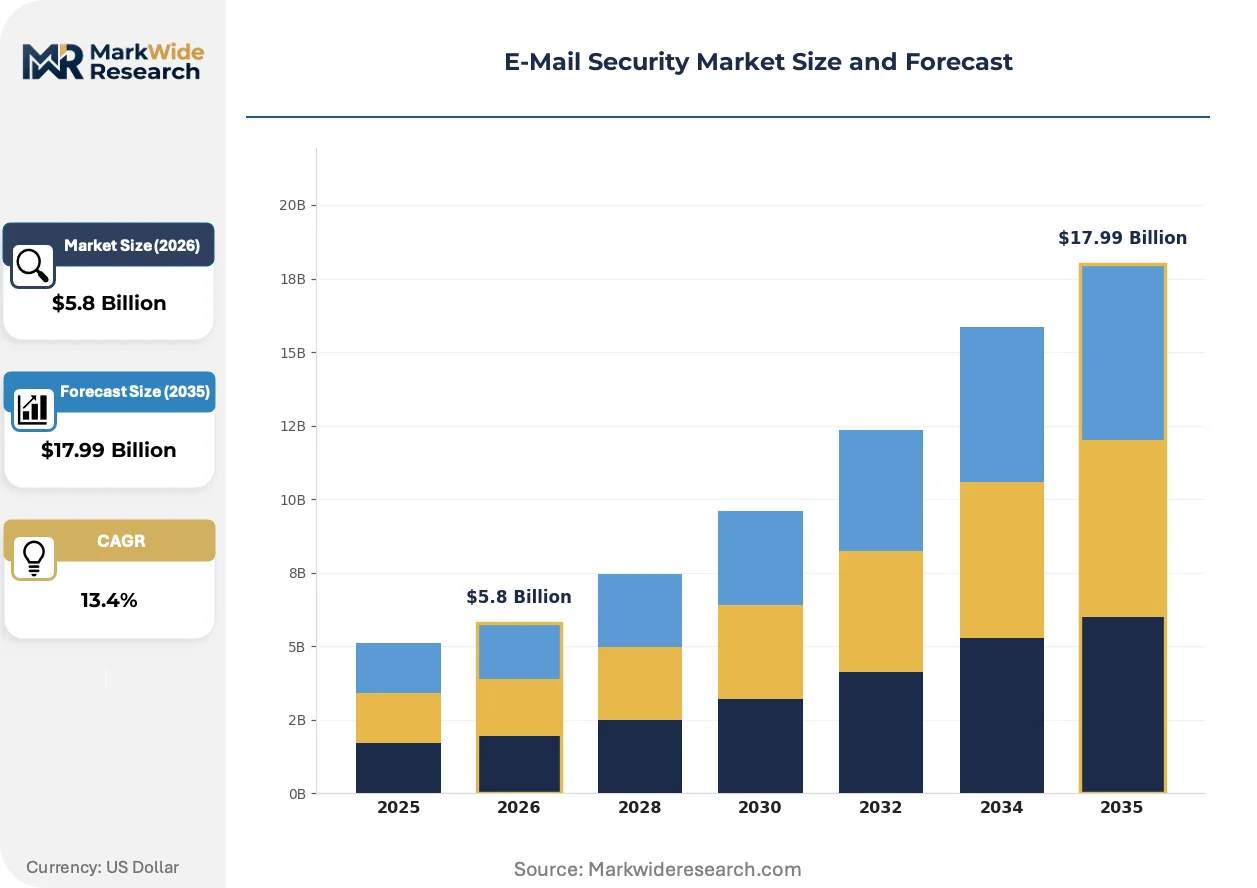
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $17.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Secure Email Gateway, Email Encryption, Email Archiving, Spam Filtering Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Businesses, Enterprises, Government Agencies, Educational Institutions Service Type: Managed Services, Professional Services, Consulting, Technical Support |
| Companies Covered | Proofpoint Inc., Cisco Systems Inc., Fortinet Inc., Barracuda Networks Inc., Trend Micro Inc., Mimecast Limited, Microsoft Corporation, Broadcom Inc., Sophos Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Mail Security Market Shifts & Advancements
Behavioral biometrics and natural language processing are reconfiguring how identity verification integrates with email threat detection, compressing the window between compromise and containment.
Natural language generation detection systems is collapsing the distinction between legitimate business correspondence and AI-crafted phishing content. Financial institutions in London and Frankfurt are deploying these tools at enterprise scale. The technology is collapsing response latency from hours to minutes for credential-harvesting campaigns.
The EU AI Act's risk classification framework for automated decision-making systems is mandating human-in-the-loop review protocols for high-risk email filtering algorithms. Security vendors must now document training data provenance and algorithmic transparency. European enterprises are responding by demanding audit trails that satisfy both GDPR and AI Act compliance officers.
Consolidated platform procurement is displacing point-solution accumulation as CISOs reduce vendor management overhead. Mid-market buyers in particular are abandoning standalone email security appliances for integrated SASE architectures. France and Germany show the most pronounced consolidation behavior, with buyers prioritizing unified policy management across network and email security stacks.
E-Mail Security Market Segmentation
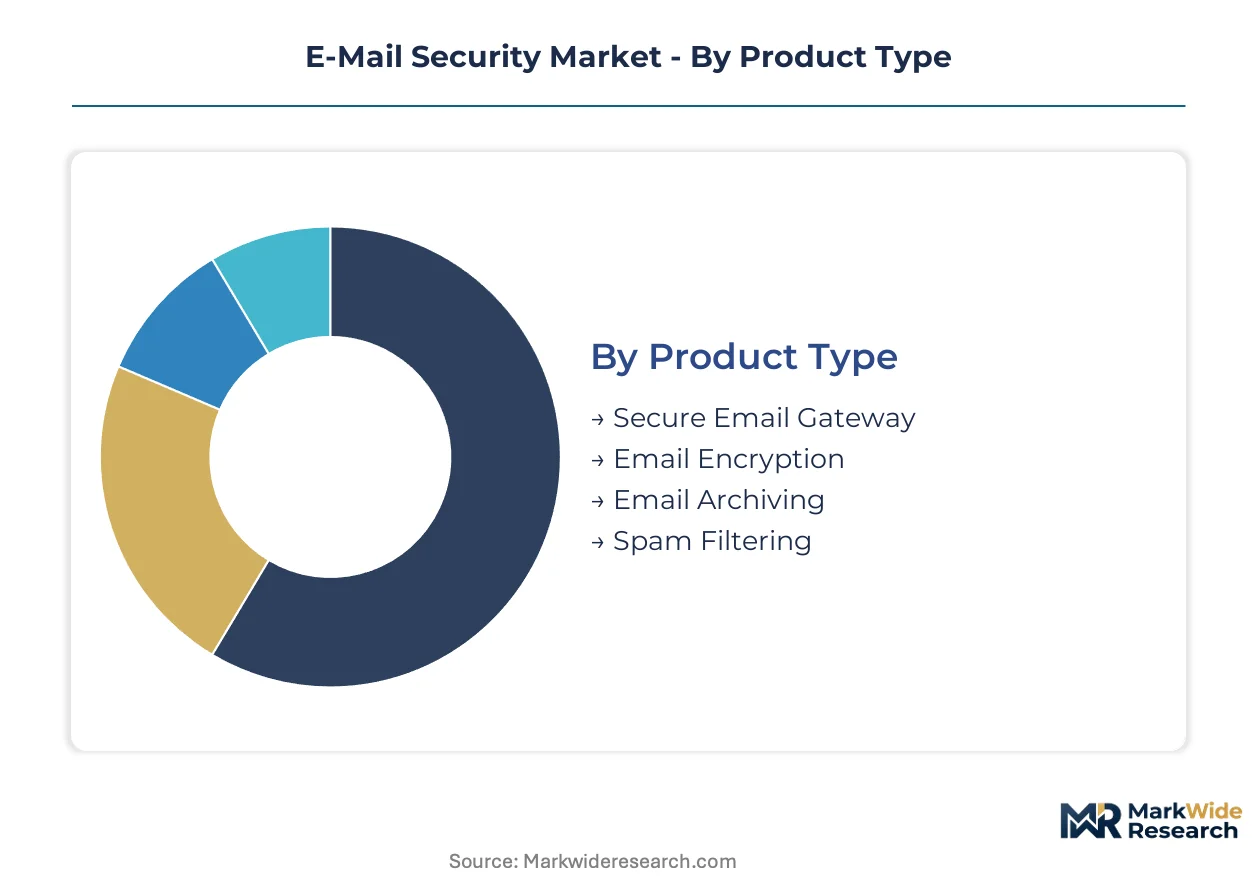
E-mail security procurement patterns diverge sharply across organizational scale and technical architecture. Buyers prioritize different capability bundles—perimeter inspection versus encryption-at-rest versus compliance archiving—based on legacy infrastructure and regulatory exposure.
Product Type:
After-sales service intensity peaks with Secure Email Gateway deployments, where vendors assume continuous threat signature updates and false-positive tuning.
- Secure Email Gateway:SMTP traffic inspection appliances and virtual appliances that enforce TLS encryption, malware scanning, and URL rewriting. Banks in Germany and France deploy these at network edge positions to intercept business email compromise attempts before inbox delivery.
- Email Encryption:Content-level protection using S/MIME or PGP protocols with centralized key management. Healthcare providers in the United Kingdom concentrate demand here under NHS Digital compliance mandates for patient data transmission.
- Email Archiving:Immutable storage systems satisfying legal hold and e-discovery requirements.
- Spam Filtering:Reputation-based and heuristic filtering for unsolicited bulk email.
Secure Email Gateway holds the largest share; momentum sits with Email Encryption as GDPR Article 32 enforcement tightens.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from operational-expense cloud models favored by mid-market buyers.
- Cloud-Based:API-integrated security layers operating inline with Microsoft 365 and Google Workspace. Financial services firms in London and Frankfurt are displacing perimeter appliances with these architectures to support hybrid workforces.
- SaaS:Fully managed subscription services with zero infrastructure footprint. Small businesses across the United Kingdom adopt these for rapid deployment without dedicated security staff.
- On-Premises:Physical or virtual appliances maintained within organizational data centers.
- Hybrid:Split configurations preserving sensitive traffic on-premises while routing general correspondence through cloud gateways.
Cloud-Based configurations dominate new procurement; SaaS is climbing the fastest as vendor consolidation accelerates.
End User:
Application intensity varies—enterprises demand behavioral analytics while government agencies prioritize classification and audit trails.
- Enterprises:Large organizations with dedicated SOC teams requiring advanced threat protection, sandboxing, and SIEM integration. German automotive manufacturers and French aerospace contractors represent concentrated demand for these capabilities.
- Government Agencies:Public sector bodies with classified or sensitive citizen data. UK central government departments under the Government Security Classifications Policy drive specialized procurement here.
- Small Businesses:Organizations under 500 employees with limited security staffing.
- Educational Institutions:Universities and school districts managing high-volume, low-sensitivity correspondence.
Enterprises command the largest segment; government procurement is expanding most quickly under NIS2 Directive critical infrastructure designations.
Service Type:
Margin concentration follows operational responsibility—vendors capturing full threat response capture recurring revenue unavailable to software-only suppliers.
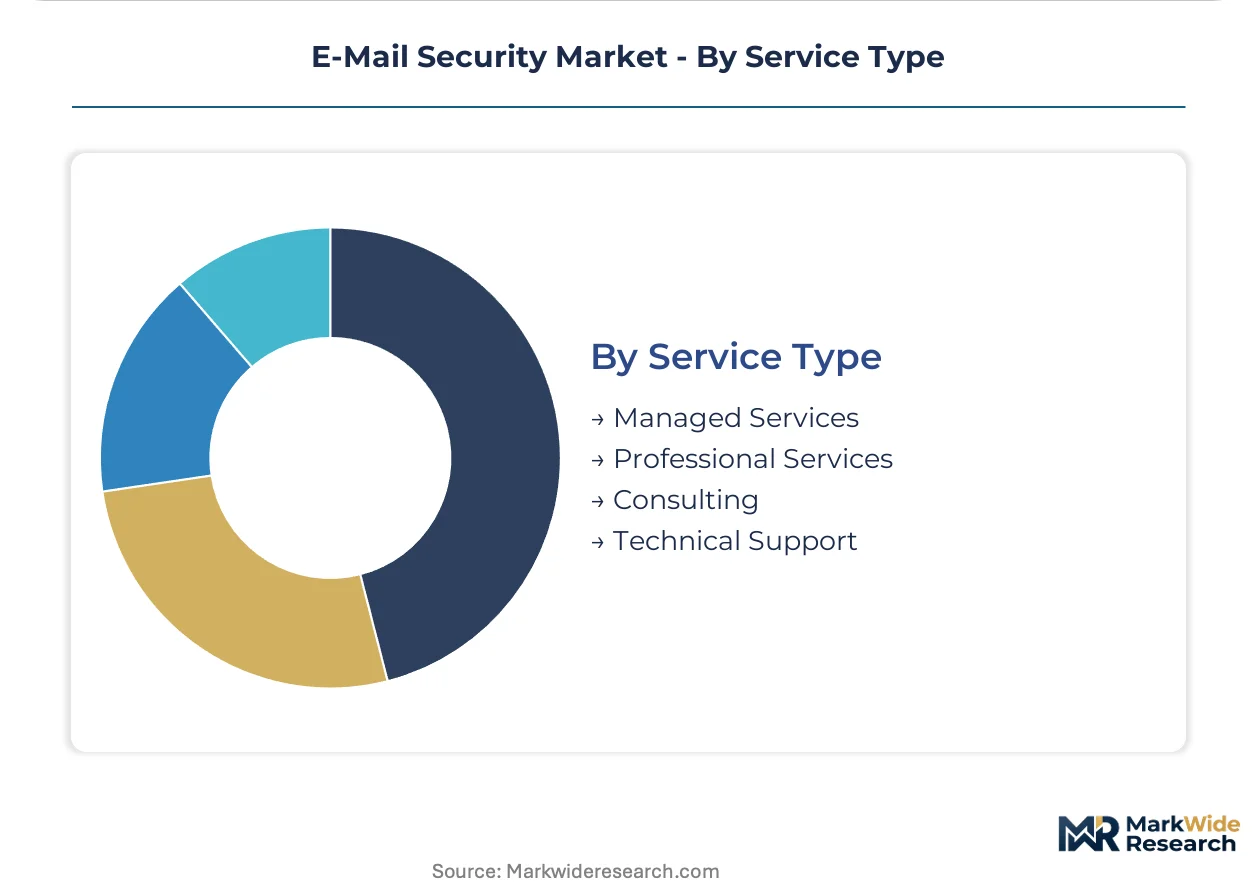
- Managed Services:Complete operational outsourcing including 24/7 monitoring, incident response, and compliance reporting. French banking consortiums and German energy utilities contract these services to address SOC analyst shortages.
- Professional Services:Implementation, migration, and integration projects for complex deployments. UK National Health Service trusts utilize these for legacy Exchange-to-cloud transitions.
- Consulting:Advisory engagements for security architecture and policy development.
- Technical Support:Break-fix and maintenance contracts for licensed software.
Managed Services holds the largest share; Professional Services sees steepest expansion as cloud migration complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German financial institutions and French aerospace contractors concentrate procurement of advanced email security platforms, while UK healthcare trusts drive encryption demand under NHS Digital mandates.
United States
Financial services firms and federal agencies anchor North American procurement volumes. The FTC enforces Section 5 unfair practices standards against organizations failing to secure consumer email data. New York and Chicago banking clusters deploy behavioral analytics to counter wire transfer fraud schemes.
Germany
Automotive manufacturers and energy utilities dominate enterprise adoption of secure email gateways. The NIS2 Directive mandates encrypted transmission and incident disclosure for critical infrastructure operators. Munich and Stuttgart industrial corridors replace legacy perimeter appliances with cloud-native architectures.
United Kingdom
NHS Digital compliance mandates drive healthcare sector encryption procurement. The Government Security Classifications Policy shapes specialized procurement for central government departments. London financial services firms deploy API-integrated security layers alongside Microsoft 365 migrations.
France
Aerospace contractors and banking consortiums concentrate demand for managed detection services. The CNIL enforces GDPR Article 32 requirements for patient data transmission security. Paris and Toulouse defense-industrial clusters prioritize unified policy management across network and email stacks.
Japan
Manufacturing conglomerates and telecommunications operators drive mid-market bundling demand. METI guidelines encourage zero-trust architectures for supply chain communications. Tokyo and Osaka enterprise clusters adopt SaaS email security to reduce dedicated security staffing requirements.
E-Mail Security Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where bundled platform vendors capture mid-market consolidation while best-of-breed specialists defend enterprise accounts. The vendor landscape separates into three archetypes: network-security incumbents extending email modules, pure-play email security specialists, and cloud-platform giants integrating native protection. Dominant competitive moves include portfolio diversification into adjacent SASE capabilities and strategic partnerships to embed email security within broader zero-trust architectures.
Within the network-security incumbent tier, Cisco Systems Inc. and Fortinet Inc. occupy positions defined by firewall-email bundling strategies. Proofpoint Inc. anchors the pure-play specialist segment. These three exemplify how competitive positioning diverges between consolidation-driven mid-market penetration and behavioral analytics-driven enterprise retention.
| Leading Market Players |
|---|
| Proofpoint Inc. |
| Cisco Systems Inc. |
| Fortinet Inc. |
| Barracuda Networks Inc. |
| Trend Micro Inc. |
| Mimecast Limited |
| Microsoft Corporation |
| Broadcom Inc. |
| Sophos Ltd. |
| Others |
Supply & Pricing Matrix
Amsterdam-Rotterdam-Antwerp freight corridors transmit silicon wafer and cryptographic component shipments from Asian foundries to European assembly plants, with container rate volatility feeding directly into tiered SaaS subscription pricing and hardware appliance cost structures across German and French security vendors.
Pricing Analysis
Cost-plus contracts with semiconductor indexation anchor enterprise licensing agreements, particularly for Secure Email Gateway appliances incorporating dedicated ASICs for TLS acceleration. Three-tier pricing structure across premium, standard, and economy levels separates behavioral analytics bundles from basic spam filtering, with customization depth and SOC integration complexity as primary differentiation drivers. Pricing pressure stems from hyperscaler-native email platforms bundling baseline protection at marginal cost, compressing standalone vendor margins. Mid-market buyers in the United Kingdom exhibit highest price sensitivity, while German automotive manufacturers prioritize certification-grade solutions with reduced cost elasticity.
Supply Chain Analysis
Contract manufacturing for security appliance hardware concentrates with Foxconn, Jabil, and Flex facilities in Taiwan, Malaysia, and Mexico, with firmware development and threat intelligence pipelines anchored in Israel, United States, and United Kingdom engineering centers. Production draws from specialized semiconductor foundries in Taiwan and South Korea for cryptographic processors, NAND flash from South Korea and Japan, and precision connectors from China and Vietnam. Single-source vulnerability in advanced node fabrication for AI inference chips presents concentrated supply risk. Distribution runs through value-added resellers and direct enterprise sales teams, with managed services provisioning shifting toward cloud-native API delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-mail security sits in early-cycle expansion as NIS2 Directive compliance deadlines force critical infrastructure operators across Europe into accelerated replacement procurement, creating penetration tailwinds absent in mature cybersecurity segments.
For Market Incumbents: Insulate enterprise accounts against hyperscaler displacement by embedding behavioral analytics into Microsoft 365 and Google Workspace API layers, reducing friction for hybrid workforce deployments. Deepen vertical integration into threat intelligence feeds through exclusive partnerships with financial sector information sharing centers, creating switching costs that pure cloud-native competitors cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in DMARC enforcement services for brand-dependent sectors, where spoofing attack volumes outpace incumbent professional services capacity and pricing remains undefined. Target French banking consortiums and German mid-market manufacturers with managed detection and response offerings that assume full SOC responsibility, bypassing direct competition with Cisco and Fortinet in appliance markets. For Investors and Strategic Acquirers: Cloud-native API security specialists with pre-built Microsoft 365 integrations represent the highest-probability acquisition archetype for platform consolidation plays. Long-term viability hinges on sustained R&D intensity to maintain algorithmic parity against generative AI-enabled phishing campaigns. Monitor hyperscaler security bundle pricing announcements as the critical inflection signal for standalone vendor margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native deployment with Microsoft 365 and Google Workspace captures cloud migration spend in London and Frankfurt banking clusters. |
| Managed Detection and Response | Full SOC outsourcing addresses analyst scarcity in French energy utilities and German automotive supply chains. |
| DMARC Enforcement Services | Authentication deployment assistance targets underpenetrated brand protection budgets in UK retail and aerospace sectors. |
| Strategic Partnership | Zero-trust architecture embedding with SASE vendors consolidates procurement decisions for mid-market buyers. |
| Acquisition of Specialist Firm | Natural language generation detection capabilities compress response latency against AI-crafted phishing campaigns. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CISOs at German automotive manufacturers, security architects at London financial services firms, procurement leads at French aerospace contractors, and channel partners distributing across the United Kingdom and Benelux. Secondary validation incorporated SEC filings from publicly traded vendors, EU NIS2 Directive implementation guidance documents, NHS Digital compliance frameworks, and customs data on security appliance imports. Bottom-up sizing from product-type deployment volumes was triangulated against top-down IT security budget allocation surveys.
Calibration against historical adoption curves for cloud-based email platforms and on-premises Exchange displacement patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, deployment model, organization scale, service type, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for compliance mandate acceleration and generative AI threat vector expansion. Forecast inputs incorporated SOC analyst hiring rates and hyperscaler security bundle attach rates.
Stress conditions across NIS2 enforcement timing, hyperscaler pricing aggression, and generative AI phishing volume acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology substitution elasticities. Quarterly review of hyperscaler security bundle pricing and EU critical infrastructure designation expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Global Serverless Security Market
Cybersecurity
Network Detection and Response Market
Cybersecurity
Global Automated Breach and Attack Simulation (BAS) Market
Cybersecurity
Wireless Lan Security Market
Cybersecurity
India Cybersecurity Market
Cybersecurity
Spain Cybersecurity Market
Cybersecurity
Cloud-Based Database Security Market
Cybersecurity
Data-Centric Security Market
Cybersecurity
Asia Pacific Digital Forensics Market
Cybersecurity
CDN Security Market
Cybersecurity
Asia-Pacific Cloud DLP Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
Threat Hunting Market
Cybersecurity
Europe Mobile Security Market
Cybersecurity
Europe Cybersecurity Market