
 Global Call Center Platform Market | 2026-2036
Global Call Center Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Call Center Platform Market Foresight
Aftermarket service revenue from legacy on-premise installations is reconfiguring vendor economics toward recurring cloud subscriptions. Genesys Telecommunications Laboratories, Inc. leverages its hybrid architecture to anchor enterprise migrations. Cisco Systems, Inc. competes through deep network infrastructure integration. Five9, Inc. specializes in pure-play cloud delivery for mid-market buyers.
A call center platform is an integrated software stack that manages inbound and outbound customer communications across voice, digital, and messaging channels, typically processing call routing through automatic call distribution algorithms with sub-second latency requirements. Its primary purpose is to optimize agent productivity, reduce average handle time, and maintain service level agreements in high-volume contact center environments. Cloud-based deployment leads in new bookings as enterprises abandon capital-intensive server farms. AI-powered solutions represent the fastest-expanding category within the solution dimension, with natural language processing engines now handling tier-one query resolution without human intervention.
The U.S. FCC enforces telemarketing and robocall restrictions that shape outbound dialing architecture requirements, while HIPAA compliance obligations constrain how healthcare call centers handle protected information across platform layers. The EU AI Act introduces risk classification for automated decision-making in customer interactions, forcing vendors to embed audit trails and human oversight mechanisms. India's TRAI regulations on telemarketer registration and Do Not Disturb enforcement create localized compliance modules that vendors must maintain for market access. Stakeholders should evaluate which regulatory frameworks will tighten fastest and align platform roadmaps accordingly.
Market Dynamics
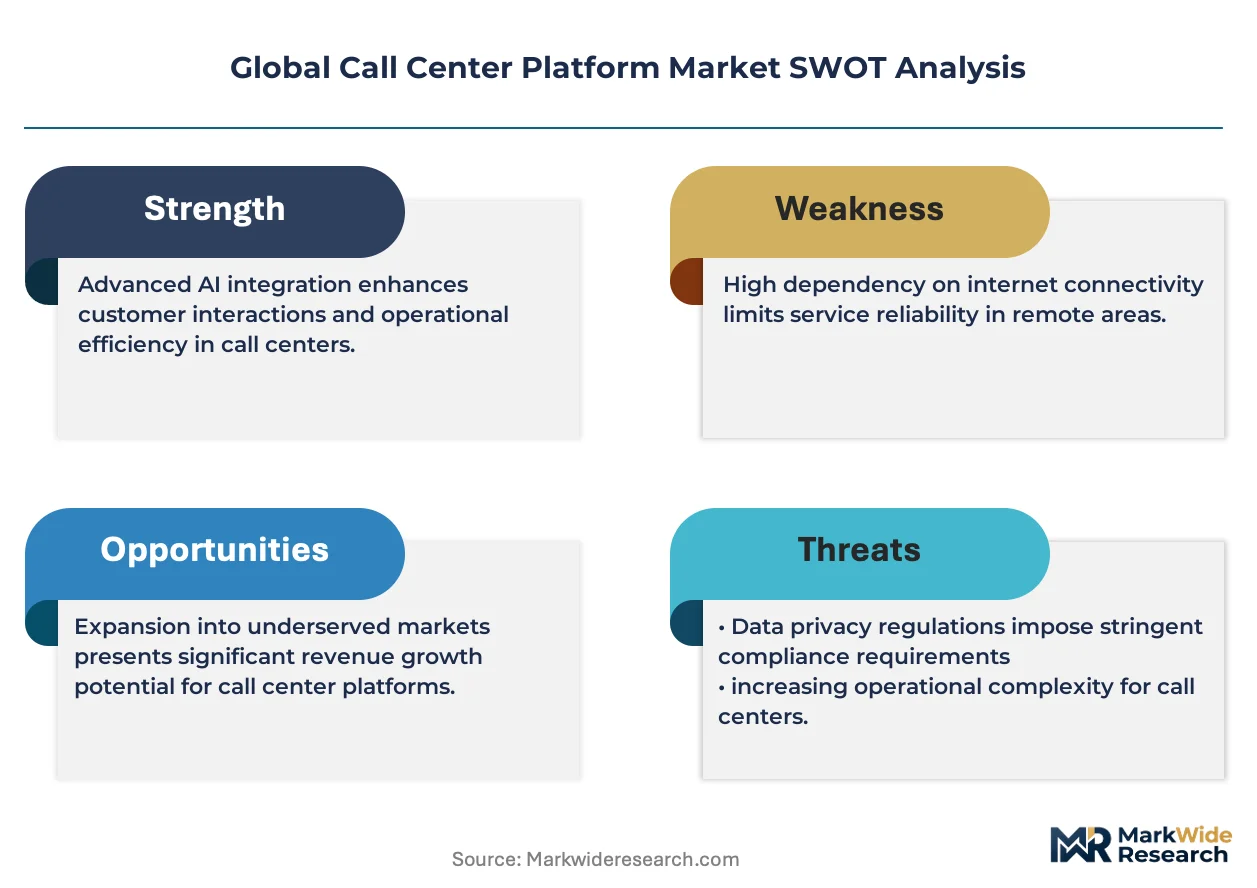
Cloud migration is compressing vendor revenue models from perpetual licenses to consumption-based subscriptions, forcing incumbents to rebuild sales compensation and R&D allocation around recurring metrics rather than upfront deals.
Growth Catalysts
- EU AI Act enforcement:European contact centers face mandatory risk classification for automated decision systems, triggering wholesale platform replacements that embed audit trails and human oversight by design.
- BFSI modernization budgets:Banking and insurance institutions are reallocating capital from branch networks to unified customer engagement infrastructure, prioritizing platforms that consolidate voice, chat, and video channels.
- Natural language processing engines:Self-service resolution rates for tier-one queries now operate without agent intervention, expanding addressable call volume without linear headcount expansion.
Market Restraints
- Telephony cost volatility:Voice minute pricing fluctuates with carrier interconnection disputes, squeezing margins for providers offering unlimited calling plans to enterprise buyers.
- Concentrated cloud infrastructure:Three hyperscalers control the underlying compute and storage layers that power most cloud-native deployments, creating supplier power asymmetry.
- HIPAA technical safeguards:Healthcare call centers must implement access controls, encryption, and audit logging across every platform layer, extending sales cycles and implementation timelines.
Strategic Opportunities
- India's digital-first infrastructure:Enterprise scaling in Mumbai, Bangalore, and Hyderabad demands cloud-native platforms capable of handling vernacular language support and TRAI-compliant telemarketer registration systems.
- ISO 27001 certification convergence:Buyers increasingly mandate information security management certification as a table-stakes requirement, creating differentiation for vendors that front-load compliance investment.
- Workforce engagement management fusion:Platforms that integrate quality management, coaching, and gamification with core routing engines capture expanded budget from operations leaders seeking agent retention improvements.
Industry Challenges
- Conversational AI talent scarcity:Shortage of linguists and machine learning engineers capable of training intent models in low-resource languages delays product localization for emerging markets.
- On-premise technical debt:Enterprises running legacy automatic call distribution hardware face forklift upgrade costs and data migration complexity that stall cloud transition decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Call Center Platform Market |
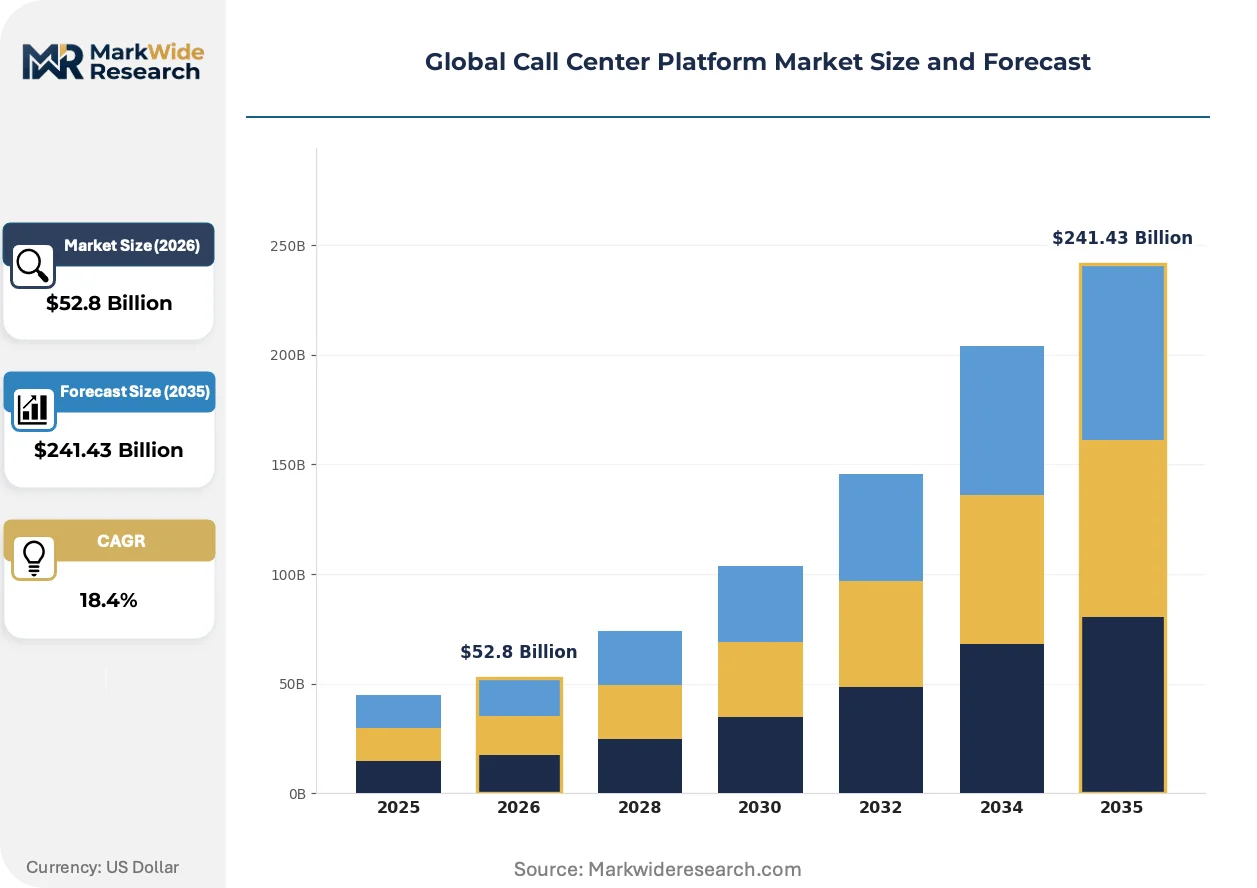
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $241.43 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Hosted End User: Telecom, BFSI, Retail, Healthcare Deployment: Public Cloud, Private Cloud, Virtual, Dedicated Solution: AI-Powered, Omnichannel, Automatic Call Distributor, Analytics |
| Companies Covered | Genesys Telecommunications Laboratories, Inc., Cisco Systems, Inc., Avaya Holdings Corp., Five9, Inc., Talkdesk, Inc., NICE, Twilio, Amazon Web Services, Inc., Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Call Center Platform Market Shifts & Advancements
Artificial intelligence is collapsing the traditional separation between self-service and assisted-service channels, forcing platform architects to design continuous handoff mechanisms rather than discrete channel silos.
Large language models are hybridizing contact center architecture by embedding generative response capabilities directly into agent desktops. Retail and telecommunications buyers are deploying these copilot functions within eighteen-month refresh cycles. The technology is compressing training timelines for new hires while elevating handle-time expectations for experienced staff.
The EU AI Act introduces binding transparency requirements for emotion recognition systems deployed in customer interactions. Vendors must now document training data provenance and maintain human-in-the-loop override capabilities. Financial services and healthcare verticals in Germany and France are prioritizing platforms with pre-built compliance modules to accelerate procurement approvals.
Enterprise buyers are consolidating vendor relationships around platforms that bundle workforce optimization with core routing. Mid-market contact centers in the United States are abandoning best-of-breed point solutions in favor of integrated suites that reduce integration overhead. This preference shift favors providers with native quality management and analytics rather than those dependent on third-party connectors.
Global Call Center Platform Market Segmentation
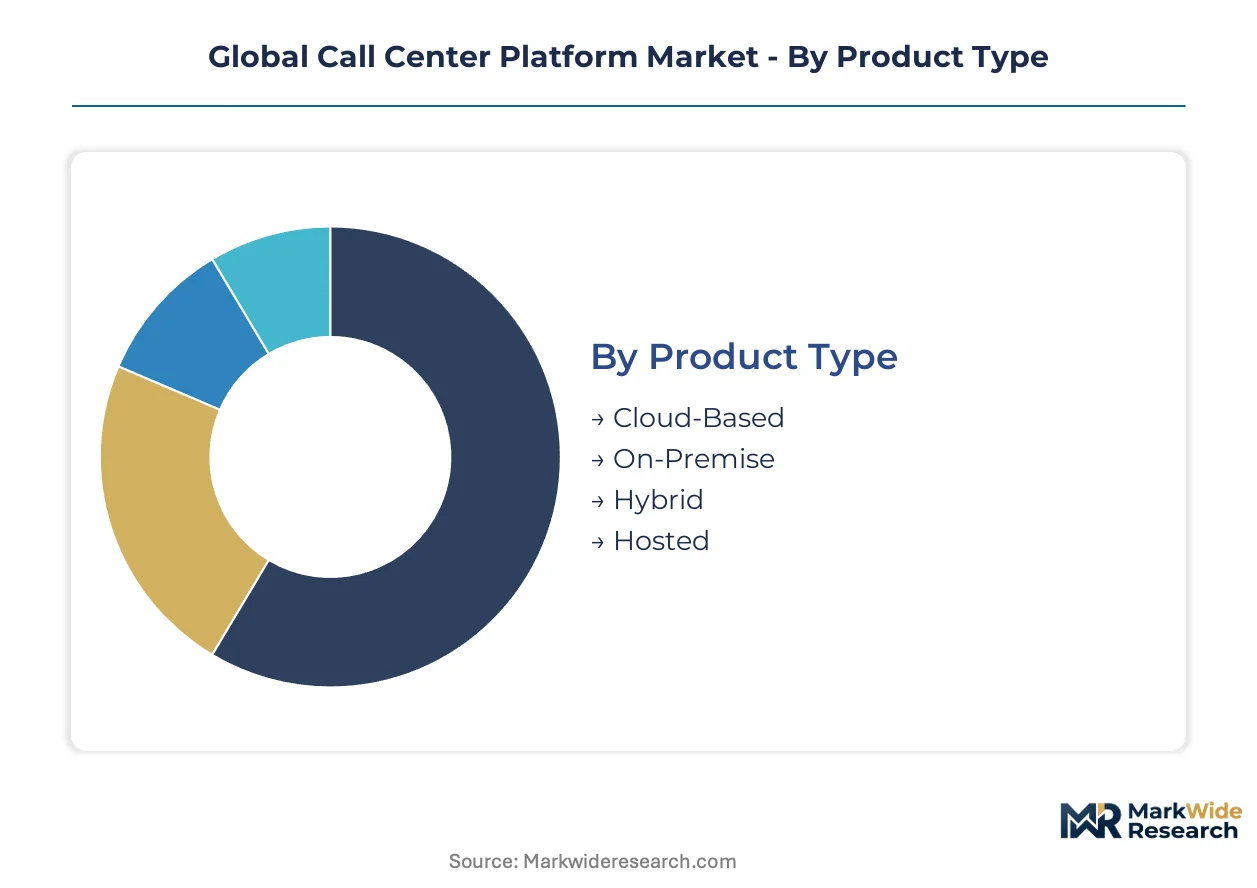
Call center platform buyers segment procurement decisions across infrastructure architecture, regulatory exposure, and channel complexity. Each dimension carries distinct technical requirements and vendor evaluation criteria.
Product Type:
Use-case spectrum spans capital-preserving startups to compliance-bound institutions with legacy investments.
- Cloud-Based:Multi-tenant architectures deliver automatic scaling and zero hardware maintenance. Banking contact centers in India and retail operations in Germany favor this model for rapid deployment without data center capital. Consumption-based billing aligns cost with seasonal volume fluctuation.
- On-Premise:Dedicated hardware installations maintain complete data sovereignty and custom security postures. Healthcare systems under HIPAA and European banks under GDPR constraints select this option for audit trail control. High upfront capital and internal IT burden limit expansion to regulated verticals.
- Hybrid:Split workloads between cloud elasticity and on-premise critical systems. Enterprises with phased migration timelines use this bridge architecture to preserve legacy automatic call distribution investments while adding cloud channels.
- Hosted:Single-tenant managed services in third-party data centers offer dedicated resources without internal infrastructure management. Mid-market buyers lacking internal telephony expertise select this for professional operations support.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
End User:
Vertical-specific compliance and interaction patterns reshape platform configuration requirements.
- Telecom:Massive scale inbound routing with real-time billing integration and churn prediction analytics. Indian and Brazilian carriers drive demand for vernacular language AI and TRAI-compliant telemarketer modules.
- BFSI:Multi-factor authentication, PCI-DSS compliance, and wealth management video banking. European institutions under EU AI Act mandate risk-classified automation with human override protocols.
- Retail:Seasonal elasticity requirements and omnichannel order management. Peak handling during promotional periods demands auto-scaling infrastructure.
- Healthcare:HIPAA technical safeguards across encryption, access logging, and business associate agreements. Appointment scheduling and prescription refill automation dominate use cases.
Telecom captures the largest transaction volumes; Healthcare presents the steepest compliance premium.
Deployment:
Infrastructure control levels segment buyers by risk tolerance and data residency mandates.
- Public Cloud:Shared infrastructure with hyperscaler economics. Startups and mid-market enterprises prioritize speed over isolation.
- Private Cloud:Dedicated single-tenant environments with custom network policies. Financial services in Singapore and healthcare in Switzerland select this for regulatory comfort.
- Virtual:Software-defined instances on commodity hardware. Cost-conscious buyers with internal virtualization expertise favor this for license optimization.
- Dedicated:Bare-metal servers with no resource contention. High-volume outsourcers in Philippines and India deploy this for predictable latency on voice quality.
Public Cloud dominates new bookings; Private Cloud commands the highest annual contract values.
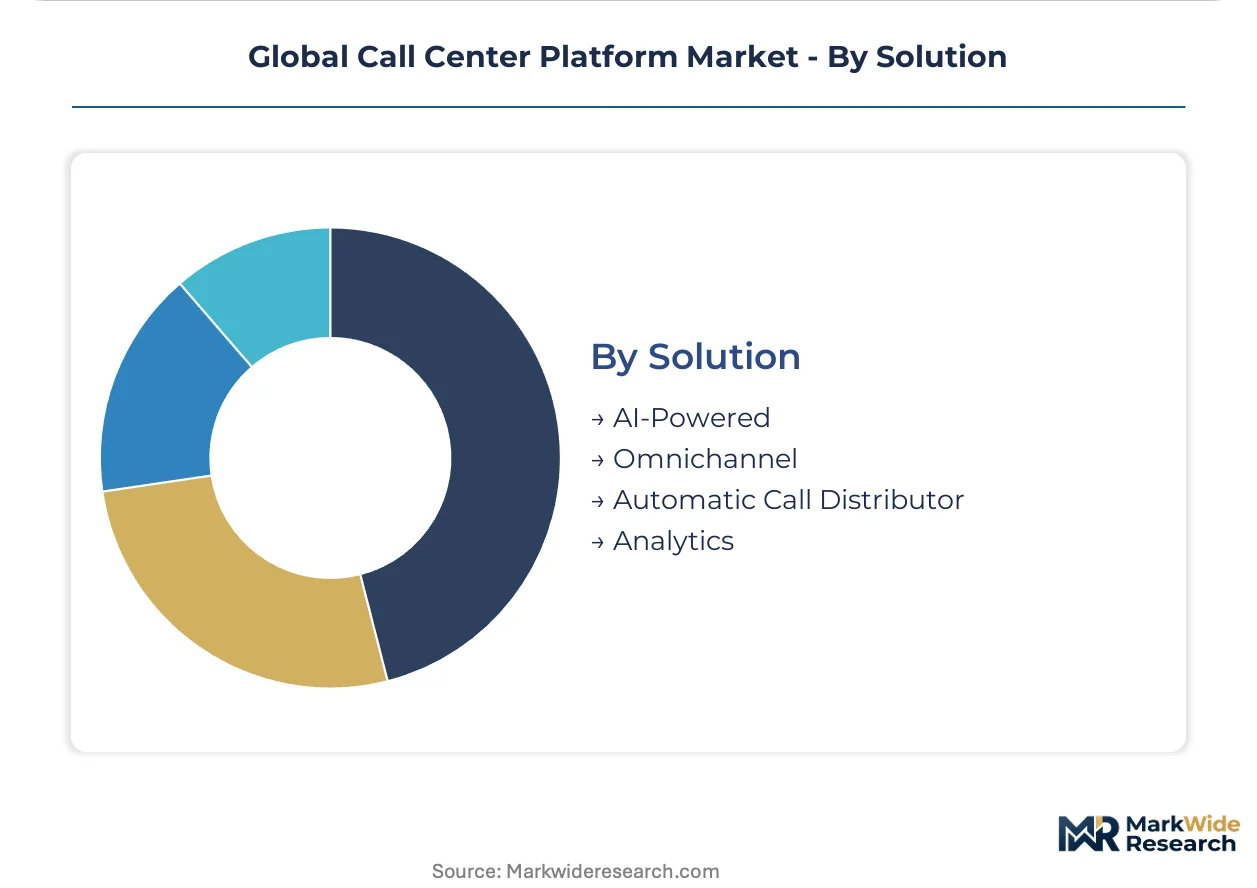
Solution:
Functional modules determine whether platforms replace point solutions or consolidate vendor relationships.
- AI-Powered:Natural language processing engines handle tier-one resolution without agent intervention. Intent classification and sentiment analysis reduce average handle time in retail and telecom deployments.
- Omnichannel:Unified routing across voice, chat, email, and messaging with continuous conversation context. Customer journey visibility prevents channel repetition frustration.
- Automatic Call Distributor:Skills-based routing algorithms with sub-second decision latency. Workforce optimization integration elevates this core function beyond basic queue management.
- Analytics:Real-time and historical dashboards for quality management and predictive staffing. Speech analytics extract compliance and coaching insights from recorded interactions.
Automatic Call Distributor remains the baseline procurement; AI-Powered solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers demonstrate the highest price elasticity, squeezing vendors on per-seat licensing, while Swiss healthcare and German financial institutions absorb substantial compliance premiums without volume contraction.
United States
FCC telemarketing enforcement and HIPAA technical safeguard mandates drive platform replacement cycles among healthcare payers and outbound BPOs. The FCC's STIR/SHAKEN authentication protocols force voice infrastructure overhauls. Dallas-Fort Worth and Phoenix host expanding captive centers for retail and insurance verticals.
Germany
EU AI Act risk classification requirements and GDPR data residency rules compel financial services to abandon US-hosted solutions. The BaFin supervisory framework demands audit trails for automated credit decisions. Frankfurt's banking cluster and Munich's insurance hub are consolidating vendor relationships around compliant European cloud instances.
India
TRAI telemarketer registration mandates and vernacular language AI demand reshape procurement specifications for domestic enterprises and global outsourcers. The Digital India program accelerates cloud-first customer service infrastructure in tier-two cities. Hyderabad, Bangalore, and Pune dominate new seat deployment for banking, telecom, and e-commerce platforms.
United Kingdom
FCA consumer duty obligations and post-Brexit data adequacy negotiations complicate cross-border hosting arrangements for insurance and wealth management contact centers. The Information Commissioner's Office enforces GDPR-equivalent standards through domestic legislation. London's fintech cluster and Manchester's shared service centers prioritize platforms with pre-built regulatory modules.
Brazil
ANATEL quality-of-service regulations and LGPD data protection implementation create dual compliance burdens for telecommunications carriers and retail banks. Central bank open banking mandates require API-integrated customer engagement infrastructure. São Paulo's financial district and Rio de Janeiro's telecom headquarters drive demand for Portuguese-language AI and elastic cloud capacity.
Global Call Center Platform Market Competitive Landscape
Capability concentration sits with pure-play cloud specialists; scale advantage sits with infrastructure conglomerates with installed base leverage. The market exhibits tiered consolidation, with three to four platforms capturing majority new bookings while a long tail of regional and vertical specialists defends niche positions. Strategic archetypes include hybrid architecture incumbents, born-in-cloud challengers, and hyperscaler-backed entrants. Dominant competitive moves encompass workforce optimization module integration and geographic compliance certification acceleration.
Within the hybrid architecture tier, Genesys Telecommunications Laboratories, Inc. exemplifies the incumbent migration specialist position, while Cisco Systems, Inc. represents the network-integrated systems vendor archetype. Five9, Inc. anchors the pure-play cloud-native segment for mid-market buyers seeking rapid deployment without legacy baggage. These three occupy positions that illustrate the market's fundamental segmentation between infrastructure depth and deployment agility.
| Leading Market Players |
|---|
| Genesys Telecommunications Laboratories, Inc. |
| Cisco Systems, Inc. |
| Avaya Holdings Corp. |
| Five9, Inc. |
| Talkdesk, Inc. |
| NICE |
| Twilio |
| Amazon Web Services, Inc. |
| Oracle |
| Others |
Supply & Pricing Matrix
Hyperscaler concentration risk in cloud infrastructure determines both the tiered subscription spreads between enterprise and mid-market buyers and the geographic shape of vendor supply chains. Three hyperscalers control underlying compute layers, forcing platform vendors to absorb margin compression or pass through infrastructure cost volatility.
Pricing Analysis
Recurring cloud subscription revenue drives lifetime value, displacing perpetual license models across the vendor base. Pricing stratifies across enterprise, mid-market, and entry-level tiers based on agent seat volume and AI feature depth. Cost compression in the mid-market tier is intensifying because pure-play cloud vendors compete aggressively on consumption-based billing. Healthcare and BFSI buyers demonstrate lowest price sensitivity due to compliance premium absorption, while Indian domestic enterprises exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from enterprise buyers strain vendor working capital, accelerating supply-chain finance facility adoption among platform providers. Cloud infrastructure draws from United States, Ireland, and Singapore data center clusters. Specialized AI accelerators, voice termination services, and workforce optimization modules constitute critical input dependencies. Single-source vulnerability sits with hyperscaler compute allocation. Distribution runs through direct enterprise sales teams, systems integrators, and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around integrated suite procurement, with mid-market contact centers abandoning best-of-breed point solutions for consolidated vendor relationships.
For Market Incumbents: Build switching-cost moats through native workforce engagement management fusion. Deepen ISO 27001 certification investment ahead of procurement table-stakes elevation. Defend against born-in-cloud challengers by accelerating hybrid architecture migration tooling. Anchor position through pre-built EU AI Act compliance modules that compress European sales cycles. For New Entrants and Emerging Players: Establish a beachhead in India's tier-two city digital-first infrastructure deployments. Target vernacular language AI gaps that incumbent NLP engines leave unresolved. Penetrate TRAI-compliant telemarketer registration system demand that domestic enterprises require. Pursue land-and-expand motion through API-first integration with existing CRM investments. For Investors and Strategic Acquirers: Regional compliance specialists with pre-certified EU AI Act modules present asymmetric upside capture. Long-term viability hinges on recurring revenue mix and gross retention metrics rather than legacy license conversion. Monitor hyperscaler partnership tier elevation as inflection signal for distribution leverage expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Workforce Optimization Module Integration | Captures expanded operations budgets from retention-focused contact center leaders. |
| EU AI Act Compliance Certification | Accelerates procurement approvals among German and French financial services buyers. |
| Vernacular Language AI Development | Unlocks penetration in India's tier-two banking and telecom expansion markets. |
| Hyperscaler Marketplace Distribution | Reduces customer acquisition friction through AWS and Azure co-sell programs. |
| Hybrid Architecture Bridge Tooling | Preserves incumbent relevance during enterprise phased cloud migration timelines. |
Research Methodology
A spread of perspectives from contact center operations directors, CIOs at BFSI institutions, cloud procurement officers, systems integrators, and TRAI compliance consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and Indian telecom authority circulars. Bottom-up seat deployment estimates triangulated against top-down vendor revenue attribution.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions spanned deployment architecture, vertical regulatory exposure, solution module integration depth, and regional compliance maturity. CAGRs derived from fitted growth curves applied to disclosed seat expansion and pricing trajectory indicators. Voice minute cost volatility and AI feature adoption curves served as key forecast inputs.
Sensitivities concentrate around hyperscaler pricing actions, EU AI Act enforcement timing, and India TRAI regulation expansion. Forecasts reflect documented assumptions on cloud migration velocity and compliance-driven replacement cycles. Macroeconomic contraction, accelerated regulatory tightening, or generative AI disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Global Passenger Information System Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Dispatch Console Market
Communication Services
Video Managed Services Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Audio Conferencing Services Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Meeting Solutions Market
Communication Services
Mobile Messaging Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Consumer Communication Services Market
Communication Services
Global Communications Interface Market
Communication Services
Green Communication Market
Communication Services
Web Conferencing Market
Communication Services
Cloud Communication Platform Market