
 Global Custom Procedure Trays and Packs Market | 2026-2036
Global Custom Procedure Trays and Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Custom Procedure Trays and Packs Market Intelligence
Market Context
ISO 13485 certification is unwinding the competitive landscape as smaller regional assemblers lose hospital purchasing contracts. Stryker Corporation leverages its endoscopy and surgical instrument portfolio to bundle custom trays with capital equipment placements. Cardinal Health, Inc. sustains dominant hospital distribution reach through its captive logistics network spanning acute-care IDNs.
Technical Definition and Segments
Custom procedure trays and packs denote pre-assembled, procedure-specific collections of medical devices, drapes, instruments, and consumables sterilized via gamma irradiation or ethylene oxide and sealed in barrier packaging for immediate clinical use. The configuration eliminates intraoperative nursing assembly time and reduces foreign-body retention risk. Sterile trays and single-use kits anchor current revenue given their penetration in orthopedic and cardiovascular service lines, while biodegradable polymers represent the fastest-expanding material category as EU REACH restrictions on single-use plastics intensify. Multi-compartment packs command premium positioning in ambulatory surgery centers where space constraints favor compact, procedure-dedicated inventory.
Regulatory Framework
The FDA enforces 21 CFR Part 820 quality system regulations for tray assemblers, while the EU MDR requires notified-body oversight of sterile barrier validation and unique device identification. Health Canada and TGA align with ISO 11607 standards for sterile packaging integrity, creating harmonized but capital-intensive compliance thresholds. Stakeholders must monitor how FDA draft guidance on pre-market notification for kit modifications reshapes product lifecycle management and R&D allocation.
Market Dynamics
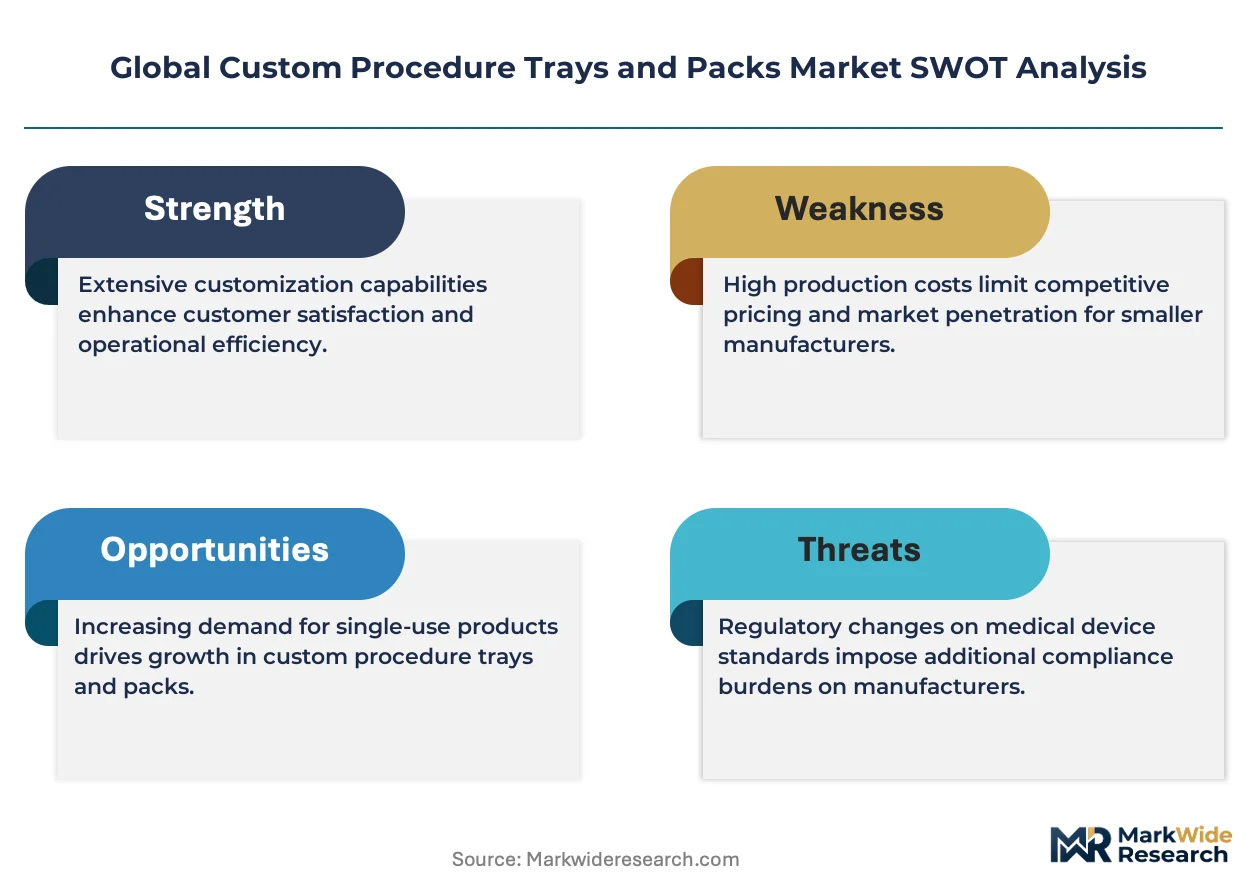
EU MDR sterilization validation requirements are compressing the supplier base as ISO 13485 certification becomes a mandatory threshold for hospital contracts, eliminating smaller regional assemblers unable to fund quality system upgrades.
Growth Catalysts
- EU MDR compliance mandates:Tightened sterile barrier validation rules under the Medical Device Regulation are forcing hospital systems to consolidate purchasing around certified manufacturers, accelerating tray standardization across German and French acute-care networks.
- Orthopedic bundled payments:Medicare's Comprehensive Care for Joint Replacement model in the United States incentivizes supply cost control, driving academic medical centers toward pre-configured kits that reduce operating room turnover time.
- Gamma irradiation infrastructure:Expanded contract sterilization capacity in India and Mexico is enabling regional tray assembly near manufacturing clusters, shortening lead times for North American distributors.
Market Restraints
- Ethylene oxide supply concentration:Sterilization gas production concentrates among three North American chemical suppliers, creating vulnerability to EPA emission regulation changes that could constrain tray throughput.
- Biodegradable polymer cost premiums:Polylactic acid and polyhydroxyalkanoate alternatives to polypropylene carry raw material cost multiples that compress margins for standard kit configurations.
- Notified body capacity bottlenecks:EU MDR implementation has overwhelmed TÜV SÜD and BSI certification queues, extending sterile barrier validation timelines to fourteen months for new tray configurations.
Strategic Opportunities
- Ambulatory surgery center expansion:United States outpatient procedural volume is shifting toward multi-compartment packs optimized for space-constrained facilities, creating premium positioning for compact, procedure-dedicated inventory systems.
- Indian hospital privatization:Corporate hospital chains in Maharashtra and Karnataka are adopting Western supply chain models, opening direct procurement channels bypassing traditional distributor markups.
- RFID-enabled traceability:Convergence of sterile barrier packaging with NFC tagging technology enables real-time expiration monitoring, differentiating tray offerings for Japan's METI-mandated device tracking requirements.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification body personnel shortages are extending quality system implementation timelines for mid-size assemblers seeking hospital vendor qualification.
- Legacy ERP integration:Tray configurators face technical friction connecting cloud-based order platforms with hospital materials management information systems running on-premise architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Custom Procedure Trays and Packs Market |
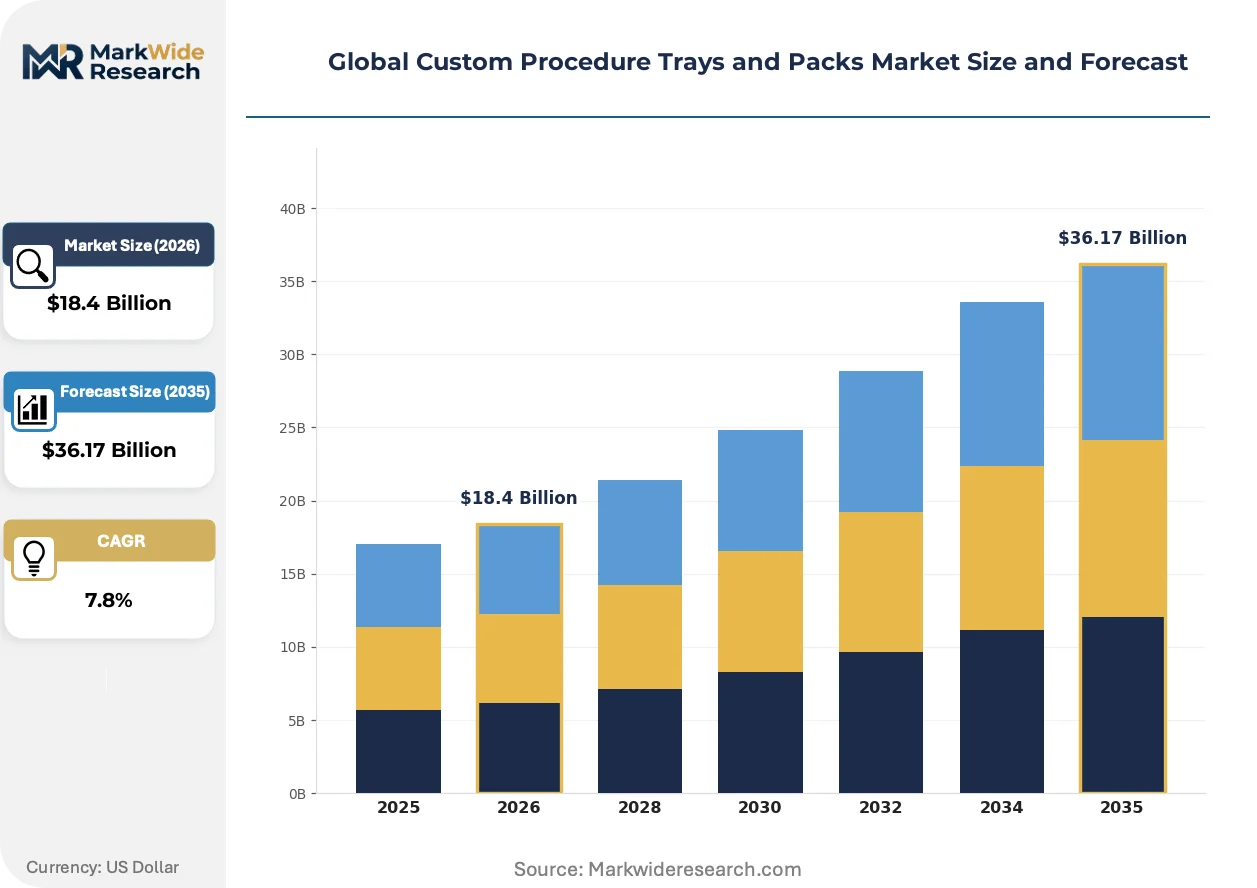
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $36.17 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Trays, Non-Sterile Trays, Multi-Compartment Packs, Single-Use Kits, Modular Trays Material: Plastic, Paperboard, Thermoformed Foam, Aluminum, Biodegradable Polymers Application: Surgical Procedures, Diagnostic Tests, Dental Treatments, Veterinary Care, Emergency Care End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Dental Clinics, Veterinary Clinics |
| Companies Covered | B. Braun Melsungen AG, Stryker Corporation, Cardinal Health, Inc., Becton, Dickinson and Company, Getinge AB, Medline Industries, L.P., STERIS plc, 3M, Owens & Minor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Custom Procedure Trays and Packs Market Strategic Shifts & Innovations
Automation in sterile barrier sealing and AI-driven demand forecasting are compressing kit configuration cycles while regulatory pressure on single-use plastics accelerates material substitution programs across European manufacturing footprints.
Biodegradable polymer films derived from corn starch and sugarcane bagasse are displacing conventional polypropylene drapes in EU-bound orthopedic trays as ECHA REACH restrictions on microplastics intensify. German hospital procurement coalitions are mandating sustainable material content minimums in tender specifications. This displacement is compressing margins for legacy petrochemical-based barrier suppliers unable to retool extrusion lines.
FDA draft guidance on pre-market notification for kit modifications is reshaping product lifecycle management, requiring assemblers to file 510(k) supplements for component substitutions previously handled through internal change control. Orthopedic tray manufacturers with high component volatility face administrative burden increases. The agency's sterilization master file pilot program offers a compliance pathway for contract manufacturers serving multiple brand owners.
Hospital materials managers are consolidating vendor panels around full-line distributors capable of integrating custom tray procurement with capital equipment and pharmaceutical supply contracts. This concentration is displacing standalone tray specialists dependent on group purchasing organization access fees. The shift is most visible in United States academic medical centers where value analysis committees now evaluate total cost of ownership across supply categories rather than line-item pricing.
Global Custom Procedure Trays and Packs Market Segmentation
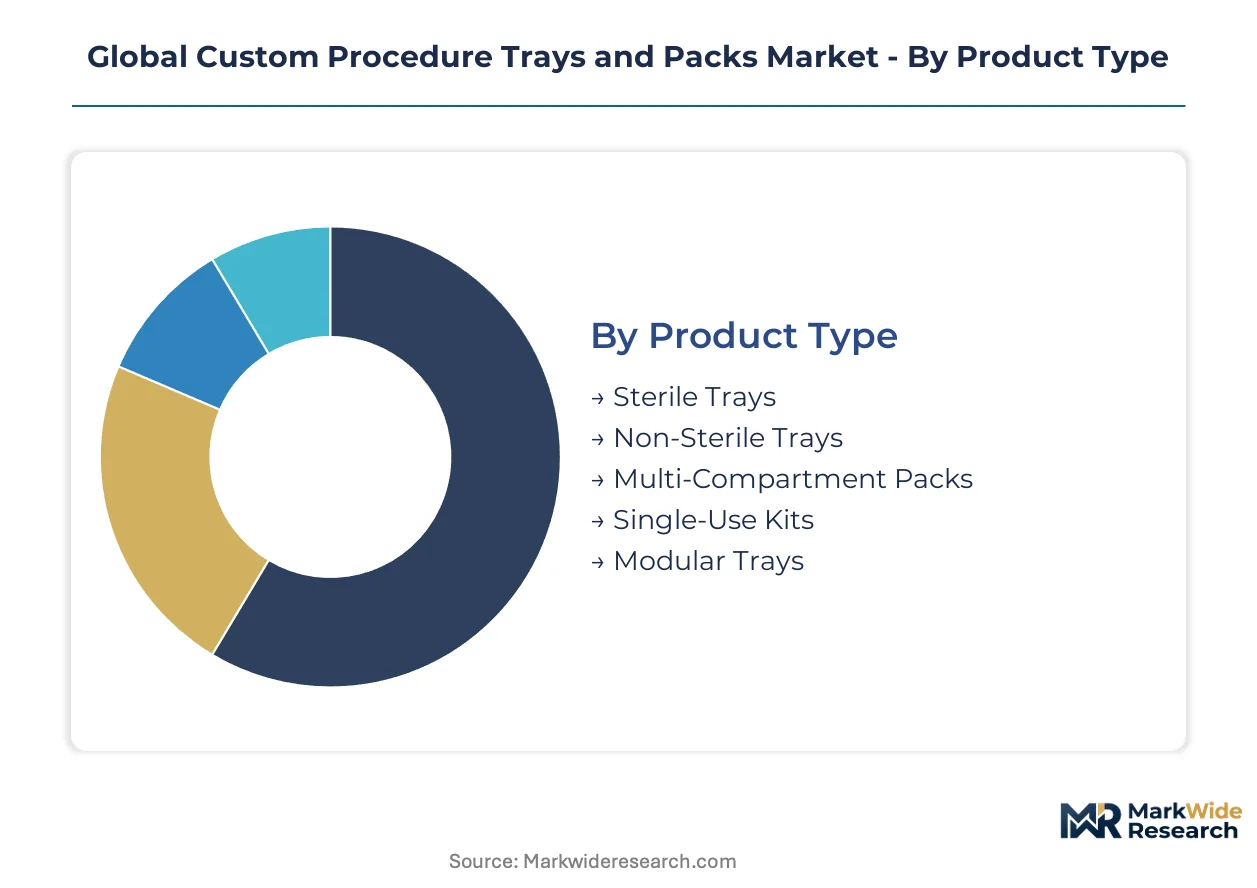
Procedure tray segmentation determines sterilization validation pathways, supply chain configuration, and hospital vendor qualification thresholds. Material and application dimensions increasingly dictate regional manufacturing footprints as EU REACH and FDA quality system regulations diverge.
Product Type:
Domestic production dominates sterile and non-sterile tray categories in Germany and the United States, while multi-compartment packs and modular configurations show stronger export orientation toward emerging hospital markets.
- Sterile Trays:Pre-validated gamma or ethylene oxide sterilized assemblies sealed in ISO 11607-compliant barrier packaging. German acute-care networks and United States academic medical centers concentrate procurement around these configurations to minimize operating room turnover time and foreign-body retention risk.
- Multi-Compartment Packs:Space-optimized configurations integrating drapes, instruments, and consumables in segmented layouts. Ambulatory surgery centers in the United States and corporate hospital chains in Maharashtra favor these for inventory density in constrained storage environments.
- Non-Sterile Trays:Component collections requiring terminal sterilization at hospital central processing departments.
- Single-Use Kits:Procedure-dedicated disposable assemblies eliminating reprocessing overhead.
- Modular Trays:Reconfigurable base platforms accommodating component substitution without full redesign.
Sterile trays command the established base. The steepest expansion runs through multi-compartment packs.
Material:
Cost tier stratification separates commodity petrochemical substrates from certified biodegradable alternatives carrying raw material multiples that compress assembler margins.
- Biodegradable Polymers:Polylactic acid and polyhydroxyalkanoate films derived from corn starch or sugarcane bagasse. EU REACH microplastic restrictions and German hospital procurement coalition mandates are accelerating displacement of conventional polypropylene in orthopedic tray drapes.
- Plastic:Polypropylene and polyethylene dominate standard kit configurations through extrusion-formed barrier layers and injection-molded instrument organizers.
- Thermoformed Foam:Instrument retention layers with die-cut cavities matching specific surgical tool geometries.
- Paperboard:Cost-minimized outer cartons and procedure documentation sleeves.
- Aluminum:Foil barrier layers in moisture-sensitive diagnostic test kits.
Plastic substrates retain volume leadership. Biodegradable polymers are climbing the fastest as regulatory pressure intensifies.
Application:
Customer type concentration varies sharply: surgical and diagnostic applications flow through hospital materials management, while dental and veterinary channels operate through specialized distributor networks with distinct sterilization validation requirements.
- Surgical Procedures:Orthopedic and cardiovascular service lines drive tray standardization under United States Medicare bundled payment models. Pre-configured kits reduce nursing assembly time and support operating room throughput targets in German university hospitals.
- Diagnostic Tests:Sterile barrier packaging for specimen collection and processing consumables. Clinical laboratory networks in the United States consolidate procurement around FDA 510(k)-cleared configurations to minimize quality system audit burden.
- Dental Treatments:Implant and endodontic procedure kits with specialized instrument complements.
- Veterinary Care:Species-specific surgical and examination configurations.
- Emergency Care:Rapid-deployment trauma and resuscitation packs.
Surgical applications anchor revenue concentration. Diagnostic tests are expanding most quickly as laboratory automation drives standardization.
End User:
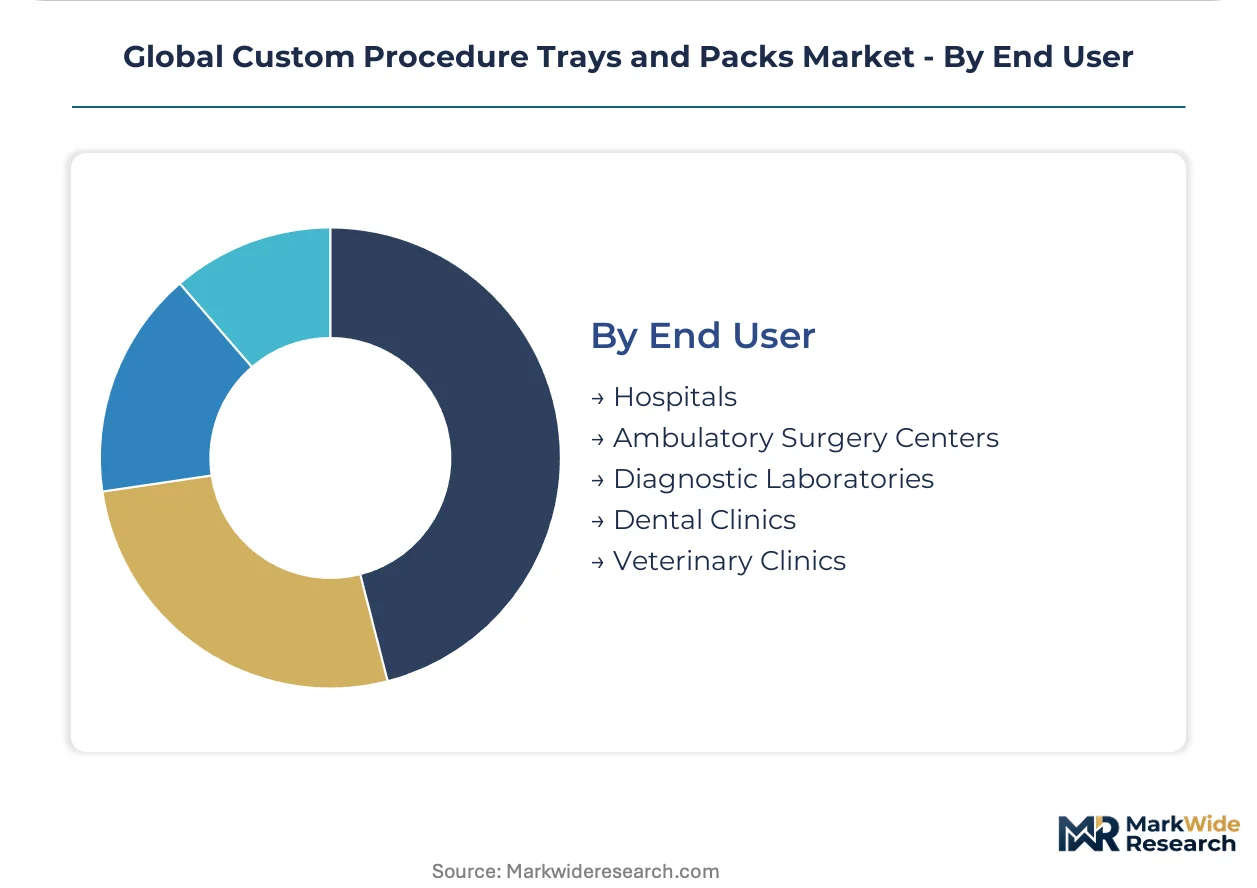
Volume scale separates high-throughput hospital systems from fragmented clinic networks, with ambulatory surgery centers representing the fastest-growing customer class for compact, procedure-dedicated inventory systems.
- Hospitals:Integrated delivery networks in the United States and German hospital procurement coalitions drive vendor consolidation around ISO 13485-certified assemblers capable of integrating tray supply with capital equipment and pharmaceutical contracts.
- Ambulatory Surgery Centers:Space-constrained facilities in the United States favor multi-compartment packs and modular configurations. Premium positioning accrues to suppliers offering compact footprints and real-time inventory monitoring.
- Diagnostic Laboratories:High-volume specimen processing operations with standardized consumable requirements.
- Dental Clinics:Decentralized procurement through dental-specific distributor channels.
- Veterinary Clinics:Mixed small-animal and equine practice configurations with lower sterilization validation stringency.
Hospitals retain the dominant share. Ambulatory surgery centers are gaining share fastest as procedural volume shifts outpatient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers in the United States and Germany dominate purchasing volume for pre-configured sterile trays, while emerging demand clusters in India and Brazil reshape supplier manufacturing footprints.
United States
Medicare's Comprehensive Care for Joint Replacement bundled payment model drives academic medical centers toward supply standardization. FDA 21 CFR Part 820 quality system regulations enforce sterilization validation protocols. Cleveland Clinic and Mayo Clinic procurement coalitions consolidate vendor panels around distributors integrating tray supply with capital equipment contracts.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia expand adoption of gamma-sterilized trays to reduce operating room turnover time. EU MDR sterile barrier validation requirements compress the supplier base toward ISO 13485-certified assemblers. Tübingen and Leipzig manufacturing clusters host contract sterilization facilities serving Central European tray producers.
India
Corporate hospital chains in Maharashtra and Karnataka adopt Western supply chain models, opening direct procurement channels. CDSCO medical device rules align with ISO 11607 standards for sterile packaging integrity. Mumbai and Bengaluru medical device parks attract tray assembly operations seeking proximity to private hospital networks.
Japan
METI-mandated device tracking requirements accelerate RFID-enabled traceability integration in sterile barrier packaging. PMDA quality system regulations govern kit modification notification pathways. Osaka and Nagoya industrial corridors concentrate gamma irradiation infrastructure serving domestic tray manufacturers.
Brazil
ANVISA medical device regulations harmonize with ISO 13485 certification requirements for imported tray assemblies. São Paulo and Minas Gerais hospital privatization drives demand for pre-configured surgical kits. Campinas medical device cluster hosts regional distribution hubs for multinational tray suppliers.
Global Custom Procedure Trays and Packs Market Key Industry Players
Player mix skews toward diversified medical device conglomerates with captive distribution networks and specialized sterilization service providers. Consolidation pressure intensifies as hospital procurement committees favor full-line suppliers capable of bundling tray contracts with pharmaceutical and capital equipment agreements. Two strategic archetypes dominate: integrated device-distributor hybrids leveraging end-to-end supply chain control, and pure-play sterilization specialists monetizing regulatory compliance expertise. Competitive moves center on M&A-driven portfolio expansion and ISO 13485 certification capacity building to qualify for hospital vendor panels.
Among Germany-based medical technology conglomerates, B. Braun Melsungen AG exemplifies the integrated manufacturer archetype with vertically structured hospital supply operations. Stryker Corporation and Cardinal Health, Inc. occupy positions within the North American diversified distributor tier, representing contrasting models of device manufacturing integration versus logistics-centric procurement consolidation. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across distinct regulatory environments.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Stryker Corporation |
| Cardinal Health, Inc. |
| Becton, Dickinson and Company |
| Getinge AB |
| Medline Industries, L.P. |
| STERIS plc |
| 3M |
| Owens & Minor, Inc. |
| Others |
Cost & Logistics Intelligence
Biodegradable polymer substitution for conventional polypropylene drapes is simultaneously shifting manufacturing geography toward EU-bound production clusters and compressing margin structures for assemblers unable to absorb raw material cost multiples. Hospital procurement coalitions in Germany now mandate sustainable content minimums, forcing price recalibration across orthopedic tray configurations.
Pricing Analysis
Cost-plus contracts indexed to polylactic acid and polyhydroxyalkanoate commodity benchmarks dominate German and United States hospital purchasing agreements. Three-tier pricing structure across premium ISO 13485-certified, standard validated, and economy non-sterile configurations separates vendor tiers. Cost compression in biodegradable polymer tiers is intensifying because EU REACH microplastic restrictions constrain petrochemical alternatives. Ambulatory surgery centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize total cost of ownership over line-item pricing.
Supply Chain Analysis
Inventory cycles stretching fourteen months for EU MDR sterile barrier validation are tethering production planning to notified body queue management. Gamma irradiation infrastructure concentrates in Germany, the United States, and India, while ethylene oxide sterilization gas production draws from three North American chemical suppliers. Single-source vulnerability in sterilization gas supply creates exposure to EPA emission regulation changes. Distribution runs through integrated delivery networks and group purchasing organizations serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital buyer power is concentrating around value analysis committees that consolidate vendor panels, eliminating standalone tray specialists dependent on GPO access fees.
For Market Incumbents: Secure ISO 13485 certification capacity ahead of notified body queue bottlenecks to defend hospital vendor qualification status against emerging contract sterilization specialists. Deepen backward integration into gamma irradiation infrastructure in India and Mexico to shorten lead times for North American distributors. Channel control through captive logistics networks anchors pricing power against distributor disintermediation threats. For New Entrants and Emerging Players: RFID-enabled traceability integration represents a service-layer gap where incumbents under-serve Japan's METI-mandated device tracking requirements. Target corporate hospital chains in Maharashtra and Karnataka through direct procurement channels bypassing traditional distributor markups. White-space penetration runs fastest through compact multi-compartment packs optimized for United States ambulatory surgery center space constraints. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors contract sterilization specialists with EU MDR validation expertise and established notified body relationships. Long-term viability hinges on consolidation plays capturing ISO 13485-certified assembly capacity. The signal to watch is FDA draft guidance finalization on kit modification notification pathways, which would reshape administrative burden economics for component-volatile orthopedic tray manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Capacity Buildout | Qualifies assemblers for hospital vendor panels under EU MDR and FDA quality system mandates. |
| Biodegradable Polymer Material Transition | Aligns tray configurations with ECHA REACH restrictions and German procurement coalition sustainability minimums. |
| RFID-Enabled Traceability Integration | Addresses Japan METI device tracking requirements and differentiates offerings for real-time expiration monitoring. |
| Gamma Irradiation Infrastructure Expansion | Shortens lead times for North American distributors sourcing from India and Mexico manufacturing clusters. |
| Direct Procurement Channel Development | Bypasses distributor markups in India's privatizing corporate hospital chains in Maharashtra and Karnataka. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and sterile processing department directors; and secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, CMS Medicare bundled payment program documentation, and hospital procurement contract repositories. Bottom-up tray configuration demand modeling and top-down healthcare supply chain expenditure triangulation anchored volume estimates.
Across the analysis window, forecasts applied procedure volume projections by surgical service line, sterilization validation pathway segmentation, and material substitution elasticity parameters. CAGRs derived from weighted average of historical tray adoption curves and regulatory implementation timelines. Modeled dimensions span product type, material category, application specialty, and end-user facility scale. Industry-specific inputs incorporated orthopedic bundled payment penetration rates and ambulatory surgery center procedural volume shifts.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 and EU MDR implementation; material policy shifts in EPA ethylene oxide emission standards or ECHA REACH microplastic restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Ophthalmic Packaging Market