
 North America Parenteral Packaging Market | 2026-2036
North America Parenteral Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Parenteral Packaging Market Analytics
Multi-source procurement for elastomeric closures is rebalancing toward dual-qualified supply arrangements as drug sponsors reduce single-source risk. West Pharmaceutical Services anchors North American capacity through captive rubber formulation and finishing operations. Gerresheimer AG competes via specialized borosilicate glass converting for high-value injectables. Schott AG differentiates through controlled siliconization technology that minimizes protein aggregation in biologic drug products.
North America parenteral packaging comprises sterile container systems designed to maintain drug product integrity from manufacture through administration, typically involving materials resistant to thermal shock, chemical leaching, and gas permeation within specified pharmacopeial limits. These systems serve primarily to protect sensitive injectable formulations from contamination, oxidation, and mechanical failure during filling, storage, transport, and clinical use. Glass vials retain the largest share of biologics applications due to chemical inertness requirements, while prefillable syringes capture the fastest expansion as self-administration protocols expand in chronic disease management. Plastic and rubber materials command differentiated margin pools based on extractables testing burden and specialized barrier coatings.
FDA container closure integrity guidance, USP Chapter 1207 on package integrity evaluation, and Health Canada ICH Q1A stability requirements collectively shape validation protocols and material qualification timelines across North American manufacturing. The EPA's evolving standards for pharmaceutical manufacturing emissions further influence material selection and coating chemistry decisions. Stakeholders must monitor how regulatory convergence on visible particulate limits and subvisible particle detection thresholds will reshape equipment investment and supplier qualification criteria.
Market Dynamics
Biologics manufacturers are consolidating procurement around ready-to-use container systems, forcing converters to absorb validation costs while FDA container closure integrity standards harden. This structural pressure is compressing supplier margins and accelerating dual-qualification requirements across the Northeast pharmaceutical corridor.
Growth Catalysts
- Self-administration protocols:Chronic disease management protocols are expanding prefillable syringe demand as patients shift from clinical to home settings. Rheumatology and endocrinology therapeutic areas drive volume concentration.
- USP Chapter 1207:Package integrity evaluation standards are mandating probabilistic detection methods over deterministic alternatives. This is upgrading equipment investment across sterile converting operations.
- Borosilicate glass resilience:Thermal shock resistance and chemical inertness requirements in high-value injectables sustain vial dominance despite polymer competition. Oncology and monoclonal antibody applications anchor this material preference.
Market Restraints
- Specialized rubber formulation concentration:Captive elastomeric closure supply concentrates among integrated manufacturers, limiting second-source options for drug sponsors. Single-source risk persists for high-barrier formulations.
- Extractables testing burden:USP Chapter 1661 on plastic packaging systems is extending qualification timelines and analytical costs. Small-volume parenteral sponsors face disproportionate compliance overhead.
- Silicone oil alternatives:Protein aggregation concerns in biologics are driving evaluation of fluoropolymer and ceramic-coated surfaces. Glass barrel siliconization faces substitution pressure in sensitive formulations.
Strategic Opportunities
- Cell and gene therapy cold chain:Cryogenic storage requirements for mRNA and viral vector products are creating demand for specialized polymer containers. Massachusetts and New Jersey biotech clusters are piloting qualification programs.
- Health Canada alignment with ICH Q1A:Stability testing harmonization is reducing redundant validation for cross-border sponsors. This regulatory convergence lowers barrier costs for US-Canada integrated supply chains.
- Modular filling line integration:Ready-to-use nested container formats are converging with isolator technology to reduce cleanroom footprint. Contract manufacturing organizations in Puerto Rico are adopting this configuration.
Industry Challenges
- Container closure integrity validation:Probabilistic method implementation requires specialized microbiology and engineering skill sets that compete with broader pharmaceutical quality functions. Talent scarcity extends project timelines.
- Legacy glass converting asset retrofit:Controlled siliconization and barrier coating upgrades demand capital deployment against depreciated equipment bases. Mid-cap converters face compressed returns on modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Parenteral Packaging Market |
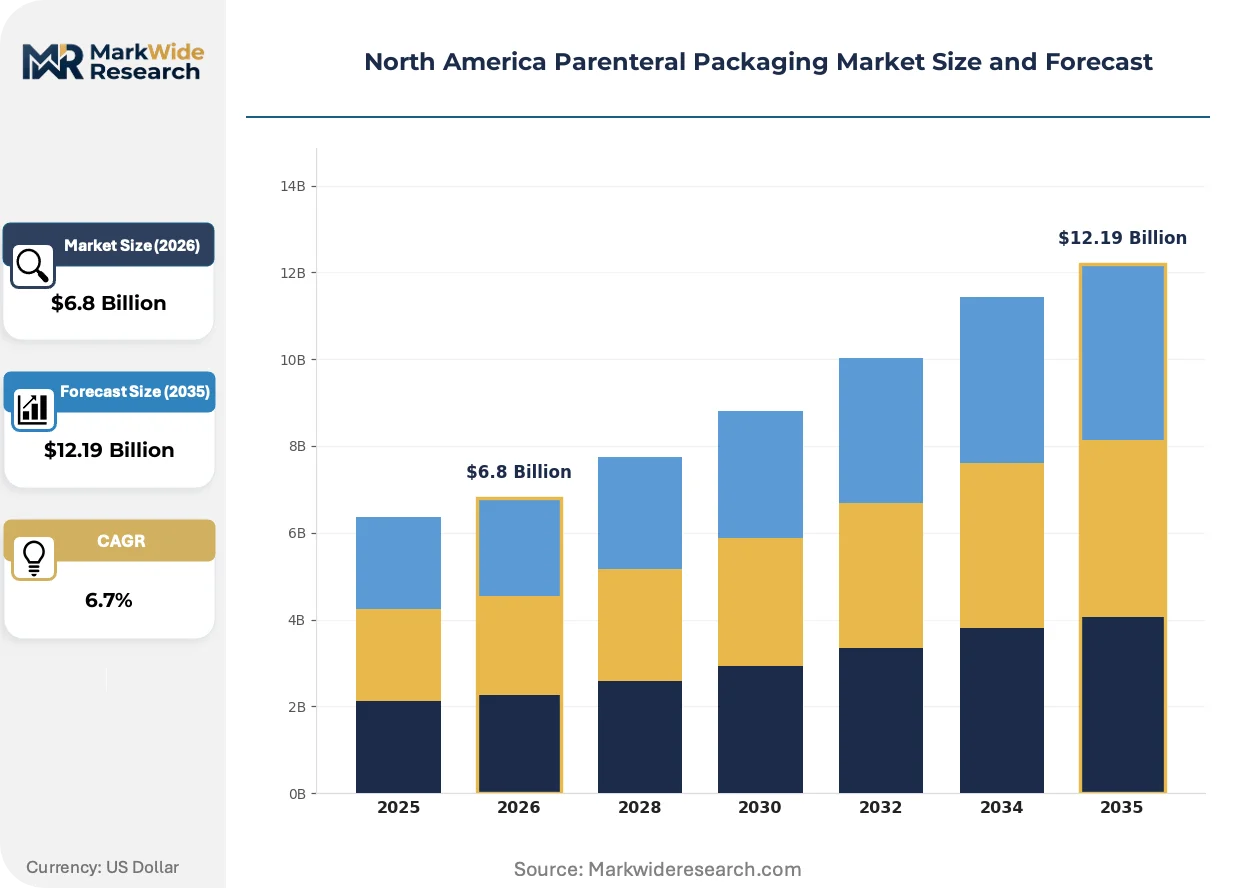
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Ampoules, Vials, Syringes, Cartridges Material: Glass, Plastic, Rubber, Aluminum Application: Injectable Drugs, Vaccines, Biologics, Infusion Therapies End User: Hospitals, Clinics, Pharmaceutical Companies, Contract Manufacturers |
| Companies Covered | West Pharmaceutical Services, Gerresheimer AG, Schott AG, Amcor PLC, AptarGroup, SGD Pharma, Becton Dickinson and Company, Berry Global, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Parenteral Packaging Market Evolving Landscape
Digital traceability and advanced barrier coatings are converging to redefine sterile packaging performance standards. These developments are compressing traditional qualification cycles while elevating functional requirements for container-drug product interaction.
Platinum-cured silicone components are integrating with high-precision molding to reduce particulate generation in elastomeric closures. Biologics fill-finish operations are adopting these materials at accelerated rates to meet visible particulate limits. This integration is enabling shorter supplier qualification timelines while compressing cost structures for standard-grade alternatives.
FDA guidance on container closure integrity is mandating shift from dye ingress to deterministic methods such as vacuum decay and high-voltage leak detection. Sterile packaging converters are revalidating legacy product lines under compressed schedules. High-value biologics applications in the Northeast corridor are experiencing the most intensive retooling activity.
Drug sponsors are consolidating vendor relationships around integrated container-closure-delvery system suppliers. Single-source risk mitigation is displacing fragmented procurement across multiple component specialists. This concentration is most visible among mid-cap biotech sponsors in Massachusetts and New Jersey seeking streamlined technical support.
North America Parenteral Packaging Market Segmentation
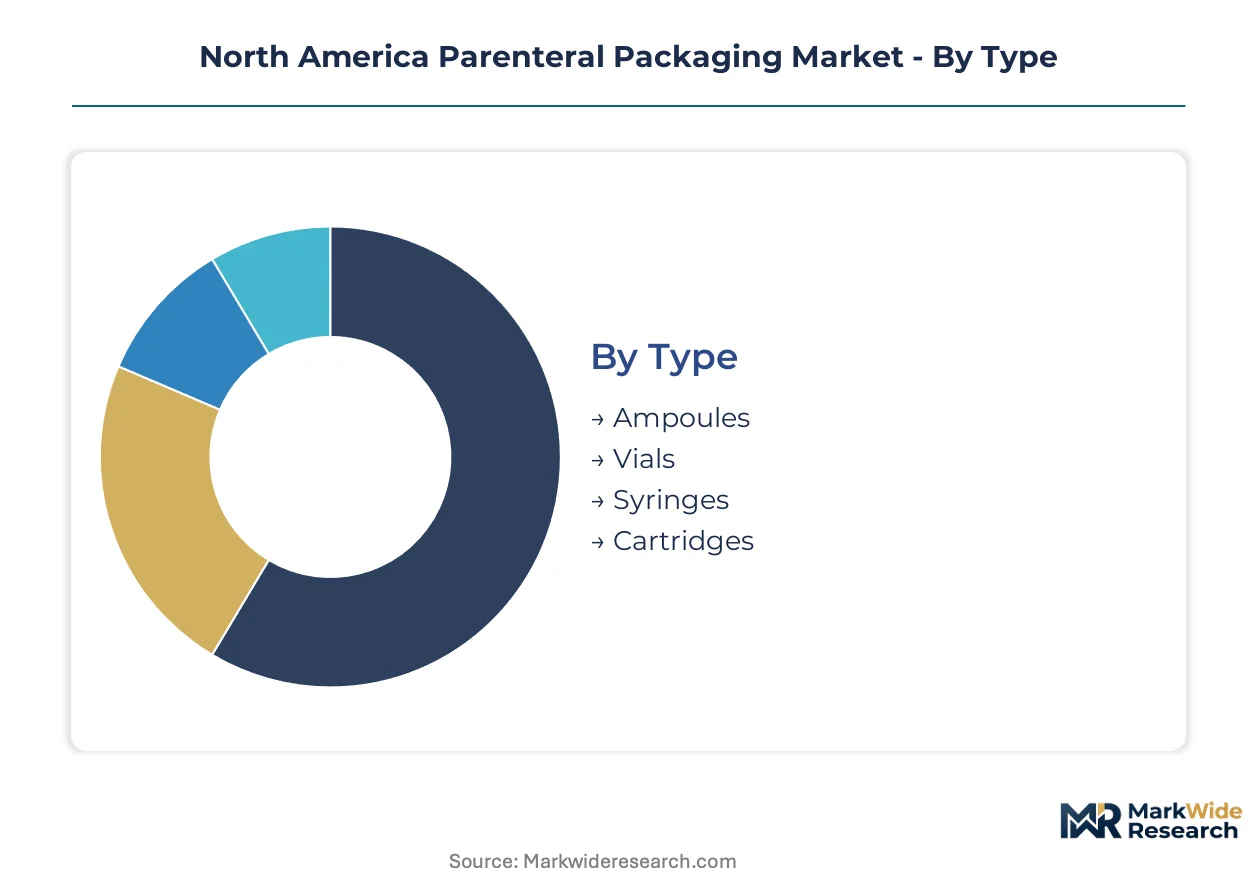
Segmentation in parenteral packaging reveals how material science, regulatory burden, and end-use concentration create distinct margin pools. Understanding these divides enables targeted investment in validation capabilities and geographic capacity alignment.
Type:
Container format selection separates chronic disease sponsors seeking patient convenience from oncology and biologics manufacturers prioritizing chemical inertness.
- Vials:Borosilicate glass construction delivers thermal shock resistance and chemical stability required for monoclonal antibodies and cytotoxic formulations. Demand concentrates in Massachusetts and New Jersey biotech corridors where high-value injectables anchor fill-finish operations. FDA container closure integrity standards sustain premium pricing despite polymer competition.
- Syringes:Prefillable formats integrate staked needles and Luer lock configurations for rheumatology and endocrinology self-administration. Massachusetts chronic disease sponsors are consolidating procurement around ready-to-use nested formats to reduce cleanroom footprint.
- Ampoules:Single-dose glass containers serve emergency medicine and anesthesiology applications requiring immediate access without reconstitution steps.
- Cartridges:Pen injector compatibility drives diabetes and growth hormone therapeutic demand, with specialized plunger and seal configurations.
Volume sits with vials; growth tilts toward syringes.
Material:
Material choice directly determines extractables testing burden, supplier qualification timeline, and barrier coating investment requirements.
- Glass:Type I borosilicate dominates biologics applications through chemical inertness and USP <660> compliance. Controlled siliconization technology from specialized converters minimizes protein aggregation in sensitive formulations.
- Plastic:Cyclic olefin polymer and copolymer formats are gaining traction in cell and gene therapy cold chain applications. Cryogenic storage requirements for mRNA products in New Jersey and Massachusetts clusters are piloting polymer container qualification programs.
- Rubber:Bromobutyl and chlorobutyl elastomeric closures command differentiated margins based on platinum-cured formulation and particulate control. West Pharmaceutical Services anchors North American capacity through captive rubber operations.
- Aluminum:Flip-off seals and overseals provide tamper evidence and mechanical protection across vial and ampoule formats.
Glass captures the dominant revenue share; plastic climbs the fastest on cell therapy demand.
Application:
Therapeutic category determines barrier performance requirements, cold chain infrastructure, and delivery system integration complexity.
- Biologics:Monoclonal antibodies, fusion proteins, and recombinant hormones demand highest barrier integrity and protein stability assurance. Massachusetts and New Jersey sponsors drive specification intensity through concentrated fill-finish investment.
- Injectable Drugs:Small-molecule parenterals span generic antibiotics to complex liposomal formulations, with USP Chapter 1661 extending plastic packaging qualification timelines.
- Vaccines:Multi-dose vial formats with preservative compatibility requirements serve public health and travel medicine segments.
- Infusion Therapies:Large-volume parenterals and parenteral nutrition require specialized port configurations and extended shelf-life validation.
Injectable drugs hold volume concentration; biologics command the steepest expansion trajectory.
End User:
Customer scale and technical capability determine procurement centralization, validation support requirements, and dual-qualification urgency.
- Pharmaceutical Companies:Integrated drug sponsors in the Northeast corridor are consolidating vendor relationships around integrated container-closure-delivery system suppliers to streamline technical support.
- Contract Manufacturers:Puerto Rico and Massachusetts CMOs are adopting modular filling line integration with ready-to-use nested container formats to reduce cleanroom footprint and accelerate batch turnaround.
- Hospitals:Health system procurement concentrates on standardized prefilled syringe formats for pharmacy efficiency and medication safety.
- Clinics:Ambulatory settings drive demand for single-unit packaging and patient-ready labeling configurations.
Pharmaceutical companies anchor procurement volume; contract manufacturers are expanding capacity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in West Virginia and Pennsylvania anchor borosilicate glass feedstock supply for northeastern pharmaceutical packaging corridors. This raw material proximity shapes converter location decisions and logistics cost structures across the region.
United States
Massachusetts and New Jersey biotech clusters drive specification intensity for monoclonal antibody vials and prefillable syringes. FDA container closure integrity guidance mandates probabilistic testing methods that extend validation timelines for converters. The Northeast pharmaceutical corridor spanning Boston to Princeton concentrates fill-finish investment and dual-qualification procurement programs.
Canada
Ontario's contract manufacturing sector expands ready-to-use nested container adoption for cross-border biologics supply chains. Health Canada alignment with ICH Q1A stability requirements reduces redundant validation for US-Canada integrated sponsors. Toronto and Montreal clusters pilot modular filling line configurations with isolator technology integration.
Mexico
Baja California medical device manufacturing zones attract sterile packaging converters serving US pharmaceutical sponsors seeking nearshore capacity. COFEPRIS regulatory convergence with FDA standards accelerates supplier qualification for export-oriented operations. Tijuana and Mexicali industrial parks concentrate plastic component molding for prefillable syringe assemblies.
North America Parenteral Packaging Market Competitive Landscape
Global majors compete with regional champions across elastomeric closure formulation and controlled siliconization technology. The vendor base stratifies between integrated rubber compounders, specialized glass converters, and diversified healthcare packaging conglomerates. Three archetypes dominate: captive rubber formulators with in-house finishing, borosilicate specialists with barrier coating capabilities, and diversified players with modular delivery system portfolios. Capacity expansion and strategic partnerships constitute the primary competitive vectors as drug sponsors consolidate vendor relationships.
Among German-based glass and packaging specialists, Gerresheimer AG and Schott AG exemplify the specialized converter archetype through their positioning in high-barrier pharmaceutical applications. West Pharmaceutical Services anchors the integrated elastomeric closure tier with captive rubber operations. These three entities occupy positions that reflect the market's segmentation between material science depth and delivery system integration.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Gerresheimer AG |
| Schott AG |
| Amcor PLC |
| AptarGroup |
| SGD Pharma |
| Becton Dickinson and Company |
| Berry Global |
| Baxter International |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap glass converters with multi-generational ownership structures dominate borosilicate supply in West Virginia and Pennsylvania, anchoring pricing discipline through captive silica sand access and limiting margin erosion despite FDA validation cost pressures.
Pricing Analysis
Warranty and validation service bundling separates premium converters from commodity competitors, with extended container closure integrity guarantees commanding 15-20% price premiums over unbundled alternatives. Three-tier pricing structure across platinum-cured, standard bromobutyl, and economy chlorobutyl closure grades reflects extractables testing burden and particulate control certification. Cost compression in standard-grade segments is intensifying because mid-cap sponsors are consolidating procurement volumes. Small-volume parenteral sponsors exhibit highest price sensitivity, while monoclonal antibody manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Regional distribution centers in New Jersey and Massachusetts operate hub-and-spoke patterns serving the Northeast pharmaceutical corridor, with secondary nodes in Puerto Rico and Ontario supporting cross-border biologics flows. Raw material supply draws from West Virginia silica sand deposits, Pennsylvania boron sources, and Texas petrochemical feedstocks for cyclic olefin polymers. Single-source vulnerability concentrates in platinum-cured elastomeric formulations where West Pharmaceutical Services anchors North American capacity. Distribution runs through validated cold chain logistics providers with specialized pharmaceutical handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around dual-qualified supply arrangements as FDA container closure integrity standards force sub-scale converters into strategic exits or acquisition.
For Market Incumbents: Lock in exclusive supply relationships with Massachusetts and New Jersey biotech sponsors before second-source qualification programs conclude. Backward integration into controlled siliconization technology defends margin position against fluoropolymer-coated barrel substitutes. Capacity addition in Puerto Rico captures contract manufacturing organization growth while Ontario facilities serve Health Canada-aligned stability requirements. For New Entrants and Emerging Players: The price-point gap between premium borosilicate vials and economy polymer alternatives creates entry space for specialized cyclic olefin containers in cell therapy cold chain applications. Massachusetts mRNA sponsors represent the most penetrable segment given cryogenic storage qualification gaps. A go-to-market angle emphasizing modular filling line integration with ready-to-use nested formats accelerates technical validation timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap glass converters with depreciated West Virginia assets and existing FDA master files in the Northeast corridor. Long-term viability hinges on barrier coating technology ownership and isolator-compatible format development. The signal to watch is Health Canada-PMRA convergence pace on ICH Q1A stability testing harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Siliconization Technology Investment | Minimizes protein aggregation in biologic formulations, differentiating high-value vial supply. |
| Ready-to-Use Nested Container Format Expansion | Reduces cleanroom footprint for Massachusetts and New Jersey fill-finish operations. |
| Dual-Qualification Supply Arrangement | Mitigates single-source risk for drug sponsors under FDA container closure integrity guidance. |
| Cyclic Olefin Polymer Cold Chain Qualification | Captures cell and gene therapy demand from mRNA and viral vector sponsors. |
| Modular Isolator Technology Integration | Accelerates batch turnaround for Puerto Rico contract manufacturing organizations. |
Research Methodology
SEC 10-K filings, FDA packaging master file databases, and USP chapter revision records formed the secondary backbone, supplemented by trade data from West Virginia and Pennsylvania silica sand districts. Primary interviews with fill-finish operations directors, regulatory affairs specialists at biologics sponsors, elastomeric compounders, and hospital pharmacy procurement managers validated secondary findings. Bottom-up triangulation across container format volumes and top-down cross-check against therapeutic category demand produced convergent estimates.
Historical trendline analysis of borosilicate glass converting capacity and prefillable syringe adoption patterns established baseline growth parameters across the analysis window. Segmentation modeling incorporated material type, container format, therapeutic application, and end-user scale dimensions. CAGRs were derived from regression-adjusted growth rates incorporating FDA guidance implementation timelines and biologics pipeline expansion. Industry-specific inputs included USP Chapter 1207 probabilistic testing adoption curves and Health Canada ICH Q1A alignment progress.
Inputs from FDA guidance documents and USP chapter drafts were available through the study window; gaps in real-time sponsor qualification data introduce uncertainty bands around converter market share estimates. Forecasts reflect documented assumptions regarding regulatory convergence pace and biologics capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market