
 Medical-Grade Foil Market | 2026-2036
Medical-Grade Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Medical-Grade Foil Market Outlook
Multi-layer coextrusion with ethylene vinyl alcohol barrier layers is tilting medical-grade foil specifications toward higher oxygen and moisture resistance. Amcor plc leverages integrated film-to-foil lamination capabilities across European and North American pharmaceutical packaging hubs. Constantia Flexibles Group GmbH anchors its position through specialized cold-form blister foils for high-potency drugs. Hindalco Industries Limited dominates primary aluminum rolling for thin-gauge medical applications from Indian manufacturing complexes.
Medical-grade foil denotes barrier sheet materials engineered to meet pharmacopeial and device biocompatibility standards, typically ranging from twenty to one hundred fifty micrometers in thickness and manufactured through tandem cold rolling or cast film extrusion with controlled surface oxidation. The material functions primarily to protect sterile pharmaceuticals, medical devices, and diagnostic components from environmental degradation, particulate contamination, and microbial ingress. Aluminum foil within product type classifications retains the largest volume position due to established compatibility with thermoforming and cold-forming processes, while composite foil structures capture expanding share as combination drug-device products require tailored heat-seal and peel properties. Laminated foil segments command premium positioning where pharmaceutical companies specify custom print layers for anti-counterfeiting and brand authentication features.
FDA cGMP regulations for pharmaceutical packaging materials, EU MDR device labeling and traceability requirements, and ISO 13485 quality management standards collectively shape material qualification timelines and supplier audit intensity for foil converters. CE marking under the MDR framework now extends to primary packaging components deemed integral to device sterility, compelling foil producers to maintain technical documentation beyond prior custom. Stakeholders must monitor evolving pharmacopeial revisions for elemental impurity limits and polymer extractables testing protocols that will determine qualification costs and supplier switching flexibility.
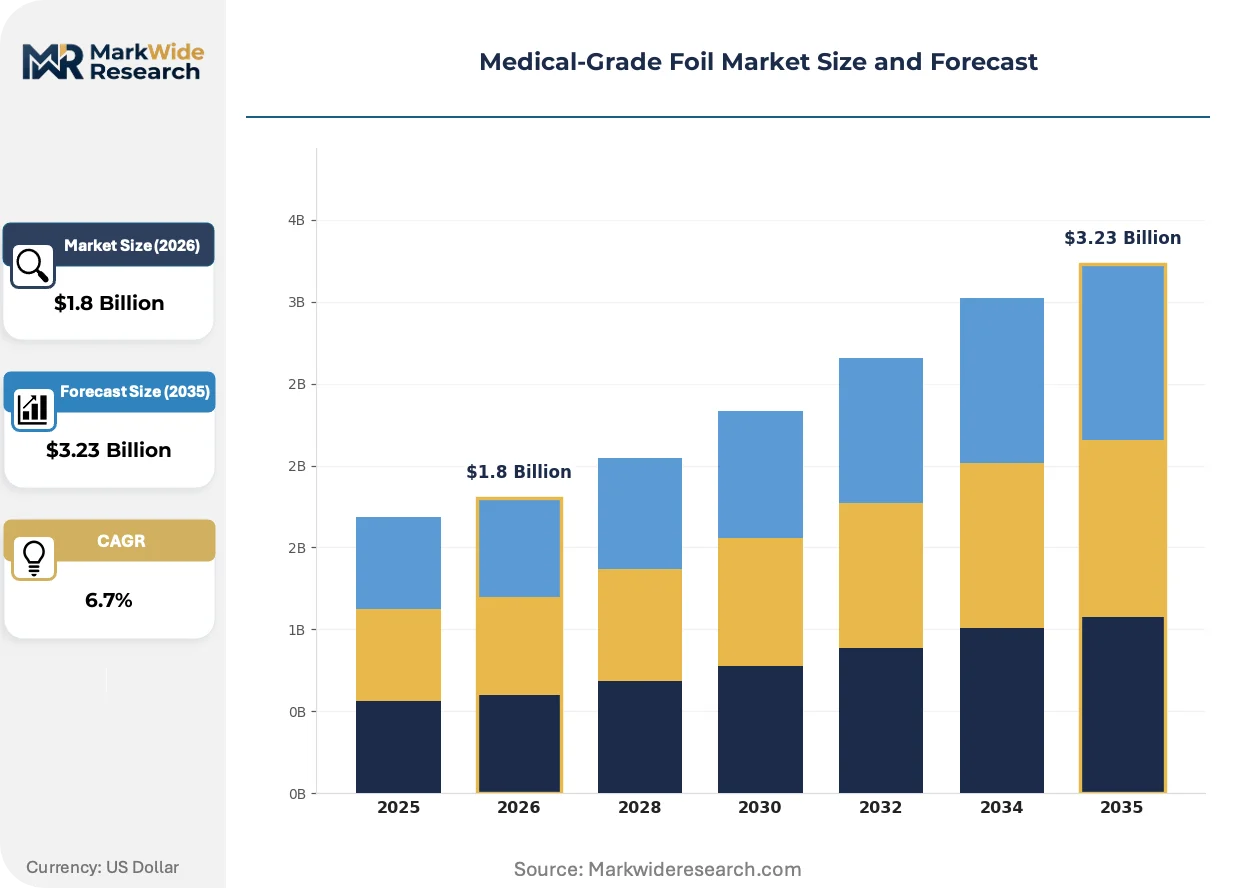
Market Dynamics
Serialization mandates under EU MDR and FDA DSCSA are compressing qualification timelines for foil converters while simultaneously expanding specification complexity for cold-form blister applications.
Growth Catalysts
- Biologics cold-chain expansion:Temperature-sensitive monoclonal antibodies and mRNA therapies require ultra-high barrier foils with thermal stability profiles that standard packaging cannot satisfy.
- EU MDR Annex I requirements:CE marking extension to primary packaging components deemed integral to device sterility forces pharmaceutical companies to upgrade foil specifications and audit supplier technical documentation.
- Cold-forming aluminum alloys:Advances in tandem cold rolling enable thinner-gauge foils with equivalent barrier performance, reducing material intensity per blister pack.
Market Restraints
- Primary aluminum ingot volatility:LME aluminum price swings directly compress converter margins on fixed-price pharmaceutical supply contracts.
- Specialty polymer supply concentration:Ethylene vinyl alcohol resin production clusters in Japan and South Korea, creating geographic single-point vulnerability for multi-layer coextrusion lines.
- ISO 13485 certification timelines:Eighteen-month supplier qualification cycles delay new converter entry and lock incumbent relationships.
Strategic Opportunities
- Indian contract packaging scale-up:CDSCO manufacturing license reforms and PLI scheme incentives attract biologics fill-finish investment, driving localized foil demand.
- Combination drug-device convergence:Prefilled syringes with integrated foil-laminated plunger seals create specification white space beyond traditional blister formats.
- Anti-counterfeiting print integration:Microtext and holographic authentication layers embedded during lamination command premium positioning against generic foil imports.
Industry Challenges
- Thin-gauge rolling technician scarcity:Tandem mill operation requires specialized metallurgy expertise concentrated among aging workforces in Germany and the United States.
- Extractables testing protocol fragmentation:USP 1664, ISO 10993, and EP 3.2.2 divergent requirements force parallel validation studies for multi-jurisdiction product launches.
- Legacy thermoforming line retrofit costs:Cold-form foil adoption demands press modification investments that mid-cap generic producers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical-Grade Foil Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Foil, Plastic Foil, Composite Foil, Laminated Foil End User: Hospitals, Clinics, Pharmaceutical Companies, Research Labs Application: Packaging, Sterilization, Drug Delivery, Medical Devices Certification: ISO 13485, FDA Approved, CE Mark, GMP Compliant |
| Companies Covered | Amcor plc, Constantia Flexibles Group GmbH, Hindalco Industries Limited, Novelis Inc., ACG Pharmapack Pvt. Ltd., Uflex Ltd., Tekni-Plex, Inc., Ess Dee Aluminium Ltd., Klöckner Pentaplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical-Grade Foil Market Strategic Shifts
Barrier engineering is pivoting from single-material dominance toward engineered multi-layer architectures that reconcile oxygen transmission limits with thermoformability requirements.
Multi-layer coextrusion with discrete ethylene vinyl alcohol barrier cores is hybridizing previously separate foil and film supply chains. Pharmaceutical packagers in Germany and Switzerland are specifying these structures for high-potency oncology drugs. The technology is compressing converter differentiation around lamination precision rather than base aluminum sourcing alone.
EU MDR technical documentation requirements for primary packaging components are extending CE marking obligations to foil producers previously exempt from device-level compliance. Converter audit intensity has tripled since the regulation's full enforcement. German and Austrian packaging hubs are absorbing disproportionate compliance costs as they supply pan-European pharmaceutical manufacturing networks.
Serialization-driven track-and-trace mandates are compressing pharmaceutical procurement cycles toward qualified supplier lists with pre-validated foil specifications. Brand-name drug manufacturers are consolidating vendor relationships from twelve to four primary converters. This concentration is most visible in the United States, where FDA DSCSA enforcement deadlines have eliminated spot-market foil purchasing for prescription blister packs.
Medical-Grade Foil Market Segmentation
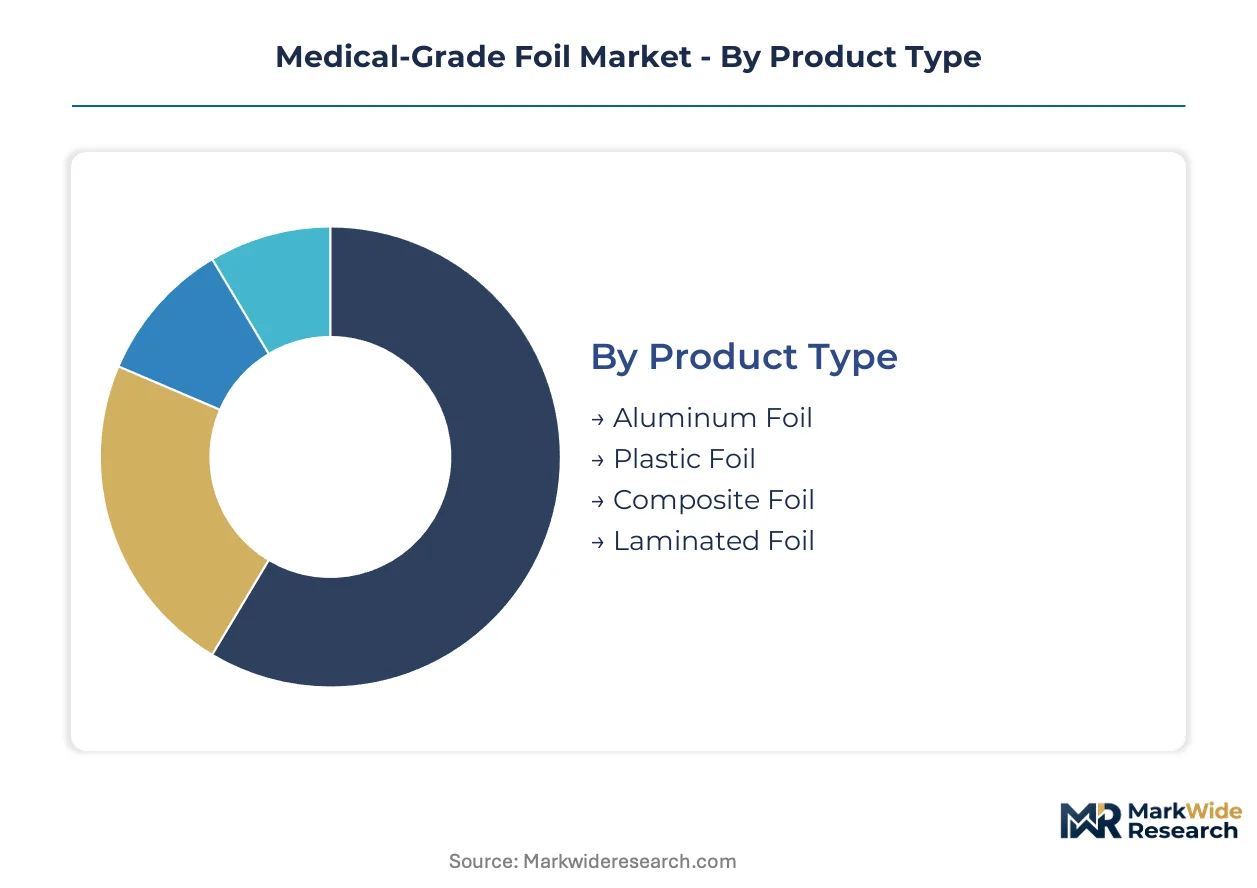
Medical-grade foil segmentation reveals how material specifications diverge across sterilization intensity, regulatory exposure, and end-use criticality. Each dimension carries distinct qualification burdens and margin structures that shape converter strategy.
Product Type:
After-sales service intensity escalates with material complexity, as multi-layer laminations demand technical troubleshooting that commodity aluminum foils rarely require.
- Aluminum Foil:Cold-rolled thin-gauge sheet with controlled surface oxidation for thermoforming and cold-forming compatibility. Demand concentrates in German pharmaceutical packaging hubs where tandem mill expertise anchors supply for high-volume blister packs, though LME price volatility compresses converter margins on fixed contracts.
- Composite Foil:Engineered multi-layer structures combining aluminum with polymer films to reconcile barrier performance with heat-seal customization. Momentum clusters in Swiss and German oncology drug packaging where EVOH barrier cores address ultra-high oxygen transmission requirements for moisture-sensitive biologics.
- Plastic Foil:Cast or oriented polymer films serving lower-barrier applications where metal detection compatibility matters.
- Laminated Foil:Discrete layer architectures with integrated print substrates for anti-counterfeiting microtext and holographic authentication.
Aluminum foil holds the largest share; momentum sits with composite foil as combination drug-device products proliferate.
End User:
Cost tier stratification separates institutional procurement from branded pharmaceutical specifications, with research labs occupying a volatile middle ground of small-batch customization.
- Pharmaceutical Companies:Brand-name and generic drug manufacturers specifying foil for primary packaging with full pharmacopeial traceability. Volume concentrates in United States and Indian manufacturing networks where FDA DSCSA and CDSCO serialization mandates compress supplier qualification timelines toward pre-validated converter relationships.
- Hospitals:Central sterile supply departments sourcing foil for surgical kit wrapping and instrument sterilization pouches. Demand clusters in United States health systems where Joint Commission accreditation drives specification consistency across regional purchasing alliances.
- Clinics:Outpatient and specialty practices with fragmented procurement and price-sensitive spot purchasing.
- Research Labs:Academic and contract research organizations requiring custom slit widths and short-run laminations for experimental drug formulations.
Pharmaceutical companies command the premium tier; clinics represent the most price-elastic demand pool.
Application:
Volume distribution tracks directly to sterilization validation burden, with packaging applications absorbing disproportionate regulatory documentation overhead.
- Packaging:Primary and secondary containment for pharmaceuticals, medical devices, and diagnostic components including blister packs, sachets, and pouch formats. Demand concentrates in cold-chain biologics where temperature stability requirements exceed standard barrier specifications, particularly for mRNA therapies requiring ultra-low temperature protection.
- Sterilization:Terminal sterilization wraps and peel pouches maintaining sterility assurance levels through steam, ethylene oxide, or gamma irradiation cycles. Momentum sits with ethylene oxide-compatible laminations as device manufacturers consolidate sterile barrier systems.
- Drug Delivery:Prefilled syringe plunger seals, transdermal patch backings, and inhaler foil components.
- Medical Devices:Implantable and diagnostic device packaging with extended shelf-life requirements.
Packaging dominates volume; drug delivery applications are climbing the fastest as combination products blur device-drug boundaries.
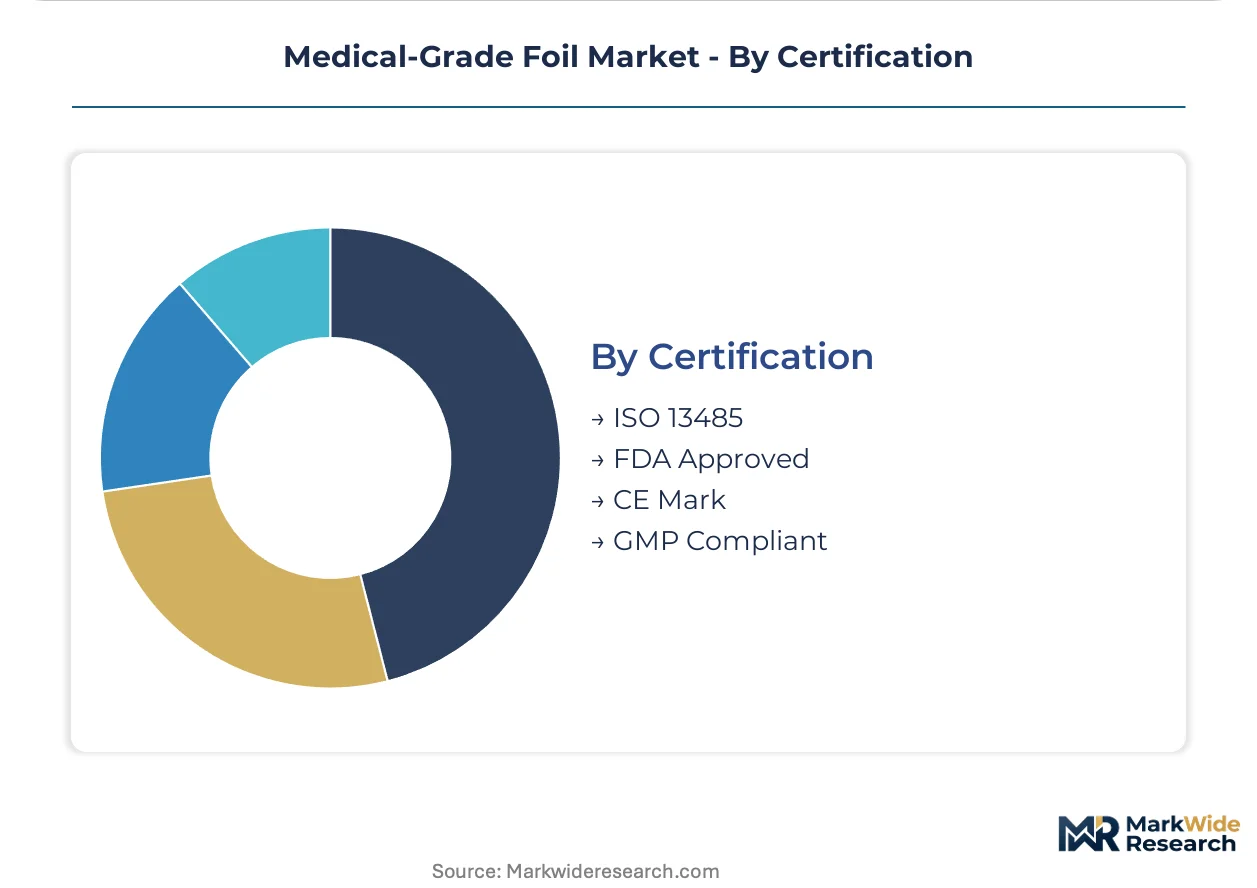
Certification:
Margin tiering follows audit intensity, with FDA-approved specifications commanding substantial premiums over base ISO compliance due to inspection frequency and documentation depth.
- ISO 13485:Quality management system certification mandatory for medical device packaging suppliers, establishing baseline traceability and risk management protocols. German and Austrian converters anchor European supply with mature certification infrastructure serving pan-European pharmaceutical networks.
- FDA Approved:Drug master file submissions and facility registrations enabling United States commercial distribution. Qualification timelines extend eighteen months, locking incumbent supplier relationships and delaying new converter entry.
- CE Mark:EU MDR Annex I compliance for primary packaging components deemed integral to device sterility, extending technical documentation obligations previously exempt.
- GMP Compliant:FDA cGMP and EU GMP adherence for pharmaceutical packaging materials with batch release testing and environmental monitoring.
ISO 13485 represents the baseline requirement; FDA-approved specifications capture the steepest expansion trajectory as United States biologics capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packaging organizations and biologics manufacturers concentrate foil procurement in Germany, the United States, and India, with secondary demand clusters forming around Swiss oncology packaging hubs and Chinese domestic drug production networks.
Germany
Cold-form blister foil demand from high-potency oncology drug packagers drives specifications toward ultra-thin aluminum gauges with EVOH barrier integration. EU MDR Annex I technical documentation requirements now extend CE marking obligations to foil converters supplying pan-European pharmaceutical networks. The Rhine-Main packaging corridor around Frankfurt anchors tandem mill expertise and lamination capacity for temperature-sensitive biologics.
United States
FDA DSCSA serialization enforcement has eliminated spot-market foil purchasing for prescription blister packs, compressing supplier relationships toward pre-validated converter lists. Biologics cold-chain expansion for mRNA therapies and monoclonal antibodies demands thermal stability profiles exceeding standard barrier specifications. The New Jersey-Pennsylvania pharmaceutical manufacturing belt concentrates foil qualification activity for domestic biologics fill-finish capacity.
India
CDSCO manufacturing license reforms and PLI scheme incentives attract biologics investment, driving localized foil demand from contract packaging organizations scaling capacity. Primary aluminum rolling for thin-gauge medical applications concentrates at Hindalco Industries Limited manufacturing complexes. The Mumbai-Pune pharmaceutical corridor anchors domestic foil specification development for export-oriented generic drug packaging.
Switzerland
Specialized oncology drug packaging requirements from Swiss pharmaceutical headquarters operations push foil specifications toward multi-layer coextrusion with discrete barrier cores. Swissmedic device regulations reinforce technical documentation standards for primary packaging components deemed integral to sterility assurance. The Basel biopharma cluster generates premium-tier foil demand for combination drug-device products.
China
NMPA pharmaceutical packaging material regulations and domestic biologics manufacturing scale-up create parallel qualification tracks for local and export-market foil specifications. GB standards for pharmaceutical aluminum foil diverge from USP and EP pharmacopeial requirements, forcing dual validation studies for multinational drug launches. The Yangtze River Delta pharmaceutical manufacturing zone concentrates domestic foil converter capacity for regional generic drug production.
Medical-Grade Foil Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered qualification barriers that lock pharmaceutical procurement relationships. The vendor base stratifies between integrated packaging conglomerates with film-to-foil lamination capabilities and specialized aluminum rolling operations serving thin-gauge medical applications. Three archetypes dominate: integrated packaging systems providers, primary aluminum converters with pharmaceutical certifications, and regional specialists in cold-form blister specifications. Competitive moves concentrate on M&A for qualification portfolio expansion and capacity additions near biologics manufacturing clusters.
Within the integrated packaging tier, Amcor plc and Constantia Flexibles Group GmbH occupy positions spanning film-to-foil lamination and pharmaceutical certification infrastructure. Among primary aluminum specialists, Hindalco Industries Limited exemplifies the thin-gauge rolling archetype anchored to Indian manufacturing complexes. Novelis Inc. represents the North American aluminum rolling position serving medical-grade specifications. These three named entities anchor the competitive structure without exhausting the qualified supplier base that pharmaceutical companies maintain for procurement risk distribution.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles Group GmbH |
| Hindalco Industries Limited |
| Novelis Inc. |
| ACG Pharmapack Pvt. Ltd. |
| Uflex Ltd. |
| Tekni-Plex, Inc. |
| Ess Dee Aluminium Ltd. |
| Klöckner Pentaplast Group |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Main pharmaceutical logistics corridor anchors cold-form foil distribution across German manufacturing networks, with freight cost volatility from Rotterdam-Frankfurt rail links amplifying price differentiation between ISO 13485-certified converters and commodity aluminum suppliers serving spot-market buyers.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate pharmaceutical foil procurement, with three-tier pricing structure across premium, standard, and economy levels separating FDA-approved specifications from base ISO compliance and unvalidated imports. Price differentiation rests on certification grade and volume scale, with eighteen-month qualification timelines locking brand-name drug manufacturers into premium tiers. Cost compression in standard-grade aluminum foil is intensifying because Indian contract packaging organizations leverage localized Hindalco rolling capacity. Clinics and research labs exhibit highest price sensitivity; biologics manufacturers show least elasticity due to thermal stability requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for pharmaceutical foil converters, with Section 301 duties on aluminum semis forcing dual-sourcing strategies. Primary supply concentrates in Germany, India, and Japan, with ethylene vinyl alcohol resin production drawing from South Korean and Japanese petrochemical complexes. Single-source vulnerability sits with EVOH barrier layer supply from Asia-Pacific polymer producers. Distribution runs through qualified supplier lists maintained by pharmaceutical contract packaging organizations, eliminating spot-market purchasing for serialized blister packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical-grade foil market functions as a regulatory entrenchment story, where eighteen-month FDA qualification cycles and EU MDR technical documentation requirements create switching-cost moats that protect incumbent converter relationships.
For Market Incumbents: Pre-empt emerging Indian contract packaging scale-up by anchoring capacity additions near Mumbai-Pune biologics clusters before CDSCO manufacturing license reforms mature. Consolidate backward integration into ethylene vinyl alcohol lamination capabilities to offset polymer supply concentration risk from Japanese and South Korean producers. Defend against Hindalco's thin-gauge rolling cost advantage by embedding anti-counterfeiting print layers that command premium positioning.
For New Entrants and Emerging Players: Establish a beachhead in research lab custom slit-width specifications, where short-run laminations for experimental drug formulations bypass eighteen-month pharmaceutical qualification barriers. Target Swiss oncology packaging hubs with multi-layer coextrusion capabilities for high-potency drugs, as Swissmedic device regulations extend CE marking obligations that deter commodity converters. Lead with thermal stability validation for mRNA therapy cold-chain applications as the go-to-market angle.
For Investors and Strategic Acquirers: Cold-form blister specialists with integrated EVOH lamination lines represent the priority acquisition archetype, as EU MDR Annex I requirements compress procurement toward pre-validated converter relationships. Long-term viability hinges on biologics cold-chain expansion sustaining premium-tier demand through the next decade. Watch for FDA DSCSA enforcement deadline acceleration as the inflection signal indicating supplier list consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Lamination | Captures margin from Japanese and South Korean polymer suppliers while securing barrier layer supply. |
| Capacity Expansion near Mumbai-Pune Corridor | Positions converters for CDSCO-licensed biologics fill-finish investment under PLI scheme incentives. |
| FDA Drug Master File Submission Acceleration | Compresses eighteen-month qualification timelines for United States biologics procurement consolidation. |
| Anti-Counterfeiting Print Layer Integration | Commands premium positioning against generic foil imports through microtext and holographic authentication. |
| Cold-Form Blister Specification Development | Addresses ultra-high oxygen transmission requirements for Swiss and German oncology drug packaging. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical packaging engineers, regulatory affairs specialists at foil converters, contract manufacturing organization procurement directors, and hospital sterile supply managers, then refined through secondary validation against FDA drug master file submissions, EU MDR technical documentation databases, CDSCO manufacturing license registries, and aluminum trade flow data. Bottom-up demand modeling from blister pack unit economics and top-down market sizing from pharmaceutical packaging expenditure triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end user, application, and certification tier alongside regional regulatory cluster differentiation. CAGRs were derived from pharmaceutical production volume trajectories and biologics cold-chain expansion rates. Forecast inputs incorporated LME aluminum price volatility assumptions and EU MDR enforcement timeline progression.
Stress conditions across primary aluminum ingot pricing, ethylene vinyl alcohol resin supply disruption, and FDA DSCSA deadline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding serialization mandate adoption curves and biologics manufacturing capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market