
 Global Pet Food and Pet Product Packaging Market | 2026-2036
Global Pet Food and Pet Product Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Food and Pet Product Packaging Market Outlook
Subscription-based replenishment services is restructuring how pet food packaging gets specified, with brands now demanding portion-controlled, shelf-stable formats that integrate with direct-to-consumer logistics. Amcor plc leverages its global flexible film network to supply multi-layer barrier solutions for automated fulfillment. Mondi Group anchors European demand through kraft-paper-based recyclable packaging that aligns with retailer sustainability mandates. ProAmpac LLC differentiates via specialized high-speed form-fill-seal films engineered for wet food retort applications.
Pet food and pet product packaging encompasses primary and secondary containment systems—ranging from metallized polyester laminates and extruded polyethylene films to molded polyethylene terephthalate trays and tinplate cans—designed to preserve nutritional integrity, extend shelf life, and enable brand differentiation at point of sale. Flexible packaging dominates volume for dry food and treats due to lightweight logistics and material efficiency, while rigid formats sustain premium positioning for wet food where thermal processing demands structural integrity. Paper-based substrates represent the fastest-growing material class as mono-material specifications displace legacy multi-layer constructions that complicate mechanical recycling streams.
The US FDA and EPA govern material safety and environmental claims for pet food contact substances, while the EU PPWR and REACH framework mandate recyclability targets and chemical transparency across packaging placed on European markets. These regulatory architectures force converters to validate alternative barrier technologies—bio-based coatings, plasma-deposited silicon oxide layers—that maintain oxygen and moisture protection without compromising end-of-life processing. Stakeholders must monitor evolving extended producer responsibility schemes and certification protocols that will determine which material platforms retain market access across major economies.
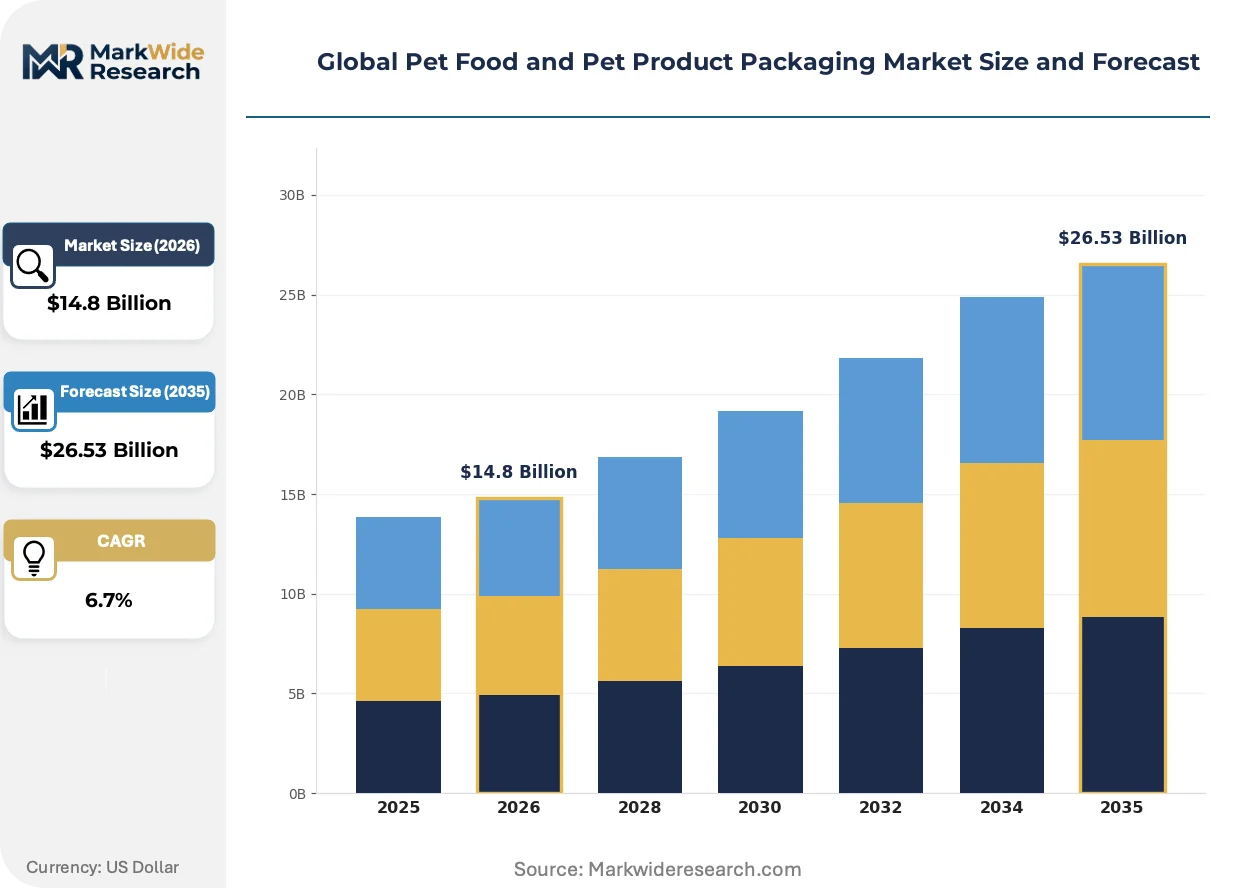
Market Dynamics
EU PPWR recyclability mandates are compressing multi-layer flexible packaging specifications toward mono-polymer alternatives, forcing converters to redesign barrier architectures without sacrificing shelf-life performance for premium wet and dry pet food formats.
Growth Catalysts
- REACH chemical transparency requirements:European converters accelerate validation of bio-based coatings and silicon oxide barrier layers to maintain oxygen protection while satisfying recyclability targets.
- Pet humanization in China:Urban household pet ownership rates climb fastest in tier-one cities, generating demand for portion-controlled, shelf-stable packaging compatible with e-commerce fulfillment.
- Retort pouch technology:High-speed form-fill-seal films engineered for wet food thermal processing enable brands to displace metal cans with lightweight flexible alternatives.
Market Restraints
- Aluminum and ethylene input cost volatility:Metallized polyester laminates and extruded polyethylene films face margin pressure from petrochemical feedstock price swings.
- Barrier coating technical limitation:Plasma-deposited silicon oxide layers struggle to match aluminum oxide performance at commercial scale for extended shelf-life applications.
- Mechanical recycling infrastructure gaps:Collection and sorting systems in the United States lag mono-material specification rollout, creating end-of-life processing bottlenecks.
Strategic Opportunities
- Kraft-paper-based recyclable formats:European retailer sustainability mandates create white space for fiber-primary structures with thin polymer barrier layers.
- Subscription direct-to-consumer channel:Automated fulfillment networks demand portion-controlled, shelf-stable formats with integrated reseal features.
- Extended producer responsibility schemes:Germany's packaging fee modulation rewards mono-material adoption with reduced compliance levies.
Industry Challenges
- Barrier chemist talent scarcity:Formulation expertise for bio-based coatings and vapor-deposited layers concentrates among a narrow specialist pool.
- Retort equipment capex intensity:Wet food flexible packaging lines require specialized high-temperature sterilization infrastructure.
- Multi-region certification timelines:FDA food contact notification and EU REACH dossier preparation create extended product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Food and Pet Product Packaging Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Pouches, Boxes Material: Plastic, Paper, Metal, Glass End User: Retailers, Wholesalers, Distributors, Online Retailers Product Type: Dry Food, Wet Food, Treats, Supplements |
| Companies Covered | Amcor plc, Berry Global Group, Inc., Mondi Group, ProAmpac LLC, Huhtamäki Oyj, Smurfit Kappa Group, Sealed Air Corporation, Sonoco Products Company, Crown Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Food and Pet Product Packaging Market Strategic Shifts
Digitally-enabled production workflows and advanced barrier deposition techniques are compressing development cycles for sustainable packaging alternatives while regulatory pressure accelerates material substitution timelines.
Digital printing for short-run customization is decentralizing brand packaging strategies. Premium pet food marketers in Germany and the United States adopt variable-data graphics for limited-edition releases and regional flavor variants. This capability collapses minimum order quantities and enables test-market agility previously reserved for multinational brands with dedicated converter relationships.
REACH Annex XIV authorization requirements are forcing substitution of perfluorinated barrier chemistries in European markets. Converters accelerate plasma-enhanced chemical vapor deposition of silicon oxide layers as drop-in replacements. Wet food retort applications face the steepest compliance burden, driving collaboration between film suppliers and equipment manufacturers to validate alternative barrier performance under thermal processing conditions.
Veterinary-formulated therapeutic diets are fragmenting procurement patterns among specialty retailers and veterinary clinics. Brands now specify distinct packaging formats for prescription channels versus mass-market distribution, with anti-counterfeiting features and dosing instructions tailored to professional dispensing workflows. This bifurcation is most pronounced in the United States, where prescription pet food sales concentrate through veterinary practice networks and authorized online pharmacies.
Global Pet Food and Pet Product Packaging Market Segmentation
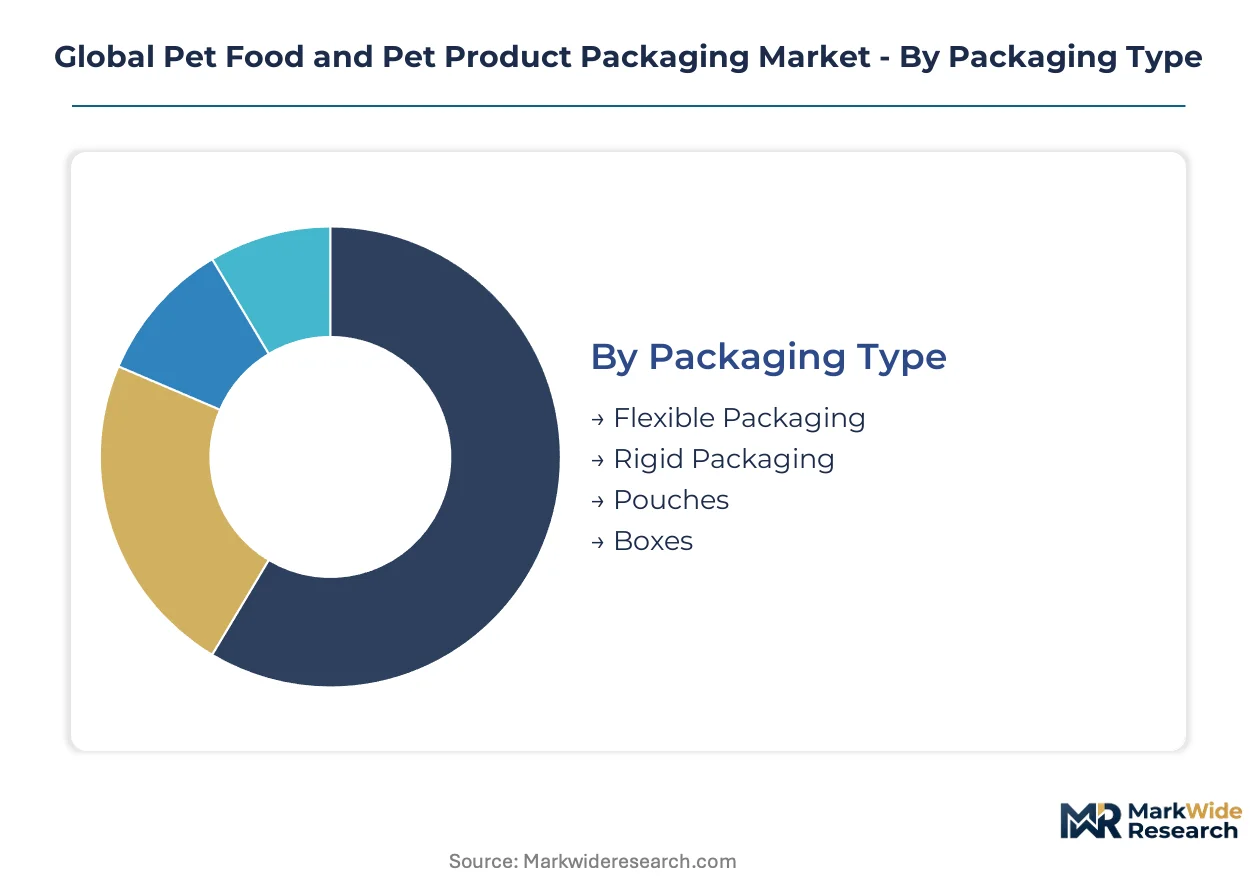
Packaging specification decisions in pet food diverge sharply across distribution channels and product formats. Material selection, barrier requirements, and shelf-life demands vary substantially between e-commerce fulfillment networks and traditional retail stocking patterns.
Packaging Type:
Cost tier drives converter selection, with premium brands prioritizing reseal functionality and logistics efficiency over unit economics.
- Flexible Packaging:Multi-layer metallized polyester and polyethylene laminates dominate dry food and treat applications. Demand concentrates in the United States for subscription replenishment services requiring lightweight, shelf-stable formats with integrated zipper closures.
- Rigid Packaging:Molded polyethylene terephthalate trays and tinplate cans sustain thermal processing requirements for wet food. Germany's retailer sustainability mandates accelerate transitions toward recyclable mono-polymer alternatives.
- Pouches:Stand-up flexible structures with spout fitments gain traction in portion-controlled wet food segments.
- Boxes:Corrugated secondary containment serves bulk dry food and multi-pack configurations for club retail channels.
Flexible packaging leads on scale; pouches lead on momentum.
Material:
Application-specific barrier requirements determine material substitution timelines under evolving recyclability mandates.
- Plastic:Extruded polyethylene films and polypropylene structures retain volume leadership despite regulatory pressure. China's urban pet humanization trends sustain demand for portion-controlled flexible formats compatible with e-commerce logistics.
- Paper:Kraft-paper-based substrates with thin polymer barrier layers expand most quickly as European converters redesign for EU PPWR compliance.
- Metal:Tinplate and aluminum sustain retort applications where thermal processing demands structural integrity.
- Glass:Premium positioning for specialty supplements and veterinary-formulated therapeutic diets.
Plastic leads on scale; paper leads on momentum.
End User:
Customer type dictates order quantity, customization requirements, and sustainability certification demands.
- Retailers:Mass-market and specialty pet chains specify high-volume standardized formats with pallet-optimized cube efficiency.
- Wholesalers:Intermediate stocking points require bulk secondary packaging with extended shelf-life protection.
- Distributors:Veterinary clinic networks demand anti-counterfeiting features and professional dispensing instructions for prescription diets.
- Online Retailers:Direct-to-consumer fulfillment centers prioritize damage-resistant, lightweight structures compatible with automated sortation systems.
Retailers lead on scale; online retailers lead on momentum.
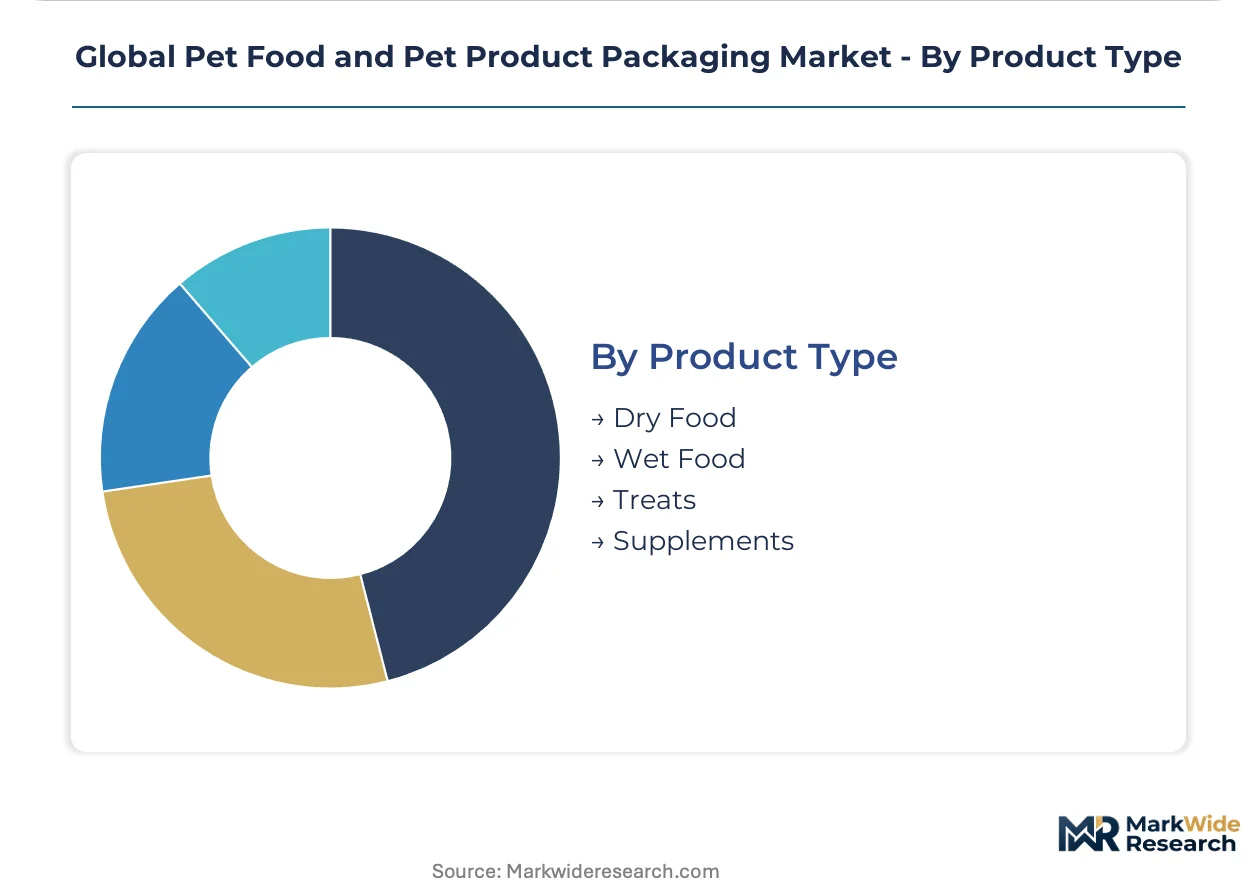
Product Type:
Maturity gradients separate established dry food formats from emerging therapeutic and supplement categories.
- Dry Food:Kibble and extruded formulations sustain flexible packaging dominance with high-barrier pouches and multi-wall bags.
- Wet Food:Retort pouch technology enables flexible alternatives to metal cans, with Germany and the United States driving validation of silicon oxide barrier layers.
- Treats:Resealable flexible pouches support premium positioning and portion control for training and reward applications.
- Supplements:Veterinary-formulated and wellness-oriented formats require specialized containment with dosing precision and moisture protection.
Dry food leads on scale; supplements lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping converter location decisions as EU PPWR compliance costs widen the gap between European and North American production economics. Brands now route premium flexible packaging orders toward jurisdictions with clearer extended producer responsibility frameworks.
United States
Subscription replenishment services headquartered in Austin and Denver are driving specification demand for portion-controlled pouches with integrated zipper closures. FDA food contact notification requirements govern barrier coating approvals for wet food retort applications. Flexible packaging converters cluster in the Midwest industrial corridor around Chicago and Grand Rapids to serve automated fulfillment networks.
Germany
Retailer sustainability mandates from dm-drogerie markt and Fressnapf are accelerating mono-polymer transitions for private-label pet food lines. ECHA REACH Annex XIV authorization deadlines are forcing substitution of perfluorinated chemistries in barrier coatings. Converters in North Rhine-Westphalia and Bavaria are validating silicon oxide deposition technologies for recyclable flexible structures.
China
Urban pet ownership rates in Shanghai and Beijing are generating demand for shelf-stable formats compatible with Alibaba and JD.com logistics networks. SAMR packaging safety standards govern material migration limits for pet food contact substances. Yangtze River Delta converters are expanding high-barrier film capacity to serve domestic premium brands and export orders.
United Kingdom
Veterinary-formulated therapeutic diet sales through Mars Petcare and Nestlé Purina channels are fragmenting packaging specifications between prescription and mass-market formats. UK REACH alignment with EU chemical transparency requirements is extending compliance timelines for barrier coating transitions. Flexible packaging specialists in the Midlands are developing anti-counterfeiting features for professional dispensing workflows.
Brazil
Mass-market dry food volume in São Paulo and Rio de Janeiro sustains demand for multi-wall paper bags with polyethylene liners. ANVISA sanitary surveillance requirements govern material safety for imported packaging substrates. Local converters in the Southeast industrial zone are investing in form-fill-seal capacity to displace imported flexible formats.
Global Pet Food and Pet Product Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium pet food brands favoring dedicated converter relationships while private-label retailers source through diversified supplier panels. The market exhibits moderate consolidation at the film extrusion tier and fragmentation among regional pouch converters. Three archetypes dominate: integrated multinational film suppliers with global flexible networks, European paper-based specialists leveraging kraft-recyclable positioning, and regional form-fill-seal operators serving wet food retort niches. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as converters race to validate mono-material barrier architectures.
Among integrated multinational suppliers, Amcor plc, Mondi Group, and ProAmpac LLC exemplify the scale-driven archetype. Amcor occupies a position as a global flexible film network anchor with multi-layer barrier capabilities spanning dry and wet food applications. Mondi represents the European paper-primary specialist tier, leveraging kraft-based recyclable formats aligned with retailer sustainability mandates. ProAmpac sits within the high-performance retort niche, supplying form-fill-seal films engineered for thermal processing requirements. These three companies collectively illustrate how converter specialization maps to regulatory geography and distribution channel fragmentation.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group, Inc. |
| Mondi Group |
| ProAmpac LLC |
| Huhtamäki Oyj |
| Smurfit Kappa Group |
| Sealed Air Corporation |
| Sonoco Products Company |
| Crown Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU PPWR recyclability mandates are forcing converters to absorb retooling costs for mono-polymer barrier architectures, compressing margins on legacy multi-layer specifications while premium brands absorb price premiums for certified sustainable formats.
Pricing Analysis
Distributor markups for veterinary-formulated therapeutic diets run higher than mass-market channels due to anti-counterfeiting features and professional dispensing workflows. Three-tier pricing structure across premium, standard, and economy levels separates resealable flexible pouches from basic multi-wall bags and commodity cans. Pricing pressure stems from aluminum and ethylene feedstock volatility eroding converter margins on metallized polyester laminates. Private-label retailers exhibit highest price sensitivity, while subscription direct-to-consumer brands prioritize logistics efficiency over unit economics.
Supply Chain Analysis
Ocean freight cost fluctuations between Asia and Europe are reshaping converter location decisions as brands route premium flexible packaging orders toward jurisdictions with clearer extended producer responsibility frameworks. Raw material supply draws from Saudi Arabia for polyethylene feedstock, China for metallized film substrates, and Germany for kraft paper specialties. Single-source vulnerability concentrates in plasma-deposited silicon oxide barrier coating equipment anchored in German and Japanese manufacturing clusters. Distribution runs through automated fulfillment networks for direct-to-consumer channels and pallet-optimized bulk shipments for club retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU PPWR compliance costs and US regulatory lag creates margin expansion opportunities for converters with dual-hemisphere production footprints.
For Market Incumbents: Extend silicon oxide barrier validation programs to capture wet food retort share before REACH Annex XIV deadlines eliminate perfluorinated alternatives. Deepen backward integration into bio-based coating feedstocks to defend margin position against petrochemical price volatility. Prioritize capacity expansion in the US Midwest industrial corridor to anchor automated fulfillment network relationships. For New Entrants and Emerging Players: The price-point gap between premium resealable pouches and economy multi-wall bags creates white space for mid-tier mono-material formats with thin polymer barrier layers. Target kraft-paper-based recyclable specifications for European private-label retailers facing sustainability mandates. Pursue equipment partnerships with retort pouch technology licensors to bypass capex barriers for wet food thermal processing. For Investors and Strategic Acquirers: Asymmetric upside sits with regional form-fill-seal operators possessing validated silicon oxide barrier expertise and established veterinary channel relationships. Long-term viability hinges on converters bridging mechanical recycling infrastructure gaps in North America while scaling mono-material production. Watch Germany's packaging fee modulation implementation as an inflection indicator for mono-polymer adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Validation | EU PPWR compliance secures market access for wet food retort applications in Germany and France. |
| Backward Integration into Bio-Based Coatings | Captive supply of REACH-compliant barrier chemistries reduces regulatory risk exposure. |
| Direct-to-Consumer Channel Expansion | Subscription replenishment services in Austin and Denver demand portion-controlled pouch formats. |
| Kraft-Paper Recyclable Format Launch | dm-drogerie markt and Fressnapf sustainability mandates create white space for fiber-primary structures. |
| Retort Equipment Partnership | Collaboration with thermal processing specialists accelerates wet food flexible packaging validation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converters, brand procurement managers, and veterinary distribution specialists alongside secondary validation through FDA food contact notifications, ECHA REACH dossiers, and EU PPWR implementation guidance. Customs records for polyethylene film imports, flexible packaging trade flows, and retailer sustainability mandate disclosures anchored supply-side modeling. Bottom-up capacity estimates from North Rhine-Westphalia and Yangtze River Delta converter clusters triangulated against top-down demand projections from pet food brand production forecasts.
Segment-weighting approaches distributed value across packaging type, material substrate, and end-user channel dimensions, with additional granularity for regulatory compliance tier and thermal processing requirement. CAGRs derived from historical volume trajectories, substitution elasticity estimates for mono-material transitions, and channel shift assumptions for subscription replenishment services across the analysis window. Forecast inputs incorporated EU extended producer responsibility fee schedules, aluminum oxide barrier performance benchmarks, and wet food retort pouch adoption curves.
The model assumes a particular technology adoption path; alternative pathways for plasma-deposited silicon oxide barrier layers would alter the outlook if commercial scale validation lags REACH authorization deadlines. Forecasts reflect assumptions about mechanical recycling infrastructure buildout rates and petrochemical feedstock price stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Middle East and Africa Baby Food Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
North America Home Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market