
 Medical Containers Market | 2026-2036
Medical Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Containers Market Foresight
Asset-light leasing models for temperature-controlled container fleets is rewriting competitive entry barriers in pharmaceutical logistics. Thermo Fisher Scientific leverages its cryogenic equipment network to anchor high-value cold chain contracts. Cardinal Health sustains hospital system relationships through consignment inventory programs that embed container management into supply agreements. Becton Dickinson differentiates via integrated sharps disposal systems that bundle containers with compliance tracking.
Medical containers are purpose-built receptacles manufactured from borosilicate glass, medical-grade polypropylene, or aluminum alloys, designed to maintain sterility, chemical stability, and dimensional integrity across temperature ranges from minus eighty degrees Celsius to ambient conditions. Their primary function spans drug storage, specimen transport, sharps containment, and biologics distribution throughout healthcare supply chains. Plastic containers lead volume production due to cost scalability and design flexibility, while glass vials command premium positioning in parenteral drug packaging where inert surface properties prevent protein denaturation. Infusion bags represent the fastest-expanding category as ambulatory care shifts intravenous therapy outside hospital walls.
The FDA enforces container closure system integrity standards under Current Good Manufacturing Practice guidelines, while Europe's Medical Device Regulation requires notified body certification for Class I reusable containers. The EPA's Resource Conservation and Recovery Act governs hazardous medical waste container labeling and disposal tracking across the United States. Stakeholders must monitor evolving pharmacopeial extractables and leachables testing protocols, as regulatory convergence between USP Chapter 1661 and EMA guidelines will reshape material qualification timelines and supplier qualification burdens.
Market Dynamics
Biopharmaceutical cold chain logistics is collapsing traditional container specifications as gene therapies and mRNA platforms demand cryogenic integrity across distribution networks. This structural pressure is forcing material science investments and reshaping supplier qualification protocols.
Growth Catalysts
- MDR compliance mandates:Europe's Medical Device Regulation tightens traceability requirements for reusable containers, accelerating fleet replacement cycles among hospital systems.
- Cell therapy logistics:CAR-T manufacturing expansion requires validated cryogenic shippers that maintain minus one hundred fifty degrees Celsius across multi-modal transport.
- Rhine-Main corridor concentration:Germany's pharmaceutical manufacturing density generates concentrated demand for specialized borosilicate glass and aluminum alloy containers.
Market Restraints
- Medical-grade polymer feedstock volatility:Polypropylene resin prices fluctuate with propylene monomer supply, squeezing margins for injection-molded container producers.
- Glass furnace capacity concentration:Borosilicate tubing production clusters in Central Europe and China, creating geographic single-source exposure for parenteral packaging.
- Extractables testing burden:USP Chapter 1661 and EMA convergence on leachables protocols extends material qualification timelines by twelve to eighteen months.
Strategic Opportunities
- Home infusion expansion:Ambulatory intravenous therapy migration creates demand for patient-portable infusion bags with integrated safety features.
- Asset-light leasing models:Temperature-controlled container fleet rentals reduce capital barriers for emerging biopharma logistics providers.
- IRAct manufacturing incentives:United States domestic production credits for active pharmaceutical ingredients stimulate local container molding capacity.
Industry Challenges
- Specialized polymer compounding expertise:Medical-grade additive formulation and validation capabilities concentrate among a limited supplier base.
- Multi-site qualification complexity:Container manufacturers must replicate FDA and notified body audits across distributed molding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Containers Market |
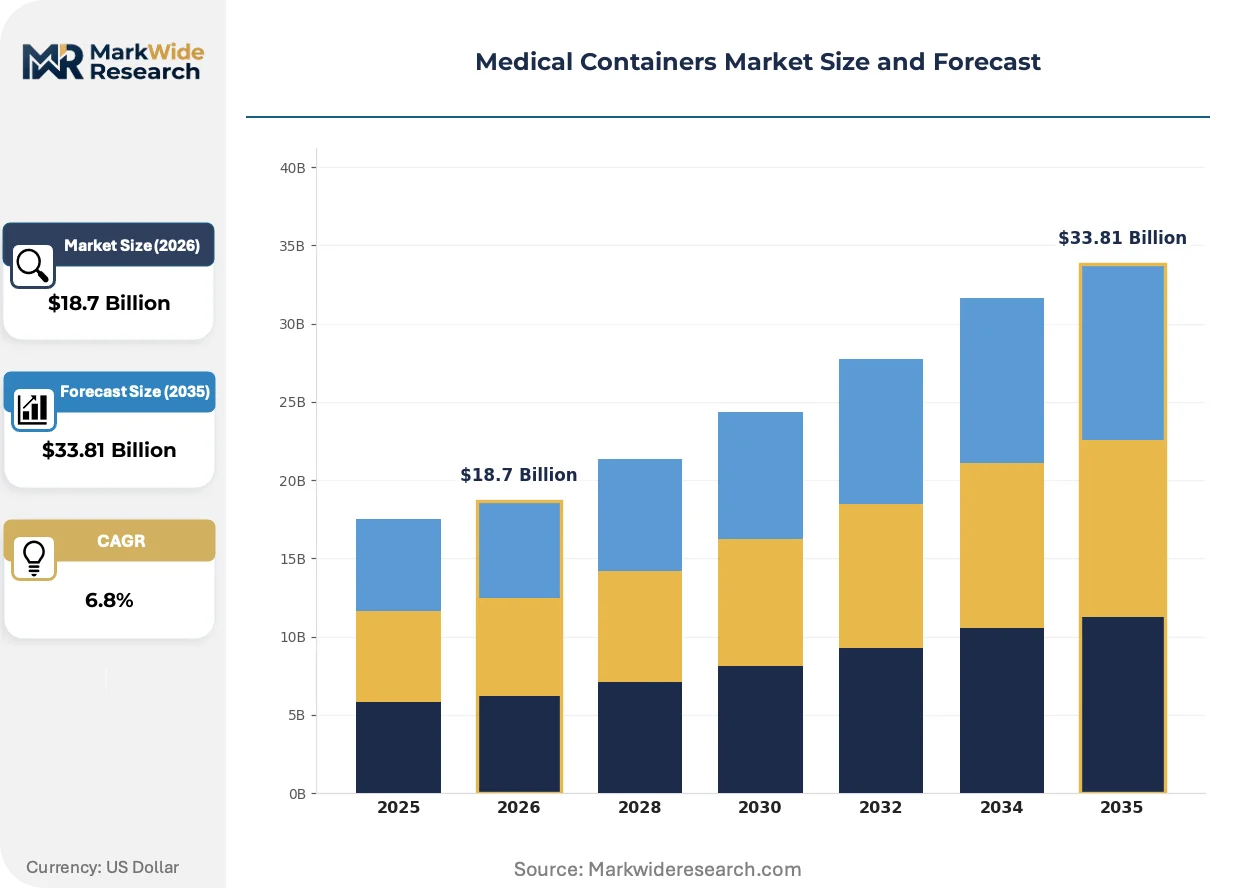
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Ampoules, Infusion Bags Material: Plastic, Glass, Metal, Rubber Size: Small, Medium, Large, Extra Large End User: Hospitals, Clinics, Pharmacies, Laboratories |
| Companies Covered | Becton Dickinson, Bemis Manufacturing Company, Cardinal Health, Thermo Fisher Scientific, Daniels Health, Bondtech Corporation, Amcor Plc, Berry Global Group, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Containers Market Shifts & Advancements
Active temperature monitoring integration is collapsing the distinction between packaging and data infrastructure. Smart containers now embed sensor networks that validate chain of custody across pharmaceutical distribution.
Phase-change material engineering is collapsing thermal protection design cycles. Advanced paraffin and salt hydrate formulations enable passive cooling systems that maintain two to eight degrees Celsius for ninety-six hours without external power. Biopharma third-party logistics providers are adopting these systems for last-mile delivery to clinical trial sites. This collapse of active-passive hybrid designs is compressing equipment capital requirements for regional distributors.
REACH substance restrictions are forcing material substitutions across European supply chains. The European Chemicals Agency's candidate list expansion targets phthalates and bisphenol derivatives used in flexible container films. Manufacturers are accelerating bio-based polyester and polyolefin elastomer development to maintain compliance. Germany's notified bodies are prioritizing certification reviews for alternative formulations.
Consignment inventory integration is restructuring hospital procurement relationships. Health systems now require container suppliers to embed stock management into supply agreements, transferring working capital burden upstream. Cardinal Health and regional distributors are deploying vendor-managed inventory systems across United States integrated delivery networks. This shift concentrates purchasing authority among supply chain executives rather than clinical material managers.
Medical Containers Market Segmentation
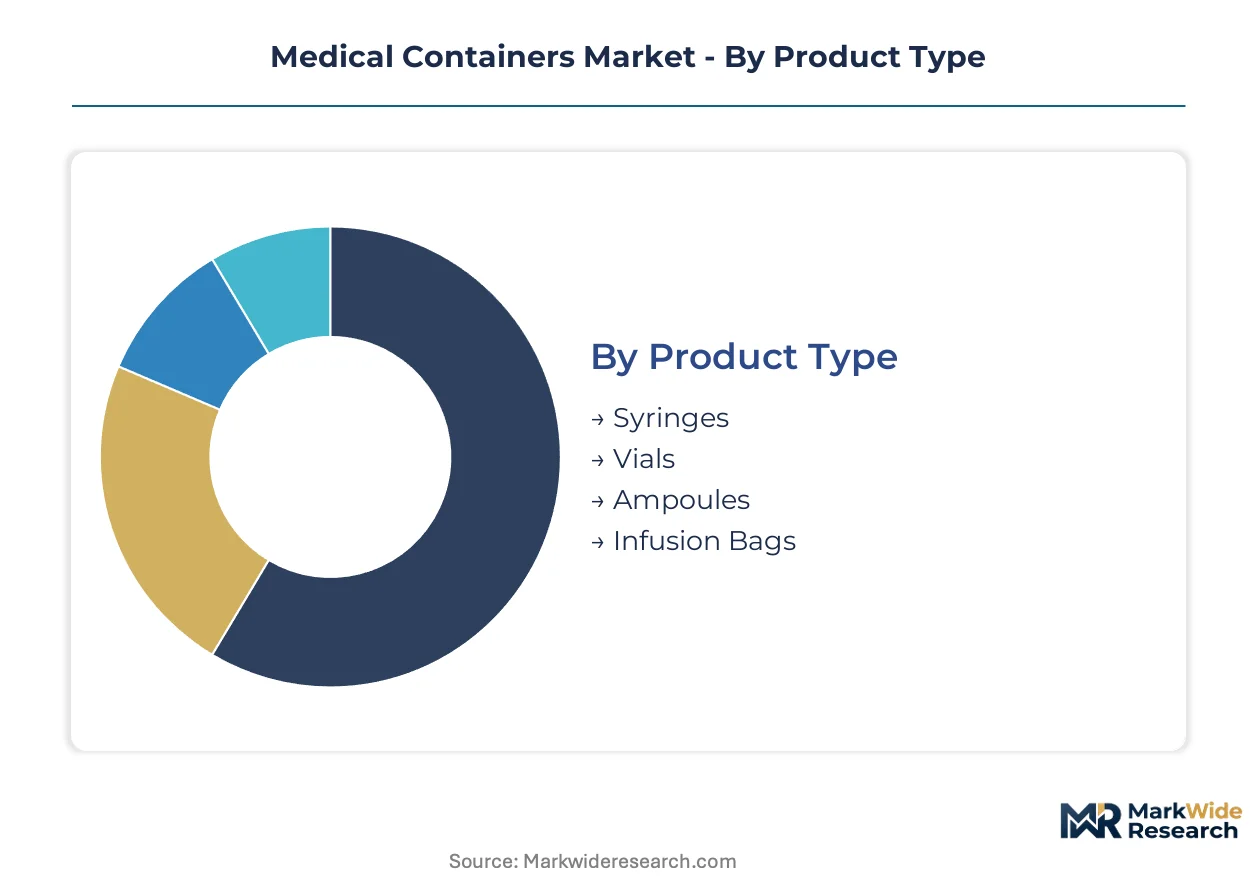
Medical container procurement decisions cascade through multiple technical and commercial dimensions. Material compatibility, dimensional specifications, and end-use sterility requirements create distinct supplier qualification pathways across each segment boundary.
Product Type:
Application-driven functional requirements separate these categories by sterility maintenance, dosing precision, and administration modality.
- Syringes:Pre-filled glass or polymer barrels with integrated needles or Luer-lock interfaces enable single-unit dosing for vaccines and biologics. Prefilled formats concentrate demand in Germany's Rhine-Main manufacturing corridor where automated fill-finish lines integrate directly with packaging operations.
- Infusion Bags:Flexible polyvinyl chloride or polyolefin chambers with integrated ports deliver large-volume parenteral solutions and chemotherapy regimens. Ambulatory care expansion in United States integrated delivery networks drives adoption of patient-portable designs with tamper-evident closures.
- Vials:Borosilicate or cyclic olefin polymer cylinders with elastomeric stoppers store multi-dose formulations requiring repeated access.
- Ampoules:Single-use glass vessels with scored necks provide hermetic sealing for emergency medications and contrast agents.
Syringes command the established base. The steepest expansion runs through infusion bags.
Material:
Cost tier and performance specifications divide the supply base by extractables profiles, thermal stability, and regulatory qualification burdens.
- Glass:Borosilicate tubing delivers inert surfaces with near-zero ion leaching for protein-based therapeutics. Central European furnace capacity constraints create supply bottlenecks for parenteral packaging requiring Type I hydrolytic resistance certification.
- Plastic:Polypropylene, polycarbonate, and cyclic olefin polymers enable injection-molded designs with design flexibility and drop resistance. Polypropylene resin price volatility tied to propylene monomer supply squeezes margins for high-volume producers.
- Metal:Aluminum alloys and stainless steel provide structural integrity for cryogenic shippers and reusable surgical instrument containers.
- Rubber:Bromobutyl and chlorobutyl elastomers form plunger stoppers and septum seals with gas barrier properties.
Plastic dominates volume production. Glass captures premium positioning in parenteral applications.
Size:
Volume requirements align with dosing protocols, inventory turnover, and automated handling system compatibility across healthcare settings.
- Small:Sub-10 milliliter capacities serve pediatric dosing, ophthalmic preparations, and high-potency biologics requiring minimal headspace. United States hospital systems concentrate procurement of unit-dose vials to reduce medication errors and waste.
- Large:One-to-five liter capacities support bulk API storage, buffer preparation, and centralized compounding operations. Germany's pharmaceutical manufacturing density generates concentrated demand for validated large-format containers with integrated sampling ports.
- Medium:10-100 milliliter formats balance handling efficiency with dosing flexibility for standard injectables.
- Extra Large:Vessels exceeding five liters enable manufacturing-scale fluid transfer and waste containment.
Medium sizes anchor routine procurement. Small formats are gaining share fastest in precision medicine applications.
End User:
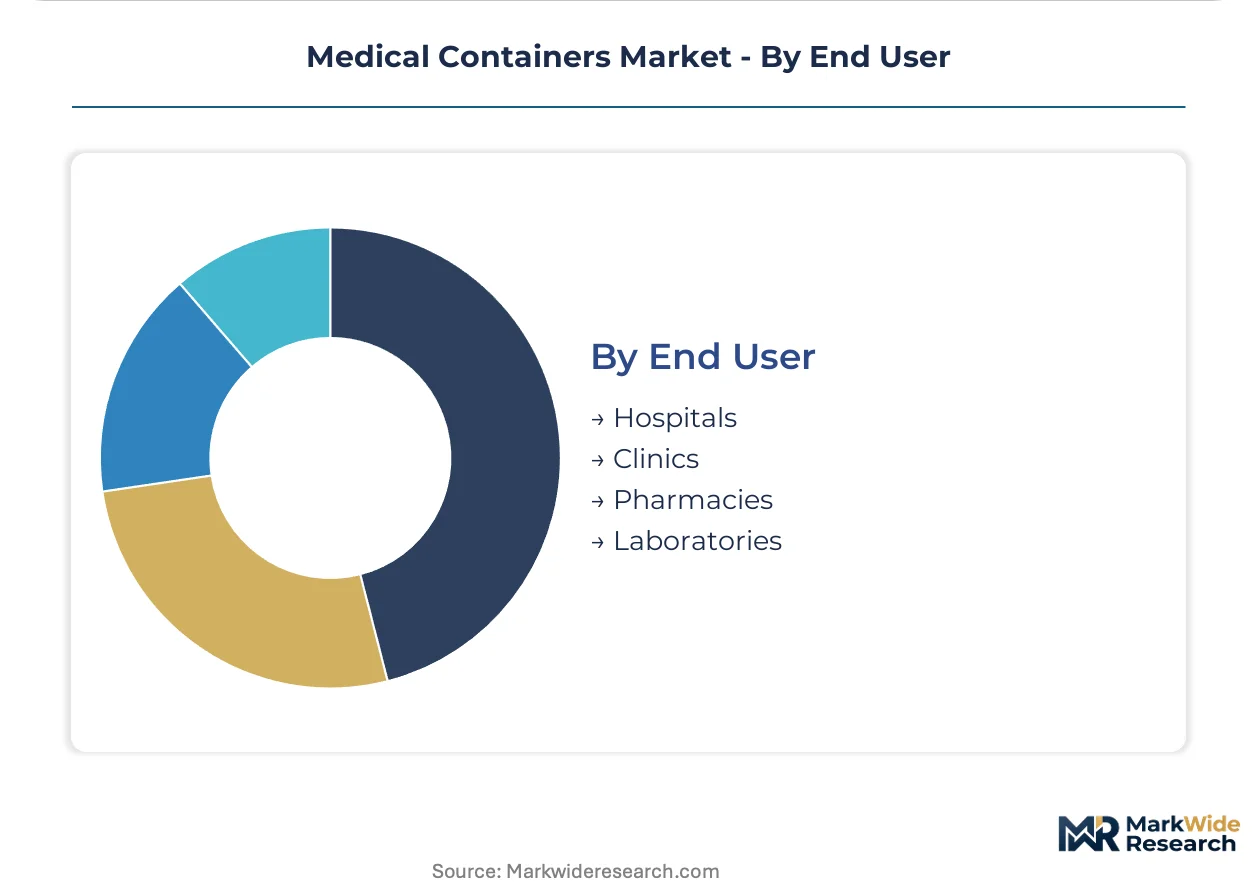
Customer type determines sterility assurance levels, traceability requirements, and purchasing authority structures.
- Hospitals:Acute care systems require validated container closure systems for compounded sterile preparations, blood products, and hazardous drug handling. FDA enforcement of 503B outsourcing facility regulations drives consolidation toward qualified suppliers with documented extractables profiles.
- Laboratories:Diagnostic and research facilities demand certified RNase-free and DNase-free containers for molecular specimen integrity. United States reference laboratories concentrate procurement of barcoded tubes compatible with automated analyzers.
- Clinics:Outpatient settings prioritize single-unit packaging and point-of-care compatibility for vaccination and infusion therapy.
- Pharmacies:Retail and specialty dispensers require child-resistant closures and compliance packaging for oral solid and liquid medications.
Hospitals concentrate purchasing authority. Laboratories are expanding most quickly in precision diagnostic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and biopharmaceutical manufacturers concentrate procurement authority in mature healthcare economies with dense manufacturing corridors and stringent regulatory frameworks. Cold chain logistics providers and contract manufacturers drive specialized container demand across distinct geographic clusters.
United States
FDA enforcement of 503B outsourcing facility regulations compels hospital systems toward qualified suppliers with documented extractables profiles. The IRA manufacturing incentives stimulate domestic molding capacity expansion for active pharmaceutical ingredient containers. Greater Boston's biotech cluster generates concentrated demand for cryogenic shippers supporting cell therapy clinical trials.
Germany
Rhine-Main pharmaceutical manufacturing density anchors European demand for borosilicate glass vials and aluminum alloy containers. EMA's Medical Device Regulation tightens traceability mandates for reusable surgical instrument containers, accelerating fleet replacement cycles. Baden-Württemberg's medical technology corridor concentrates sterilization validation services for reusable container systems.
China
NMPA's updated pharmacopeial standards for container closure systems reshape material qualification protocols for domestic and export markets. Yangtze River Delta pharmaceutical manufacturing clusters drive demand for high-volume polypropylene injection-molded containers. Zhejiang province's medical plastics industry scales cyclic olefin polymer production for parenteral packaging applications.
India
CDSCO's convergence with international extractables testing protocols extends supplier qualification timelines for export-oriented manufacturers. Gujarat's pharmaceutical formulation hub concentrates demand for multi-dose vials and ampoules serving regulated markets. CDSCO's phased implementation of track-and-trace requirements for medical devices accelerates serialization investments in container labeling.
Switzerland
Swissmedic's stringent leachables testing requirements for biologics packaging sustain premium positioning for inert glass and polymer systems. Basel's pharmaceutical headquarters cluster drives demand for validated cold chain containers supporting global distribution of temperature-sensitive therapeutics. The country's precision manufacturing base supplies high-integrity elastomeric closures for parenteral drug containment.
Medical Containers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Consolidation pressure concentrates among distributors managing hospital system consignment inventory, while material specialists defend position through regulatory qualification depth. Three archetypes dominate: integrated healthcare supply chain managers, cryogenic equipment network operators, and specialized polymer compounders. Strategic moves center on backward integration into medical-grade resin production and geographic expansion of sterilization service networks.
Among integrated supply chain operators, Cardinal Health and Thermo Fisher Scientific exemplify channel-control strategies that embed container management into broader service agreements. Becton Dickinson occupies a position within the safety-engineered containment tier, representing specialists that bundle physical containers with compliance infrastructure. These three anchors illustrate how competitive positioning stratifies across logistics integration depth versus product engineering intensity.
| Leading Market Players |
|---|
| Becton Dickinson |
| Bemis Manufacturing Company |
| Cardinal Health |
| Thermo Fisher Scientific |
| Daniels Health |
| Bondtech Corporation |
| Amcor Plc |
| Berry Global Group |
| Ardagh Group |
| Others |
Supply & Pricing Matrix
Rhine-Main freight corridors tie container logistics costs directly to borosilicate glass furnace concentration in Central Europe, amplifying price spreads between certified parenteral-grade and standard polymer alternatives as hospital systems consolidate procurement.
Pricing Analysis
Polypropylene resin contracts with propylene monomer indexation dominate transactional pricing for injection-molded containers. Three-tier pricing structure across premium, standard, and economy levels separates USP Class VI-certified glass from medical-grade polypropylene and commodity resin alternatives. Cost compression in standard polymer tiers is intensifying because propylene feedstock volatility transfers directly to converter margins. Ambulatory care clinics exhibit highest price sensitivity due to thin reimbursement margins, while cell therapy manufacturers accept premium positioning for validated cryogenic systems.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for borosilicate tubing sourcing. Production gravity centers on Central European furnace operations, Chinese injection-molding clusters, and Indian formulation hubs for multi-dose vials. Raw material supply draws from propylene monomer streams, pharmaceutical-grade silica sand, and bromobutyl elastomer compounding. Single-source vulnerability concentrates in Type I hydrolytic resistance glass certification. Distribution runs through health system GPO contracts, biopharma third-party logistics providers, and regional sterilization service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container fleet leasing and sensor-integrated validation services are expanding faster than hardware sales, reframing competitive advantage around recurring revenue attachment rather than unit shipment scale.
For Market Incumbents: Entrench hospital system relationships through vendor-managed inventory programs that transfer working capital burden upstream while embedding proprietary container formats into 503B outsourcing facility compliance workflows. Cardinal Health's consignment model illustrates channel control defensibility against emerging biopharma logistics entrants. Backward integration into medical-grade resin compounding secures margin protection against propylene monomer volatility. For New Entrants and Emerging Players: India's CDSCO-track-and-trace implementation lag creates white-space for serialization-integrated container labeling systems ahead of regulatory enforcement. Target Gujarat's pharmaceutical formulation hub with multi-dose vial formats pre-qualified for export markets. Partner with regional sterilization validation services to bypass multi-site FDA audit replication barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial packaging parents with underutilized medical-grade cleanroom assets and dormant FDA master files. Long-term viability hinges on regulatory qualification depth rather than manufacturing scale alone. Monitor EMA-USP extractables testing protocol convergence as inflection signal for material substitution investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Fast-Track | EMA's tightened traceability mandates accelerate fleet replacement revenue for notified body-approved reusable containers. |
| Cryogenic Shipper Network Expansion | Cell therapy clinical trial density in Greater Boston demands validated minus-one-hundred-fifty-degrees-Celsius distribution infrastructure. |
| Sensor-Integrated Container Development | FDA's container closure system guidance rewards active temperature monitoring with reduced stability testing burdens. |
| Consignment Inventory Integration | Health system GPO contracts now require upstream working capital absorption through embedded stock management. |
| Medical-Grade Resin Compounding | Specialized additive formulation capabilities concentrate among limited suppliers, creating captive supply opportunities. |
Research Methodology
Desk research of FDA 483 inspection observations, EMA certification databases, and USP pharmacopeial monographs preceded structured interviews with hospital GPO contract managers, biopharma supply chain directors, container sterilization validation specialists, and medical-grade polymer compounding technical leads. Secondary triangulation drew from customs trade data for borosilicate tubing imports, SEC 10-K filings of listed packaging converters, and CDSCO medical device registration disclosures. Bottom-up container unit demand estimates and top-down healthcare logistics spending allocations were reconciled across analysis approaches.
Assumptions held MDR compliance timelines and IRA domestic manufacturing incentive structures fixed while varying propylene monomer price trajectories and cell therapy approval velocities across modeling scenarios. Segmentation dimensions included material type, product format, end-user facility scale, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to hospital system procurement cycle data and biopharma clinical trial expansion rates. Cryogenic shipper utilization intensity and infusion bag ambulatory migration pace served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich industrial packaging conglomerates into medical-grade cleanroom capacity would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market