
 Europe Medical Devices Packaging Market | 2026-2036
Europe Medical Devices Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Devices Packaging Market Foresight
Hospital procurement dominance is collapsing as home care and outpatient clinics capture larger volume shares. Amcor Plc leverages its European converting footprint to serve decentralized delivery networks. Gerresheimer AG anchors glass-and-plastic hybrid formats for injectable devices moving into patient homes. West Pharmaceutical Services Inc. specializes in containment solutions that bridge institutional and self-administration use cases.
Europe medical devices packaging encompasses sterile barrier systems, primary containers, and secondary distribution formats engineered from polymer films, coated papers, aluminum laminates, and thermoformed plastics to maintain device sterility, integrity, and regulatory traceability through shelf life and clinical use. Blister packs and pre-formed trays lead unit volume due to their compatibility with high-speed automated filling lines and ethylene oxide sterilization cycles. Pouches constructed from Tyvek-film composites capture expanding share in low-temperature sterilization segments where breathable barriers outperform rigid alternatives. ISO 13485 and CE marking requirements concentrate margin pools with certified converters capable of validated manufacturing processes and batch-level documentation.
EMA coordination with notified bodies under the EU MDR extends conformity assessment timelines and elevates documentation burdens for packaging suppliers seeking device accessory classification. REACH and RoHS frameworks restrict phthalate plasticizers and heavy metal stabilizers in polymer formulations, forcing material substitutions across the supply base. Stakeholders must monitor notified body capacity bottlenecks and polymer feedstock certification gaps as dual regulatory pressures tighten market access thresholds.
Market Dynamics
The EU Medical Device Regulation is decomposing legacy supply relationships by forcing packaging converters to assume device-accessory liability, compressing the qualified supplier base and concentrating procurement power with ISO 13485-certified manufacturers capable of validated batch documentation.
Growth Catalysts
- Home care migration:Patient-administered injectables and continuous glucose monitors are pulling sterile barrier systems into domestic settings, expanding addressable volume beyond hospital procurement.
- REACH material compliance:Phthalate restrictions are accelerating adoption of bio-based polymer alternatives in flexible films and thermoformed trays.
- German precision clusters:Baden-Württemberg and Bavaria host concentrated converting capabilities that shorten development cycles for complex multi-layer laminates.
Market Restraints
- Notified body capacity:EMA-coordinated conformity assessment timelines have extended to 18-24 months, freezing new supplier qualification.
- Tyvek supply concentration:Single-source dependence on DuPont's Luxembourg facility creates vulnerability for breathable barrier segments.
- Ethylene oxide sterilization limits:Industrial emissions restrictions in the Netherlands and Belgium are compressing terminal sterilization capacity for porous packaging formats.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Lower labor costs and EU MDR regulatory equivalence position these markets for secondary packaging and kit assembly expansion.
- Pre-filled syringe growth:Biologic drug delivery formats are creating demand for nested container closure systems combining glass barrels with rigid needle shields.
- Digital traceability mandates:Unique Device Identification requirements are opening service revenue streams for serialized label integration and cloud-based batch records.
Industry Challenges
- Validation engineering scarcity:Qualified process engineers capable of IQ/OQ/PQ documentation for sterile barrier systems command premium compensation and extended recruitment timelines.
- Legacy ERP integration:Batch-level genealogy tracking required by MDR Article 10 conflicts with decades-old manufacturing execution systems at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Devices Packaging Market |
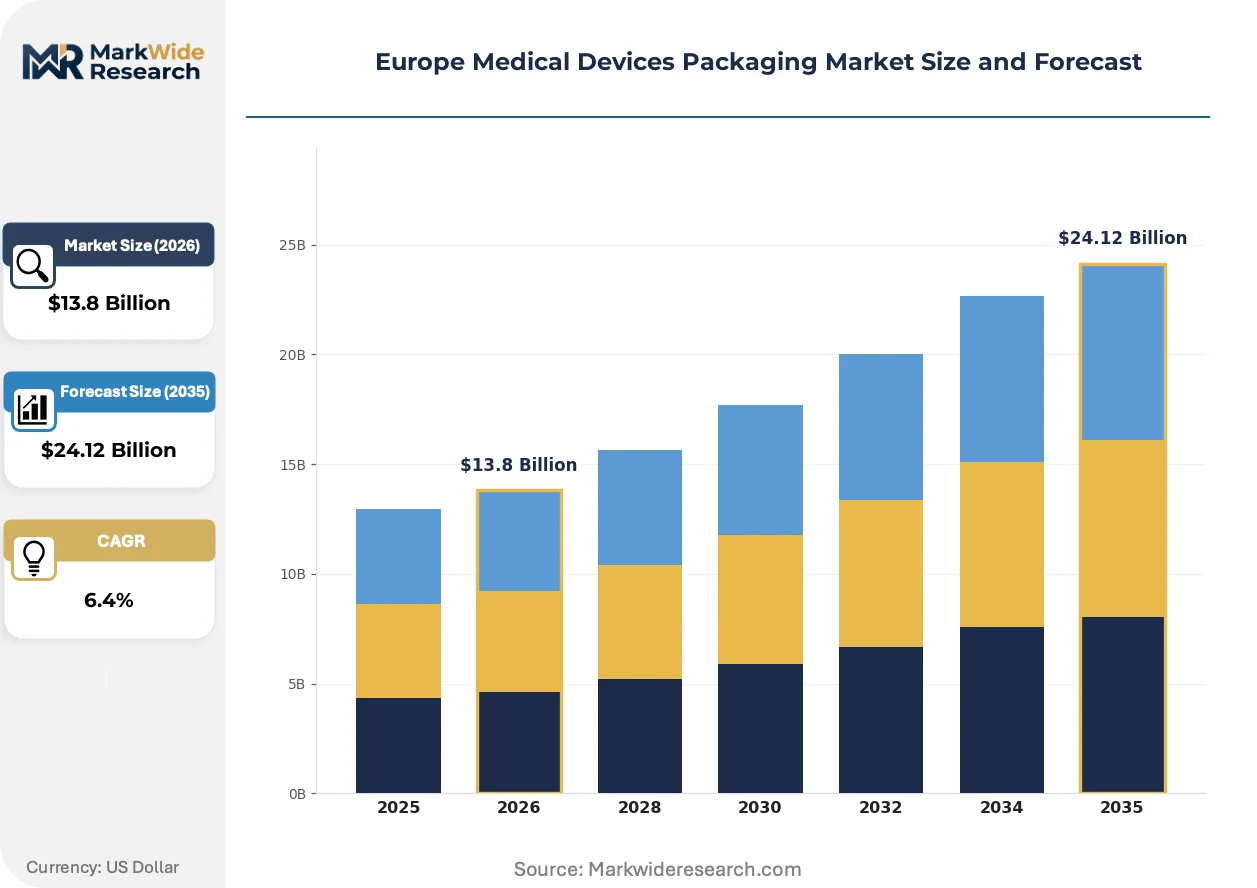
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Trays, Pouches, Labels Material: Plastic, Metal, Paper, Composite End User: Hospitals, Clinics, Home Care, Laboratories Certification: ISO 13485, CE Mark, FDA Approval, Others |
| Companies Covered | Amcor Plc, Berry Global Inc., Gerresheimer AG, DuPont de Nemours Inc., Constantia Flexibles Group GmbH, West Pharmaceutical Services Inc., Nelipak Corp., Sonoco Products Co., Röchling SE & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Devices Packaging Market Shifts & Advancements
Material science convergence with digital manufacturing is collapsing traditional boundaries between primary containment and secondary distribution formats, enabling functionally integrated packaging systems that reduce assembly steps and contamination exposure.
Tyvek-film composite laminates are decomposing conventional paper-film pouch architectures in low-temperature sterilization applications. Outpatient surgery centers and home infusion services are specifying these breathable barriers for hydrogen peroxide plasma cycles. The technology is decomposing rigid tray dominance in Class II device segments where flexibility and reduced cube size offset unit cost premiums.
EU MDR Article 117 accessory classification is forcing packaging suppliers to maintain technical documentation equivalent to device manufacturers. German notified bodies are interpreting this provision to require design dossiers for sterile barrier systems. Small converters in Italy and Spain are exiting the market rather than absorbing compliance infrastructure costs.
Hospital procurement consortia are consolidating vendor panels and demanding multi-year total cost of ownership contracts. France's RESAH and England's NHS Supply Chain are shifting from unit-price tenders to performance-based agreements incorporating sterilization validation and logistics integration. Southern European markets lag this transition, maintaining fragmented purchasing that favors local converters over pan-European suppliers.
Europe Medical Devices Packaging Market Segmentation
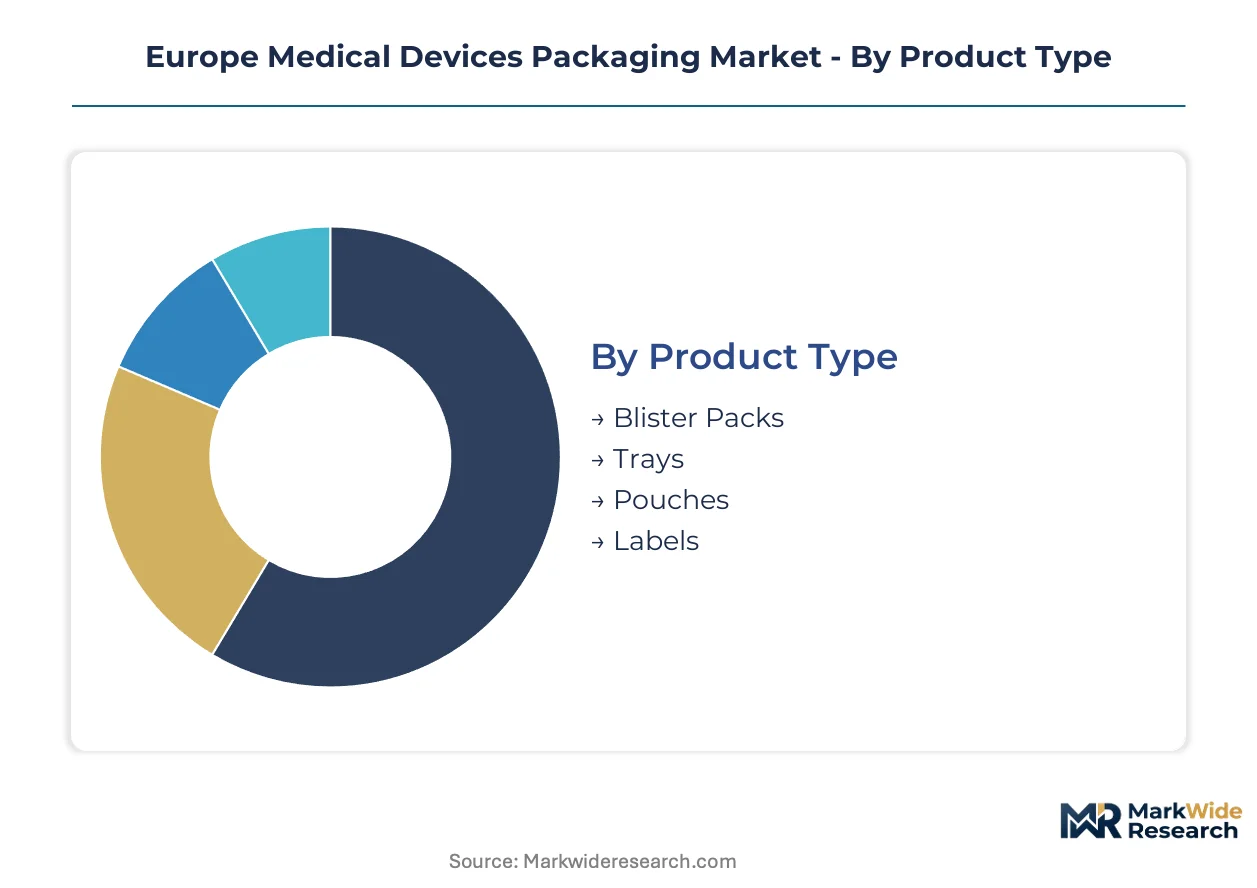
Packaging format selection determines sterilization compatibility and distribution economics across Europe's fragmented healthcare procurement landscape. Channel-specific requirements from German hospital consortia to Mediterranean home care networks create divergent specification patterns that reshape converter priorities.
Product Type:
Blister packs and trays flow through high-volume automated hospital supply chains, while pouches and specialized labels serve decentralized home care channels where manual handling predominates.
- Blister Packs:Thermoformed plastic cavities sealed with lidding films provide rigid protection for implantable devices and surgical instruments. German precision manufacturing clusters in Baden-Württemberg anchor regional supply for these high-throughput formats demanded by hospital procurement consortia.
- Trays:Pre-formed rigid containers engineered from PETG or HIPS polymers accommodate complex device geometries and automated filling lines. France's RESAH and England's NHS Supply Chain specify these formats for sterilization validation integration and logistics efficiency.
- Pouches:Tyvek-film composites enable breathable barriers for hydrogen peroxide plasma cycles.
- Labels:Serialized adhesive substrates integrate Unique Device Identification mandates for traceability.
Blister packs dominate installed base. Pouches are where expansion concentrates.
Material:
REACH compliance tiers separate premium-certified feedstocks from restricted formulations, concentrating margin pools with converters holding polymer certification documentation.
- Plastic:Multi-layer polymer films and thermoformed resins constitute the volume foundation, with bio-based alternatives displacing phthalate-plasticized formulations under ECHA restrictions. German and Benelux converters lead validated manufacturing for these compliant substrates.
- Paper:Coated and uncoated medical-grade papers serve breathable barrier applications and secondary packaging, though declining in primary sterile barrier share. Italian converters maintain specialized coating capabilities for these heritage formats.
- Metal:Aluminum laminates provide moisture and light protection for sensitive biologics.
- Composite:Hybrid structures combining polymer, foil, and paper layers optimize specific protection profiles.
Plastic commands volume leadership. Composite materials are climbing the fastest as functional integration demands intensify.
End User:
Procurement authority concentration varies dramatically across settings, with hospital consortia demanding multi-year contracts while home care channels prioritize flexibility and reduced cube size.
- Hospitals:Centralized sterilization departments and surgical suites require validated sterile barrier systems compatible with ethylene oxide and steam cycles. Procurement consortia in France, England, and Germany consolidate vendor panels around these high-reliability formats.
- Home Care:Patient-administered injectables and continuous glucose monitors pull packaging into domestic settings where simplicity and disposal safety predominate. This segment is gaining share fastest as chronic disease management decentralizes across Europe.
- Clinics:Outpatient surgery centers specify mid-volume formats balancing automation compatibility with space constraints.
- Laboratories:Diagnostic device packaging emphasizes contamination control and sample integrity.
Hospitals retain procurement scale dominance. Home care is where specification innovation concentrates.
Certification:
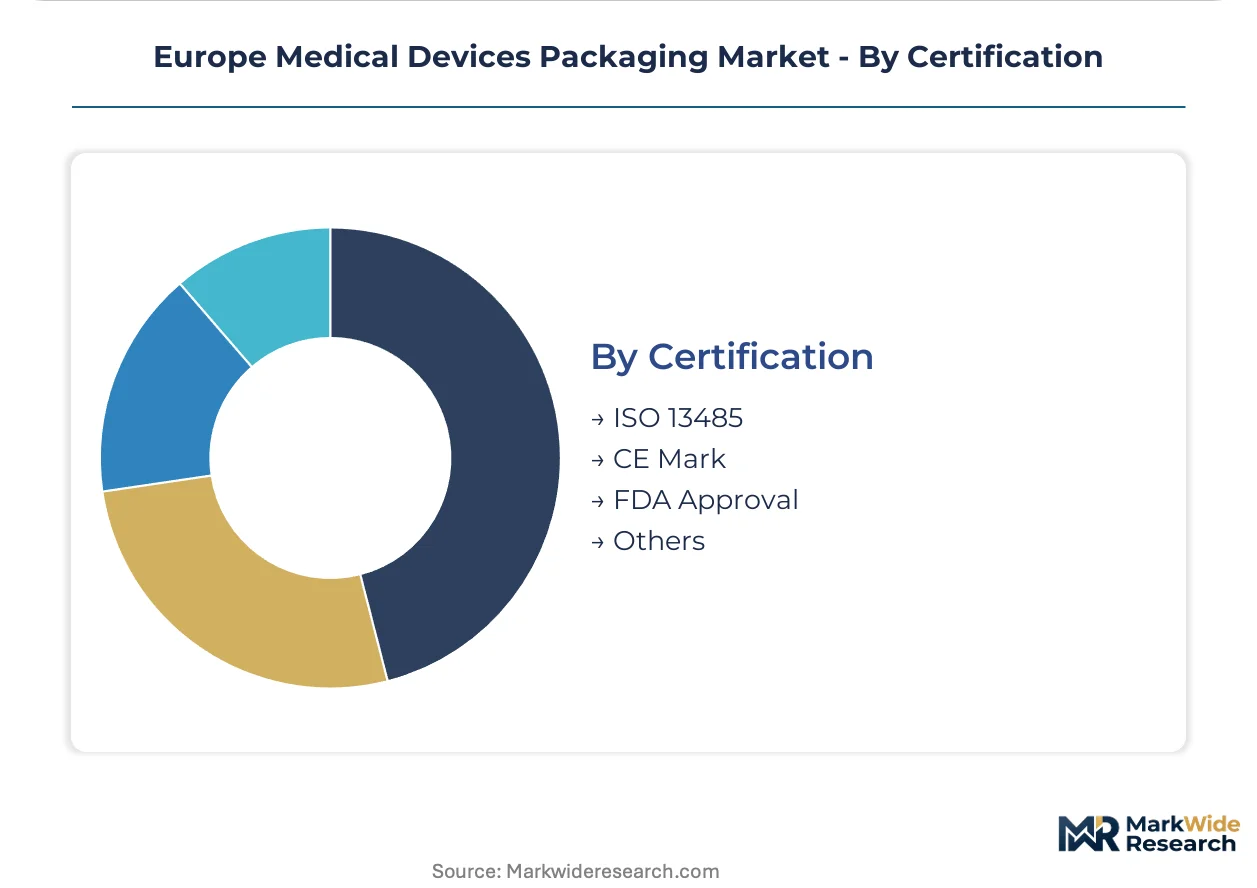
Regulatory tiering creates supplier qualification moats, with EU MDR accessory classification extending documentation burdens to packaging converters.
- ISO 13485:Quality management system certification for medical device suppliers constitutes the baseline market access credential. German notified bodies interpret EU MDR provisions to require validated batch documentation from certified converters.
- CE Mark:Conformity marking for device accessories enables free movement within the European Economic Area. Extended assessment timelines of 18-24 months under EMA coordination freeze new supplier qualification.
- FDA Approval:US regulatory alignment supports export-oriented European manufacturers.
- Others:National registrations and specialty certifications address specific member state requirements.
ISO 13485 dominates supplier qualification. CE Mark processes are where compliance investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's high-capacity freight rail network underwrites Germany's dominance in sterile barrier manufacturing, connecting Baden-Württemberg converting clusters to Rotterdam port distribution hubs.
Germany
Baden-Württemberg and Bavaria host Europe's densest concentration of ISO 13485-certified converters serving precision medical device manufacturers. The EU MDR's notified body capacity constraints hit hardest here, with TÜV SÜD and BSI Group processing queues extending sterilization validation timelines. Stuttgart's industrial belt anchors multi-layer laminate production for nested container closure systems.
France
RESAH procurement consortium consolidation is compressing vendor panels for hospital sterile barrier systems, favoring converters with validated ethylene oxide sterilization documentation. ANSM interprets EU MDR Article 117 to require design dossiers for primary packaging accessories. The Lyon-Grenoble corridor maintains specialized coating capabilities for breathable barrier films.
United Kingdom
NHS Supply Chain's shift to multi-year total cost of ownership contracts is displacing unit-price tendering for sterile barrier procurement. MHRA post-Brexit regulatory divergence creates parallel conformity assessment tracks for packaging suppliers serving both UK and EU markets. Cambridge-Oxford biotech corridor pulls demand for pre-filled syringe containment systems.
Italy
Lombardy and Emilia-Romagna converters face ECHA phthalate restriction compliance deadlines, accelerating bio-based polymer substitution in flexible film formulations. Small-scale heritage paper-coating specialists in Bologna's industrial district are exiting rather than absorbing EU MDR documentation infrastructure costs. Milan's logistics hub channels southern European distribution.
Poland
Lower labor costs and full EU MDR regulatory equivalence position Warsaw-Kraków manufacturing zones for secondary packaging and kit assembly expansion. EMA-coordinated notified body access avoids the 18-24 month qualification freezes blocking non-EU suppliers. Poznań's converting sector captures overflow volume from German capacity constraints.
Europe Medical Devices Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions, creating a tiered structure where scale-driven converters hold hospital procurement consortia relationships while mid-cap specialists defend niche sterilization formats. Three archetypes dominate: pan-European integrated converters with multi-country notified body registrations; regional specialists concentrating on single-format excellence; and material science innovators commercializing bio-based barrier substrates. Competitive moves concentrate on M&A for notified body registration assets and capacity expansion into Polish and Czech secondary packaging zones.
Among publicly traded packaging conglomerates, Amcor Plc and Berry Global Inc. occupy positions spanning multiple sterile barrier formats and European regulatory jurisdictions. Gerresheimer AG anchors the glass-and-plastic hybrid specialist tier, representing converters bridging pharmaceutical containment with device packaging requirements. These three exemplify how scale and regulatory breadth concentrate procurement power with hospital consortia and home care distributors.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Gerresheimer AG |
| DuPont de Nemours Inc. |
| Constantia Flexibles Group GmbH |
| West Pharmaceutical Services Inc. |
| Nelipak Corp. |
| Sonoco Products Co. |
| Röchling SE & Co. KG |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month notified body qualification timelines compress converter margins while amplifying procurement power for ISO 13485-certified suppliers serving German hospital consortia. This lead-time band concentrates pricing leverage with established players capable of validated batch documentation under EU MDR Article 117.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates sterile barrier procurement. Premium tiers capture CE-marked accessory classifications with design dossiers, while standard tiers serve outpatient clinics with ISO 13485 baseline certification. Price differentiation hinges on sterilization validation depth and multi-year total cost of ownership contracting. Cost compression in economy tiers intensifies as Polish and Czech converters absorb overflow volume from German capacity constraints. Hospital procurement consortia in France and England exhibit lowest price sensitivity due to performance-based agreement structures, whereas Mediterranean home care distributors prioritize per-unit economics.
Supply Chain Analysis
Germany and the Benelux region anchor multi-layer laminate production for nested container closure systems, while Poland and the Czech Republic capture secondary packaging and kit assembly expansion. Raw material flows draw from DuPont's Luxembourg Tyvek facility, German polymer compounders, and Italian coated paper specialists. Single-source dependence on breathable barrier substrates creates vulnerability for hydrogen peroxide plasma sterilization segments. Distribution runs through Rhine-Alpine freight rail corridors connecting Baden-Württemberg converting clusters to Rotterdam port hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
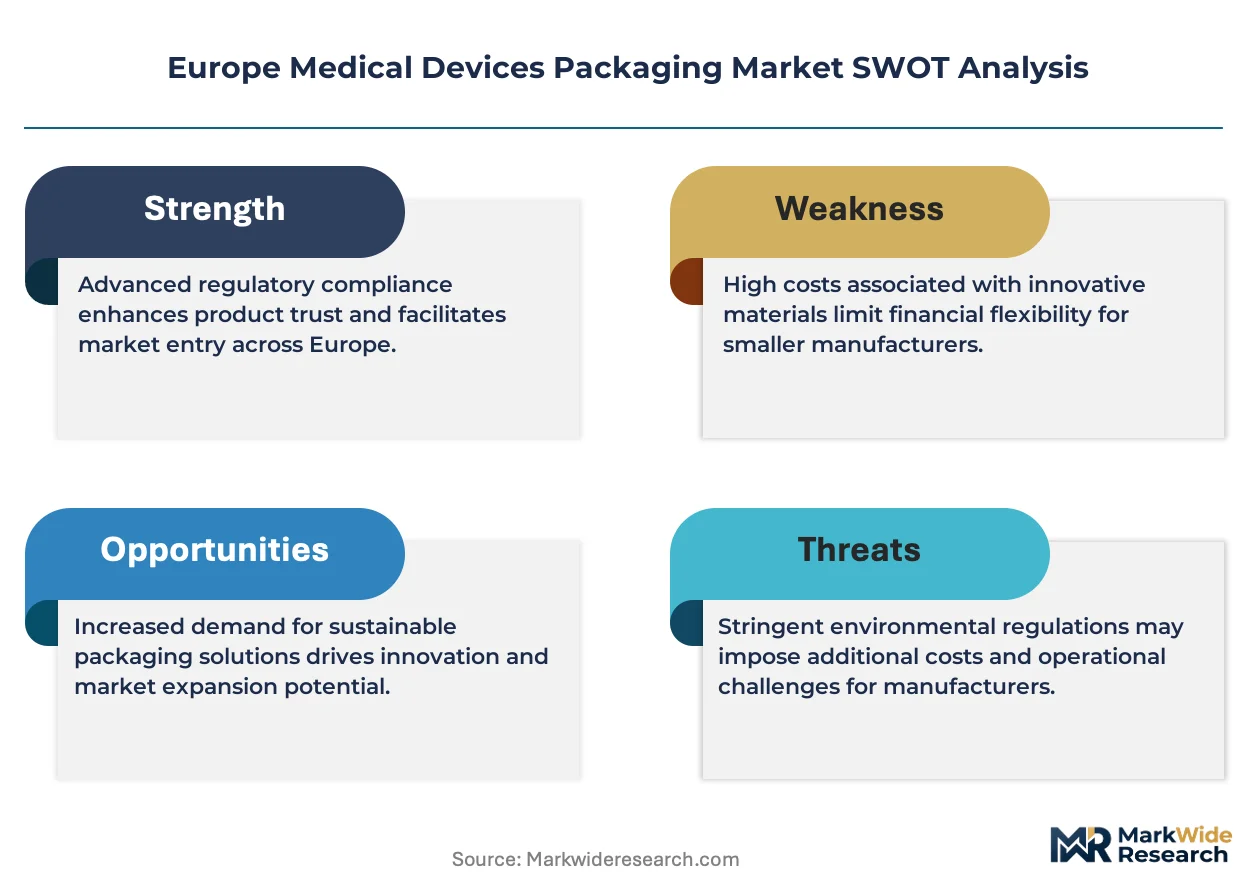
This market functions as a regulatory entrenchment story where EU MDR accessory classification erects compliance moats that freeze new supplier qualification for 18-24 months.
For Market Incumbents: Compound defensive positioning by acquiring notified body registration assets in Poland and the Czech Republic to capture overflow volume from German capacity constraints. Deepen backward integration into bio-based polymer feedstocks ahead of ECHA phthalate restriction deadlines. Channel control through multi-year NHS Supply Chain and RESAH performance agreements locks out mid-tier Italian and Spanish converters exiting under documentation burden. For New Entrants and Emerging Players: Lead with digital traceability service revenue streams for serialized label integration and cloud-based batch records, exploiting legacy ERP integration gaps at mid-tier converters. Target home care packaging segments where specification innovation concentrates and procurement authority fragments across decentralized networks. White-space opportunity sits with pre-filled syringe nested container closure systems serving Cambridge-Oxford biotech corridor demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterilization validation infrastructure as EU MDR design dossier requirements extend to primary packaging accessories. Five-to-ten-year viability favors acquisition targets holding pan-European notified body registrations with validated manufacturing execution systems. Signal to watch is notified body capacity expansion announcements from TÜV SÜD and BSI Group as inflection indicator for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 accessory classification extends conformity assessment to packaging converters. |
| Hospital System Partnership | RESAH and NHS Supply Chain multi-year contracts displace unit-price tendering for sterile barriers. |
| Backward Integration | Bio-based polymer feedstock control hedges ECHA phthalate restriction compliance costs. |
| Geographic Manufacturing Footprint | Polish and Czech secondary packaging zones capture overflow from German notified body queues. |
| Software Companion Development | Cloud-based batch records and serialized label integration open service revenue streams. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts managers, and sterile barrier validation specialists provided ongoing calibration against secondary sources including EMA MDR guidance documents, notified body assessment reports, hospital procurement databases, and REACH compliance filings. Primary interviews with German precision manufacturing clusters and Italian paper-coating specialists combined with customs records and SEC filings from listed packaging conglomerates. Bottom-up segment modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Consistency checks validated outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include packaging format, material compliance tier, end-user setting, and certification level. CAGRs derived from sterilization cycle demand curves, home care migration velocity, and regulatory implementation timelines. Industry-specific inputs encompassed ethylene oxide sterilization capacity constraints and Tyvek supply concentration metrics.
The analysis sits within stated boundaries; outcomes outside EU MDR implementation pace, notified body capacity expansion, or REACH enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding home care volume shift acceleration and polymer feedstock certification availability. Recalibration cycles align with material shifts in regulatory interpretation from German notified bodies and EMA coordination protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
North America Medical Devices Packaging Market