
 Asia Pacific Blood Glucose Test Strip Packaging Market | 2026-2036
Asia Pacific Blood Glucose Test Strip Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Blood Glucose Test Strip Packaging Market Outlook
Homecare patient volumes are pivoting toward self-monitoring protocols across the Asia Pacific region. Roche Diagnostics leverages its diagnostic heritage to sustain premium packaging specifications for hospital-grade strip shipments. Abbott Laboratories anchors large-format pouch production for retail pharmacy channels across Southeast Asia. Shijiazhuang Xinfuda Medical Packaging Co., Ltd. dominates domestic Chinese supply with in-house lamination and printing capabilities.
Blood glucose test strip packaging denotes engineered primary containers that maintain strip chemical stability against moisture, oxygen, and light ingress, typically employing aluminum-laminated films with desiccant integration and precision-sealed cavities. Blister pack formats lead volume due to individual-dose protection and compliance tracking utility, while pouch configurations represent the fastest-growing structural category as homecare bulk purchasing expands. Plastic and aluminum composite materials command the deepest margin pools because of their barrier performance and converter technical specialization.
China's NMPA enforces medical device packaging validation under GB standards, while India's CDSCO mandates strip stability documentation through shelf-life protocols. Australia's TGA and South Korea's MFDS impose comparable barrier-performance benchmarks that shape regional material selection and testing expenditure. Stakeholders must monitor evolving homecare reimbursement pathways and domestic substitution policies to calibrate capacity allocation across packaging formats.
Market Dynamics
Homecare patient volumes across the Asia Pacific region are pivoting toward self-monitoring protocols, forcing converters to reconfigure packaging formats for retail pharmacy distribution rather than hospital-centric supply chains.
Growth Catalysts
- Domestic manufacturing expansion:China's NMPA streamlined medical device packaging registration pathways, accelerating local strip production capacity additions in Jiangsu and Zhejiang provinces.
- Barrier-grade material mandates:India's CDSCO tightened shelf-life documentation requirements, compelling converters to adopt aluminum-laminated films with integrated desiccant systems.
- Self-monitoring protocols:Patient-managed diabetes care outside clinical settings is generating bulk pouch demand for multi-strip retail packs across Southeast Asian pharmacy channels.
Market Restraints
- Aluminum price volatility:Primary aluminum input costs fluctuate with energy pricing in Chinese smelter regions, compressing converter margins on barrier-grade laminates.
- Domestic supply concentration:Chinese converter capacity clusters in Shijiazhuang and Dongguan corridors, creating geographic single-point vulnerability for regional strip manufacturers.
- Desiccant integration complexity:Precision-sealed cavity requirements for strip chemical stability demand specialized heat-sealing equipment that limits converter entry.
Strategic Opportunities
- Vietnam and Indonesia penetration:Underdeveloped domestic packaging infrastructure in these markets creates first-mover openings for regional converters with barrier-film expertise.
- Retail pharmacy channel expansion:Direct-to-consumer strip sales through e-pharmacy platforms are bypassing traditional hospital procurement, enabling format innovation.
- South Korea MFDS alignment:Harmonized barrier-performance benchmarks with China's GB standards reduce dual-certification burdens for cross-border suppliers.
Industry Challenges
- Specialized heat-sealing technician scarcity:Precision cavity sealing for desiccant-integrated pouches requires skills concentrated in Japanese and Taiwanese converter workforces.
- Validation timeline compression:Australia's TGA stability documentation requirements extend product launch cycles for new laminate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Blood Glucose Test Strip Packaging Market |
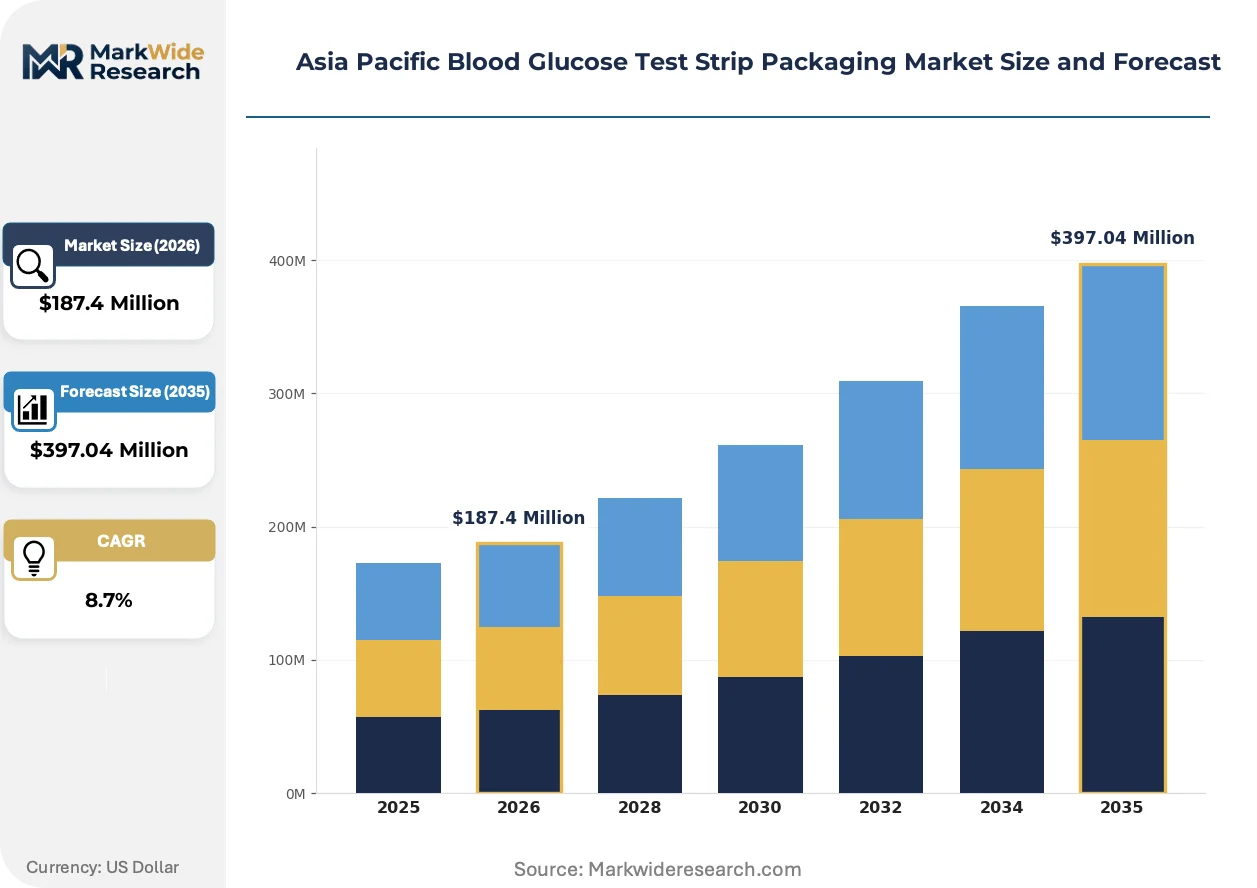
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Pack, Bottle, Pouch, Vial Material: Plastic, Aluminum, Cardboard, Composite End User: Hospitals, Clinics, Homecare, Laboratories Distribution Channel: Online Retail, Pharmacy, Direct Sales, Wholesaler |
| Companies Covered | Roche Diagnostics, Lifescan Inc., Shijiazhuang Xinfuda Medical Packaging Co., Ltd., Trividia Health, I-Sens Inc., Procurenet Limited, Abbott Laboratories, HMD, ARKRAY, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Blood Glucose Test Strip Packaging Market Strategic Shifts
Active material science advancement and regulatory harmonization are compressing traditional packaging development cycles while opening format diversification pathways for Asia Pacific converters.
Aluminum-laminated films with embedded desiccant layers are overtaking conventional plastic mono-materials in premium strip applications. Hospital-grade shipments in Japan and South Korea now specify these constructions exclusively. The technology is overtaking legacy barrier solutions by enabling 24-month shelf-life claims that satisfy MFDS and TGA stability protocols.
China's NMPA is enforcing GB standard medical device packaging validation with expanded scope for primary container integrity testing. Converter testing expenditure has risen proportionally. Domestic Chinese strip manufacturers are responding by consolidating supplier relationships with vertically integrated laminate producers.
Retail pharmacy procurement patterns now favor multi-strip pouch formats over individual blister units for homecare bulk purchasing. E-pharmacy platforms in India and Southeast Asia are displacing traditional distributor networks. This shift concentrates most visibly in China's tier-2 and tier-3 cities where direct-to-patient delivery infrastructure has matured fastest.
Asia Pacific Blood Glucose Test Strip Packaging Market Segmentation
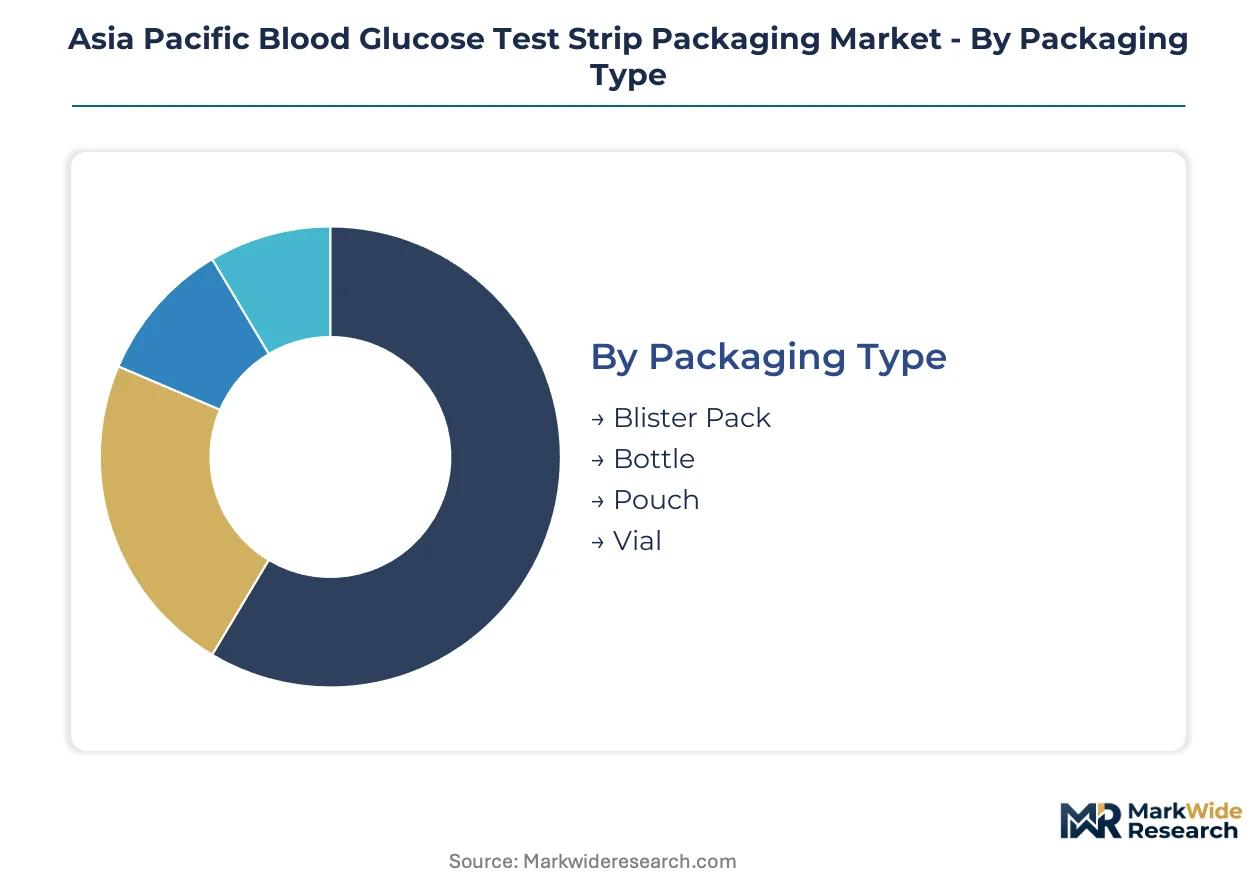
Packaging format and material selection in Asia Pacific blood glucose test strip markets directly determines shelf-life performance and regulatory compliance. Segmentation patterns reveal where converter investment flows and which specifications command premium positioning across hospital, retail, and direct-to-patient channels.
Packaging Type:
Volume concentration favors individual-dose formats, while bulk configurations capture expanding homecare procurement.
- Blister Pack:Aluminum-laminated cavities with precision heat-sealing provide moisture and oxygen barriers for single-strip dispensing. Hospital procurement across Japan and South Korea specifies this format exclusively for compliance tracking and contamination control.
- Pouch:Multi-strip flexible containers with integrated desiccant layers enable retail pharmacy bulk sales and e-pharmacy direct delivery. Homecare expansion in China's tier-2 cities and India's metro corridors is accelerating format adoption fastest.
- Bottle:HDPE containers with desiccant caps serve high-volume clinical settings requiring rapid strip access.
- Vial:Glass or polymer tubes with rubber stoppers preserve chemical stability for laboratory reference standards.
Mature deployment sits with Blister Pack. Newer deployment is concentrated in Pouch.
Material:
Barrier performance tiers separate premium specifications from cost-optimized alternatives.
- Composite:Aluminum-plastic laminates with ethylene copolymer adhesive layers deliver the highest moisture vapor transmission rate protection. China's NMPA GB standard validation and India's CDSCO shelf-life documentation requirements mandate this construction for domestic strip manufacturers.
- Aluminum:Pure foil structures or heavy-gauge laminates serve temperature-sensitive shipments and extended distribution cycles. Australian TGA stability protocols and South Korean MFDS barrier benchmarks specify aluminum-dominant constructions for premium applications.
- Plastic:Mono-material PET or PP films compete on converter cost but sacrifice barrier duration.
- Cardboard:Secondary outer cartons with varnished surfaces provide structural protection and print branding real estate.
Converter margins peak with Composite. Volume manufacturing runs favor Plastic.
End User:
Channel requirements diverge sharply between institutional certification demands and retail convenience priorities.
- Homecare:Self-monitoring patients purchasing through pharmacy and e-pharmacy channels drive pouch format and multi-strip configuration demand. India's expanding reimbursement coverage for home glucose monitoring is redirecting strip volumes from clinic to retail channels.
- Hospitals:Centralized procurement departments specify blister packs with lot tracking and individual sterile presentation. Japan's METI pharmaceutical distribution standards and South Korean MFDS medical device traceability rules reinforce format lock-in.
- Clinics:Mixed procurement patterns balance cost sensitivity with regulatory minimums.
- Laboratories:Reference-grade stability requirements favor vial and specialized composite constructions.
Procurement standardization is deepest with Hospitals. Format experimentation is most active with Homecare.
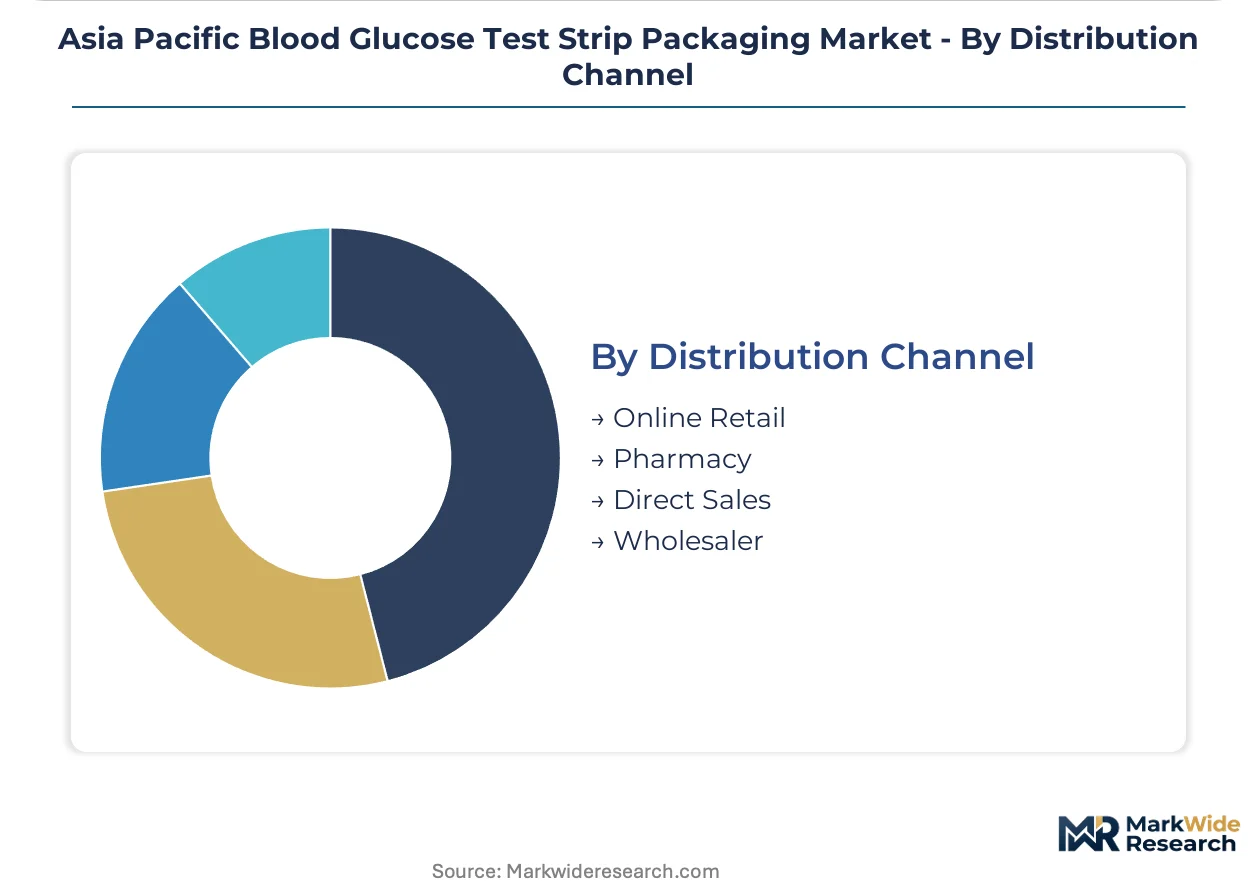
Distribution Channel:
Logistics configuration determines packaging durability specifications and unit economics.
- Pharmacy:Traditional retail networks across Southeast Asia and India handle multi-strip pouch formats with standard shelf-display requirements. Store-level inventory turnover shapes converter production batch sizing.
- Online Retail:E-pharmacy platforms in China and India demand enhanced crush resistance and moisture protection for last-mile delivery. Packaging must survive sorting facility mechanical handling and variable humidity exposure.
- Direct Sales:Manufacturer-to-patient subscription models enable customized format specification.
- Wholesaler:Bulk palletization requirements prioritize cube efficiency and stack stability.
Channel infrastructure investment is heaviest with Pharmacy. Disintermediation pressure is mounting fastest with Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of Asia Pacific's blood glucose test strip packaging capacity, yet consumption spreads across India, Japan, and Southeast Asian markets where domestic manufacturing remains underdeveloped. This production-consumption divide shapes converter location decisions and cross-border supply chain configurations throughout the region.
China
Domestic strip manufacturers in Jiangsu and Zhejiang provinces are expanding capacity to serve both local brands and export markets. The NMPA's GB standard validation requirements for medical device packaging have intensified testing protocols, pushing converters toward vertically integrated laminate production. Shijiazhuang and Dongguan corridor clusters now dominate regional barrier-film supply.
India
Homecare glucose monitoring reimbursement expansion is redirecting strip volumes from clinic channels toward retail pharmacy and e-pharmacy distribution. CDSCO shelf-life documentation mandates compel converters to adopt aluminum-laminated films with integrated desiccant systems. Domestic packaging infrastructure concentrates in Maharashtra and Gujarat where medical device manufacturing zones have attracted converter investment.
Japan
Hospital procurement departments specify blister pack formats exclusively, reinforcing format lock-in through METI pharmaceutical distribution standards. Premium barrier-performance requirements align with MFDS benchmarks across the Sea of Japan, enabling cross-border supplier certification efficiency. Converter technical specialization clusters in the Kanto region around precision heat-sealing equipment capabilities.
South Korea
MFDS barrier-performance benchmarks for medical device packaging have harmonized with China's GB standards, reducing dual-certification burdens for laminate suppliers. Domestic strip manufacturers source primarily from local converters with captive desiccant integration capabilities. The Seoul Capital Area anchors both production and R&D concentration for active packaging materials.
Vietnam
Underdeveloped domestic packaging infrastructure creates first-mover openings for regional converters with barrier-film expertise as multinational strip brands establish local assembly operations. E-pharmacy platform growth in Ho Chi Minh City and Hanoi is accelerating direct-to-patient delivery infrastructure. Foreign converter joint ventures are targeting this gap between demand growth and local supply capability.
Asia Pacific Blood Glucose Test Strip Packaging Market Competitive Environment
Top-tier vendors anchor hospital-grade specifications, while mid-tier converters compete on retail pharmacy format flexibility. The vendor base stratifies across three tiers: multinational diagnostic heritage firms with captive packaging operations, regional laminate specialists with vertical integration, and emerging local converters serving domestic strip manufacturers. Strategic moves concentrate on backward integration into aluminum lamination and geographic expansion into underpenetrated Southeast Asian markets.
Among Asia Pacific-based fabricators, Shijiazhuang Xinfuda Medical Packaging Co., Ltd. exemplifies the vertically integrated regional specialist archetype with in-house lamination and printing capabilities. Roche Diagnostics and Abbott Laboratories occupy positions representing the multinational diagnostic heritage tier, leveraging established supply chain relationships across hospital and retail channels. These three anchors illustrate the competitive spectrum from domestic Chinese supply dominance to global brand-affiliated packaging specification control.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Lifescan Inc. |
| Shijiazhuang Xinfuda Medical Packaging Co., Ltd. |
| Trividia Health |
| I-Sens Inc. |
| Procurenet Limited |
| Abbott Laboratories |
| HMD |
| ARKRAY, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across China's Jiangsu and Zhejiang provinces anchor regional supply, translating captive lamination capabilities into pricing discipline that resists commodity erosion despite aluminum input volatility. Their ownership structure enables patient capital deployment for NMPA GB standard certification, creating tiered margin pools that separate validated suppliers from price-competitive plastic-film competitors serving India's CDSCO-mandated shelf-life documentation requirements.
Pricing Analysis
Margin tightening in standard-grade laminates reflects aluminum spot-price volatility from Chinese smelter energy-cost fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-validated composite constructions from plastic mono-materials and unvalidated imports. Homecare bulk-pouch buyers in India's e-pharmacy channels exhibit highest price sensitivity, while Japan's METI-compliant hospital procurement accepts premium blister-pack specifications with minimal negotiation.
Supply Chain Analysis
Aluminum-laminated film supply rests on Chinese converter clusters in Shijiazhuang and Dongguan corridors, with secondary concentration in Japan's Kanto region for precision heat-sealing equipment. Raw material dependencies span primary aluminum from Chinese smelters, ethylene copolymer adhesives from South Korean petrochemical producers, and desiccant substrates from Taiwanese specialty chemical manufacturers. Single-source vulnerability concentrates in precision cavity-sealing technician pools. Distribution runs through hospital procurement departments in Japan and South Korea, retail pharmacy networks across India and Southeast Asia, and direct-to-patient e-pharmacy platforms in China's tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
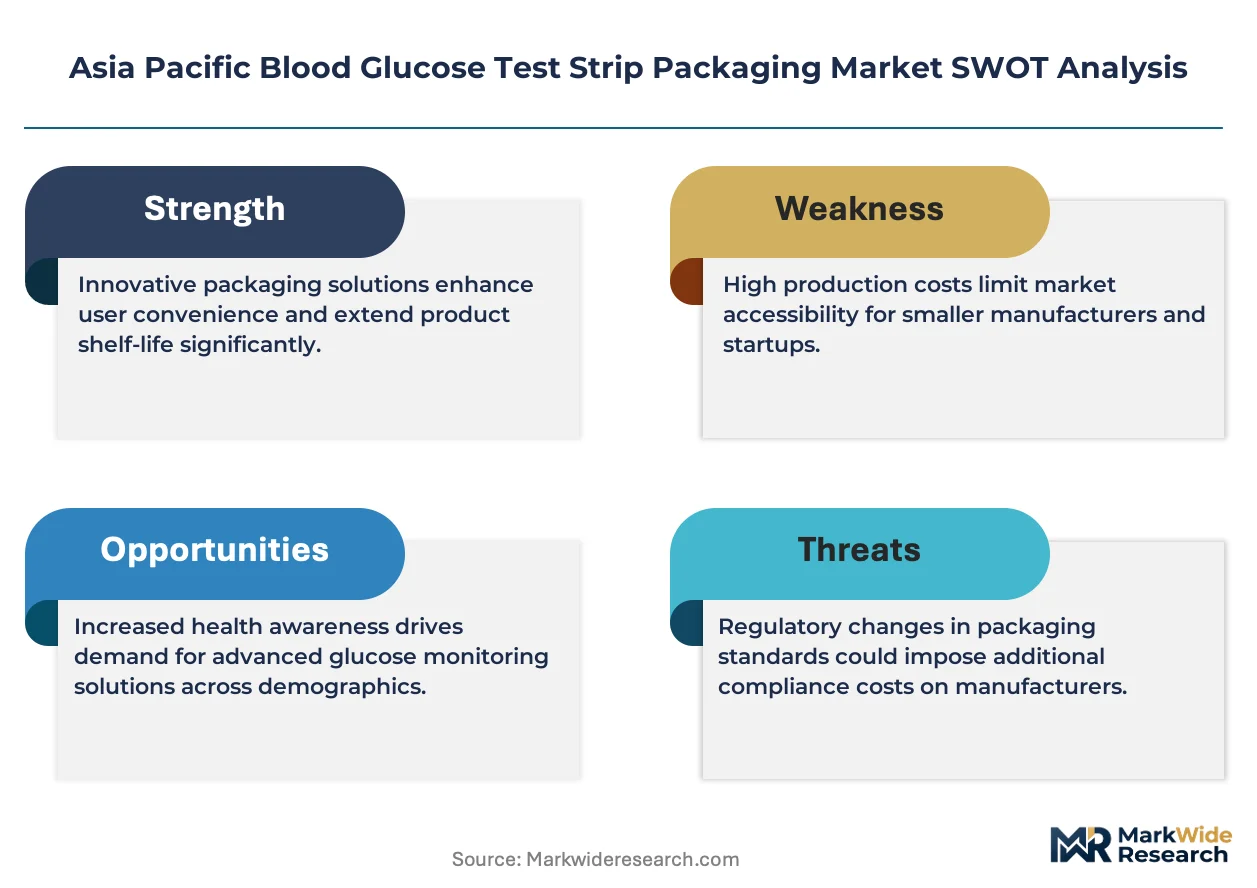
Active packaging material science advancement is displacing legacy plastic mono-materials across Asia Pacific blood glucose test strip applications, with aluminum-laminated composites embedding desiccant layers now specified for 24-month shelf-life claims.
For Market Incumbents: Deploy certification depth as a defensive moat by accelerating NMPA GB standard validation for expanded laminate formulations and securing exclusive supplier relationships with domestic Chinese strip manufacturers facing CDSCO documentation mandates. Channel control through direct hospital procurement lock-in with Japan's METI-compliant blister specifications protects against retail pharmacy format commoditization. For New Entrants and Emerging Players: Enter via Vietnam and Indonesia's underdeveloped domestic packaging infrastructure, where multinational strip brand assembly expansion outpaces local converter capability. Target barrier-film joint ventures with established desiccant integration partners as the most penetrable entry path, leveraging harmonized MFDS-GB standards to reduce dual-certification burdens for cross-border supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated Chinese mid-caps with captive lamination and printing capabilities in the Jiangsu-Zhejiang corridor, where NMPA validation timelines compress competitive response windows. Watch aluminum price stabilization signals and India's homecare reimbursement expansion as inflection indicators for capacity utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Lamination | Captive film production secures NMPA GB standard validation timelines against third-party converter queues. |
| Desiccant Integration Capability Buildout | In-house precision cavity sealing addresses technician scarcity concentrated in Japanese and Taiwanese workforces. |
| Vietnam-Indonesia Joint Venture Formation | First-mover positioning captures demand from multinational strip brands establishing local assembly operations. |
| E-Pharmacy Direct Distribution Partnership | Last-mile packaging specifications for China's tier-2 city delivery infrastructure bypass traditional wholesaler networks. |
| MFDS-TGA Harmonized Certification Investment | Dual-market validation efficiency reduces testing expenditure for premium hospital-grade blister shipments. |
Study Parameters
Regulatory filing databases, medical device packaging trade publications, and customs import-export records formed the secondary backbone, supplemented by primary interviews with converter operations managers, biomedical engineers at hospital purchasing committees, CDSCO regulatory affairs leads, and GPO contracts managers. Bottom-up triangulation across strip manufacturer procurement data and top-down validation against national diabetes prevalence statistics ensured cross-verified demand estimation.
Historical trendline analysis of packaging format adoption rates, material substitution patterns, and regulatory validation timelines informed the projection framework across the analysis window. Segmentation dimensions modeled include packaging type, material barrier-performance tier, end-user channel, and distribution logistics configuration. CAGRs derived from fitted growth curves applied to validated base-year estimates, with aluminum price indices and homecare reimbursement policy trajectories as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained aluminum price volatility or abrupt CDSCO documentation requirement changes. Forecasts reflect assumptions regarding NMPA enforcement consistency, MFDS-GB standard harmonization durability, and India's e-pharmacy infrastructure maturation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Global Medical Packaging Market