
 Ophthalmic Packaging Market | 2026-2036
Ophthalmic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Packaging Market Intelligence
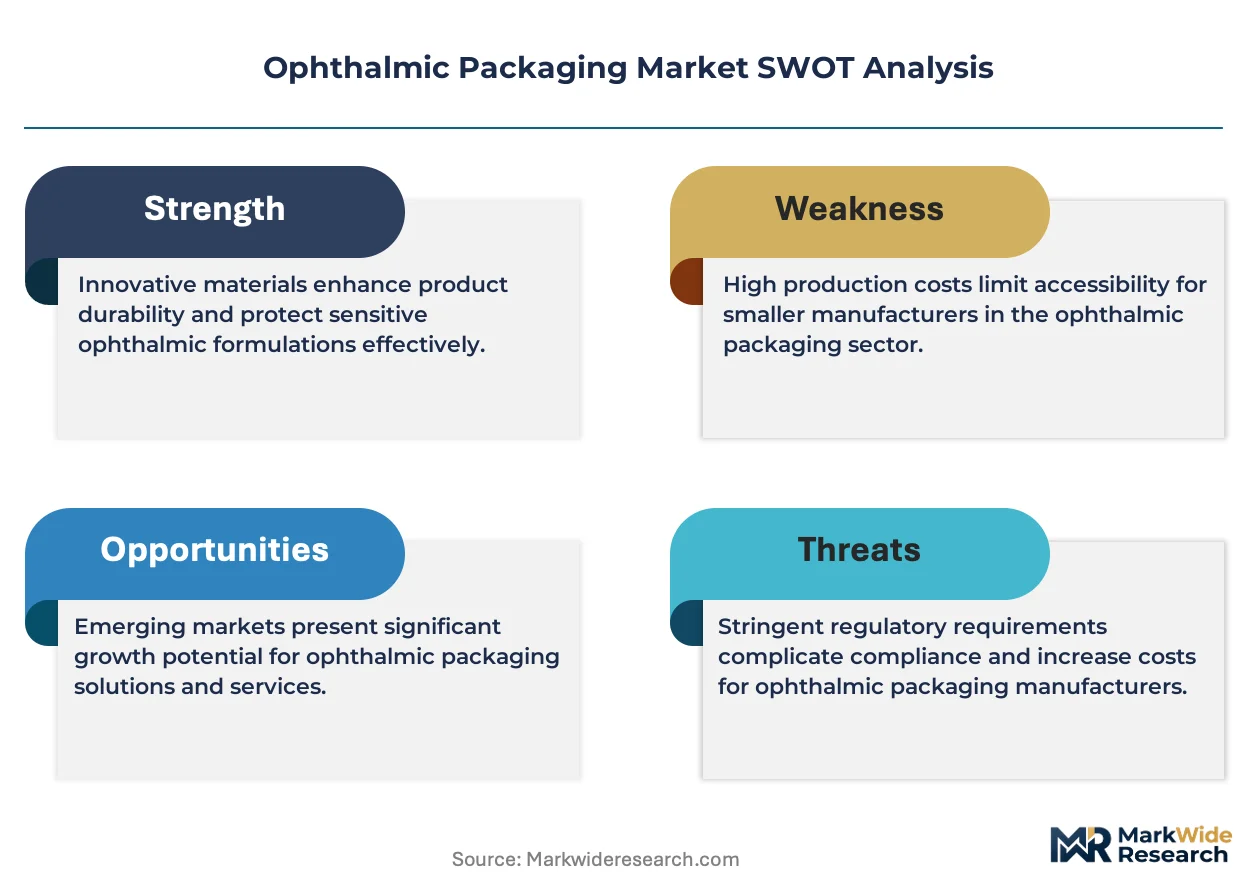
The gap between premium barrier packaging and commodity plastic bottles is realigning procurement priorities across ophthalmic supply chains. Gerresheimer AG leverages its glass-forming expertise to dominate high-value vial segments for preservative-free formulations. Amcor plc sustains broad geographic coverage through multi-material platforms spanning bottles, blisters, and pouches. Schott AG anchors the premium tier with borosilicate glass technology that meets tightened extractables standards.
Ophthalmic packaging encompasses sterile containers, closures, and delivery systems engineered to maintain drug stability, prevent microbial ingress, and enable precise dosing of eye drops, ointments, and intraocular preparations; barrier properties are specified in terms of oxygen transmission rates below 0.1 cc per square meter per day for sensitive biologics. Plastic bottles lead volume demand due to cost efficiency and compatibility with automated filling lines, while glass vials command margin pools in preservative-free and biologic segments where inert contact surfaces are non-negotiable. Primary packaging types capture the strictest regulatory scrutiny because drug-container interaction directly impacts patient safety, whereas secondary and tertiary layers concentrate innovation in patient adherence features and cold-chain logistics.
The FDA enforces Container Closure System guidance for ophthalmics through chemistry and microbiology review divisions, while EMA's MDR framework imposes stricter post-market surveillance on Class III drug-device combinations including eye drop dispensers. ISO 15378 certification for primary packaging materials is becoming a de facto market access requirement across European and North American supply chains. Stakeholders must monitor evolving pharmacopeial standards for silicone oil and tungsten residues as regulators link these contaminants to rising adverse event reports in intraocular applications.
Market Dynamics
Biologic eye therapies are fragmenting demand across polymer, glass, and hybrid container formats as preservative-free formulations force material upgrades throughout ophthalmic supply chains.
Growth Catalysts
- EMA MDR post-market surveillance:Stricter Class III device tracking elevates barrier packaging specifications for combination eye drop dispensers across European supply chains.
- Silicone oil purity mandates:Pharmacopeial upgrades for intraocular applications drive replacement cycles in vial and syringe component inventories.
- Compounding pharmacy expansion:United States specialty pharmacy networks scale unit-dose procurement for personalized ophthalmic preparations.
Market Restraints
- Borosilicate glass supply concentration:Premium vial feedstock depends on limited European and Asian furnace capacity, creating input bottlenecks for preservative-free segments.
- Extractables testing cost escalation:FDA Container Closure System guidance extends validation timelines and raises qualification expenses for polymer formulations.
- Metal substitute pressure:Polymer barrier films displace aluminum-laminate blisters in mid-tier dry eye applications, compressing margin pools for conventional foil suppliers.
Strategic Opportunities
- India CDSCO fast-track pathways:Accelerated approval frameworks for novel ophthalmic devices create first-mover packaging specification advantages.
- Cold-chain distribution partnerships:Biologic eye therapy launches require temperature-validated secondary packaging networks that incumbent logistics providers underserve.
- Connected dispenser convergence:Electronics integration with dose-capture sensors opens adherence-monitoring revenue streams beyond commodity container sales.
Industry Challenges
- ISO 15378 certification backlogs:Primary material qualification delays extend supplier onboarding timelines for pharmaceutical manufacturers.
- Tungsten residue elimination:Glass forming process reengineering demands capital redeployment as regulators link trace contaminants to intraocular adverse events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Packaging Market |
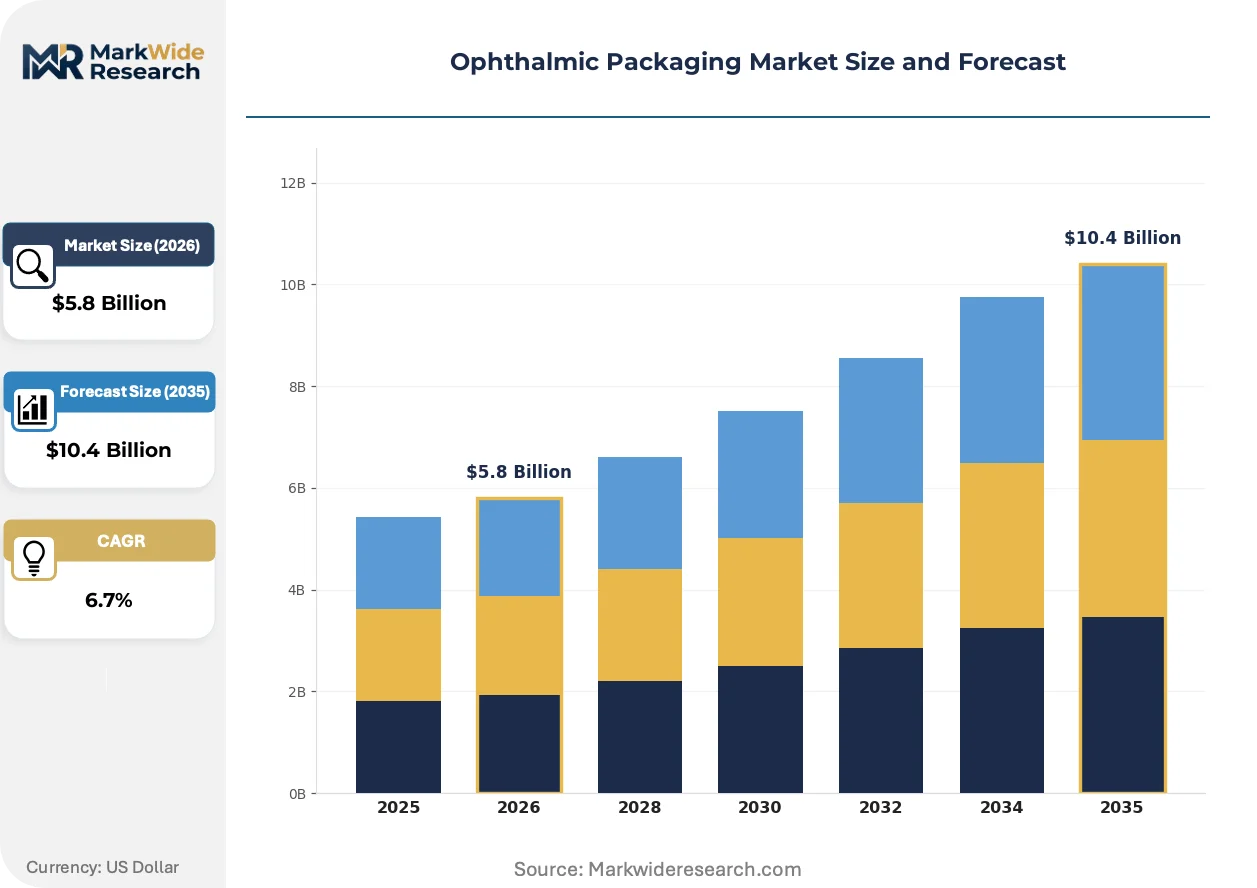
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Vials, Pouches, Blisters Material: Plastic, Glass, Aluminum, Cardboard End User: Hospitals, Clinics, Pharmacies, Research Labs Packaging Type: Primary, Secondary, Tertiary, Custom |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, AptarGroup, Inc., West Pharmaceutical Services, Inc., Berry Global Inc., Becton Dickinson, Nolato AB, Tekni-Plex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry requirements are compressing development cycles while fragmenting procurement specifications across ophthalmic packaging categories.
Cyclic olefin polymers are integrating into multi-dose bottle and vial applications where moisture barrier performance must match glass inertness. Specialty pharmaceutical manufacturers adopt these materials for biologic formulations requiring sub-0.1 cc oxygen transmission rates. The technology is integrating preservative-free and sensitive molecule segments previously reserved for borosilicate glass, compressing the premium-material cost gap.
REACH SVHC candidate list expansion is forcing reformulation of plasticizers and stabilizers in ophthalmic polymer compounds. ECHA scrutiny of phthalate alternatives accelerates migration testing protocols for European-market containers. Combination eye drop dispensers face the steepest compliance burden as device-component chemistry falls under both pharmaceutical and medical device substance restrictions.
Direct-to-specialist distribution is displacing wholesale pharmacy purchasing for high-value intraocular preparations. Ophthalmology clinic networks in the United States and Germany negotiate packaging specification authority previously held by hospital procurement departments. This channel compression elevates demand for patient-adherence features and unit-dose convenience formats that differentiate at the point of care.
Ophthalmic Packaging Market Segmentation
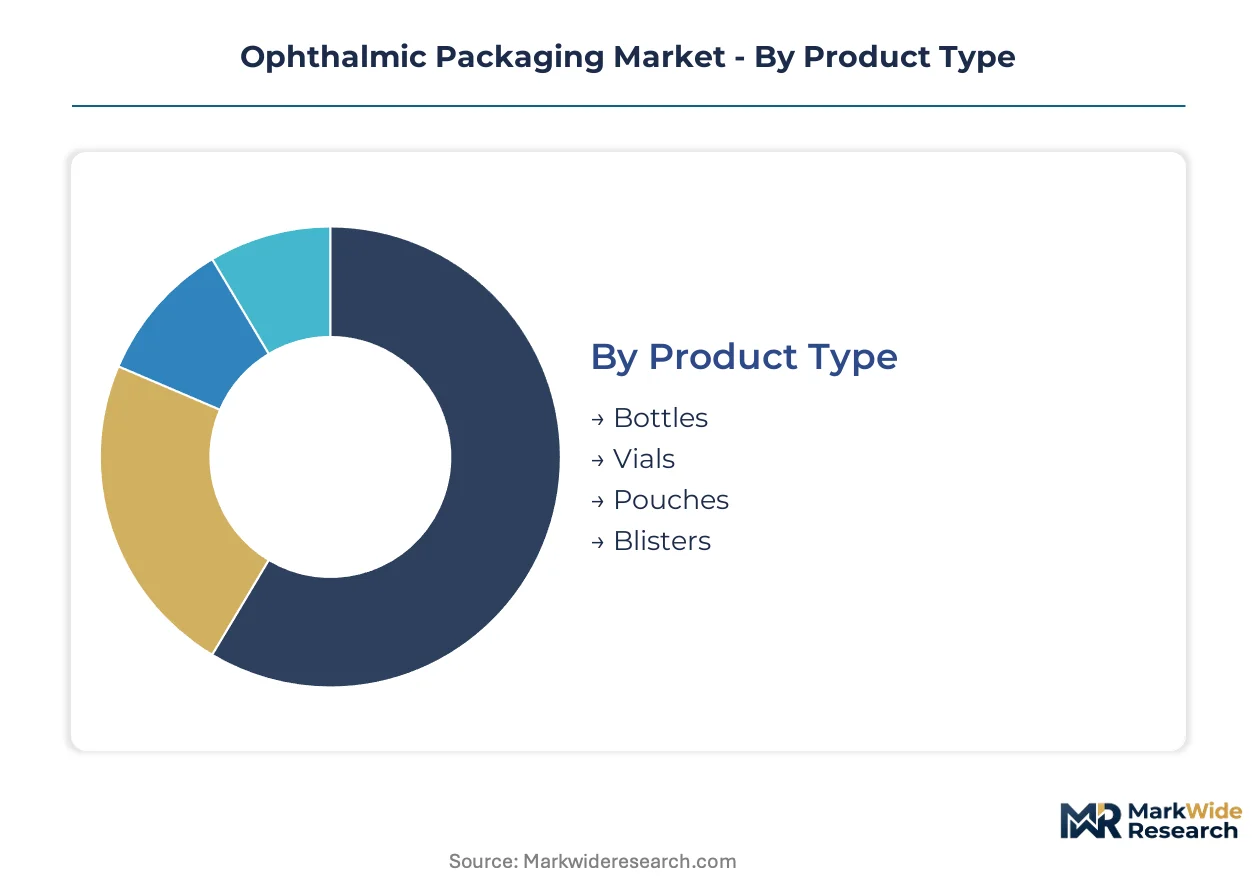
Ophthalmic packaging segmentation reflects divergent technical requirements across drug stability profiles, dosing precision needs, and regulatory exposure levels. Procurement patterns fragment sharply between high-volume commodity formats and premium barrier systems for biologic therapies.
Product Type:
Standalone containers dominate high-volume applications while integrated delivery systems embed dosing mechanisms directly into primary packaging.
- Bottles:Multi-dose plastic bottles incorporate precision dropper tips and tamper-evident closures for automated filling lines. Demand concentrates in United States retail pharmacy chains where cost-per-unit economics govern procurement of artificial tear and antihistamine formulations. FDA Container Closure System validation requirements extend development timelines for novel closure designs.
- Vials:Borosilicate and cyclic olefin polymer vials deliver sub-0.1 cc oxygen transmission rates for preservative-free biologics. German ophthalmology clinic networks specify these formats for intraocular injections where tungsten residue elimination has become mandatory. EMA MDR post-market surveillance elevates documentation burdens for combination vial-syringe systems.
- Pouches:Flexible foil-laminate pouches serve unit-dose dry eye therapies and travel-size formulations. Japanese drugstores favor these formats for over-the-counter portability.
- Blisters:Cold-form aluminum and polymer barrier blisters protect hygroscopic tablets and intraocular implants. Indian CDSCO fast-track pathways accelerate specification lock-in for novel device combinations.
Bottles lead volumes today; vials are gaining share fastest.
Material:
Cost tiers stratify sharply between commodity polymers and certified barrier substrates with extractables documentation.
- Plastic:Polyethylene, polypropylene, and cyclic olefin polymers balance cost efficiency with moisture barrier performance. REACH SVHC candidate list expansion forces reformulation of plasticizers in European-market compounds. United States compounding pharmacies scale polyethylene unit-dose procurement for personalized preparations.
- Glass:Borosilicate Type I glass maintains inert contact surfaces for sensitive biologics. Limited European and Asian furnace capacity creates input bottlenecks for preservative-free segments.
- Aluminum:Cold-form foil and laminate structures deliver absolute moisture barriers for hygroscopic formulations. Metal substitute pressure from polymer barrier films compresses margin pools in mid-tier dry eye applications.
- Cardboard:SBS and recycled fiberboard enable patient adherence features and cold-chain insulation in secondary packaging. Direct-to-specialist distribution elevates demand for printed dosing instructions and temperature indicators.
Plastic leads volumes today; glass is expanding most quickly.
End User:
Channel structure determines specification authority and convenience-feature requirements across the value chain.
- Hospitals:Central pharmacy operations procure sterile vials and syringes for surgical suites and inpatient administration. United States health system consolidation shifts volume toward group purchasing organizations with standardized barrier specifications.
- Clinics:Ophthalmology practice networks negotiate packaging specification authority previously held by hospital procurement. German clinic chains demand unit-dose formats with adherence-monitoring features at point of care.
- Pharmacies:Retail and specialty pharmacy channels drive multi-dose bottle volumes for chronic therapy refills. Indian retail pharmacy expansion creates specification fragmentation across state-level regulatory environments.
- Research Labs:Clinical trial supply chains require validated cold-chain secondary packaging and temperature-logging systems. Biologic eye therapy pipelines concentrate demand in United States and European investigational sites.
Pharmacies lead volumes today; clinics are climbing the fastest.
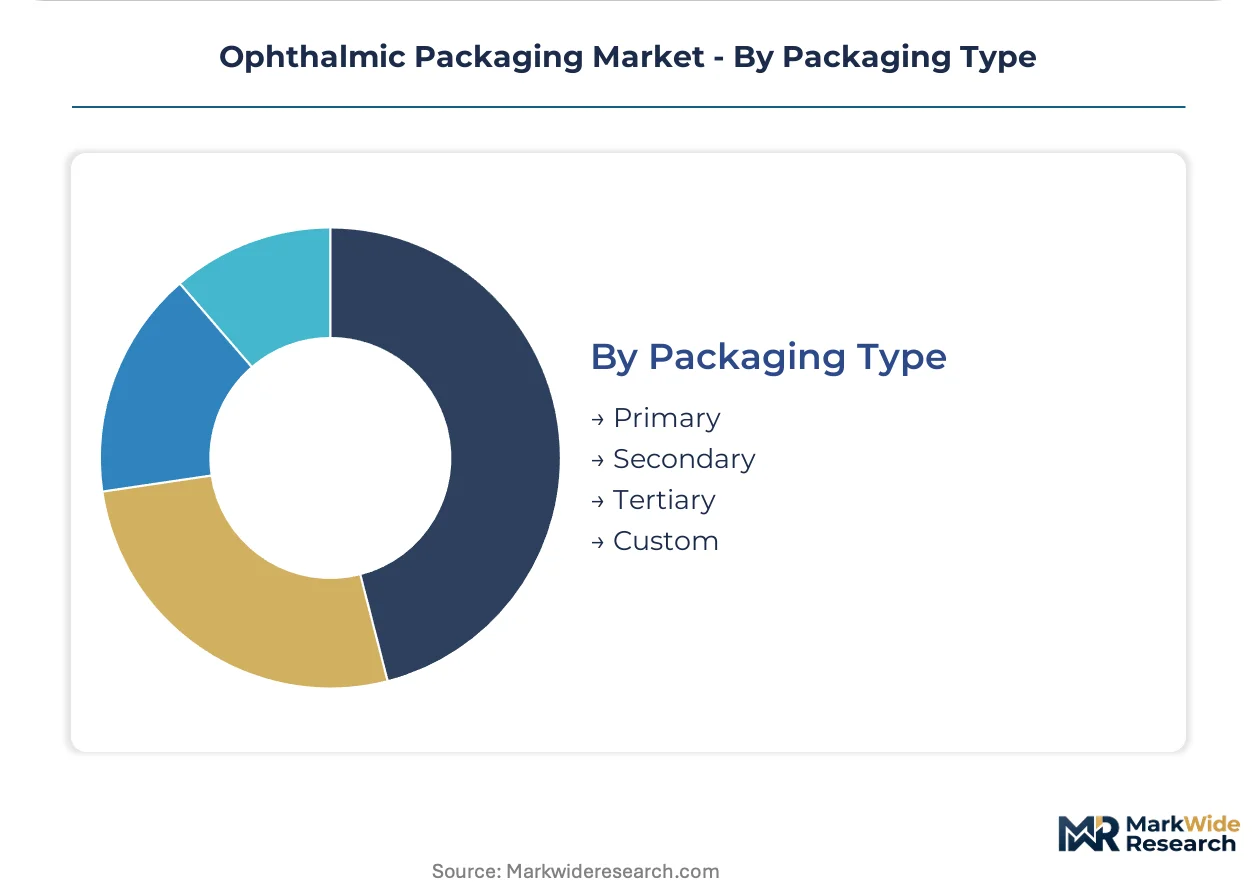
Packaging Type:
Regulatory scrutiny intensifies at each successive layer of the packaging hierarchy.
- Primary:Direct drug-contact containers face strictest FDA chemistry and microbiology review for extractables and leachables. ISO 15378 certification backlogs extend supplier onboarding timelines for pharmaceutical manufacturers.
- Secondary:Cartons, labels, and patient information leaflets concentrate innovation in adherence features and cold-chain logistics. Temperature-validated secondary packaging networks remain underserved by incumbent logistics providers.
- Tertiary:Shipping cases and pallets enable distribution efficiency and aggregation for high-volume therapies. E-commerce pharmacy growth elevates damage-resistance specifications for last-mile delivery.
- Custom:Patient-specific and clinical trial formats require flexible manufacturing runs with rapid specification changes. Connected dispenser convergence opens electronics integration opportunities beyond commodity container sales.
Primary packaging leads volumes today; custom formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and glass-forming technicians cluster in Germany, the United States, and Japan, anchoring premium barrier packaging development for ophthalmic biologics.
United States
Specialty pharmacy networks and compounding operations drive unit-dose procurement for personalized eye therapies. FDA Container Closure System guidance extends validation timelines for novel polymer formulations. Boston and Raleigh-Durham research corridors concentrate clinical trial packaging demand for biologic pipelines.
Germany
Ophthalmology clinic chains negotiate direct packaging specifications for preservative-free intraocular preparations. EMA MDR post-market surveillance elevates documentation burdens for combination vial-syringe systems. Mainz and Jena glass-forming centers supply borosilicate vials meeting tightened tungsten residue standards.
Japan
Drugstore chains favor portable pouch formats for over-the-counter dry eye therapies. PMDA pharmacopeial upgrades for silicone oil purity drive component replacement cycles. Osaka polymer processing hubs develop cyclic olefin materials matching glass barrier performance.
India
Retail pharmacy expansion creates specification fragmentation across state-level regulatory environments. CDSCO fast-track pathways for novel ophthalmic devices accelerate packaging specification lock-in. Ahmedabad and Hyderabad manufacturing clusters scale polyethylene unit-dose production for domestic and export markets.
China
Domestic biologic eye therapy launches concentrate demand for certified barrier substrates with extractables documentation. NMPA alignment with international pharmacopeial standards tightens polymer compound reformulation requirements. Suzhou and Shenzhen packaging technology parks integrate automated filling lines with multi-material platforms.
Ophthalmic Packaging Market Key Industry Players
Top-tier vendors anchor premium barrier segments, while mid-scale specialists occupy cost-efficient multi-dose formats. The vendor base stratifies across glass-forming heritage, polymer platform breadth, and device integration capability. Three archetypes dominate: integrated material-science conglomerates, precision glass specialists, and healthcare-focused packaging engineers. Capacity expansion in cyclic olefin polymer processing and strategic partnerships for cold-chain logistics represent the dominant competitive vectors.
Among German-based fabricators, Gerresheimer AG and Schott AG exemplify the precision-glass archetype with furnace-dependent supply positions. Amcor plc, an Australia-originated public limited company, occupies a position spanning multi-material platforms across bottles, blisters, and pouches. These three entities represent the tiered structure: heritage glass technology at the premium barrier extreme, polymer platform breadth at the volume tier, and integrated healthcare specialization bridging both.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| AptarGroup, Inc. |
| West Pharmaceutical Services, Inc. |
| Berry Global Inc. |
| Becton Dickinson |
| Nolato AB |
| Tekni-Plex, Inc. |
| Others |
Cost & Logistics Intelligence
Polyethylene and polypropylene resin indices cascade through ophthalmic packaging supply chains into three distinct pricing tiers, with certified barrier substrates commanding substantial premiums over commodity multi-dose bottles as extractables documentation requirements intensify.
Pricing Analysis
Bundled validation and certification services separate premium-tier suppliers from unbundled commodity producers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15378 certification status and tungsten-residue compliance grades. Cost compression in standard-tier plastic bottles intensifies as polymer barrier films displace aluminum-laminate blisters. Retail pharmacy chains exhibit highest price sensitivity; biologic manufacturers accept premium pricing for borosilicate vials with full extractables dossiers.
Supply Chain Analysis
Direct-to-specialist channels handle preservative-free biologic demand, while wholesale distribution serves high-volume artificial tear formulations. Supply concentrates in Germany, the United States, and Japan for precision glass-forming; China and India anchor polymer processing scale. Raw material flows draw from European and Asian borosilicate furnace capacity, cyclic olefin polymer resin from Japanese and Korean petrochemical complexes, and aluminum foil from Chinese rolling mills. Single-source vulnerability in premium glass feedstock creates qualification bottlenecks for preservative-free segments. Distribution runs through consolidated group purchasing organizations in United States health systems and direct clinic negotiations in German ophthalmology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic packaging offers margin-expansion pathways through cyclic olefin polymer adoption that narrows the cost gap with glass while preserving barrier performance for biologic therapies.
For Market Incumbents: Lock in long-term offtake agreements with European borosilicate furnace operators before capacity constraints worsen. Secure ISO 15378 certification ahead of supplier onboarding backlogs. Defensive consolidation around cold-chain logistics partnerships addresses the underserved temperature-validated secondary packaging networks that biologic launches require. For New Entrants and Emerging Players: E-commerce pharmacy platforms offer the lowest-friction entry route into unit-dose pouch formats for over-the-counter dry eye therapies. Target Indian retail pharmacy expansion where state-level regulatory fragmentation creates specification gaps that agile producers can exploit. White-space concentration in connected dispenser electronics integration opens adherence-monitoring revenue streams beyond commodity container sales. For Investors and Strategic Acquirers: Asymmetric upside sits with cyclic olefin polymer specialists that bridge glass-barrier performance at plastic cost structures. Five-to-ten-year viability favors producers with dual material-science and device-integration capabilities. Monitor FDA adverse event reporting trends for tungsten residue as an inflection signal for accelerated glass-forming process reengineering investment.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclic Olefin Polymer Capacity Expansion | Captures biologic packaging share from borosilicate glass with sub-0.1 cc oxygen transmission rates. |
| Cold-Chain Logistics Partnership | Addresses temperature-validated secondary packaging gaps for biologic eye therapy launches. |
| ISO 15378 Certification Investment | Accelerates supplier onboarding timelines as pharmaceutical manufacturers face qualification delays. |
| Connected Dispenser Development | Integrates dose-capture sensors for adherence-monitoring revenue beyond commodity containers. |
| Tungsten Residue Elimination Program | Preempts regulatory action linking trace contaminants to intraocular adverse event reports. |
Research Approach
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market cluster. Conversations with pharmaceutical packaging procurement managers, regulatory affairs specialists at ophthalmic drug manufacturers, glass-forming plant engineers, and polymer compound R&D directors combined with secondary validation from FDA Container Closure System guidance documents, EMA MDR implementation notices, pharmacopeial standards updates, and trade flow data. Bottom-up and top-down triangulation cross-checked volume estimates against capacity announcements and raw material consumption patterns.
Granularity-level modeling captured product type, material substrate, end-user channel, and packaging hierarchy dimensions at the country level. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Forecast inputs incorporated biologic eye therapy pipeline data, compounding pharmacy network expansion rates, and regulatory chemistry requirement evolution.
The model assumes a particular technology adoption path; alternative pathways for cyclic olefin polymer barrier performance would alter the outlook for glass substitution timelines. Forecasts reflect documented assumptions about EMA MDR enforcement intensity and FDA extractables testing protocol expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market