
 Surgical Instruments Packaging Market | 2026-2036
Surgical Instruments Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Instruments Packaging Market Analytics
A capital-intensity divergence between multinational film extruders and regional pouch converters is bifurcating competitive tiers in surgical instruments packaging. 3M leverages integrated medical-grade adhesive and film production to sustain premium positioning across sterile barrier systems. Amcor anchors global supply security through multi-continent converting footprints and hospital-direct distribution agreements. Gerresheimer AG specializes in rigid container and glass-composite formats for orthopedic and cardiac kit applications.
Surgical instruments packaging encompasses sterile barrier systems engineered to maintain device sterility from terminal sterilization through point-of-use, employing materials such as Tyvek, medical-grade papers, and multilayer polymer films with specified bacterial filtration efficiency and seal-strength thresholds. Pouches and blister packs lead volume due to compatibility with gamma and ethylene oxide sterilization cycles across general surgery and dental procedure kits. Rigid containers capture margin concentration in orthopedic and cardiac surgery applications where instrument value and reuse protocols demand higher-durability packaging. Biodegradable materials represent the fastest-growing material category as European healthcare procurement policies tighten environmental criteria.
FDA 21 CFR Part 820 quality system regulations and EU MDR Annex I general safety and performance requirements shape sterilization validation, seal integrity testing, and traceability documentation burdens for packaging suppliers. ISO 11607 standards govern material selection, design validation, and stability testing for terminally sterilized medical devices, creating compliance thresholds that filter regional competitors from hospital-approved vendor lists. Stakeholders must monitor evolving EPA and REACH restrictions on per- and polyfluoroalkyl substances that threaten incumbent high-performance coating chemistries in sterile barrier materials.
Market Dynamics
EU MDR sterilization validation requirements are compressing supplier margins while filtering regional competitors from hospital-approved vendor lists, creating a bifurcation between multinational film extruders with captive testing infrastructure and regional pouch converters dependent on third-party laboratories.
Growth Catalysts
- EU MDR Annex I requirements:General safety and performance mandates are elevating barrier-performance standards, forcing hospital systems to consolidate purchasing around validated sterile barrier suppliers.
- Ambulatory surgical center construction:United States outpatient facility expansion is generating sustained demand for gamma-compatible pouches and procedure-specific kit formats.
- Biodegradable polymer films:European healthcare procurement policies with tightened environmental criteria are accelerating material substitution away from conventional multilayer structures.
Market Restraints
- Medical-grade paper supply concentration:Tyvek and comparable high-purity pulp sources concentrate among three North American suppliers, exposing converters to input volatility.
- Per- and polyfluoroalkyl substance restrictions:EPA and REACH limitations on high-performance coating chemistries threaten incumbent barrier materials without drop-in replacements.
- Ethylene oxide sterilization capacity constraints:Terminal sterilization bottlenecks in United States and European contract facilities are extending lead times for packaging validation cycles.
Strategic Opportunities
- India surgical infrastructure expansion:CDSCO regulatory harmonization with ISO 11607 standards is opening hospital-direct distribution channels for validated sterile barrier systems.
- Reusable rigid container protocols:Orthopedic and cardiac surgery value-chain pressure is creating white space for durable glass-composite formats with integrated instrument tracking.
- Digital traceability mandates:EU MDR Unique Device Identification requirements are enabling premium pricing for packaging with embedded serialization and blockchain-verified sterilization records.
Industry Challenges
- ISO 11607-1 design validation expertise:Shortage of engineers with stability testing and accelerated aging protocol experience is extending product development timelines.
- Multi-continent converting footprint capex:Hospital-direct distribution agreements require redundant sterile barrier manufacturing capacity across three or more regulatory jurisdictions.
- Legacy ethylene oxide sterilization integration:Transitioning hospital systems from gamma to alternative sterilization modalities demands packaging material requalification without supply interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Instruments Packaging Market |
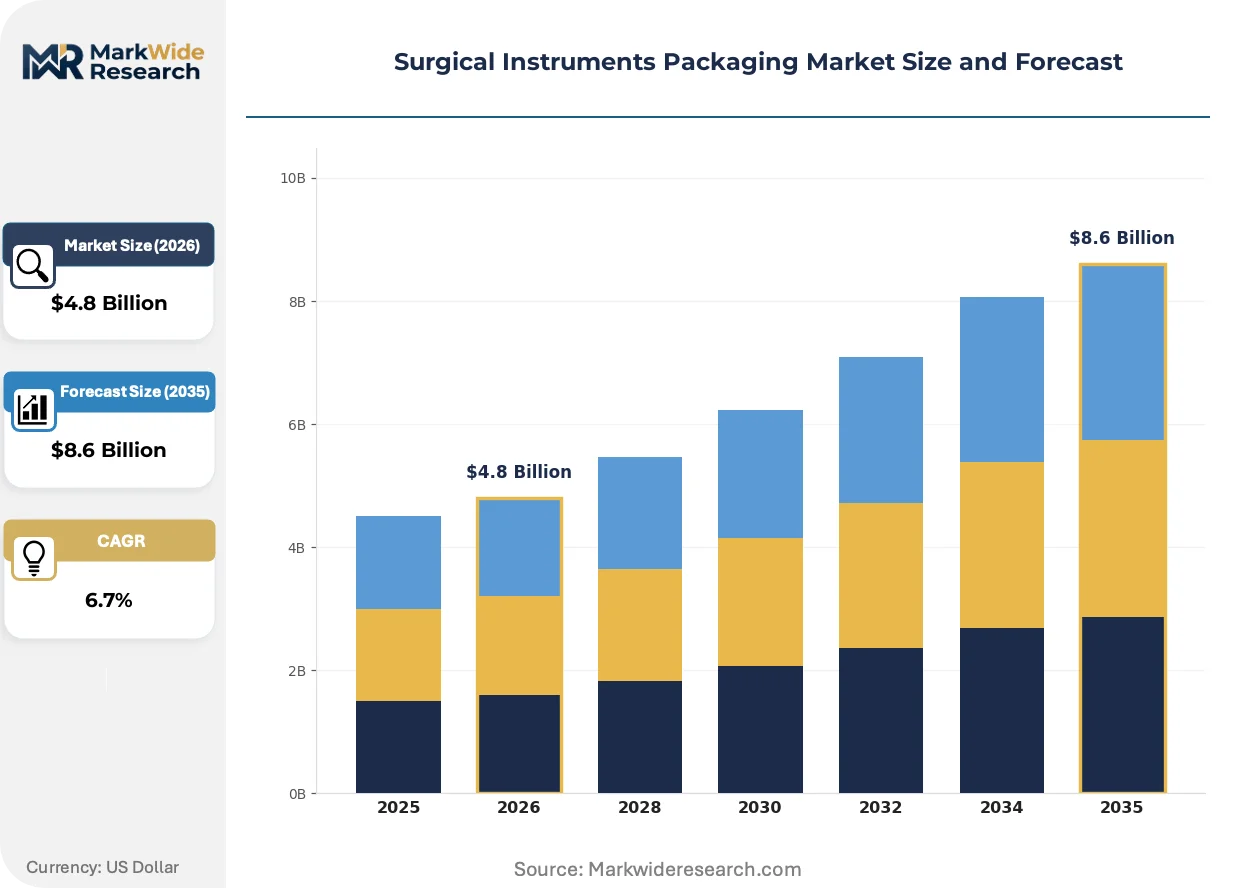
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Rigid Containers, Pouches, Trays Material: Plastic, Paper, Metal, Biodegradable Materials End User: Hospitals, Clinics, Laboratories, Surgical Centers Application: Orthopedic Surgery, Cardiac Surgery, Dental Procedures, General Surgery |
| Companies Covered | 3M, Amcor, SCHOTT AG, West Pharmaceutical Services, DuPont, Gerresheimer AG, Steripack Contract Manufacturing, Barger Packaging, North American Sterilization & Packaging Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Instruments Packaging Market Evolving Landscape
Material science advances and regulatory digitization are compressing traditional sterile barrier development cycles while elevating performance thresholds for bacterial filtration efficiency and seal integrity.
Tyvek-free synthetic nonwoven barriers are supplanting spunbonded olefin in general surgery pouch applications. German and French hospital procurement consortia are accelerating qualification timelines for these alternatives. The shift is compressing margins for incumbent medical-grade paper suppliers while enabling film extruders to capture value previously held by separate material tiers.
EU MDR Annex I general safety and performance requirements now mandate documented sterilization validation for every packaging configuration change. Industrial consequence includes mandatory investment in accelerated aging chambers and seal-strength testing equipment. Orthopedic kit suppliers in Switzerland and the Netherlands are responding by consolidating SKUs and standardizing pouch dimensions to amortize compliance costs.
Hospital system consolidation is concentrating purchasing authority among United States integrated delivery networks and European procurement alliances. Traditional medical distributor intermediaries are losing shelf space to direct manufacturer agreements with sterile processing departments. The pattern is most visible in cardiac surgery centers across Texas, Florida, and Bavaria, where instrument value justifies dedicated packaging engineering support.
Surgical Instruments Packaging Market Segmentation
Sterile barrier selection directly determines sterilization modality compatibility and regulatory validation burden. Packaging format, material substrate, and end-use environment each impose distinct performance thresholds that reshape supplier competitive positioning.
Packaging Type:
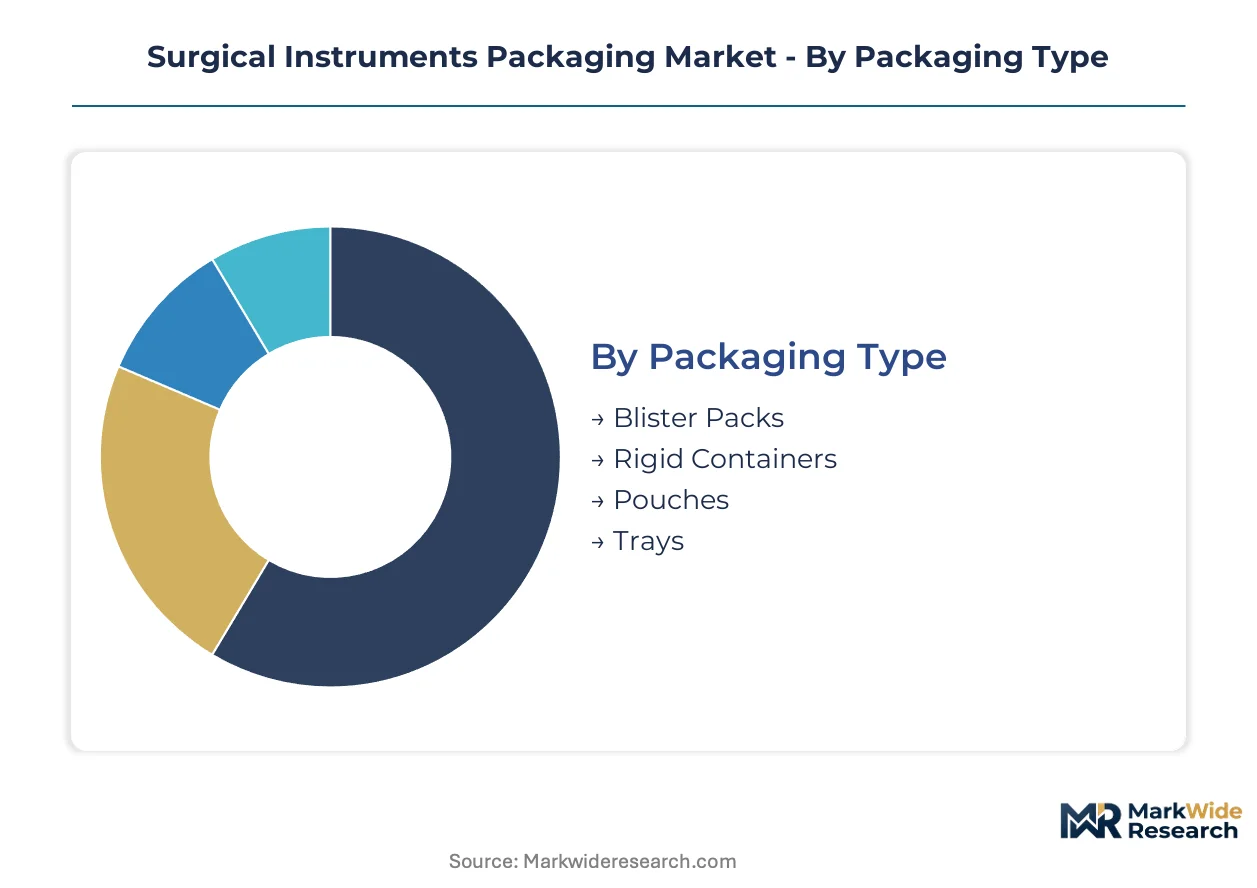
Pouches and blister packs dominate domestic consumption in the United States and Germany, while rigid containers command premium export volumes into Swiss and Dutch orthopedic centers.
- Pouches:Multilayer polymer or Tyvek-paper laminates with specified bacterial filtration efficiency and heat-seal strength. Demand concentrates in United States ambulatory surgical centers expanding gamma-compatible procedure kit volumes.
- Blister Packs:Thermoformed polymer cavities with lidding film barriers, engineered for ethylene oxide and steam sterilization cycles. German and French dental instrument manufacturers are accelerating qualification timelines for these formats.
- Rigid Containers:Glass-composite or anodized aluminum enclosures with integrated instrument tracking.
- Trays:Thermoformed polymer or molded fiber formats for bulk instrument organization.
Pouches command the established base. The steepest expansion runs through rigid containers.
Material:
Cost tiers separate commodity polymer films from validated medical-grade papers and emerging biodegradable alternatives.
- Plastic:Multilayer coextruded films combining polyethylene, polyester, and nylon barriers with specified moisture vapor transmission rates. United States pouch converters rely heavily on these substrates for gamma sterilization compatibility.
- Paper:Medical-grade kraft and synthetic nonwoven barriers including Tyvek and qualified alternatives. Swiss and Dutch hospital procurement consortia are compressing margins for incumbent suppliers while enabling film extruders to capture value.
- Metal:Anodized aluminum and stainless steel for reusable rigid container shells.
- Biodegradable Materials:Polylactic acid and polyhydroxyalkanoate films engineered for composting infrastructure.
Plastic substrates anchor volume throughput. Biodegradable materials are climbing the fastest as European environmental criteria tighten.
End User:
Customer type determines order scale, specification complexity, and direct-versus-distributor purchasing patterns.
- Hospitals:Integrated delivery networks with centralized sterile processing departments and SKU consolidation mandates. Texas and Florida cardiac surgery centers are concentrating purchasing authority through direct manufacturer agreements.
- Surgical Centers:Outpatient facilities with procedure-specific kit requirements and rapid inventory turnover. United States ambulatory construction is sustaining demand for standardized pouch dimensions.
- Clinics:Smaller-scale purchasers through medical distributor intermediaries.
- Laboratories:Research and diagnostic instrument packaging with lower validation burdens.
Hospitals command the established base. Surgical centers are gaining share fastest through outpatient procedure expansion.
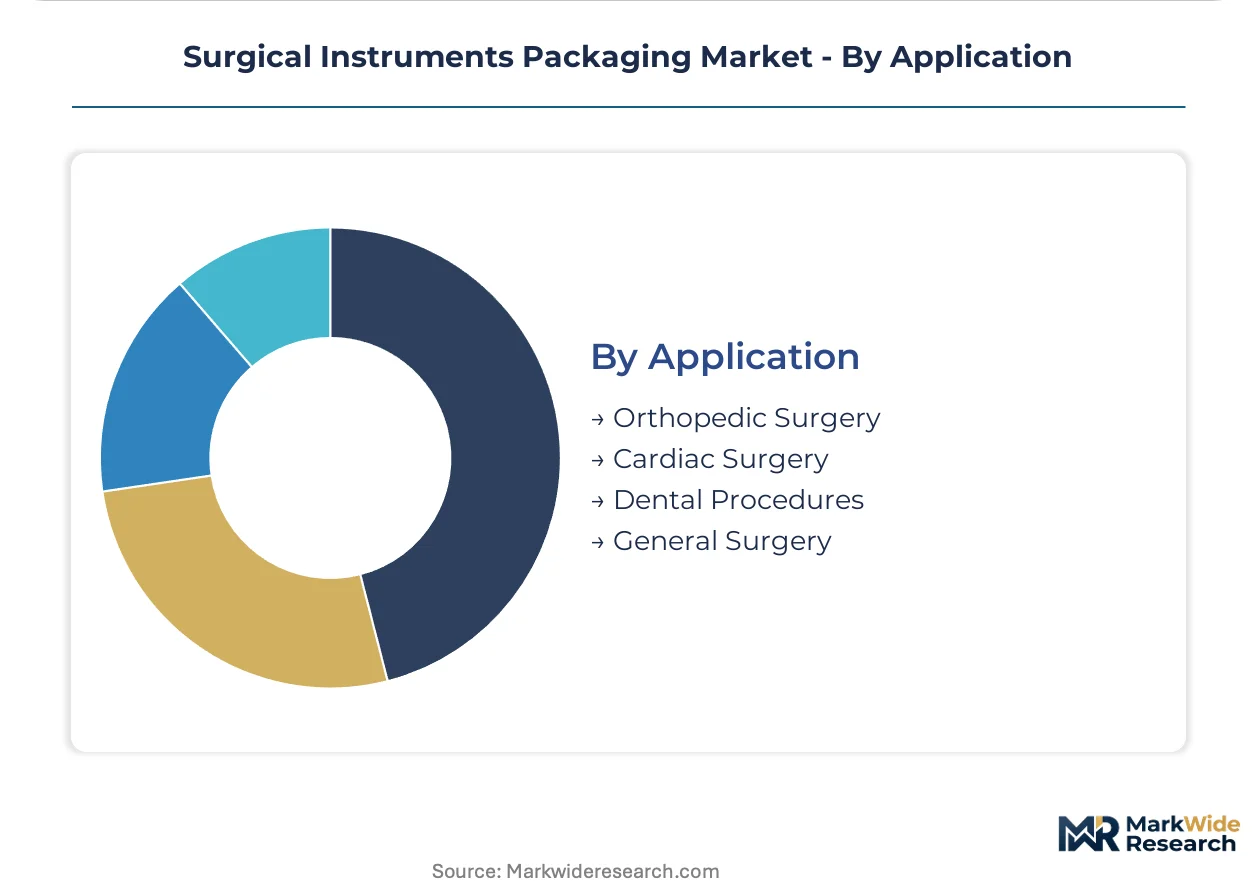
Application:
Volume concentration differs sharply from margin concentration across surgical specialties.
- General Surgery:High-volume disposable instrument kits driving standardized pouch formats. German and French hospital consortia are consolidating SKUs to amortize EU MDR compliance costs.
- Orthopedic Surgery:High-value reusable instruments demanding durable rigid containers with integrated tracking. Swiss and Bavarian centers justify dedicated packaging engineering support.
- Cardiac Surgery:Precision instrument sets with stringent barrier-performance requirements.
- Dental Procedures:Smaller-format pouches and blister packs for single-use instrument sterilization.
General surgery commands the established base. Orthopedic surgery shows the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium sterile barrier systems command pricing power in Swiss and German orthopedic centers while United States ambulatory surgical centers drive volume through standardized pouch procurement. This asymmetry reflects divergent regulatory validation burdens and reimbursement structures across developed healthcare systems.
United States
Ambulatory surgical center construction in Texas and Florida sustains demand for gamma-compatible pouches and procedure-specific kit formats. FDA 21 CFR Part 820 quality system regulations enforce sterilization validation and seal integrity documentation requirements. The Dallas-Fort Worth metroplex hosts concentrated sterile processing department consolidation among integrated delivery networks.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia are compressing margins for incumbent medical-grade paper suppliers while accelerating qualification timelines for Tyvek-free synthetic nonwovens. EU MDR Annex I general safety and performance requirements mandate documented sterilization validation for every packaging configuration change. The Stuttgart industrial corridor anchors multi-continent converting footprints serving hospital-direct distribution agreements.
Switzerland
Orthopedic and cardiac surgery centers in Zurich and Basel justify dedicated packaging engineering support for high-value reusable instrument protocols. Swissmedic medical device regulations align with EU MDR standards while maintaining distinct vigilance reporting requirements. The Basel-Land canton concentrates glass-composite rigid container manufacturing for instrument tracking integration.
India
CDSCO regulatory harmonization with ISO 11607 standards is opening hospital-direct distribution channels for validated sterile barrier systems in Maharashtra and Gujarat. Central Drugs Standard Control Organization medical device rules now recognize international stability testing protocols. The Mumbai-Pune pharmaceutical corridor attracts multinational film extruders establishing regional converting capacity.
Netherlands
European healthcare procurement policies with tightened environmental criteria are accelerating biodegradable polymer film substitution in Eindhoven and Rotterdam medical device clusters. REACH restrictions on per- and polyfluoroalkyl substances threaten incumbent high-performance coating chemistries without drop-in replacements. The Brainport Eindhoven region hosts concentrated orthopedic kit suppliers consolidating SKUs to amortize compliance costs.
Surgical Instruments Packaging Market Competitive Landscape
Concentration sits with multinational film extruders possessing captive testing infrastructure and multi-continent converting footprints. Regional pouch converters dependent on third-party laboratories face margin compression from EU MDR sterilization validation requirements. Three archetypes dominate: integrated material-science conglomerates with medical-grade adhesive and film production, global packaging converters with hospital-direct distribution agreements, and rigid container specialists serving orthopedic and cardiac kit applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers secure redundant manufacturing across regulatory jurisdictions.
Within the integrated material-science tier, 3M exemplifies premium positioning through in-house production of medical-grade adhesives and barrier films. Amcor occupies a position as a scale-driven converter with global footprint requirements for supply security. Gerresheimer AG represents the rigid container specialization archetype, anchoring durable format development for high-value instrument reuse protocols. These three companies collectively illustrate the bifurcation between multinational extruders with captive infrastructure and regional competitors filtered from hospital-approved vendor lists.
| Leading Market Players |
|---|
| 3M |
| Amcor |
| SCHOTT AG |
| West Pharmaceutical Services |
| DuPont |
| Gerresheimer AG |
| Steripack Contract Manufacturing |
| Barger Packaging |
| North American Sterilization & Packaging Company |
| Others |
Value Network & Pricing Analysis
Tyvek-free synthetic nonwoven substitution is compressing margins for incumbent medical-grade paper suppliers while enabling film extruders to capture value previously held by separate material tiers, simultaneously shifting supply geography toward German and French converting clusters and pressuring pricing economics across standard pouch formats.
Pricing Analysis
The customization-premium spread separates rigid container configurations for Swiss orthopedic centers from standardized gamma-compatible pouches procured by United States ambulatory surgical centers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 11607 certification grade, volume scale, and after-sales validation support. Cost compression in standard pouches is intensifying because EU MDR sterilization validation requirements force amortization across fewer SKUs. Surgical centers exhibit highest price sensitivity due to rapid inventory turnover and procedure-specific kit requirements, while cardiac surgery centers in Texas and Florida show lowest sensitivity given instrument value and dedicated packaging engineering support.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery for European hospital procurement consortia demanding accelerated qualification timelines. Medical-grade paper supply concentrates in the United States, Germany, and Canada, while multilayer polymer film extrusion anchors in the United States, Germany, and China. Raw material dependencies rest on high-purity pulp sources, medical-grade adhesives, and coextruded barrier films. Single-source vulnerability threatens Tyvek and comparable spunbonded olefin supply among three North American suppliers. Distribution runs through hospital-direct agreements with sterile processing departments, bypassing traditional medical distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as ambulatory surgical center construction in the United States sustains demand for gamma-compatible pouches through the outpatient procedure expansion cycle.
For Market Incumbents: Shield premium positioning by deepening in-house production of medical-grade adhesives and barrier films to offset Tyvek-free substitution pressure. Consolidate SKU portfolios to amortize EU MDR sterilization validation costs across standardized pouch dimensions. Capacity addition in Maharashtra and Gujarat secures redundant manufacturing across regulatory jurisdictions as CDSCO harmonization accelerates. For New Entrants and Emerging Players: Digital traceability integration represents a service-layer gap where incumbents under-serve EU MDR Unique Device Identification mandates for blockchain-verified sterilization records. White-space targets include biodegradable polymer films for Dutch and German procurement consortia and reusable rigid container protocols for Swiss orthopedic centers. Hospital-direct distribution partnerships in Texas and Florida cardiac surgery clusters offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional pouch converters possessing ISO 11607-1 design validation expertise but lacking multi-continent converting footprints. Long-term viability centers on acquisition targets with captive accelerated aging chambers and seal-strength testing infrastructure. The inflection signal to watch is CDSCO regulatory harmonization progress opening India hospital-direct channels.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Continent Converting Footprint Expansion | Redundant sterile barrier manufacturing across three regulatory jurisdictions secures hospital-direct distribution agreements. |
| EU MDR Sterilization Validation Infrastructure | Accelerated aging chambers and seal-strength testing equipment filter regional competitors from approved vendor lists. |
| Biodegradable Polymer Film Development | Polylactic acid and polyhydroxyalkanoate films capture European procurement policy tightening on environmental criteria. |
| Digital Traceability Integration | Embedded serialization and blockchain-verified sterilization records enable premium pricing under EU MDR mandates. |
| Reusable Rigid Container Protocols | Glass-composite formats with integrated instrument tracking address orthopedic and cardiac surgery value-chain pressure. |
Research Methodology
The analysis maps sterile barrier systems by packaging type, material substrate, and end-use environment, each validated through procurement directors at integrated delivery networks, sterile processing department managers, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and ISO 11607 certification records. Bottom-up and top-down triangulation cross-checked segment outputs against customs data and medical device trade flows.
Consistency checks validated volume and value outputs against external benchmarks including hospital construction permits, ambulatory surgical center licensing data, and sterilization capacity utilization reports across the projection horizon. Segmentation dimensions modeled include packaging format, material substrate, sterilization modality compatibility, end-user type, and surgical application specialty. CAGRs derived from procedure volume trajectories, regulatory compliance cost curves, and material substitution elasticities. Forecast inputs incorporated EU MDR implementation timelines and EPA per- and polyfluoroalkyl substance restriction pathways.
Underlying assumptions cover outpatient procedure expansion rates, sterilization modality mix stability, and regulatory harmonization progress, with deviation risk concentrated in ethylene oxide sterilization capacity constraints and REACH coating chemistry restrictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Global Medical Packaging Market