
 Middle East and Africa Medical Devices Packaging Market | 2026-2036
Middle East and Africa Medical Devices Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Medical Devices Packaging Market Foresight
Preventive maintenance contracts for sealing equipment and validation services is expanding as a recurring revenue layer alongside physical packaging sales. Amcor Group GmbH leverages its regional sterilization-grade film capacity to serve Gulf hospital networks. Sonoco Products Company anchors its position through rigid tray manufacturing tailored to orthopedic kit requirements. Wipak Group competes on high-barrier pouch formats for pharmaceutical-device combination products.
Middle East and Africa medical devices packaging encompasses engineered sterile barriers, typically multilayer polymer films or coated paperboard structures, manufactured via thermoforming, extrusion coating, or adhesive lamination to maintain sterility from terminal sterilization through point of use. Pouch formats lead volume due to their compatibility with gamma and ethylene oxide sterilization cycles across catheter and wound care applications. Blister packs capture margin concentration where pharmaceutical-device combinations require child-resistant lidding and precise cavity tolerances. Flexible form factors accelerate fastest as ambulatory surgical centers in the United Arab Emirates and Kenya prioritize lightweight, low-cube distribution.
South Africa's Health Products Regulatory Authority and Saudi Arabia's Food and Drug Authority enforce divergent sterility assurance level documentation, forcing suppliers to maintain dual validation protocols for cross-border shipments. The EU Medical Device Regulation's extraterritorial influence shapes exporter readiness across Morocco and Tunisia, where European OEMs source sterile packaging. Stakeholders must monitor harmonization talks between Gulf standardization bodies and the African Medicines Agency, as regulatory alignment will determine which packaging formats achieve economies of scale across the region.
Market Dynamics
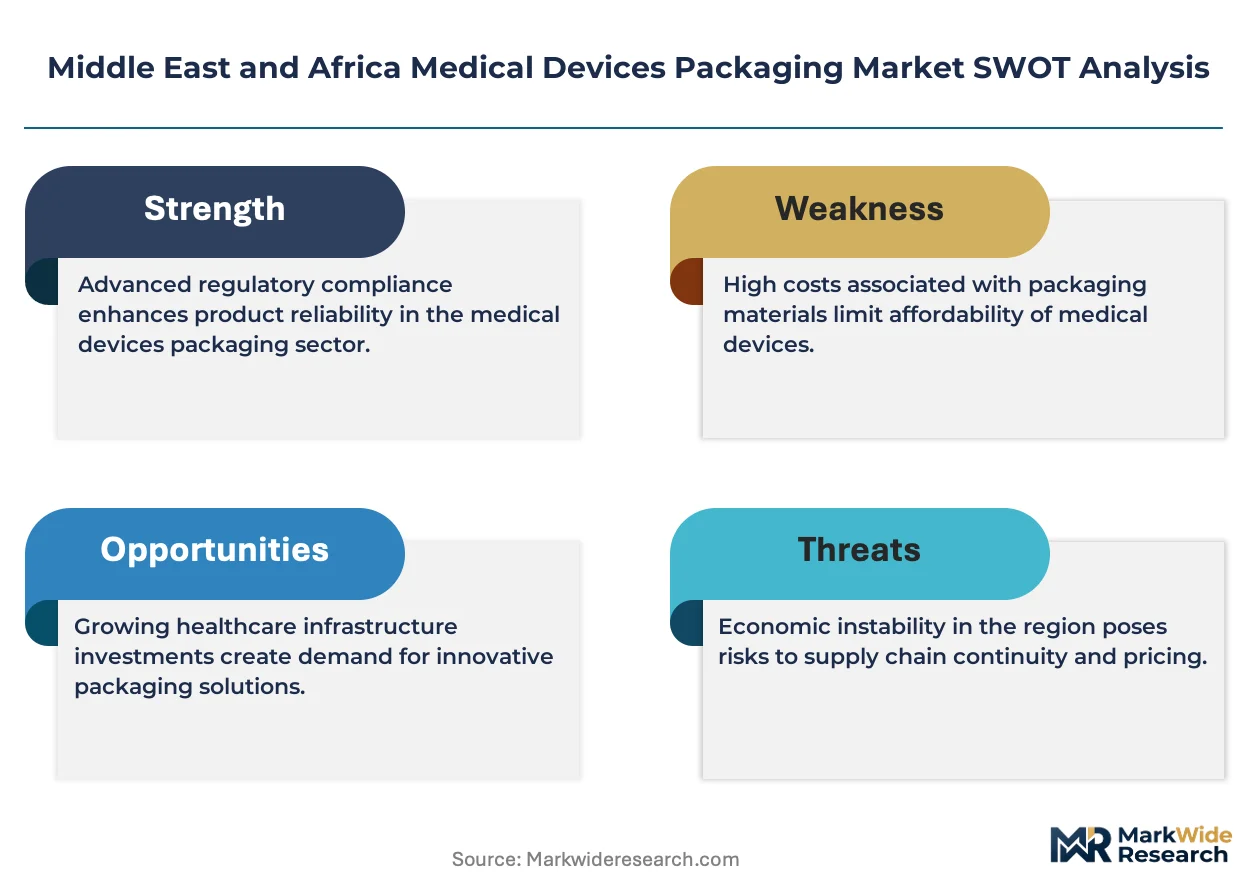
Sterile barrier validation complexity is fragmenting supplier economics across the Middle East and Africa, as dual regulatory compliance for Gulf and sub-Saharan markets forces packaging converters to maintain parallel quality management systems without scale benefits.
Growth Catalysts
- SFDA Sterility Mandates:Saudi Arabia's Food and Drug Authority tightened documentation requirements for ethylene oxide residuals, compelling domestic manufacturers to upgrade sealing equipment and validation protocols.
- Catheter Manufacturing Clusters:Riyadh-Jeddah corridor demand for gamma-compatible pouches is pulling multilayer film capacity expansion from regional converters.
- African Medicines Agency Harmonization:Draft technical guidelines for medical device packaging are creating pathway clarity for suppliers targeting Kenya, Nigeria, and Egypt simultaneously.
Market Restraints
- Ethylene Oxide Supply Concentration:Terminal sterilization gas availability concentrates through three Gulf petrochemical suppliers, exposing packaging converters to input volatility and allocation risk.
- Dual Validation Burden:South Africa's Health Products Regulatory Authority and Saudi SFDA maintain non-identical sterility assurance level testing protocols, inflating quality assurance overhead for cross-border suppliers.
- Rigid Tray Substitution Pressure:Flexible pouch formats are compressing demand for thermoformed trays in wound care applications, threatening capital recovery timelines for tray-dedicated production lines.
Strategic Opportunities
- Kenya Ambulatory Surgical Centers:Nairobi and Mombasa facility expansion is generating first-mover advantage for lightweight, low-cube pouch suppliers capable of cold-chain-free distribution.
- EU MDR Extraterritorial Alignment:Moroccan and Tunisian exporters to European OEMs can capture packaging contracts by pre-certifying to Medical Device Regulation technical documentation standards.
- Preventive Maintenance Contracting:Sealing equipment service agreements and validation outsourcing are emerging as recurring revenue streams distinct from physical packaging sales.
Industry Challenges
- Sterilization Process Engineering Talent:Gulf converters face acute shortages of ethylene oxide cycle validation specialists and gamma dose mapping technicians, elongating new product qualification timelines.
- Legacy ERP Integration:Track-and-trace requirements from Saudi SFDA and UAE MOHAP are forcing mid-tier suppliers to reconfigure inventory systems without dedicated IT capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Medical Devices Packaging Market |
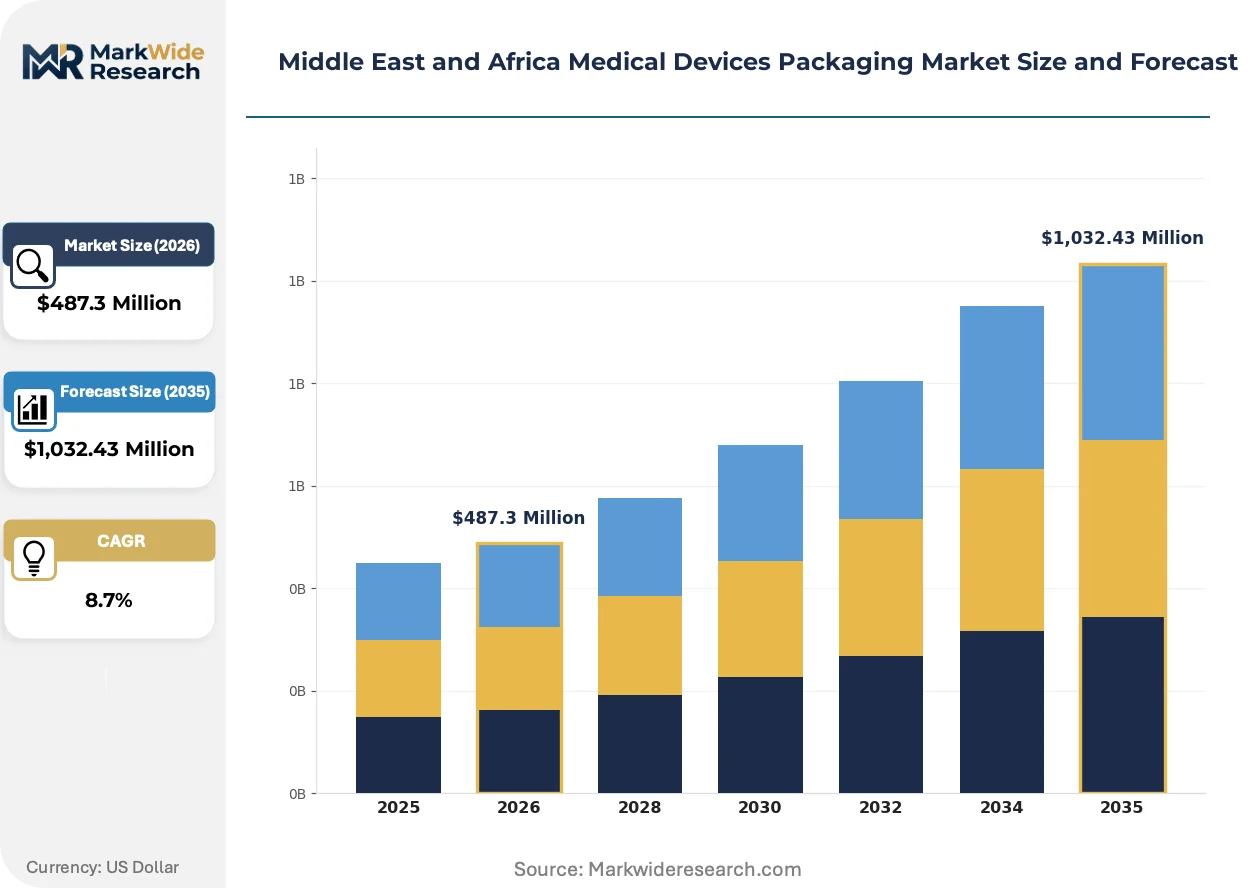
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Trays, Pouches, Cartons Material: Plastic, Glass, Metal, Paperboard Form: Rigid, Flexible, Semi-Rigid, Composite End User: Hospitals, Clinics, Pharmacies, Government Institutions |
| Companies Covered | Amcor Group GmbH, Sonoco Products Company, Wipak Group, Constantia Flexibles GmbH, WestRock Company, Berry Global, AptarGroup, Mondi Group, Schott AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Medical Devices Packaging Market Shifts & Advancements
Active and intelligent packaging technologies are penetrating sterile barrier applications, while regulatory documentation digitization and ambulatory care distribution models are compressing traditional supply chain structures across the Middle East and Africa.
Multilayer coextruded films with embedded oxygen scavengers and humidity indicators are modularizing sterile barrier functionality previously requiring separate sachet inserts. UAE hospital networks are piloting these integrated formats for implantable device kits, reducing packaging cube and simplifying sterile field opening protocols. The technology is modularizing supplier value chains by collapsing secondary packaging steps into primary barrier formation.
EU Medical Device Regulation technical documentation requirements are reshaping exporter readiness protocols in Morocco and Tunisia, where European OEMs source sterile packaging. North African converters must now maintain electronic technical files and post-market surveillance systems identical to EU-based suppliers. Pharmaceutical-device combination product manufacturers face the steepest compliance gradient, with notified body involvement now mandatory for packaging system changes.
Consignment inventory arrangements are displacing traditional purchase-order procurement in Saudi Arabia's hospital procurement landscape. Riyadh-Jeddah corridor medical device distributors now require packaging suppliers to maintain floor stock at sterilization service providers, transferring working capital burden upstream. Kenyan private hospital chains are replicating this model, compressing supplier cash conversion cycles while demanding same-day replenishment flexibility.
Middle East and Africa Medical Devices Packaging Market Segmentation
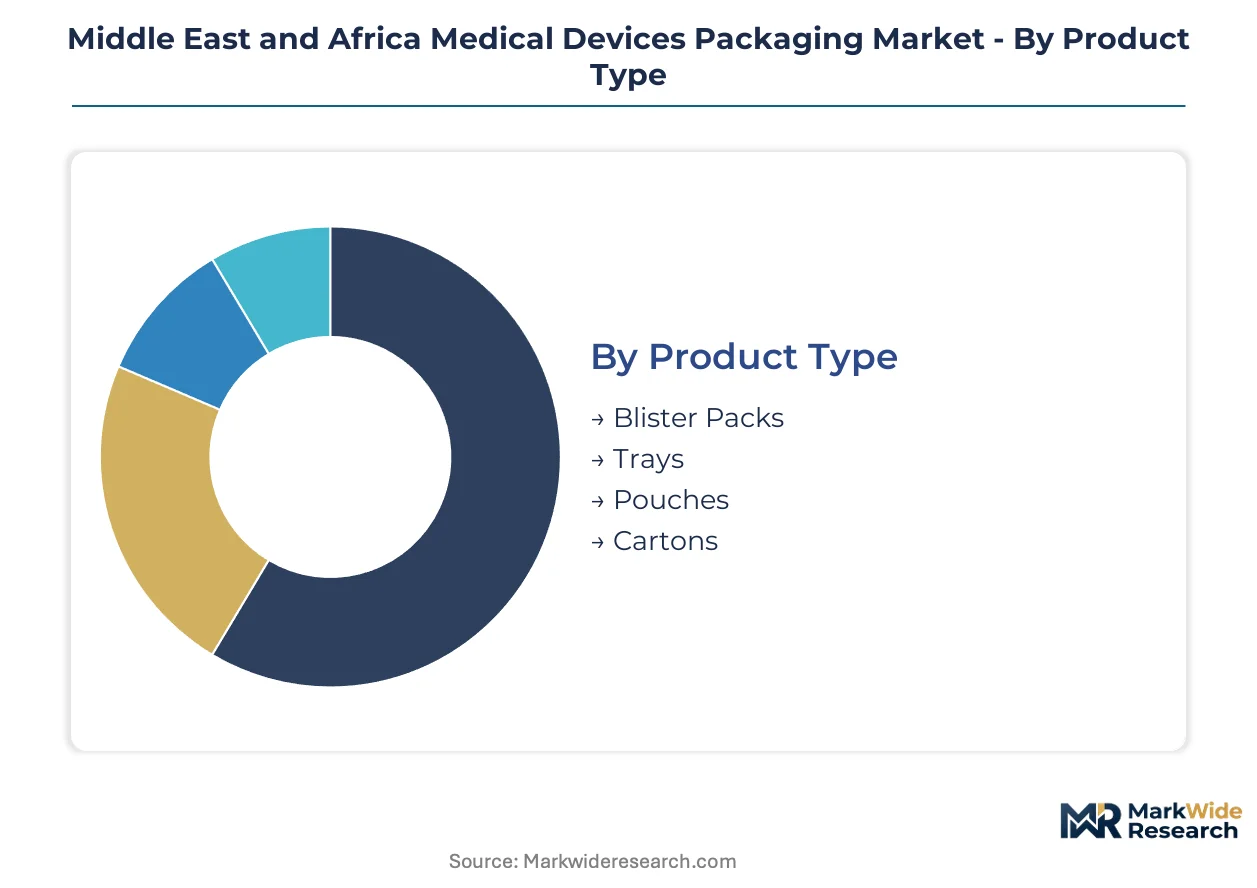
Packaging format selection in the Middle East and Africa hinges on sterilization compatibility, distribution logistics, and regulatory documentation burden. Buyers prioritize gamma and ethylene oxide resilience alongside cold-chain efficiency across diverse healthcare infrastructure.
Product Type:
Hospital procurement teams and device manufacturers select formats based on sterilization method, kit complexity, and sterile field opening protocols.
- Pouches:Multilayer polymer films engineered for gamma and ethylene oxide cycles dominate catheter and wound care applications. Riyadh-Jeddah corridor manufacturers specify these for lightweight distribution to ambulatory surgical centers across Saudi Arabia.
- Trays:Thermoformed polymer structures with precision cavity tolerances anchor orthopedic and implantable device kits. South Africa's Health Products Regulatory Authority mandates stricter sterility validation for tray-based systems, elevating quality assurance overhead.
- Blister Packs:Child-resistant lidding and precise cavity dimensions serve pharmaceutical-device combinations requiring tamper-evident barriers.
- Cartons:Secondary paperboard enclosures provide branding surface and distribution protection for retail pharmacy channels.
Pouches lead on scale; trays lead on momentum amid orthopedic kit expansion.
Material:
Material selection balances barrier performance, sterilization stability, and total cost across Gulf and sub-Saharan supply chains.
- Plastic:Coextruded films and thermoformable polymers constitute the dominant substrate, offering tunable oxygen and moisture barriers. Kenyan private hospital chains specify plastic pouches for cold-chain-free distribution to Nairobi and Mombasa facilities.
- Paperboard:Coated and uncoated grades serve secondary cartoning and sterile barrier systems where fiber-based sustainability positioning matters.
- Glass:Borosilicate and soda-lime containers preserve diagnostic reagent stability in temperature-variable logistics.
- Metal:Aluminum foils and laminates provide absolute light and gas barriers for photosensitive pharmaceutical-device combinations.
Plastic dominates volume; paperboard climbs fastest on sustainability procurement criteria.
Form:
Form factor decisions reflect distribution cube efficiency against protection requirements in multi-modal Middle East and Africa logistics.
- Flexible:Rollstock and pre-formed pouches minimize shipping volume and weight. UAE ambulatory surgical centers prioritize these formats for same-day replenishment models.
- Rigid:Thermoformed trays and injection-molded containers protect delicate instruments through rough-handled last-mile distribution.
- Semi-Rigid:Hybrid structures combine dimensional stability with partial collapsibility for intermediate protection needs.
- Composite:Multi-material assemblies integrate barrier films with structural substrates for complex kit configurations.
Flexible forms gain share fastest; rigid formats defend position in orthopedic applications.
End User:
End-user channel structure determines packaging specification complexity, inventory model, and regulatory documentation depth.
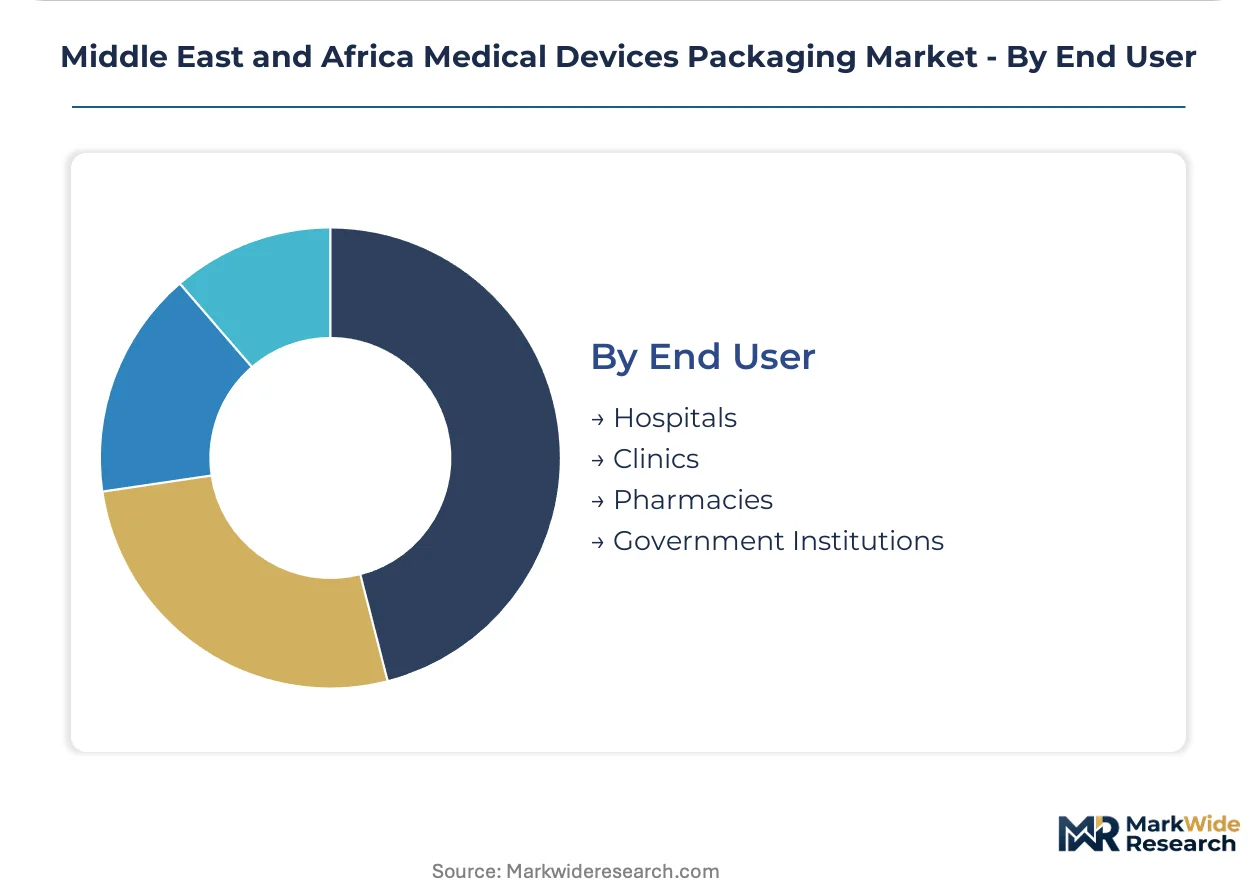
- Hospitals:Tertiary and secondary acute care facilities drive demand for sterile barrier systems with full validation documentation. Saudi Arabia's Food and Drug Authority mandates electronic track-and-trace compatibility for hospital-distributed devices.
- Clinics:Outpatient and specialty clinics favor lightweight, low-cube formats compatible with limited storage footprint. Kenyan clinic expansion generates demand for simplified sterile field opening protocols.
- Pharmacies:Retail and hospital pharmacy channels require child-resistant features and patient-facing labeling for over-the-counter device sales.
- Government Institutions:Public procurement systems in Egypt and Nigeria specify cost-optimized formats with basic sterility assurance for primary care distribution.
Hospitals anchor volume concentration; clinics represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints across the Middle East and Africa, as manufacturers relocate to jurisdictions with streamlined sterility validation protocols while maintaining Gulf market access through dual-certification strategies.
Saudi Arabia
The Riyadh-Jeddah medical device corridor drives concentrated demand for gamma-compatible pouches and catheter packaging systems. SFDA tightened ethylene oxide residual documentation requirements in 2024, compelling domestic converters to upgrade sealing validation equipment. Jeddah's industrial zone hosts expanding multilayer film capacity serving both domestic hospital networks and re-export markets.
United Arab Emirates
Dubai and Abu Dhabi ambulatory surgical centers prioritize lightweight, low-cube flexible formats for same-day replenishment procurement models. MOHAP mandates electronic track-and-trace compatibility for all hospital-distributed devices, forcing mid-tier suppliers toward ERP system modernization. The Dubai Science Park cluster attracts sterile barrier converters targeting GCC-wide distribution.
South Africa
Cape Town and Johannesburg medical device manufacturers face elevated quality assurance overhead from SAHPRA's stricter sterility assurance level testing protocols. The regulator's non-identical requirements versus Gulf standards inflate dual validation burdens for cross-border suppliers. Gauteng province's orthopedic kit assembly plants anchor regional rigid tray demand.
Kenya
Nairobi and Mombasa facility expansion generates first-mover opportunities for cold-chain-free pouch distribution to private hospital chains. The African Medicines Agency's draft harmonization guidelines are creating pathway clarity for suppliers targeting simultaneous Kenya-Nigeria-Egypt market entry. Local clinic networks favor simplified sterile field opening protocols.
Morocco
Casablanca and Tangier-Med packaging converters are pre-certifying to EU MDR technical documentation standards to capture European OEM sourcing contracts. The extraterritorial influence of European Medical Device Regulation is reshaping exporter readiness protocols across North African production bases. Pharmaceutical-device combination products face mandatory notified body involvement for packaging system modifications.
Middle East and Africa Medical Devices Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated multinational film suppliers dominating sterile barrier substrates while regional converters capture value-added forming and validation services. Three strategic archetypes define competitive positioning: integrated polymer producers with captive sterilization-grade film capacity, rigid tray specialists serving orthopedic kit assemblers, and flexible packaging converters targeting ambulatory care distribution. Capacity expansion and preventive maintenance service bundling represent the dominant competitive moves, as physical packaging margins compress and recurring revenue models gain traction.
Among integrated packaging groups, Amcor Group GmbH and Sonoco Products Company exemplify divergent strategic anchors within the regional market. Amcor leverages sterilization-grade film manufacturing infrastructure to serve Gulf hospital network procurement consolidation. Sonoco occupies a position centered on rigid tray production tailored to orthopedic device kit requirements. Wipak Group represents the high-barrier pouch specialist archetype competing for pharmaceutical-device combination product contracts. These three entities illustrate how global packaging conglomerates adapt format-specific expertise to Middle East and Africa regulatory and distribution complexity.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Sonoco Products Company |
| Wipak Group |
| Constantia Flexibles GmbH |
| WestRock Company |
| Berry Global |
| AptarGroup |
| Mondi Group |
| Schott AG |
| Others |
Supply & Pricing Matrix
Polypropylene resin indices and ethylene oxide spot pricing cascade through Middle East and Africa medical devices packaging supply chains, compressing margins for converters serving Saudi SFDA-mandated sterilization validation tiers while amplifying pricing power for Gulf petrochemical-integrated film suppliers.
Pricing Analysis
Distributor margin layers in Saudi Arabia's Riyadh-Jeddah corridor absorb validation service markups before hospital procurement committees. Three-tier pricing structure across premium sterilization-grade films, standard multilayer pouches, and economy paperboard cartons reflects SFDA certification depth and gamma compatibility. Cost compression in standard-tier pouches is intensifying because Kenyan clinic networks prioritize cold-chain-free distribution economics. Government procurement systems in Egypt and Nigeria exhibit highest price sensitivity; European OEM sourcing through Morocco and Tunisia show lowest.
Supply Chain Analysis
Reverse-logistics flows for expired sterile barriers and validation-documented returns concentrate through Jeddah industrial zone consolidation hubs before reprocessing or disposal. Raw material supply draws from Saudi petrochemical complexes, South African polymer importers, and European film converters serving North African exporters. Ethylene oxide terminal sterilization gas feeds from three Gulf suppliers, creating single-source vulnerability for cross-border converters. Distribution runs through sterilization service provider floor-stock arrangements in Saudi Arabia and Kenya, compressing supplier working capital cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East and Africa medical devices packaging functions as a geographic-arbitrage play where SFDA validation overhead in Saudi Arabia runs 40% above Kenyan clinic-tier requirements, enabling cost-optimized production repositioning.
For Market Incumbents: Anchor market position through preventive maintenance service bundling and captive multilayer film capacity expansion in Jeddah industrial zones. Rigid tray substitution pressure from flexible pouch formats threatens capital recovery timelines; defend through orthopedic kit assembler exclusive supply agreements. SFDA electronic track-and-trace mandates favor ERP-modernized incumbents over mid-tier competitors. For New Entrants and Emerging Players: Capture first-mover advantage in Nairobi and Mombasa ambulatory surgical center networks demanding lightweight, low-cube pouch distribution without cold-chain infrastructure. Kenyan private hospital chains represent the most penetrable segment due to simplified sterile field opening protocol requirements. Lead with validation outsourcing service models rather than physical packaging commodity positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with sterilization-grade film converters possessing dual SFDA-SAHPRA validation capabilities. Long-term viability hinges on regulatory harmonization between Gulf standardization bodies and the African Medicines Agency. Monitor draft harmonization guideline finalization as inflection indicator for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | SFDA and SAHPRA parallel validation unlocks Saudi-South Africa cross-border shipments without duplicate quality systems. |
| Preventive Maintenance Contracting | Sealing equipment service agreements generate recurring revenue distinct from physical packaging margin compression. |
| Kenya Distribution Footprint | Nairobi and Mombasa cold-chain-free pouch capacity captures ambulatory surgical center expansion ahead of competitors. |
| EU MDR Pre-Certification | Moroccan and Tunisian converters aligning with European Medical Device Regulation technical documentation secure OEM sourcing contracts. |
| Active Packaging Integration | Oxygen scavenger and humidity indicator embedded films reduce packaging cube for UAE hospital network implantable device kits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sterilization validation engineers, hospital procurement managers, biomedical packaging specialists, and Gulf converter operations directors with secondary validation from SFDA regulatory filings, SAHPRA guidance documents, African Medicines Agency draft technical guidelines, and EU Medical Device Regulation compliance databases. Bottom-up facility capacity assessments and top-down healthcare expenditure projections were triangulated against trade flow data.
Comparable historical reference periods anchored the projection horizon to pre-harmonization regulatory divergence and post-SFDA electronic track-and-trace mandate implementation phases. Segmentation modeling spanned packaging format, material substrate, sterilization compatibility, and end-user channel across the analysis window. CAGRs derived from facility expansion announcements, validation service pricing trends, and healthcare infrastructure investment pipelines. Ethylene oxide supply concentration indices and polymer resin price volatility bands informed scenario-weighted outputs.
Regulatory harmonization delays, ethylene oxide supply disruptions, and currency fluctuation in Egyptian and Nigerian import financing are the dominant revision risks. Practitioners should monitor African Medicines Agency guideline finalization, Gulf petrochemical supplier allocation announcements, and Kenyan central bank foreign exchange policy for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market