
 Transplant Box Market | 2026-2036
Transplant Box Market Size, Share, and Industry Trends Forecast 2026-2036
Transplant Box Market Intelligence
Market Context
MDR compliance is consolidating the cost-of-entry calculus for transplant box manufacturers seeking CE-marked distribution across Europe. TransMedics leverages its integrated perfusion platform to sustain premium positioning in heart and lung transport. Paragonix Technologies differentiates through its organ-specific container designs that anchor clinical adoption in major academic medical centers. XVIVO Perfusion competes via advanced hypothermic oxygenated perfusion systems that extend viable preservation windows.
Technical Definition and Segment Structure
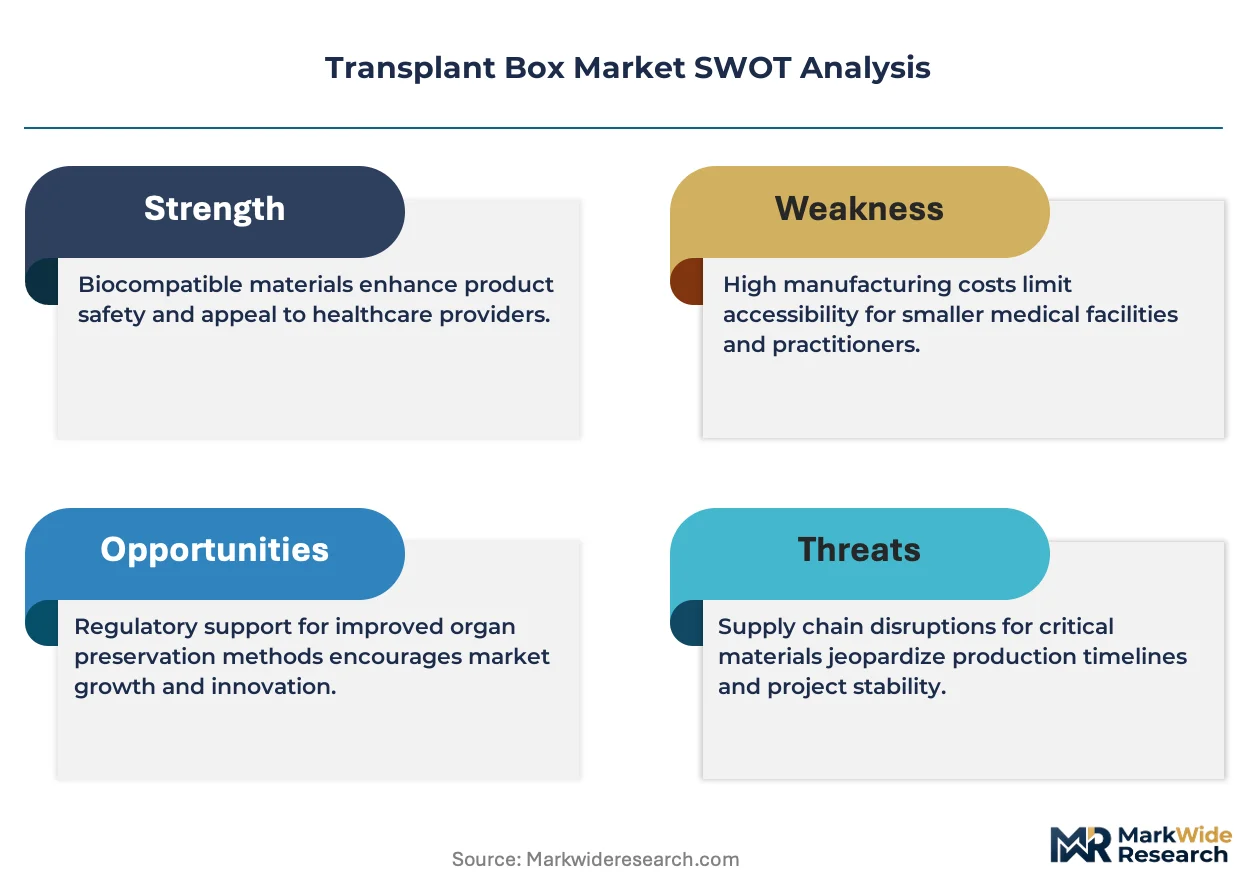
A transplant box is a thermally regulated, sterile containment system engineered to maintain organ viability through precise temperature control, oxygenation, and pressure management during transport from donor to recipient. These systems employ perfusion circuits, cold storage media, or normothermic platforms to prevent ischemic injury, with critical specifications including temperature stability within 2-8°C for hypothermic units and 34-37°C for normothermic devices. Kidney and liver product types dominate current revenue given higher procurement volumes, while lung applications represent the fastest-growing segment as ex-vivo lung perfusion protocols expand. Disposable packaging configurations command margin concentration due to recurring consumable demand, whereas reusable containers retain footholds in cost-constrained healthcare organizations.
Regulatory Frame and Outlook
FDA premarket notification pathways, EU MDR technical documentation requirements, and ISO 14155 clinical investigation standards collectively shape product development timelines and market access barriers for transplant box innovators. The FDA's Humanitarian Device Exemption framework accelerates niche indications, while MDR notified body capacity constraints extend European approval cycles. Stakeholders must monitor evolving reimbursement determinations from CMS and national health technology assessment bodies, as coverage policies directly determine institutional procurement velocity for advanced preservation systems.
Market Dynamics
Ex-vivo perfusion technology is compressing cold-storage timelines and forcing transplant centers to requalify procurement workflows around normothermic platforms. This shift redistributes capital allocation toward integrated systems and away from passive containment hardware.
Growth Catalysts
- CMS reimbursement expansion:The US Centers for Medicare & Medicaid Services is extending coverage codes for machine perfusion transport, incentivizing hospital procurement of advanced preservation systems over static cold storage.
- Lung transplant protocol adoption:Academic medical centers are standardizing ex-vivo lung perfusion as bridge-to-transplant methodology, creating institutional demand for portable normothermic containers.
- EU MDR harmonization:The Medical Device Regulation's consolidated technical documentation requirements are accelerating cross-border distribution for CE-marked perfusion systems within the European Economic Area.
Market Restraints
- Perfusion circuit input costs:Single-use oxygenators and proprietary tubing sets create recurring consumable burdens that constrain adoption in cost-constrained public health systems.
- Notified body capacity bottlenecks:EU MDR designation backlogs at TÜV SÜD and BSI extend European approval timelines by 12-18 months for novel preservation technologies.
- Static cold storage substitution:Ice-based transport remains clinically adequate for short-distance kidney retrieval, limiting premium system penetration in regional donor networks.
Strategic Opportunities
- India procurement infrastructure:The country's expanding deceased-donor program and CDSCO fast-track pathways for orphan devices create first-mover positioning for perfusion-enabled transport systems.
- Heart-in-a-box expansion:Normothermic cardiac perfusion is migrating from research protocols to standard-of-care transport, opening replacement demand for legacy static containers.
- ISO 14155 convergence:Global alignment on clinical investigation standards is reducing redundant trial requirements, compressing time-to-market for multi-regional product launches.
Industry Challenges
- Perfusionist workforce scarcity:Specialized training requirements for ex-vivo organ management outpace institutional education capacity, constraining deployment velocity.
- Legacy EHR integration:Biometric telemetry from smart transport containers requires custom API development to interface with hospital data architectures, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transplant Box Market |
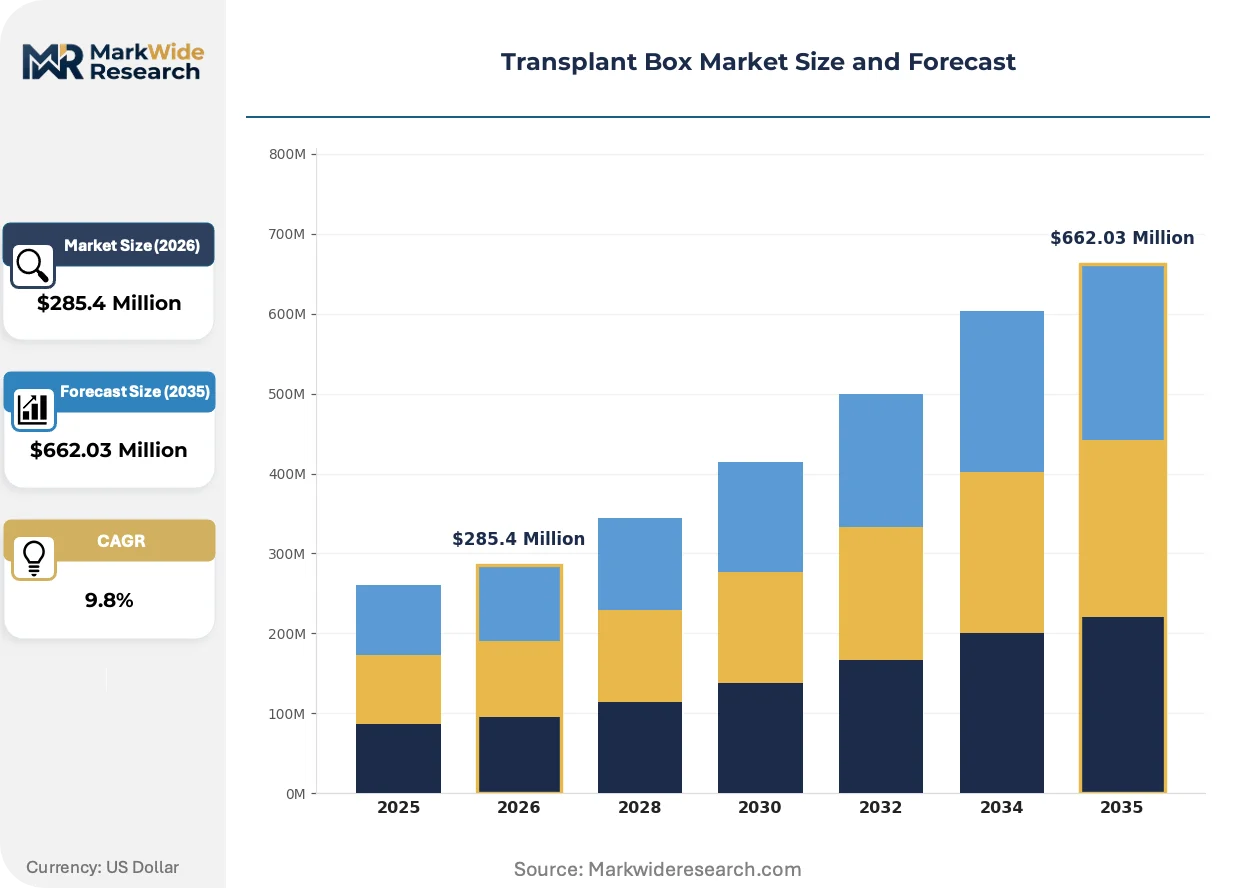
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $662.03 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart, Kidney, Liver, Lung Application: Organ Transport, Tissue Preservation, Research, Medical Training End User: Hospitals, Transplant Centers, Research Institutions, Healthcare Organizations Packaging Type: Reusable Containers, Disposable Boxes, Insulated Bags, Custom Kits |
| Companies Covered | OrganOx, Waters Medical Systems, TransMedics, Institut Georges Lopez, Bridge to Life, Paragonix Technologies, XVIVO Perfusion, Getinge, Organ Recovery Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transplant Box Market Strategic Shifts & Innovations
Digital telemetry and disposable cartridge architectures are converging to transform transplant boxes from passive containers into active clinical decision-support platforms. This evolution redefines competitive differentiation around data integration rather than thermal performance alone.
Normothermic regional perfusion is unifying oxygenation, temperature control, and metabolic monitoring into single-disposable circuits. Major academic transplant centers are adopting these integrated platforms for liver and heart retrieval. The technology is unifying what were previously separate capital equipment categories into consumable-centric business models.
The EU MDR's post-market surveillance requirements are mandating real-world performance registries for Class III medical devices. Manufacturers must now fund longitudinal outcome studies as a condition of CE marking renewal. Lung preservation systems face the steepest compliance burden due to the regulation's emphasis on novel therapeutic mechanisms.
Hospital procurement committees are consolidating vendor relationships around full-service perfusion contracts that bundle equipment, disposables, and clinical training. Traditional device distributors are losing share to manufacturer-direct clinical specialist teams. This pattern is most pronounced in the United States, where UNOS-mandated outcome reporting intensifies institutional risk aversion toward unproven suppliers.
Transplant Box Market Segmentation
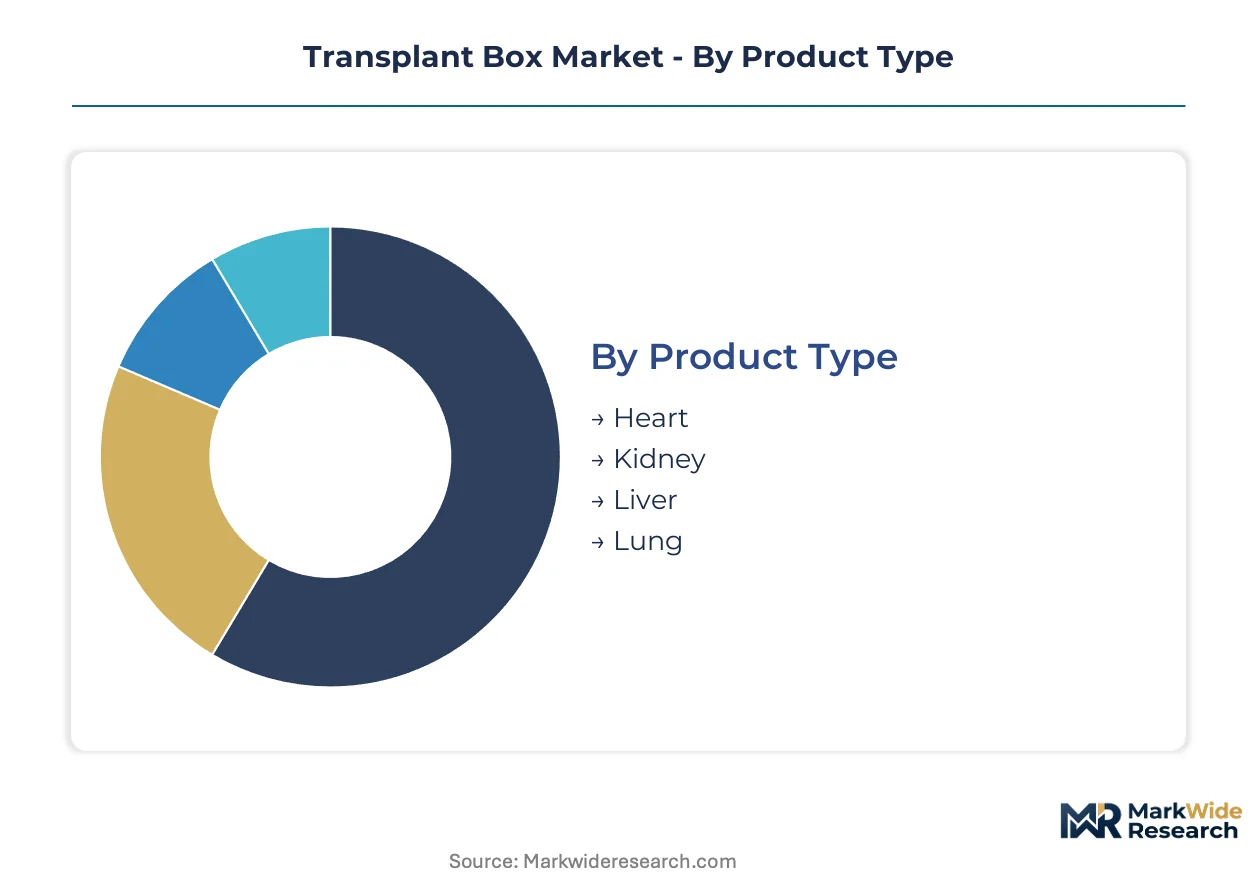
Segmentation in the transplant box market reveals how organ-specific engineering requirements and procurement economics create distinct competitive arenas. Each dimension—product type, application, end user, and packaging—carries unique regulatory burdens and margin structures that determine vendor positioning.
Product Type:
Kidney and liver systems operate as standalone perfusion platforms with embedded monitoring, while heart and lung boxes increasingly integrate with donor hospital ECMO infrastructure.
- Heart:Normothermic perfusion circuits maintain coronary flow at 34-37°C through portable oxygenators and pulsatile pumps. Demand clusters at US academic medical centers adopting standard-of-care cardiac transport protocols; CMS reimbursement codes for machine perfusion accelerate procurement velocity.
- Kidney:Hypothermic oxygenated perfusion dominates clinical practice, with disposable cassette systems replacing static cold storage in extended-criteria donor retrieval. European transplant networks under EUTOS guidelines drive volume concentration; MDR compliance costs favor established CE-marked suppliers.
- Liver:Dual-temperature platforms accommodate both hypothermic and normothermic preservation protocols within single-disposable circuits.
- Lung:Ex-vivo lung perfusion systems represent the steepest technology frontier, with portable normothermic containers enabling bridge-to-transport assessment.
Volume placements concentrate in kidney systems; the faster expansion belongs to lung perfusion platforms.
Application:
Cost tier stratification separates mission-critical organ transport from lower-margin ancillary uses, with research and training applications commanding price-sensitive procurement.
- Organ Transport:FDA-cleared and CE-marked devices with ISO 14155 clinical validation support live donor-to-recipient logistics. UNOS-mandated outcome tracking in the United States creates institutional preference for telemetry-integrated systems with biometric logging.
- Tissue Preservation:Extended hypothermic storage for corneal, vascular, and musculoskeletal grafts employs simplified thermal regulation without active perfusion.
- Research:Preclinical organ perfusion studies utilize modified commercial platforms or custom-built circuits with non-validated sensors.
- Medical Training:Simulation boxes replicate perfusion mechanics without biological load, targeting perfusionist education programs.
Revenue concentration sits in organ transport; research applications are climbing the fastest as pharmaceutical sponsors fund ex-vivo organ studies.
End User:
Customer type determines purchasing authority complexity, with transplant centers consolidating vendor relationships while research institutions fragment across project-specific procurement.
- Hospitals:General acute-care facilities with occasional organ retrieval responsibilities favor reusable containers and passive cold storage for cost containment.
- Transplant Centers:UNOS-designated programs in the United States and comparable national networks in Germany, Spain, and the United Kingdom drive premium system adoption. These institutions negotiate full-service perfusion contracts bundling equipment, disposables, and clinical training.
- Research Institutions:University laboratories and contract research organizations acquire modified platforms for mechanistic studies, prioritizing flexibility over regulatory clearance.
- Healthcare Organizations:Integrated delivery networks and public health systems standardize procurement across multiple sites, favoring disposable-centric models with predictable per-procedure costing.
Procurement volume aggregates at transplant centers; healthcare organizations are gaining share fastest as regional networks consolidate organ retrieval responsibility.
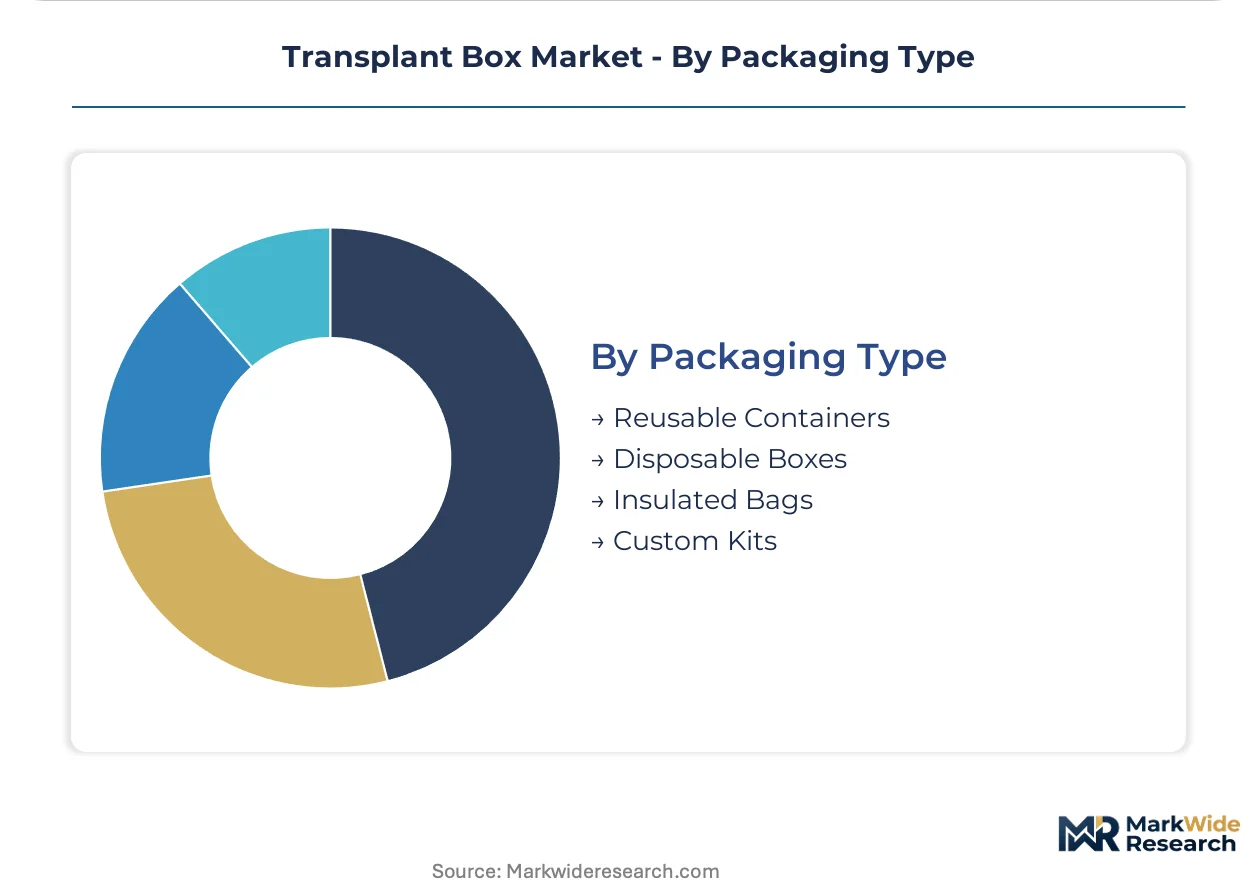
Packaging Type:
Margin structure diverges sharply between capital-intensive reusable platforms and consumable-heavy disposable architectures, with supply concentration favoring integrated manufacturers.
- Reusable Containers:Stainless-steel or composite shells with replaceable insulation cores and validated cleaning protocols support multi-use economics. Cost-constrained public health systems in India and Brazil retain footholds here despite longer turnaround times between cases.
- Disposable Boxes:Single-use sterile barriers with integrated temperature indicators and data loggers eliminate cross-contamination risk. US transplant centers under Joint Commission scrutiny favor this architecture for regulatory defensibility.
- Insulated Bags:Passive gel-pack systems serve short-distance kidney retrieval where cold ischemia time remains under four hours.
- Custom Kits:Procedure-specific configurations bundle perfusion circuits, cannulae, and monitoring sensors for heart-in-a-box or lung-in-a-box protocols.
Shipment volume tilts toward disposable boxes; custom kits are expanding most quickly as normothermic protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device zones in Massachusetts and Minnesota concentrate transplant box engineering talent and FDA premarket submission infrastructure. These clusters anchor North American product development velocity while European notified body capacity constrains rival geographies.
United States
UNOS-designated transplant centers in Boston and Houston drive procurement volume for normothermic perfusion platforms. CMS reimbursement codes for machine perfusion transport incentivize hospital capital expenditure over static cold storage. The FDA's Humanitarian Device Exemption pathway accelerates approval timelines for niche cardiac preservation indications.
Germany
Academic medical centers in Berlin and Heidelberg standardize ex-vivo perfusion protocols for marginal donor lungs. The EU MDR's technical documentation requirements extend approval cycles at TÜV SÜD and BSI notified bodies. Bavarian transplant networks under EUTOS guidelines concentrate procurement authority for multi-site perfusion contracts.
United Kingdom
NHS Blood and Transplant procurement frameworks favor disposable-centric business models with predictable per-procedure costing. The MHRA's post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining UKCA marking pathways. London teaching hospitals anchor adoption of telemetry-integrated transport containers.
Spain
Regional transplant coordination centers in Catalonia and Andalusia manage high deceased-donor retrieval volumes through centralized logistics. National health technology assessment bodies evaluate perfusion system cost-effectiveness against cold storage baselines. Madrid-based procurement committees consolidate vendor relationships around full-service clinical training bundles.
India
Expanding deceased-donor programs in Tamil Nadu and Maharashtra create infrastructure gaps that perfusion-enabled systems address. CDSCO fast-track pathways for orphan devices reduce regulatory barriers for novel preservation technologies. Hyderabad medical device manufacturing zones supply temperature-indicating disposable components to domestic assemblers.
Transplant Box Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Tier-one positions concentrate around integrated perfusion platform developers with proprietary disposable ecosystems. Tier-two players occupy organ-specific container niches with validated clinical outcomes. Tier-three competitors supply passive thermal regulation hardware for cost-constrained procurement committees. Strategic moves center on M&A absorption of disposable circuit manufacturers and capacity expansion into Indian CDSCO-registered production facilities.
Among perfusion-platform specialists, TransMedics and XVIVO Perfusion exemplify the integrated-system archetype with consumable-heavy revenue models. Paragonix Technologies occupies a differentiated position within organ-specific container design. Waters Medical Systems and Getinge represent diversified medical technology conglomerates leveraging existing distribution infrastructure. OrganOx and Institut Georges Lopez anchor European-origin engineering capabilities. Bridge to Life and Organ Recovery Systems sit within the preservation-solutions tier serving multi-organ procurement networks.
| Leading Market Players |
|---|
| OrganOx |
| Waters Medical Systems |
| TransMedics |
| Institut Georges Lopez |
| Bridge to Life |
| Paragonix Technologies |
| XVIVO Perfusion |
| Getinge |
| Organ Recovery Systems |
| Others |
Cost & Logistics Intelligence
CMS reimbursement code expansions for machine perfusion transport are forcing manufacturers to restructure cost-to-serve models around disposable-heavy consumable architectures. Supply networks must pivot from capital equipment cycles toward recurring revenue fulfillment, compressing margins on hardware while capturing lifetime value through proprietary circuit contracts.
Pricing Analysis
Short lead-time premiums for MDR-validated CE-marked systems widen spreads against standard-cycle procurement, with notified body backlog delays creating spot-market urgency among European transplant centers. Three-tier pricing structure across telemetry-integrated premium platforms, validated standard perfusion units, and passive cold-storage economy configurations reflects certification grade and after-sales bundling intensity. Cost compression in the economy tier runs through static-container commoditization as regional donor networks resist premium conversion. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while UNOS-designated transplant centers absorb premium pricing for outcome-accountable systems.
Supply Chain Analysis
Dual-sourcing mandates from US transplant centers and German academic medical centers require manufacturers to qualify redundant oxygenator and pump suppliers across geographies. Component manufacturing concentrates in the United States, Germany, and India, with Hyderabad zones supplying temperature-indicating disposables and Bavarian engineering clusters anchoring precision pump assembly. Supply chain risk centers on single-source vulnerability for proprietary perfusion circuits, where patent-protected tubing sets create captive supplier dependencies. Distribution runs through manufacturer-direct clinical specialist teams rather than traditional device distributors, with full-service contracts bundling equipment, disposables, and perfusionist training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over disposable circuit manufacturing to defend margin structures against commoditization pressure.
For Market Incumbents: Anticipate MDR post-market surveillance cost escalations by funding longitudinal outcome registries now, locking in CE-mark renewal advantages before notified body capacity constraints worsen. Secure backward integration into oxygenator and tubing production to offset single-source supplier leverage, while expanding clinical training infrastructure to address perfusionist workforce scarcity that constrains deployment velocity. For New Entrants and Emerging Players: Direct-to-transport-center digital channels bypass entrenched distributor relationships and enable rapid clinical trial recruitment for novel preservation protocols. White-space concentration sits in India's CDSCO fast-track pathway for orphan devices, where deceased-donor program expansion outpaces domestic manufacturing capacity. Target research institution procurement for preclinical platform validation, converting mechanistic study adoption into transplant center reference accounts. For Investors and Strategic Acquirers: The window for entry favors disposable-circuit specialists with FDA master file documentation and European notified body rapport already established. Long-term viability hinges on consumable recurring revenue ratios exceeding hardware depreciation cycles, with acquisition premiums accruing to platforms demonstrating UNOS-mandated outcome data integration. Watch for CMS reimbursement determination shifts toward normothermic protocols as the inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates CE-mark renewal timelines at TÜV SÜD and BSI notified bodies. |
| Disposable Circuit Backward Integration | Captures margin concentration from proprietary oxygenator and tubing sets. |
| Perfusionist Training Infrastructure Buildout | Addresses workforce scarcity constraining ex-vivo platform deployment velocity. |
| CMS Reimbursement Strategy Alignment | Secures coverage codes for machine perfusion transport over static cold storage. |
| Telemetry-Integrated Platform Development | Enables UNOS-mandated outcome tracking and biometric logging for regulatory defensibility. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with transplant surgeons, biomedical engineers, hospital purchasing committee members, and perfusionist training program directors. UNOS procurement databases, FDA 510(k) and HDE submission records, EMA and notified body technical documentation, and CMS reimbursement determination files provided secondary validation. Bottom-up segmentation modeling triangulated against top-down market sizing from transplant center census data and organ procurement organization volume reports.
Data-stream reconciliation across shipment volumes, installed base estimates, and consumable attach rates produced coherent value projections across the analysis window. Segmentation dimensions modeled include organ type, preservation temperature protocol, packaging architecture, end-user procurement authority, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns for analogous medical device categories, with explicit incorporation of MDR transition timelines and CMS coverage expansion trajectories.
The model holds under steady regulatory harmonization and reimbursement stability; deviation in notified body capacity recovery or CMS coding reversals would shift the outlook materially. Forecasts reflect assumptions regarding perfusionist workforce expansion rates and disposable circuit cost-down trajectories. Deviation in either trigger would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Medical Containers Market