
 Medical Diagnostic Packaging Market | 2026-2036
Medical Diagnostic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Diagnostic Packaging Market Foresight
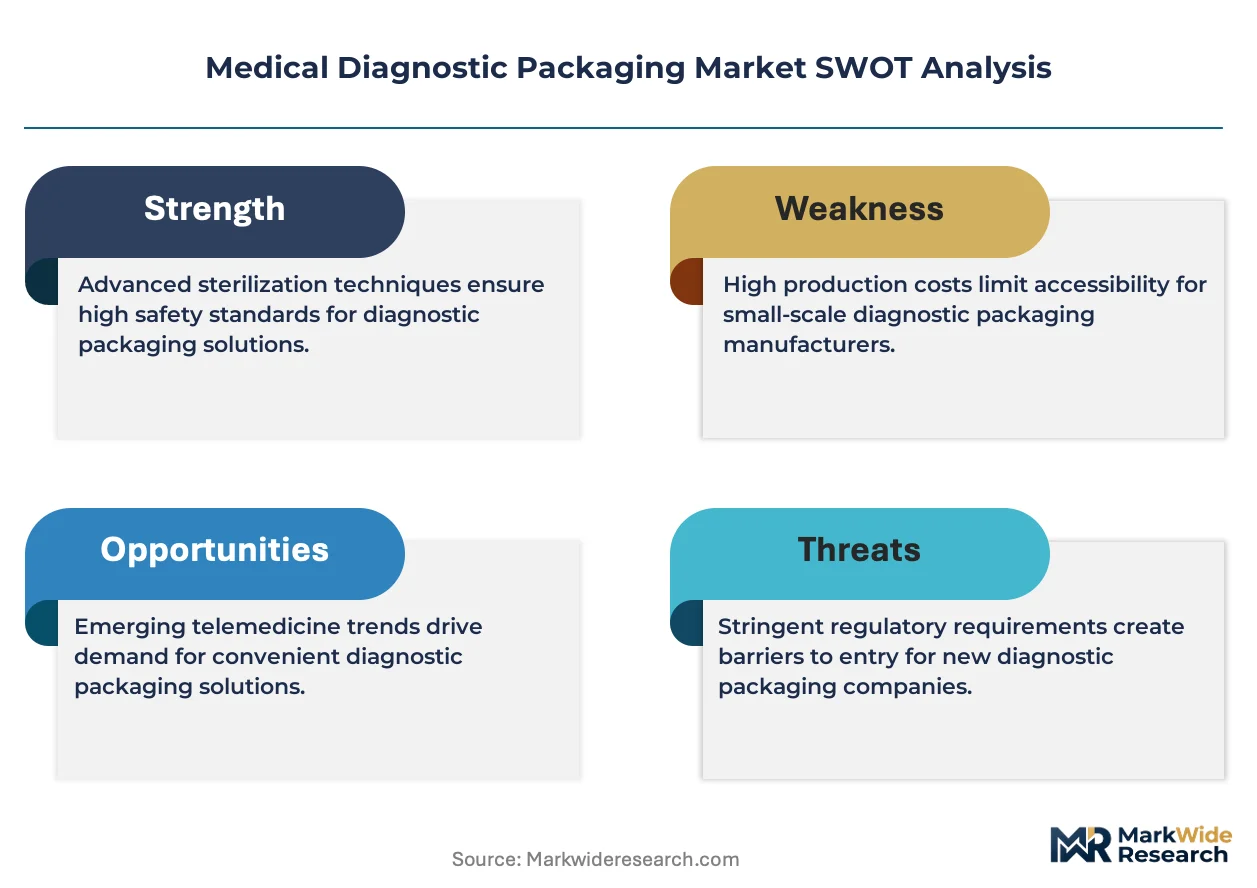
Asset-light leasing models for sterile barrier production lines are reconfiguring competitive entry in diagnostic packaging. Amcor Plc leverages global film extrusion capacity to supply multinational diagnostic OEMs with consistent barrier-grade substrates. West Pharmaceutical Services Inc. anchors its position through integrated elastomer and containment expertise for molecular diagnostic consumables. Gerresheimer AG differentiates via specialized glass and polymer primary packaging for in-vitro diagnostic reagents.
Medical diagnostic packaging encompasses sterile barrier systems, primary containers, and secondary enclosures engineered to maintain product integrity, prevent contamination, and enable traceability for in-vitro diagnostic reagents, test kits, and calibrated controls. These systems typically incorporate multi-layer coextruded films with specified oxygen transmission rates below 0.1 cc per square meter per day, heat-sealed under ISO 11607-2 validated processes to satisfy shelf-life and sterility assurance level requirements. Blister packs and sterile pouches dominate current volume as diagnostic manufacturers prioritize unit-dose formats that reduce cross-contamination risk in high-throughput laboratory environments. Flexible packaging formats are gaining share fastest among point-of-care and decentralized testing applications where portability and minimal storage footprint matter more than rigid structural protection. Material selection increasingly stratifies around high-performance composites that balance aluminum foil barrier properties with polymer processability for automated filling lines.
FDA enforcement of 21 CFR Part 820 quality system regulations and EU MDR Article 10 technical documentation requirements directly shape packaging validation protocols and supplier qualification timelines for diagnostic kit manufacturers. ISO 11607-1 sterilization barrier standards and REACH Article 33 substance disclosure obligations further constrain material formulation choices and migration testing burdens for European market access. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and state-level pharmaceutical packaging waste rules that could impose new end-of-life accountability on diagnostic supply chains.
Market Dynamics
Point-of-care testing networks are consolidating procurement power while EU MDR traceability mandates and FDA Unique Device Identification rules simultaneously tighten documentation burdens for sterile barrier suppliers. This dual pressure is compressing margins for non-specialized converters and favoring integrated packaging-service providers with validated quality systems.
Growth Catalysts
- EU MDR Article 10 technical documentation:Mandates for end-to-end traceability are forcing diagnostic OEMs to upgrade packaging validation protocols, creating replacement demand for ISO 11607-2 certified barrier systems.
- Molecular diagnostic consumables:Polymerase chain reaction and nucleic acid amplification test volumes are expanding sterile elastomer and containment requirements for reagent stability.
- Frankfurt-Munich corridor:Contract packaging hub concentration around centralized German laboratory networks is generating scale economies for automated sterile pouch production.
Market Restraints
- Aluminum-laminate substrate costs:Multi-layer coextruded films with sub-0.1 cc oxygen transmission specifications depend on volatile aluminum foil supply from concentrated Chinese smelters.
- REACH Article 33 substance disclosure:Migration testing burdens for European market access extend supplier qualification timelines by 12-18 months for new material formulations.
- Rigid container substitution:Glass and polymer vials for in-vitro diagnostic reagents face displacement risk from advanced barrier films in ambient-stable formulations.
Strategic Opportunities
- Decentralized testing channels:Pharmacy and retail clinic networks in India and Brazil are adopting portable diagnostic formats requiring minimal-footprint flexible packaging.
- Extended Producer Responsibility frameworks:Emerging state-level pharmaceutical packaging waste rules in the US and EU Green Deal circularity mandates are creating first-mover advantage for recyclable mono-material barrier designs.
- Digital watermark-sterile barrier convergence:Integration of unit-level serialization with heat-seal validation systems is enabling real-time supply chain visibility for high-value diagnostic controls.
Industry Challenges
- ISO 11607-1 sterilization validation expertise:Shortage of engineers capable of designing fractional factorial studies for sterile barrier shelf-life claims is extending product development cycles.
- Legacy ERP integration:Automated filling line data systems require costly middleware upgrades to synchronize with new track-and-trace documentation platforms demanded by FDA enforcement of 21 CFR Part 820.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Diagnostic Packaging Market |
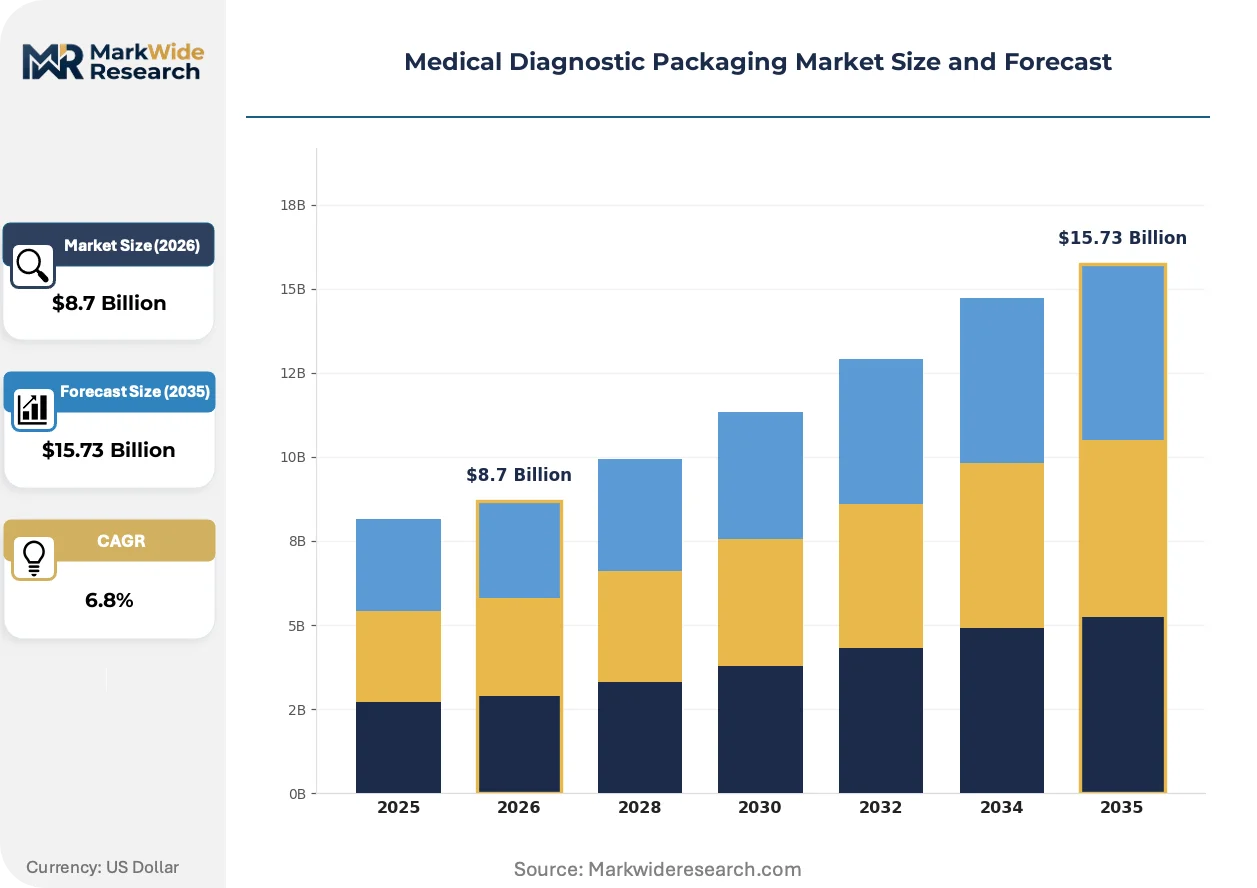
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Sterile Pouches, Trays, Labels Material: Plastic, Paper, Aluminum, Composite End User: Hospitals, Diagnostics Labs, Clinics, Research Institutes Packaging Type: Rigid Containers, Flexible Packaging, Vacuum Packs, Shrink Films |
| Companies Covered | 3M Company, West Pharmaceutical Services Inc, Amcor Plc, Schott AG, Steris Plc, DuPont de Nemours Inc., WestRock Company, Gerresheimer AG, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Diagnostic Packaging Market Shifts & Advancements
Material science advances and regulatory digitization are compressing development timelines while reconfiguring competitive advantage around barrier performance rather than structural protection. These shifts favor converters with in-house polymer compounding capabilities.
High-performance composites balancing aluminum foil barrier properties with thermoplastic processability are rendering obsolete traditional rigid tray-lid systems in automated diagnostic kit assembly. Centralized laboratory networks in Germany and the Netherlands are adopting these formats fastest, collapsing the historical trade-off between shelf-life assurance and line-speed throughput.
REACH substance disclosure obligations and EU MDR post-market surveillance requirements are mandating granular material genealogy documentation. Diagnostic packaging suppliers must now maintain batch-level migration test records spanning raw resin to finished sterile pouch, with German notified bodies auditing these systems most intensively for reagent stability claims.
Unit-dose procurement preferences among high-throughput clinical laboratories are consolidating purchase authority toward integrated diagnostic platform OEMs. This buyer concentration is squeezing standalone packaging converters in the US Northeast and forcing them toward toll-manufacturing arrangements or captive supply contracts with multinational reagent producers.
Medical Diagnostic Packaging Market Segmentation
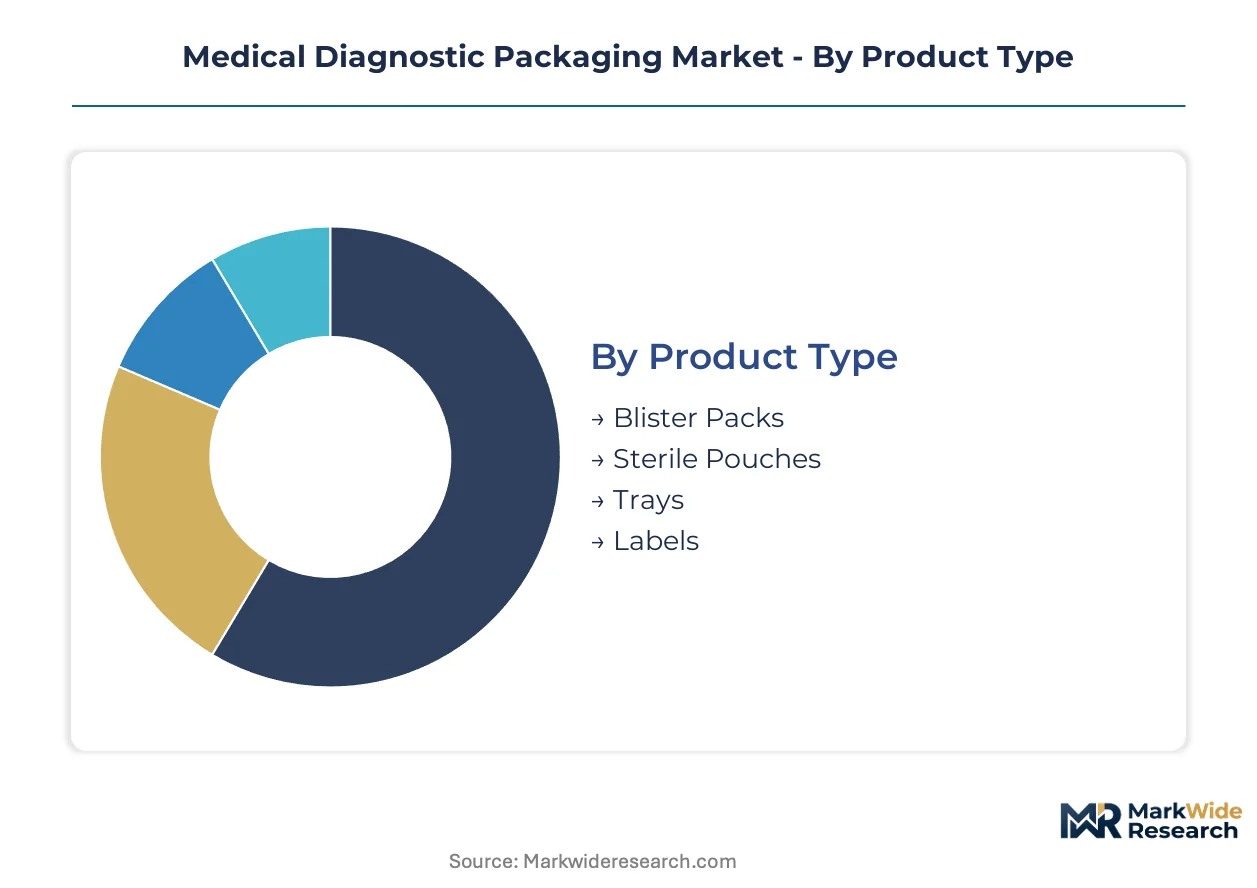
Diagnostic packaging segmentation reflects divergent performance requirements across sterile barrier specifications and end-use environments. Material selection and format design directly determine shelf-life validation protocols and regulatory compliance pathways for reagent manufacturers.
Product Type:
Format selection pivots on automation compatibility and contamination control intensity in target laboratory settings.
- Sterile Pouches:Multi-layer coextruded films with heat-sealed closures dominate high-throughput molecular diagnostic workflows. German centralized laboratory networks around Frankfurt and Munich are consolidating procurement toward ISO 11607-2 validated pouch formats that integrate with automated filling lines.
- Blister Packs:Thermoformed polymer cavities with lidding foil provide unit-dose protection for calibrated controls and single-test reagents. Point-of-care testing networks in decentralized settings favor these formats for their structural rigidity during transport.
- Trays:Injection-molded polymer structures organize multiple reagent vials within kit assemblies.
- Labels:Pressure-sensitive substrates carry FDA Unique Device Identification and EU MDR traceability data.
Sterile pouches command the established base. The steepest expansion runs through blister packs.
Material:
Barrier performance requirements stratify raw material specifications across oxygen transmission rate thresholds and migration testing burdens.
- Composite:Aluminum-laminate multi-layer constructions achieve sub-0.1 cc oxygen transmission rates essential for ambient-stable nucleic acid reagents. REACH Article 33 substance disclosure obligations extend European qualification timelines for these formulations.
- Plastic:Medical-grade polymers including cyclic olefin copolymers and polyethylene terephthalate glycol offer thermoformability for automated processing. Mono-material designs are gaining traction under EU Green Deal circularity mandates.
- Aluminum:Foil layers provide absolute moisture and gas barrier properties in coextruded laminates.
- Paper:Sterilization-grade kraft and medical packaging papers serve secondary labeling and documentation functions.
Composites dominate high-value reagent protection. Plastics are climbing the fastest on recyclability tailwinds.
End User:
Customer procurement authority concentrates differently across centralized laboratory networks versus distributed clinical access points.
- Diagnostics Labs:High-throughput centralized facilities in Germany and the Netherlands drive volume demand for automated-compatible sterile barrier systems. EU MDR Article 10 technical documentation mandates force these buyers toward suppliers with validated quality systems.
- Hospitals:Acute care settings require point-of-care compatible formats with minimal storage footprints. FDA 21 CFR Part 820 enforcement shapes supplier qualification timelines for US hospital procurement.
- Clinics:Outpatient and retail clinic networks prioritize portable packaging for rapid diagnostic tests.
- Research Institutes:Academic and commercial R&D facilities purchase small-batch calibrated controls with extended stability requirements.
Diagnostics labs command the established base. Clinics are expanding most quickly on decentralized testing adoption.
Packaging Type:
Structural rigidity versus flexibility trade-offs determine format suitability across distribution distance and shelf-life duration.
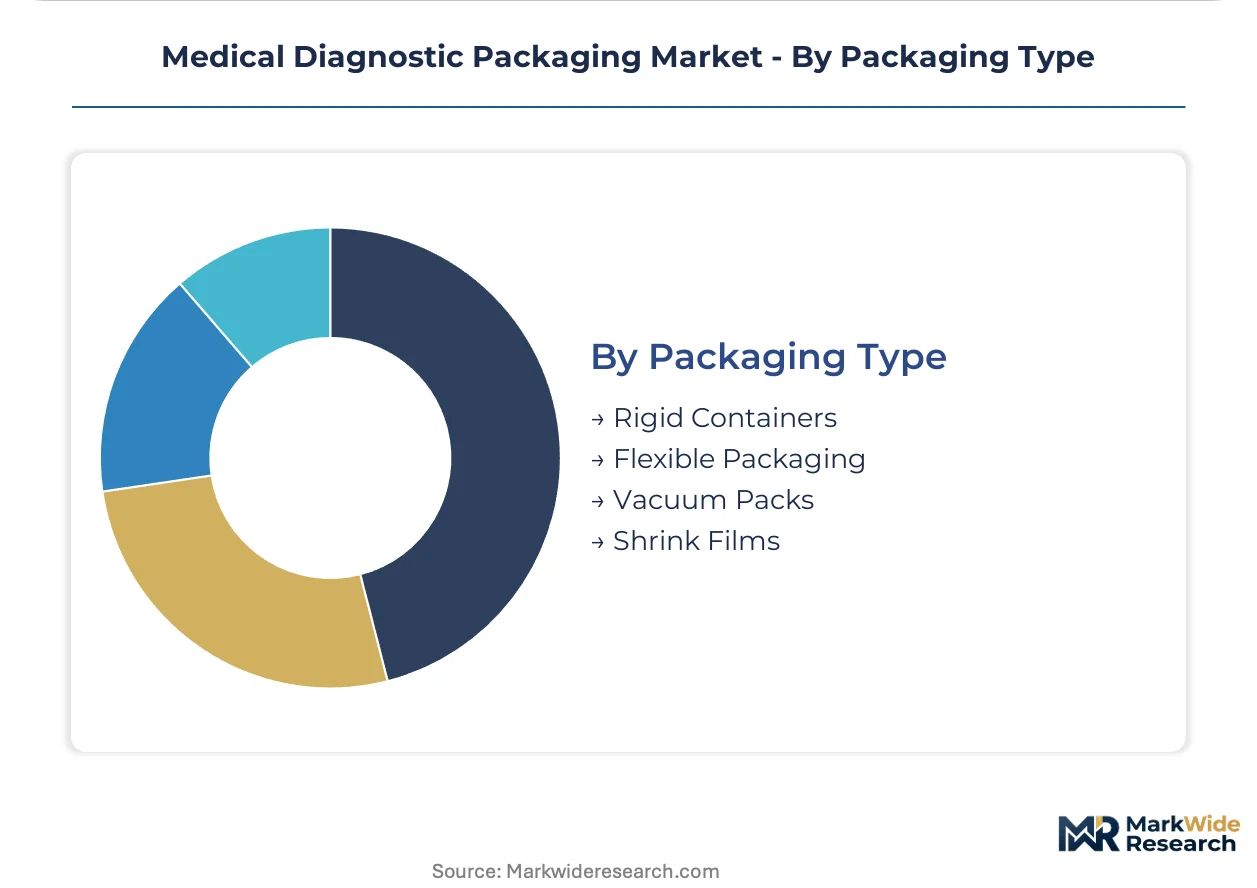
- Flexible Packaging:Roll-stock and pre-formed pouches minimize cubic volume for ambient-stable reagents. Pharmacy and retail clinic networks in India and Brazil are adopting these formats for their minimal storage footprint.
- Rigid Containers:Glass and polymer vials provide primary containment for in-vitro diagnostic reagents requiring structural protection. Gerresheimer AG anchors supply through specialized glass and polymer expertise.
- Vacuum Packs:Evacuated barrier systems extend stability for oxygen-sensitive enzymatic reagents.
- Shrink Films:Secondary bundling formats consolidate multiple units for distribution efficiency.
Rigid containers command the established base. Flexible packaging is gaining share fastest on point-of-care portability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR Article 10 traceability mandates and FDA Unique Device Identification rules are redirecting procurement toward suppliers with validated quality systems. Diagnostic OEMs now prioritize regional packaging partners capable of batch-level documentation and rapid regulatory response.
Germany
Centralized laboratory networks around Frankfurt and Munich drive automated sterile pouch demand. EU MDR post-market surveillance requirements force suppliers to maintain granular material genealogy records. Contract packaging hubs cluster in Baden-Württemberg and Hesse to serve high-throughput molecular diagnostic workflows.
United States
FDA enforcement of 21 CFR Part 820 quality system regulations compresses supplier qualification timelines for diagnostic kit manufacturers. Point-of-care testing networks in retail clinics expand procurement of portable flexible formats. The Northeast corridor hosts legacy converters adapting to toll-manufacturing arrangements with multinational reagent producers.
China
NMPA medical device registration rules tighten documentation requirements for imported barrier systems used in domestic IVD production. Ambient-stable nucleic acid reagent volumes climb in the Yangtze River Delta. Shanghai and Suzhou concentrate film extrusion capacity serving both local diagnostic OEMs and export markets.
India
Pharmacy and retail clinic networks in Maharashtra and Karnataka adopt decentralized rapid diagnostic formats. CDSCO medical device rules impose traceability requirements on sterile barrier imports. Mumbai-Pune corridor contract packers scale automated pouch production for domestic IVD manufacturers.
Brazil
ANVISA medical device regulations align with international standards for sterile barrier validation. Point-of-care expansion in São Paulo and Minas Gerais drives minimal-footprint flexible packaging demand. Local converters partner with multinational diagnostic platforms to satisfy import substitution preferences.
Medical Diagnostic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Consolidation favors integrated packaging-service providers with validated ISO 11607-2 quality systems, while non-specialized converters face margin compression from dual regulatory and procurement pressures. Three archetypes dominate: global film extrusion specialists, integrated elastomer-containment experts, and regional contract packaging hubs. Competitive moves center on M&A for quality system assets and capacity expansion near centralized laboratory clusters.
Within the global substrate tier, Amcor Plc and DuPont de Nemours Inc. occupy positions anchored by multi-layer coextrusion capabilities serving multinational diagnostic OEMs. Among integrated containment specialists, West Pharmaceutical Services Inc. exemplifies the elastomer-primary packaging convergence required for molecular diagnostic consumables. Gerresheimer AG sits within the specialized primary container segment, representing glass and polymer expertise for in-vitro diagnostic reagents. These three illustrate how barrier performance validation, rather than structural protection alone, now determines competitive position.
| Leading Market Players |
|---|
| 3M Company |
| West Pharmaceutical Services Inc |
| Amcor Plc |
| Schott AG |
| Steris Plc |
| DuPont de Nemours Inc. |
| WestRock Company |
| Gerresheimer AG |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
Chinese aluminum foil smelters anchor upstream supply for multi-layer barrier films, concentrating margin capture among converters with validated ISO 11607-2 quality systems downstream. Diagnostic OEM procurement consolidation around Frankfurt-Munich and Yangtze River Delta clusters amplifies pricing power asymmetry between specialized sterile barrier suppliers and non-certified converters.
Pricing Analysis
Certification level (ISO 11607-2/FDA-grade/CE-marked) creates the primary spread across supplier tiers, with validated barrier systems commanding substantial premia over uncertified alternatives. Contract-based long-term offtake dominates procurement relationships as molecular diagnostic OEMs lock in supply security for nucleic acid reagent volumes. Price differentiation hinges on migration testing documentation depth and automated filling line compatibility. Cost compression in standard-grade pouches is intensifying because REACH Article 33 substance disclosure obligations extend European qualification timelines. High-throughput centralized laboratories exhibit lowest price sensitivity due to sterility assurance failure costs, while retail clinic networks in emerging markets remain most price-sensitive.
Supply Chain Analysis
Extended payment terms from multinational diagnostic OEMs force mid-tier converters toward supply-chain finance facilities backed by film extrusion specialists. Raw material supply concentrates in China for aluminum foil, Germany for medical-grade polymer compounding, and the United States for high-performance coextrusion equipment. Production draws from volatile aluminum feedstock, specialized resin formulations, and precision heat-seal validation systems. Single-source vulnerability runs through concentrated Chinese smelter capacity for sub-0.1 cc oxygen transmission substrates. Distribution runs through contract packaging hubs clustered around centralized laboratory networks in Germany, the United States, and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced barrier films threaten rigid glass and polymer vial incumbents as ambient-stable nucleic acid formulations gain regulatory traction. Incumbents must navigate substitution pressure while defending validated quality system moats against integrated packaging-service providers.
For Market Incumbents: Pre-empt displacement risk from film-based barrier systems by deepening elastomer-containment integration for molecular diagnostic consumables. Anchor capacity expansion in Baden-Württemberg and Hesse to capture EU MDR-driven replacement demand. Fortify ISO 11607-2 validation expertise as the priority defensive lever against non-specialized converters facing margin compression. For New Entrants and Emerging Players: Pharmacy and retail clinic networks in Maharashtra and São Paulo represent the most penetrable entry point for minimal-footprint flexible packaging formats. CDSCO and ANVISA regulatory alignment with international standards reduces qualification burden versus FDA or EU MDR pathways. Pursue toll-manufacturing arrangements with multinational reagent producers as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract packaging hubs in the Frankfurt-Munich corridor lacking in-house polymer compounding capabilities. Five-to-ten year viability hinges on EU Green Deal circularity mandate compliance and recyclable mono-material barrier design execution. Watch for first-mover announcements on digital watermark-sterile barrier convergence as the inflection signal for supply chain visibility premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11607-2 Quality System Certification | FDA enforcement of 21 CFR Part 820 compresses supplier qualification timelines for barrier validation. |
| Recyclable Mono-Material Barrier Development | EU Green Deal circularity mandates create first-mover advantage for sustainable sterile pouch designs. |
| Digital Watermark-Sterile Barrier Integration | Unit-level serialization convergence with heat-seal validation enables real-time supply chain visibility. |
| Capacity Expansion Near Laboratory Clusters | Contract packaging hub concentration around Frankfurt and Munich captures centralized network procurement. |
| Backward Integration into Polymer Compounding | In-house resin formulation control accelerates REACH Article 33 compliance and migration testing throughput. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and ISO 11607 validation records preceded structured interviews with diagnostic OEM procurement directors, sterile barrier quality engineers, contract packaging operations managers, and notified body auditors. Secondary sources included customs trade data for aluminum-laminate substrate flows, SEC filings from listed packaging converters, and German centralized laboratory network procurement databases. Bottom-up volume estimates from reagent manufacturer packaging specifications triangulated against top-down market sizing from barrier film extrusion capacity data.
Forecast assumptions held fixed the current EU MDR and FDA Unique Device Identification regulatory frameworks while varying point-of-care testing penetration rates and ambient-stable nucleic acid reagent adoption curves across the projection horizon. Segmentation modeling incorporated product type (sterile pouch, blister pack, tray, label), material composite specifications, end-user procurement authority concentration, and packaging structural flexibility. CAGRs derived from regression analysis of historical diagnostic kit volume growth against sterile barrier unit consumption ratios, with molecular diagnostic consumables expansion and decentralized testing channel development as primary demand drivers.
Practitioners should monitor NMPA medical device registration rule tightening, Extended Producer Responsibility framework implementation timelines, and aluminum foil supply concentration shifts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market