
 Molded Pulp Clinical Packaging Market | 2026-2036
Molded Pulp Clinical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Pulp Clinical Packaging Market Analytics
The gap between premium coated pulp and commodity recycled pulp offerings is expanding as clinical shippers demand divergent performance profiles. Huhtamaki Oyj leverages its European manufacturing footprint to dominate high-barrier coated pulp production for temperature-sensitive biologics. Brodrene Hartmann A/S anchors the recycled pulp segment through scale advantages in molded fiber tray production for pharmaceutical distribution.
Molded pulp clinical packaging comprises fiber-based containers, trays, and protective structures formed under heat and pressure from recycled or virgin cellulose pulp, often enhanced with moisture-resistant coatings to meet ISO 11607 sterilization requirements. The primary purpose centers on protecting vials, syringes, and medical devices during transit while replacing petroleum-based alternatives. Recycled pulp occupies the volume base as cost-sensitive pharmaceutical logistics prioritize circular material streams, while coated pulp captures expanding margin pools as biologics shippers require validated moisture and microbial barrier performance. Trays lead product type demand due to standardized nesting geometries that optimize automated filling lines across diagnostics and vaccine manufacturing.
FDA sterility assurance guidelines, EU MDR packaging validation requirements, and ISO 11607 standards collectively elevate barrier documentation burdens for molded pulp entrants seeking clinical qualification. REACH restrictions on perfluorinated coatings are forcing material reformulation investments across European supply chains. Stakeholders must monitor coating chemistry transitions and regional regulatory divergence to preserve market access across jurisdictions.
Market Dynamics
The EU Green Deal's packaging waste reduction mandates are compressing adoption timelines for petroleum-based clinical packaging across European pharmaceutical logistics networks. FDA sterility assurance guidelines simultaneously elevate documentation burdens for molded pulp entrants seeking US market qualification.
Growth Catalysts
- EU MDR packaging validation requirements:The European Medical Device Regulation mandates documented barrier performance for sterile packaging, accelerating pharmaceutical manufacturer migration from plastic trays to validated coated pulp alternatives.
- Biologics cold chain expansion:Temperature-sensitive monoclonal antibody and cell therapy shipments require moisture-resistant fiber-based protection that maintains structural integrity across freeze-thaw cycles.
- Japan's plastic resource circulation strategy:METI enforcement of healthcare sector single-use plastic reduction targets is redirecting domestic syringe and vial distribution toward molded fiber tray systems.
Market Restraints
- Recycled pulp input cost volatility:Post-consumer OCC (old corrugated containers) fiber prices fluctuate with municipal recycling collection rates, compressing margin predictability for commodity tray manufacturers.
- Coating chemistry supply concentration:European fluorine-free barrier coating production clusters in Germany and Finland, creating geographic single-source risk for compliant clinical-grade materials.
- ISO 11607 sterilization validation timelines:The 18-24 month qualification cycle for new molded pulp formats delays revenue recognition and ties up R&D capital.
Strategic Opportunities
- India CDMO packaging localization:Contract development and manufacturing organization expansion under India's PLI scheme creates demand for domestically produced clinical trays that avoid import duty exposure.
- Home healthcare kit assembly:Direct-to-patient injection device distribution requires compact, curbside-recyclable protective packaging formats that replace expanded polystyrene.
- EMA sustainable packaging guidelines:Draft environmental criteria for marketing authorization applications position fiber-based primary packaging as a regulatory preference signal.
Industry Challenges
- Barrier coating R&D talent scarcity:Formulation chemists with combined expertise in cellulose fiber chemistry and pharmaceutical microbial barrier validation command premium compensation and extended search timelines.
- Legacy thermoforming asset stranding:Pharmaceutical contract packers face write-down pressure on existing plastic tray production lines as customer specifications pivot to fiber-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Pulp Clinical Packaging Market |
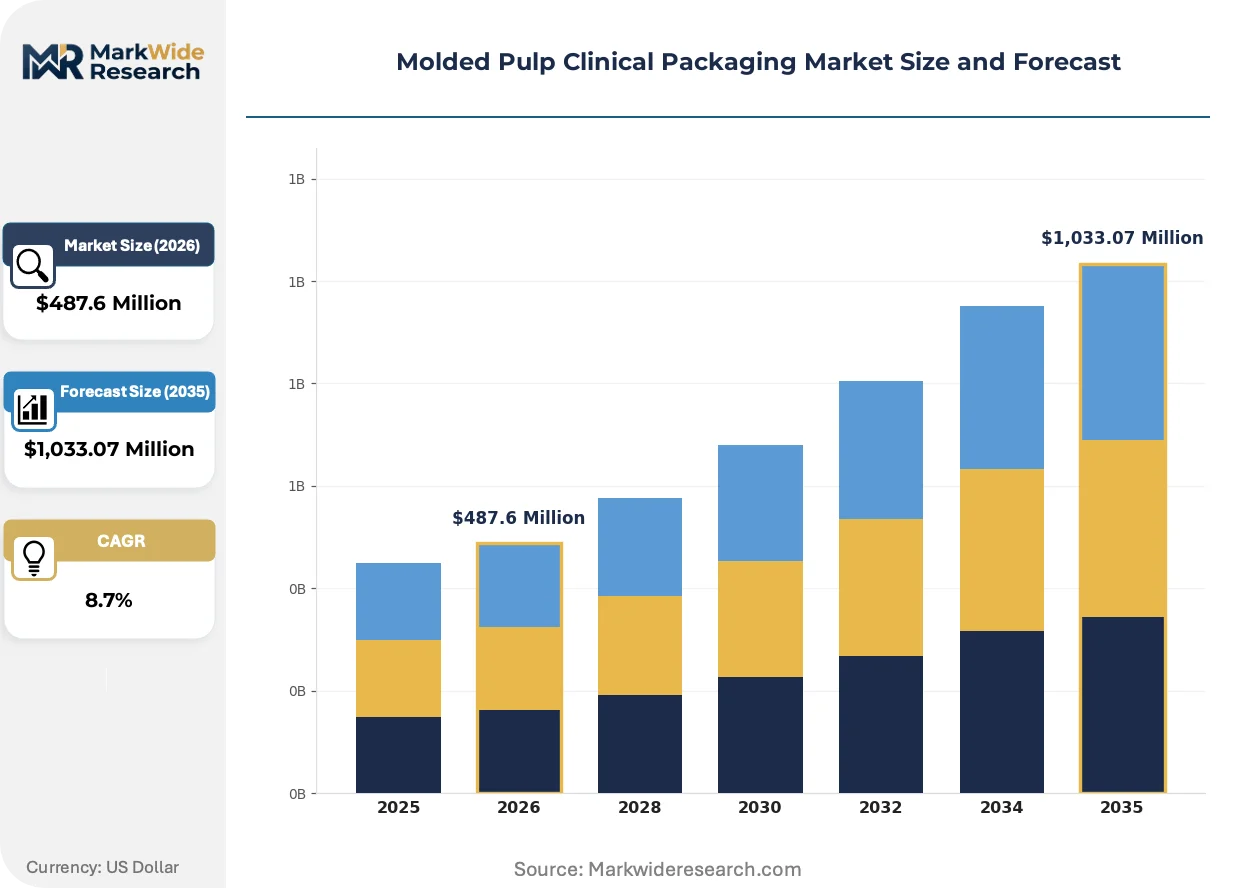
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Holders, Containers, Other End User: Pharmaceuticals, Biologics, Medical Devices, Diagnostics Material: Recycled Pulp, Virgin Pulp, Coated Pulp, Blended Pulp Application: Packaging Solutions, Shipping, Storage, Display |
| Companies Covered | UFP Technologies, Inc., Huhtamaki Oyj, Brodrene Hartmann A/S, Sonoco Products Company, Sabert Corporation, Genpak LLC, Smurfit Kappa, WestRock Company, Pactiv Evergreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Pulp Clinical Packaging Market Evolving Landscape
Barrier coating chemistry is the active frontier reshaping competitive positioning. Material scientists and pharmaceutical quality assurance teams are converging on fluorine-free formulations that satisfy both REACH restrictions and FDA sterility assurance benchmarks.
Alkyl ketene dimer (AKD) and alkenyl succinic anhydride (ASA) sizing agents are absorbing the functional load previously carried by perfluorinated chemicals in high-barrier clinical applications. Biologics shippers in Germany and Switzerland are qualifying these chemistries for moisture-sensitive parenteral packaging. The shift is absorbing margin from coating suppliers while compressing qualification timelines for pulp tray manufacturers.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing material reformulation investments across European pharmaceutical supply chains. The ECHA ban timeline accelerates R&D spending on alternative barrier technologies. Coated pulp tray producers serving EMA-regulated products face the steepest compliance curve.
Pharmaceutical procurement teams are consolidating supplier panels around vertically integrated fiber-based packaging specialists. Large molecule manufacturers in Massachusetts and North Carolina are reducing qualified vendor counts from twelve to four. This concentration is most visible among CDMOs serving late-phase clinical trials where packaging change control documentation carries the highest switching cost.
Molded Pulp Clinical Packaging Market Segmentation
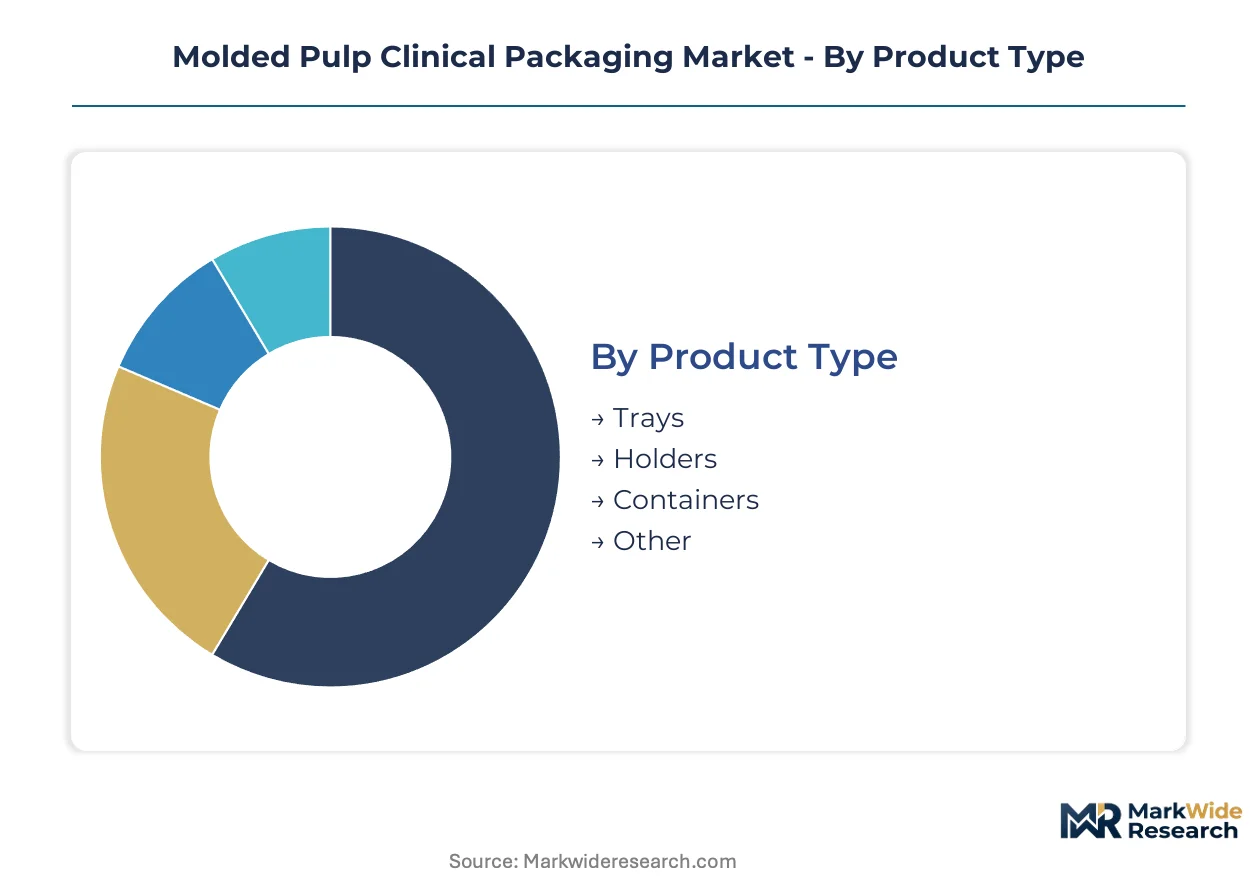
Molded pulp clinical packaging serves divergent performance requirements across pharmaceutical logistics, biologics cold chains, and diagnostic distribution networks. Segmentation reveals how material chemistry and product geometry align with specific sterilization validation burdens and automation compatibility demands.
Product Type:
Production capacity clusters around standardized geometries that minimize tooling investment while maximizing line speed for pharmaceutical contract packers.
- Trays:Nesting designs with precision-molded cavities accommodate automated vial and syringe filling lines across vaccine manufacturing facilities. German and Swiss biologics manufacturers specify these formats for temperature-sensitive monoclonal antibody shipments requiring validated dimensional stability through freeze-thaw cycles.
- Holders:Custom-engineered retention structures secure irregular medical device geometries during transit. Demand concentrates among orthopedic implant distributors in the United States seeking drop-test certification for heavy metallic components.
- Containers:Deep-drawn fiber structures with integrated lids serve bulk API powder handling and intermediate pharmaceutical processing steps.
- Other:Specialty formats including corner protectors and edge guards address niche protective packaging requirements for glass primary containers.
Trays absorb the bulk of installed capacity; containers are expanding most quickly as bulk biologics processing scales.
End User:
Customer procurement patterns separate validated sterile barrier requirements from cost-optimized diagnostic distribution economics.
- Pharmaceuticals:Small molecule and generic drug manufacturers prioritize OCC-based recycled pulp trays for high-volume oral solid dose packaging where moisture sensitivity is moderate. FDA packaging validation documentation drives supplier consolidation toward established coated pulp producers with existing drug master files.
- Biologics:Cell therapy and gene therapy developers specify high-barrier coated pulp with fluorine-free chemistry to protect parenteral products across cryogenic shipping lanes. Massachusetts and North Carolina manufacturing clusters are qualifying these formats for commercial launch packaging.
- Medical Devices:Sterile single-use instrument kits require fiber-based alternatives to expanded polystyrene that satisfy EU MDR environmental criteria for marketing authorization.
- Diagnostics:High-throughput PCR test and reagent strip distribution prioritizes commodity recycled pulp formats with minimal coating cost for single-use consumable protection.
Pharmaceuticals command the greatest volume; biologics is gaining share fastest on cold chain expansion.
Material:
Input fiber sourcing and barrier chemistry investments determine margin structure and regulatory compliance trajectory across supply chains.
- Recycled Pulp:Post-consumer OCC fiber delivers lowest unit cost for diagnostic tray production where ISO 11607 barrier requirements are less stringent. Japanese healthcare distributors are migrating syringe logistics toward these formats under METI plastic reduction mandates.
- Virgin Pulp:Bleached kraft fiber provides consistent brightness and cleanliness for medical device packaging where visual contamination standards exceed recycled stream capabilities.
- Coated Pulp:AKD and ASA sizing agents replace legacy fluorinated barriers for moisture-sensitive biologics applications. REACH PFAS restrictions are accelerating qualification timelines for these chemistries across EMA-regulated products.
- Blended Pulp:Engineered fiber combinations balance cost and performance for mid-tier pharmaceutical applications requiring moderate barrier properties.
Recycled pulp dominates volume throughput; coated pulp is climbing the fastest on regulatory chemistry transitions.
Application:
Functional use case determines structural design priorities from nesting density through drop-test performance specifications.
- Packaging Solutions:Primary and secondary sterile barrier systems for vial, syringe, and device presentation. German pharmaceutical manufacturers specify these for EU MDR-compliant commercial launches.
- Shipping:Transit protection formats engineered for ISTA 3A distribution simulation testing. United States CDMOs are adopting these for cross-country biologics lane qualification.
- Storage:Long-term warehousing trays with stack-load compression resistance for inventory holding prior to distribution.
- Display:Retail-facing formats for over-the-counter pharmaceutical and diagnostic product presentation with printed branding surfaces.
Packaging solutions represent the deepest capacity commitment; shipping is expanding most quickly on direct-to-patient distribution growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors biologics packaging qualification activity, with Cambridge-Boston corridor manufacturers validating coated pulp formats for monoclonal antibody cold chains. Pharmaceutical contract packers across three continents are consolidating supplier panels around fiber-based alternatives.
United States
FDA sterility assurance guidelines drive pharmaceutical manufacturers toward validated coated pulp documentation. CDMOs in North Carolina and Massachusetts reduce qualified vendor counts from twelve to four for late-phase clinical trial packaging. Boston-Cambridge biologics clusters are qualifying fluorine-free barrier chemistries for commercial launch formats.
Germany
EU MDR packaging validation requirements accelerate migration from plastic trays to documented barrier alternatives. REACH PFAS restrictions force coating reformulation investments across pharmaceutical supply chains. Bavarian and Baden-Württemberg manufacturing corridors concentrate high-barrier coated pulp production for temperature-sensitive shipments.
Japan
METI enforcement of healthcare single-use plastic reduction redirects syringe and vial distribution toward molded fiber systems. Domestic pharmaceutical logistics prioritize circular material streams under plastic resource circulation strategy. Osaka-Tokyo industrial belt manufacturers specify recycled pulp trays for diagnostic consumable protection.
India
CDMO expansion under PLI scheme creates demand for domestically produced clinical trays avoiding import duty exposure. National pharmaceutical regulator packaging validation requirements align with ISO 11607 standards for sterile barrier qualification. Maharashtra and Gujarat pharmaceutical manufacturing zones localize molded pulp capacity for export-oriented production.
Switzerland
Swissmedic sterility guidelines elevate barrier documentation burdens for molded pulp entrants seeking market qualification. Basel biopharma manufacturing cluster demands moisture-resistant fiber protection validated across cryogenic shipping lanes. Domestic shippers specify AKD and ASA sizing agents replacing legacy fluorinated barriers for parenteral products.
Molded Pulp Clinical Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors. The vendor base separates into European coating chemistry specialists, Nordic recycled pulp scale operators, and North American integrated packaging converters. Three archetypes dominate: vertically integrated fiber-based packaging specialists with captive pulp supply, regional contract manufacturers serving single-country pharmaceutical logistics, and coating technology licensors supplying barrier chemistry to third-party molders. Consolidation concentrates around capacity expansion in Germany and Finland, while strategic partnerships bridge coating chemistry gaps for commodity tray producers.
Among European manufacturers, Huhtamaki Oyj and Brodrene Hartmann A/S occupy distinct tier positions representing coating-intensive and recycled volume archetypes respectively. UFP Technologies, Inc. anchors North American specialist positioning. These three exemplify how geographic manufacturing footprint and pulp sourcing strategy determine competitive access to biologics versus diagnostic customer segments.
| Leading Market Players |
|---|
| UFP Technologies, Inc. |
| Huhtamaki Oyj |
| Brodrene Hartmann A/S |
| Sonoco Products Company |
| Sabert Corporation |
| Genpak LLC |
| Smurfit Kappa |
| WestRock Company |
| Pactiv Evergreen |
| Others |
Value Network & Pricing Analysis
Post-consumer OCC fiber index volatility cascades through molded pulp clinical packaging supply chains, compressing margin predictability for commodity tray manufacturers while amplifying pricing power for coated pulp specialists with captive barrier chemistry supply. Pharmaceutical procurement teams exploit this bifurcation to extract volume discounts from recycled pulp producers while paying premiums for validated sterile barrier formats.
Pricing Analysis
Barrier validation documentation anchors value-based pricing tiers across the market. Three-tier pricing structure across premium, standard, and economy levels separates fluorine-free coated pulp for biologics from commodity recycled trays for diagnostics and virgin pulp formats for medical devices. Cost compression in the recycled segment is intensifying because municipal OCC collection rate fluctuations feed directly into input cost uncertainty. Diagnostic distributors exhibit highest price sensitivity, while biologics manufacturers prioritize barrier performance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA sterility assurance guidelines and EU MDR packaging validation force pharmaceutical manufacturers to qualify redundant coated pulp suppliers across Germany, Finland, and the United States. Raw material dependencies center on bleached kraft pulp from Nordic mills, AKD and ASA sizing agents from German chemical producers, and post-consumer OCC fiber from municipal recycling streams. Single-source vulnerability concentrates in European fluorine-free barrier coating production clusters. Distribution runs through pharmaceutical contract packers serving CDMO networks and direct-to-patient logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded pulp clinical packaging market sits in a technology-transition phase as fluorine-free barrier chemistries displace legacy perfluorinated coatings under REACH restrictions. AKD and ASA sizing agents are absorbing the functional load previously carried by PFAS in high-barrier applications.
For Market Incumbents: Extend coating chemistry R&D capabilities into fluorine-free formulations to defend against regulatory obsolescence of legacy barriers. Backward integration into captive pulp supply secures input cost stability against OCC fiber index volatility. Capacity expansion in Germany and Finland preserves access to EMA-regulated biologics customers facing the steepest compliance curves. For New Entrants and Emerging Players: Enter via India's CDMO packaging localization opportunity under the PLI scheme, where import duty exposure creates white-space for domestic tray production. Home healthcare kit assembly for direct-to-patient injection devices offers penetrable demand for compact, curbside-recyclable formats replacing expanded polystyrene. Partner with regional pharmaceutical logistics specialists to bypass incumbent qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor coating technology licensors with validated AKD and ASA formulations in Germany and Switzerland, where regulatory chemistry transitions compress valuations for non-compliant asset bases. Long-term viability hinges on barrier validation documentation depth rather than molding capacity scale. Watch EMA sustainable packaging guideline finalization as inflection signal for fiber-based primary packaging preference.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating Qualification | AKD and ASA sizing agent validation satisfies REACH restrictions and FDA sterility benchmarks for biologics. |
| Backward Integration into Pulp Supply | Captive OCC fiber sourcing insulates margin predictability from municipal recycling collection volatility. |
| CDMO Partnership Consolidation | Reduced vendor counts from twelve to four lock in late-phase clinical trial packaging change control. |
| India Manufacturing Localization | Domestic tray production under PLI scheme avoids import duty exposure for export-oriented pharmaceutical manufacturing. |
| Home Healthcare Format Development | Compact curbside-recyclable designs replace expanded polystyrene in direct-to-patient injection device distribution. |
Research Methodology
Trade association filings, ECHA regulatory databases, and pharmaceutical packaging validation records formed the secondary backbone for this analysis. Primary interviews with quality assurance directors at biologics manufacturers, procurement leads at pharmaceutical CDMOs, barrier coating formulation chemists, and sterile packaging validation consultants combined with secondary triangulation. Bottom-up modeling of installed molding capacity and top-down demand estimation from pharmaceutical logistics expenditure patterns were cross-referenced for consistency.
Bottom-up volume modeling tracked individual production facility capacities across Germany, Finland, and the United States, while top-down validation referenced pharmaceutical packaging procurement expenditure patterns across the analysis window. Segmentation dimensions included product type, material chemistry, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical adoption curves and regulatory mandate implementation timelines. Forecast inputs incorporated EU MDR packaging validation requirement phase-in schedules and METI plastic reduction enforcement intensity.
Revisions become necessary when REACH PFAS restriction timelines accelerate, FDA sterility assurance guidelines expand documentation burdens, or biologics cold chain shipping lane qualifications shift toward alternative barrier formats. Deviation in coating chemistry supply concentration or OCC fiber index volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market