
 Global Medical Devices Packaging Market | 2026-2036
Global Medical Devices Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Devices Packaging Market Foresight
The gap between premium sterilizable barrier systems and commodity-grade packaging is expanding as OEMs dual-source across performance tiers. Amcor plc leverages its global film extrusion network to sustain high-volume supply contracts for diagnostic consumables. Berry Global Group anchors North American pouch capacity while competing on multi-layer coextrusion technology for surgical kits.
Medical devices packaging encompasses sterile barrier systems, protective enclosures, and distribution containers engineered to maintain device functionality, prevent contamination, and ensure patient safety through validated sealing integrity and material biocompatibility. Pouch and blister pack formats dominate unit volume due to compatibility with gamma and ethylene oxide sterilization cycles, while Tyvek-laminated structures command margin pools in implantable device applications where FDA 510(k) sterilization validation is mandatory. Rigid containers lead in orthopedic implant logistics where dimensional stability protects high-value instrument sets through global distribution.
FDA enforces 21 CFR Part 820 quality system regulations and ISO 11607 compliance for sterile barrier validation, directly shaping material selection and testing protocols for US market access. EMA's Medical Device Regulation and REACH chemical restrictions in Europe compound formulation complexity, forcing suppliers to maintain dual-certified resin streams. Japan's PMDA and METI coordinate on foreign manufacturer registration and Japan Pharmacopoeia packaging standards, adding a third compliance layer for Asia-Pacific entry. Stakeholders must monitor evolving sterilization modality shifts from ethylene oxide to vaporized hydrogen peroxide as device OEMs redesign for reduced environmental footprints.
Market Dynamics
Sterilization modality migration from ethylene oxide to vaporized hydrogen peroxide is forcing material reformulation across sterile barrier systems, compressing validation timelines and fragmenting supplier qualification pools.
Growth Catalysts
- Point-of-care diagnostic expansion:Decentralized testing networks in Germany and the United States are pulling high-volume pouch formats into ambulatory settings, accelerating unit demand for gamma-stable materials.
- FDA 21 CFR Part 820 enforcement:Quality system tightening is elevating certified sterile barrier suppliers above uncertified competitors, concentrating contract awards among dual-ISO 11607 validated producers.
- Tyvek-laminate adoption for implantables:FDA 510(k) sterilization validation requirements for cardiovascular and orthopedic implants are locking in premium material specifications that resist commodity substitution.
Market Restraints
- Medical-grade resin concentration:Polypropylene and cyclic olefin polymer supply chains cluster among Gulf Coast petrochemical complexes, exposing converters to hurricane disruption and force majeure risk.
- REACH chemical restriction cascade:ECHA's expanding substance of very high concern list is eliminating legacy plasticizers and stabilizers faster than replacement chemistry achieves biocompatibility certification.
- Ethylene oxide capacity contraction:EPA emissions enforcement is shuttering regional sterilization facilities, forcing device OEMs to absorb freight costs for cross-country sterilization logistics.
Strategic Opportunities
- Brazil ANVISA registration acceleration:Mercosur harmonization is reducing technical barrier duplication for sterile barrier exporters, opening Latin American surgical kit supply contracts previously captured by local converters.
- Vaporized hydrogen peroxide material compatibility:Polymer scientists are engineering seal-layer chemistries that withstand oxidative sterilization without Tyvek dependency, unlocking cost reduction for mid-tier device categories.
- Japan PMDA foreign manufacturer registration streamlining:METI digital submission pilots are compressing approval timelines for imported sterile barriers, enabling direct supply to Japanese orthopedic OEMs without local agent intermediation.
Industry Challenges
- ISO 11607-1 validation engineering scarcity:Sterile barrier design verification and accelerated aging protocol expertise concentrates among retiring specialists, constraining new product introduction capacity at mid-tier converters.
- Multi-jurisdiction certification synchronization:Simultaneous FDA 510(k), EMA MDR technical documentation, and Japan Pharmacopoeia compliance requires parallel testing streams that extend commercialization timelines.
- Legacy ethylene oxide sterilization asset stranding:Device OEMs with captive EtO facilities face accelerated depreciation pressure as vaporized hydrogen peroxide and e-beam alternatives achieve validation equivalence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Devices Packaging Market |
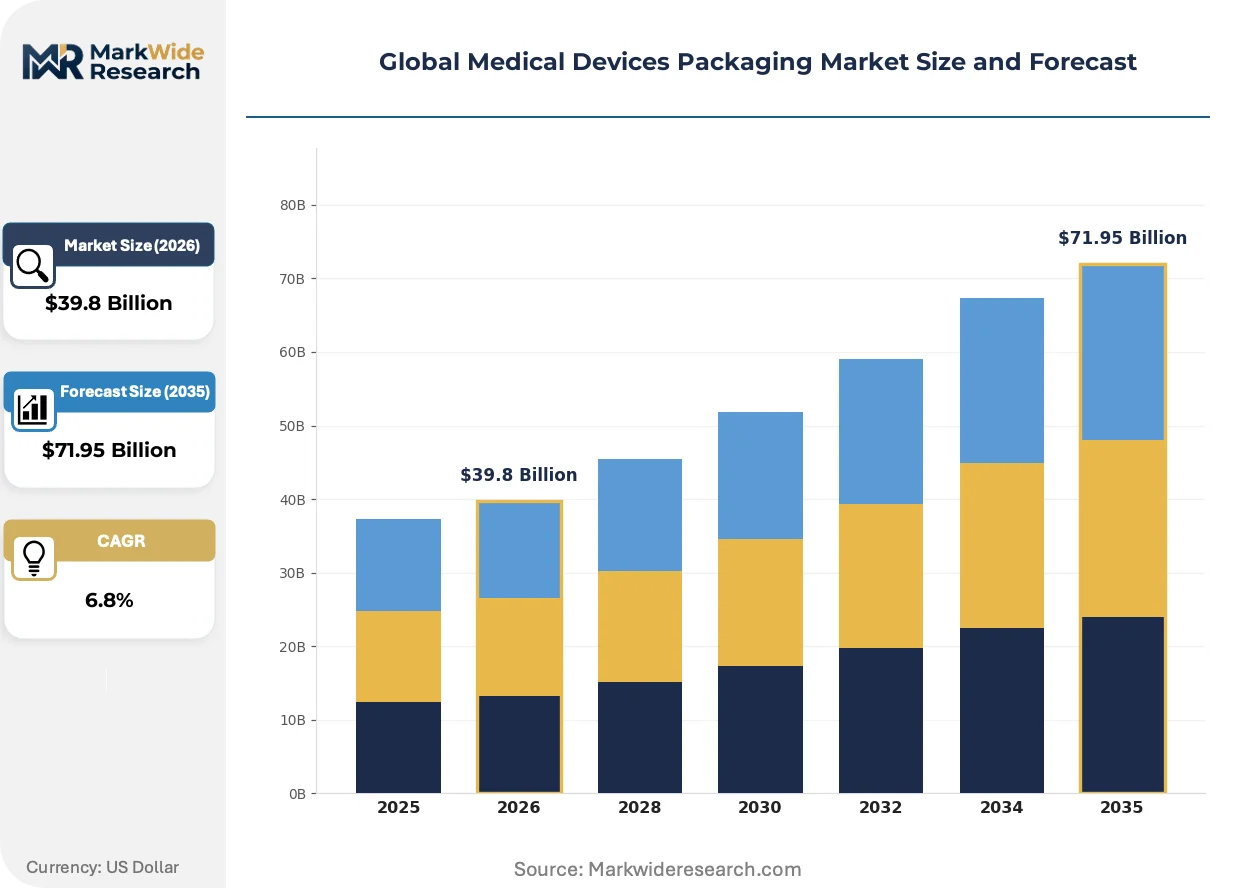
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $71.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Clamshells, Pouches, Rigid Containers, Vials Material: Polyethylene, Polyvinyl Chloride, Tyvek, Polypropylene, Foil Laminates Application: Diagnostics, Surgical Instruments, Drug Delivery, Monitoring Devices, Orthopedic Implants End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Labs, Specialty Clinics, Research Institutions |
| Companies Covered | Amcor plc, Berry Global Group, Sonoco Products Company, DuPont de Nemours, Sealed Air Corporation, 3M Company, West Pharmaceutical Services, SteriPack, Oliver Healthcare Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Devices Packaging Market Shifts & Advancements
Material science convergence with sterilization technology is redefining performance benchmarks across sterile barrier categories, compressing the gap between validated medical-grade systems and industrial packaging alternatives.
Multi-layer coextrusion with ethylene vinyl alcohol oxygen barriers is integrating high-performance passive protection into thermoformable films previously limited to simple polyolefin structures. Cardiovascular device OEMs in Switzerland and the Netherlands are adopting these structures for implantable pacemaker packaging, displacing legacy foil laminates that required hand-finished sealing. This integration is compressing unit costs for premium sterile barriers while maintaining ISO 11607 seal-strength requirements.
EMA's Medical Device Regulation (MDR) Annex I general safety and performance requirements are mandating post-market clinical follow-up data that traces back to packaging lot records. Sterile barrier suppliers must now implement unique device identification-compatible labeling and electronic data interchange connectivity that FDA 21 CFR Part 820 did not explicitly require. European orthopedic and wound care segments are responding by consolidating supplier bases to those with validated serialization infrastructure.
Hospital procurement consolidation through group purchasing organizations is compressing sterile barrier supplier margins while elevating technical service requirements. United States health system purchasing alliances are unbundling packaging specification development from material supply, forcing converters to maintain dedicated clinical engineering liaison staff. This pattern is most visible in the southeastern United States, where Catholic health system networks and for-profit hospital chains have centralized sterile processing department contracting.
Global Medical Devices Packaging Market Segmentation
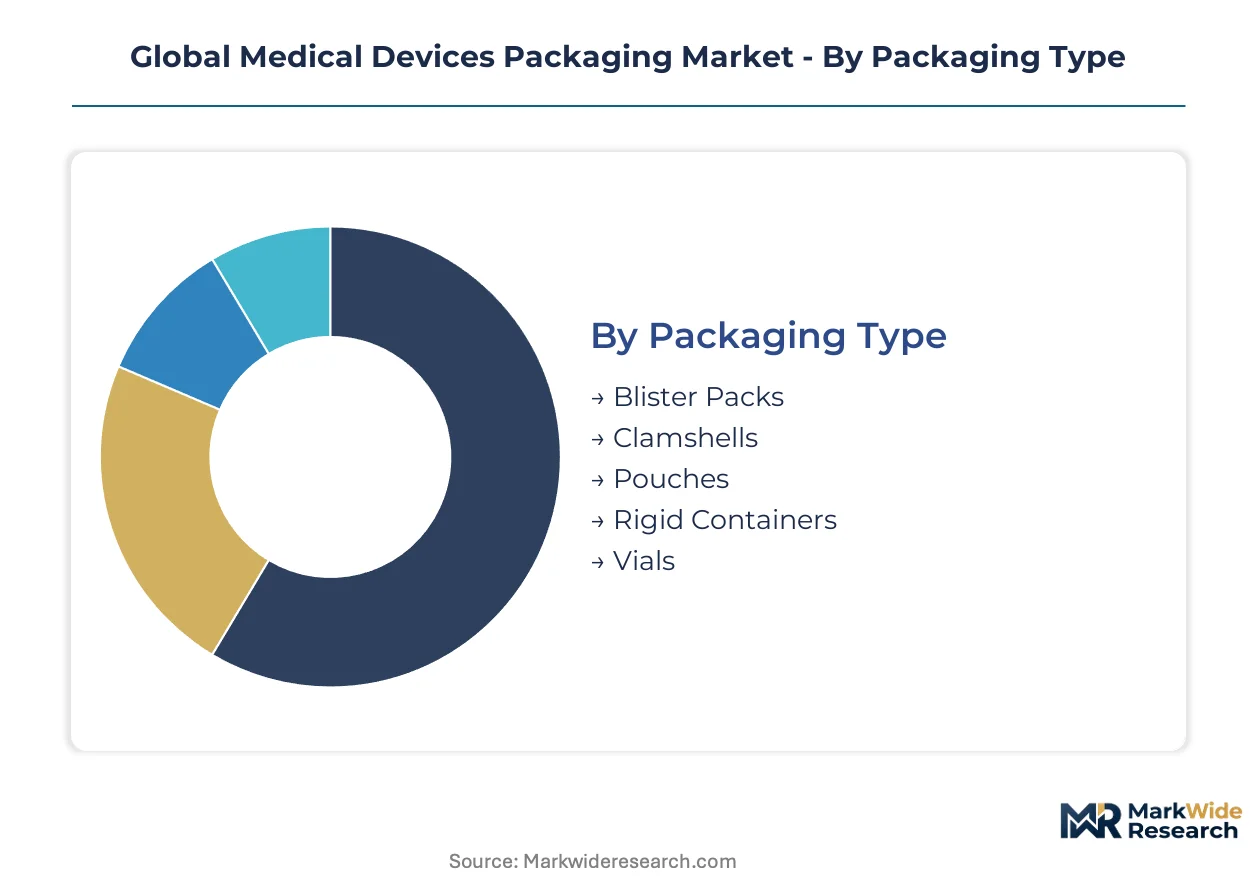
Segmentation in medical devices packaging reveals how sterilization modality, material specification, and end-use environment fragment supply chains. Each category carries distinct regulatory burdens and margin structures that reshape competitive positioning across OEM procurement decisions.
Packaging Type:
Supply concentration for sterile barrier formats clusters among North American and European converters with validated ISO 11607 production lines.
- Pouches:Multi-layer coextruded films with Tyvek or medical-grade paper lidding dominate gamma and ethylene oxide sterilization workflows. Diagnostic labs in Germany and ambulatory surgical centers in the United States pull high volumes of peelable pouch formats for point-of-care testing expansion.
- Blister Packs:Thermoformed cavities with lidding foil structures protect single-use devices through distribution. Cardiovascular OEMs in Switzerland specify these for pacemaker and stent delivery systems where dimensional precision meets FDA 510(k) validation requirements.
- Rigid Containers:Injection-molded polymer shells with silicone gasket seals protect orthopedic instrument sets through repeated sterilization cycles. These command premium positioning in hospital sterile processing departments.
- Clamshells:Two-piece hinged designs serve non-sterile protective applications for durable medical equipment distribution.
- Vials:Borosilicate glass or cyclic olefin polymer containers house liquid and lyophilized drug-device combination products.
Today's leader: Pouches. Tomorrow's challenger: Rigid containers as orthopedic OEMs consolidate instrument kit logistics.
Material:
Cost tier stratification separates implant-grade specifications from commodity diagnostic packaging across resin and laminate selections.
- Tyvek:Flash-spun high-density polyethylene provides breathable sterile barrier performance with superior tear resistance. FDA 510(k) sterilization validation for cardiovascular and orthopedic implants locks in this specification despite premium positioning.
- Polypropylene:Biaxially oriented and cast film variants offer clarity and heat-seal compatibility for pouch and tray applications. Gulf Coast petrochemical concentration exposes converters to hurricane disruption risk.
- Foil Laminates:Aluminum-polymer multilayer structures deliver oxygen and moisture barrier protection for moisture-sensitive devices.
- Polyethylene:Low-density and linear low-density grades serve cost-sensitive diagnostic consumable packaging.
- Polyvinyl Chloride:Rigid and flexible formulations face REACH chemical restriction pressure across European markets.
Current margin concentration sits with Tyvek laminates for implantables; polyethylene is gaining share fastest in high-volume diagnostic segments.
Application:
Volume distribution across medical device categories tracks procedure reimbursement rates and sterilization modality standardization.
- Diagnostics:Test kits, reagent containers, and sample collection devices require gamma-stable materials compatible with high-throughput automated packaging lines. Point-of-care expansion in the United States and Germany accelerates unit demand for pouch and blister formats.
- Surgical Instruments:Sterile barrier systems for reusable and single-use instruments must withstand steam, ethylene oxide, or vaporized hydrogen peroxide sterilization cycles. Hospital consolidation through group purchasing organizations compresses supplier margins while elevating technical service requirements.
- Drug Delivery:Prefilled syringes, auto-injectors, and inhalation devices combine primary drug contact materials with secondary protective packaging.
- Monitoring Devices:Continuous glucose monitors and wearable sensors demand moisture barrier protection with patient-friendly opening features.
- Orthopedic Implants:Joint replacement and spinal hardware packaging requires dimensional stability through global distribution logistics.
Diagnostics leads unit volume; surgical instruments present the steepest expansion trajectory as ambulatory settings proliferate.
End User:
Customer type determines packaging specification complexity, with hospital procurement consolidation reshaping supplier relationship economics.
- Diagnostic Labs:High-throughput reference laboratories and decentralized testing networks specify standardized pouch formats for workflow efficiency. Automated opening and waste minimization drive material selection in Germany and the United States.
- Hospitals:Integrated delivery networks and Catholic health system alliances in the southeastern United States centralize sterile processing department contracting. These buyers unbundle specification development from material supply, forcing converter investment in clinical engineering liaison staff.
- Ambulatory Surgical Centers:Freestanding procedure facilities prioritize compact, lightweight packaging for inventory efficiency and freight cost reduction.
- Specialty Clinics:Ophthalmology, dermatology, and wound care practices specify procedure-specific kit packaging with simplified opening protocols.
- Research Institutions:Preclinical and clinical trial packaging requires lot-level traceability and temperature excursion documentation.
Hospital networks dominate contract value; diagnostic labs are climbing the fastest as point-of-care testing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sterile barrier engineers concentrate in southern Germany, Massachusetts, and Osaka-Kobe, anchoring the technical workforce that validates multi-jurisdiction packaging systems for cardiovascular and orthopedic OEMs.
United States
Diagnostic lab networks in North Carolina's Research Triangle and Boston's Route 128 corridor pull gamma-stable pouch formats into decentralized testing workflows. FDA 21 CFR Part 820 enforcement elevates certified suppliers above uncertified competitors in contract awards. Minnesota's Twin Cities host sterile barrier validation laboratories serving Medtronic and Boston Scientific.
Germany
Point-of-care expansion in Bavaria and Baden-Württemberg accelerates unit demand for automated packaging lines serving Roche and Siemens Healthineers. EMA MDR Annex I mandates post-market clinical follow-up data tracing back to packaging lot records. Freiburg's medical technology cluster concentrates Tyvek-laminate converting capacity for implantable devices.
Japan
Orthopedic OEMs in Osaka and Kobe specify rigid containers for instrument sets distributed through Asia-Pacific logistics hubs. PMDA foreign manufacturer registration requirements add compliance layers for imported sterile barriers. Tokyo's Koto ward hosts sterilization validation facilities coordinating with METI on digital submission pilots.
Switzerland
Cardiovascular device manufacturers in Zurich and Basel adopt multi-layer coextruded films with ethylene vinyl oxygen barriers for pacemaker packaging. Swissmedic maintains alignment with EMA MDR while preserving distinct national certification pathways. Jura Arc industrial corridor concentrates precision thermoforming capacity for implant-grade blister packs.
China
Domestic device OEMs in Suzhou and Shenzhen are localizing sterile barrier supply chains previously dependent on imported Tyvek structures. NMPA medical device registration reforms compress approval timelines for packaging materials. Yangtze River Delta medical device parks attract converters establishing dual-certified production for export markets.
Global Medical Devices Packaging Market Competitive Landscape
Top-tier vendors anchor high-volume sterile barrier supply for multinational device OEMs, while mid-tier converters compete on regional certification agility and specialized application expertise. The market structure concentrates among North American and European players with validated ISO 11607 production networks. Three archetypes dominate: integrated material-converter conglomerates, sterile barrier specialists, and diversified industrial packaging firms with medical-grade certifications. Competitive moves center on multi-layer coextrusion technology licensing and sterilization modality compatibility expansion.
Within the integrated material-converter tier, Amcor plc and Berry Global Group represent archetypes of global film extrusion networks sustaining high-volume diagnostic consumable contracts. Sonoco Products Company exemplifies the diversified industrial player with medical-grade certification depth. These three occupy positions spanning premium implantable specifications through commodity diagnostic pouch formats, with geographic footprints concentrated in North American and European manufacturing clusters.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Sonoco Products Company |
| DuPont de Nemours |
| Sealed Air Corporation |
| 3M Company |
| West Pharmaceutical Services |
| SteriPack |
| Oliver Healthcare Packaging |
| Others |
Supply & Pricing Matrix
Sterile barrier validation engineers concentrated in southern Germany, Massachusetts, and Osaka-Kobe command wage premiums that widen spreads between ISO 11607-certified premium tiers and uncertified commodity alternatives. Labor-cost differentials across these technical clusters directly feed into pricing-tier stratification as OEMs dual-source across performance levels.
Pricing Analysis
The bundled-vs-unbundled service split separates specification development from material supply across hospital procurement contracts. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 11607 validation depth and Tyvek-laminate adoption for implantables. Price differentiation hinges on FDA 510(k) sterilization validation status and multi-layer coextrusion complexity. Margins are tightening in commodity diagnostic pouches as group purchasing organizations consolidate contract awards. Ambulatory surgical centers exhibit highest price sensitivity; cardiovascular implant OEMs show least.
Supply Chain Analysis
Regional distribution centers in Memphis, Rotterdam, and Singapore anchor hub-and-spoke patterns for sterile barrier logistics. Raw material concentration in United States Gulf Coast polypropylene complexes, German Tyvek converting facilities, and Japanese cyclic olefin polymer producers creates geographic dependencies. Medical-grade resin supply rests on petrochemical feedstock stability and hurricane exposure. Single-source vulnerability concentrates in flash-spun high-density polyethylene for breathable barriers. Distribution runs through validated cold-chain networks serving hospital sterile processing departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder underpinned by irreversible regulatory compliance burdens that perpetually elevate certified suppliers above uncertified competitors.
For Market Incumbents: Anticipate vaporized hydrogen peroxide sterilization modality shifts by engineering seal-layer chemistries that withstand oxidative cycles without Tyvek dependency. Deepen backward integration into medical-grade resin compounding to secure Gulf Coast supply disruptions. ISO 11607-1 validation engineering scarcity among retiring specialists threatens new product introduction capacity.
For New Entrants and Emerging Players: Digital submission pilots at Japan's METI compress foreign manufacturer registration timelines for direct orthopedic OEM supply without local agent intermediation. Target Brazil ANVISA registration acceleration under Mercosur harmonization for surgical kit contracts previously captured by local converters. White-space exists in mid-tier device categories seeking cost-reduced alternatives to premium sterile barriers.
For Investors and Strategic Acquirers: Device OEMs with captive ethylene oxide sterilization assets are the most active acquirer in this space as they face accelerated depreciation pressure from vaporized hydrogen peroxide validation equivalence. Five-to-ten year viability favors converters with dual-certified resin streams for FDA and EMA parallel compliance. Acquisition target archetype: mid-tier converters with ISO 11607 validation infrastructure and sparse sterilization modality compatibility. Signal to monitor: EPA emissions enforcement shuttering additional regional EtO facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Sterilization Validation | Locks premium material specifications for cardiovascular implants against commodity substitution. |
| EMA MDR Technical Documentation | Mandates post-market clinical follow-up data tracing back to packaging lot records. |
| Hospital System Partnership | Secures sterile processing department contracts amid GPO consolidation pressure. |
| Multi-layer Coextrusion Licensing | Integrates ethylene vinyl alcohol oxygen barriers into thermoformable films for pacemaker packaging. |
| Vaporized Hydrogen Peroxide Compatibility | Unlocks cost reduction for mid-tier devices through Tyvek-independent seal-layer engineering. |
Research Methodology
Multiple input streams — primary interviews with sterile barrier validation engineers, GPO contracts managers, and biomedical engineers; secondary validation against FDA 510(k) filings, EMA MDR technical documentation, and hospital procurement databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork concentrated in southern Germany, Massachusetts, and Osaka-Kobe technical clusters. Secondary sources included ISO 11607 certification registries, customs trade data for medical-grade resin flows, and sterilization facility EPA emissions records.
Data-stream reconciliation anchored volume and value outputs across packaging type, material specification, sterilization modality, and end-user environment dimensions throughout the forecast period. CAGRs were derived from procedure volume trajectories, reimbursement rate stability, and regulatory compliance burden expansion. Industry-specific forecast inputs incorporated point-of-care diagnostic network expansion rates and orthopedic OEM instrument kit consolidation patterns.
Regulatory deadline shifts, sterilization modality validation failures, and resin supply disruption events are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Transplant Box Market