
 Medical Processing Seals (MPS) Market | 2026-2036
Medical Processing Seals (MPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Processing Seals (MPS) Market Intelligence
Revenue from custom-engineered sealing solutions for bioprocessing equipment is tilting market profitability away from standardized commodity seals. This shift favors suppliers with deep material science and application engineering expertise. Trelleborg AB specializes in advanced polymer solutions for critical aseptic connections. Parker Hannifin Corp leverages its broad engineering capabilities across pharmaceutical packaging and device manufacturing. Saint-Gobain S.A. competes with its portfolio of high-performance materials designed for extreme processing environments.
Medical processing seals are components engineered to create a sterile barrier in pharmaceutical and medical device manufacturing. These seals must maintain integrity under specific pressures, temperatures, and sterilization methods like gamma irradiation or autoclaving. Their primary function is to prevent contamination and ensure product purity in aseptic environments. Silicone materials dominate high-purity applications due to their inertness and thermal stability. Demand for disposable seals is accelerating with the expansion of single-use bioprocessing, while mechanical seals remain integral to traditional stainless-steel equipment.
The US FDA's requirements for material biocompatibility and the European Union's Medical Device Regulation (MDR) directly influence material selection and validation protocols. Conformance with ISO 13485 quality management standards is a prerequisite for market access in most developed economies, including the United States and Japan. The critical decision for suppliers involves balancing investment in novel polymer research and development against the cost pressures inherent in high-volume, single-use applications.
Market Dynamics
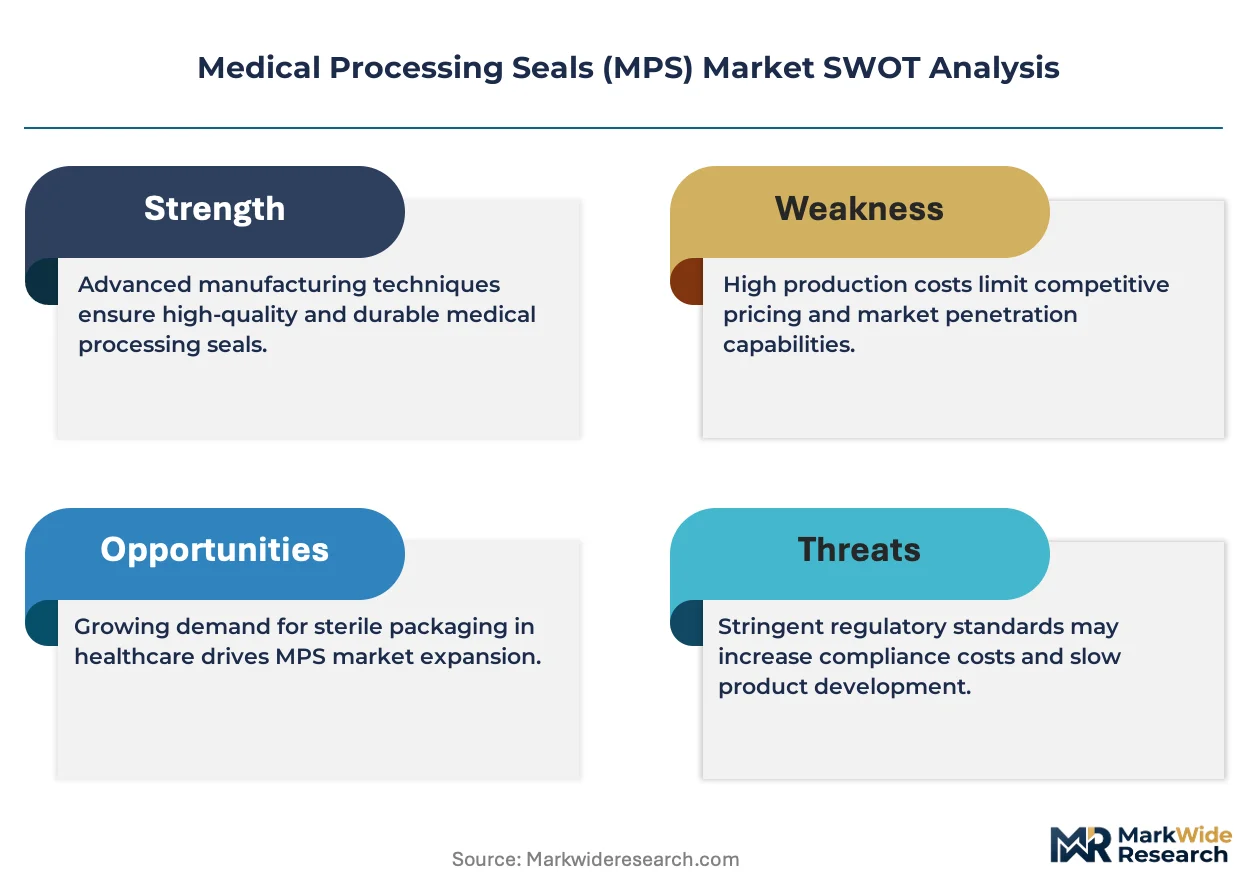
The central dynamic in the medical processing seals market is the tension between the high-value customization required for bioprocessing applications and the intense cost pressures associated with high-volume, single-use systems, which are rapidly displacing traditional reusable equipment.
Growth Catalysts
- Single-Use Systems:The accelerated shift to single-use bioprocessing assemblies in pharmaceutical manufacturing drives volume demand for disposable seals, gaskets, and O-rings that ensure sterility and eliminate cross-contamination risks.
- Regulatory Scrutiny:Stringent frameworks, particularly the European Union's Medical Device Regulation (MDR), mandate extensive material validation and performance testing, favoring suppliers with robust quality management systems and documentation.
- Manufacturing Hubs:Demand is concentrating within specialized medical device and pharmaceutical manufacturing clusters, including those in Ireland, Costa Rica, and Germany, creating localized growth opportunities for seal suppliers.
Market Restraints
- Material Cost Volatility:The market is sensitive to price fluctuations in specialty raw materials like high-purity silicones and fluoropolymers, which can compress margins for seal manufacturers, especially in the commodity segment.
- Extractables and Leachables:Complex biologic drugs are highly sensitive to contamination from extractables and leachables (E&L), creating a significant technical barrier and requiring extensive, costly testing for any new seal material.
- Validation Timelines:Any change in a seal's material composition or manufacturing process requires lengthy and expensive re-validation by end-users to comply with US FDA and other regulatory agency requirements.
Strategic Opportunities
- Smart Sealing Solutions:Developing seals with embedded micro-sensors offers a path to differentiation by enabling real-time monitoring of pressure, temperature, and integrity within aseptic processing environments.
- Cell and Gene Therapy:Manufacturing processes for cell and gene therapies have unique and stringent sterility requirements, creating a new, high-value application segment for custom-engineered, ultra-pure sealing components.
- Sustainable Polymers:Investment in R&D for biodegradable or more easily recyclable polymers for single-use seals can address growing environmental concerns from large pharmaceutical and biotechnology customers.
Industry Challenges
- Talent Scarcity:A persistent shortage of application engineers and material scientists who possess dual expertise in polymer science and the specifics of cGMP-compliant biopharmaceutical manufacturing hinders innovation.
- Traceability Burden:The operational challenge of maintaining meticulous batch traceability from raw material to finished seal, as required by ISO 13485, adds significant administrative and systems-related costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Processing Seals (MPS) Market |
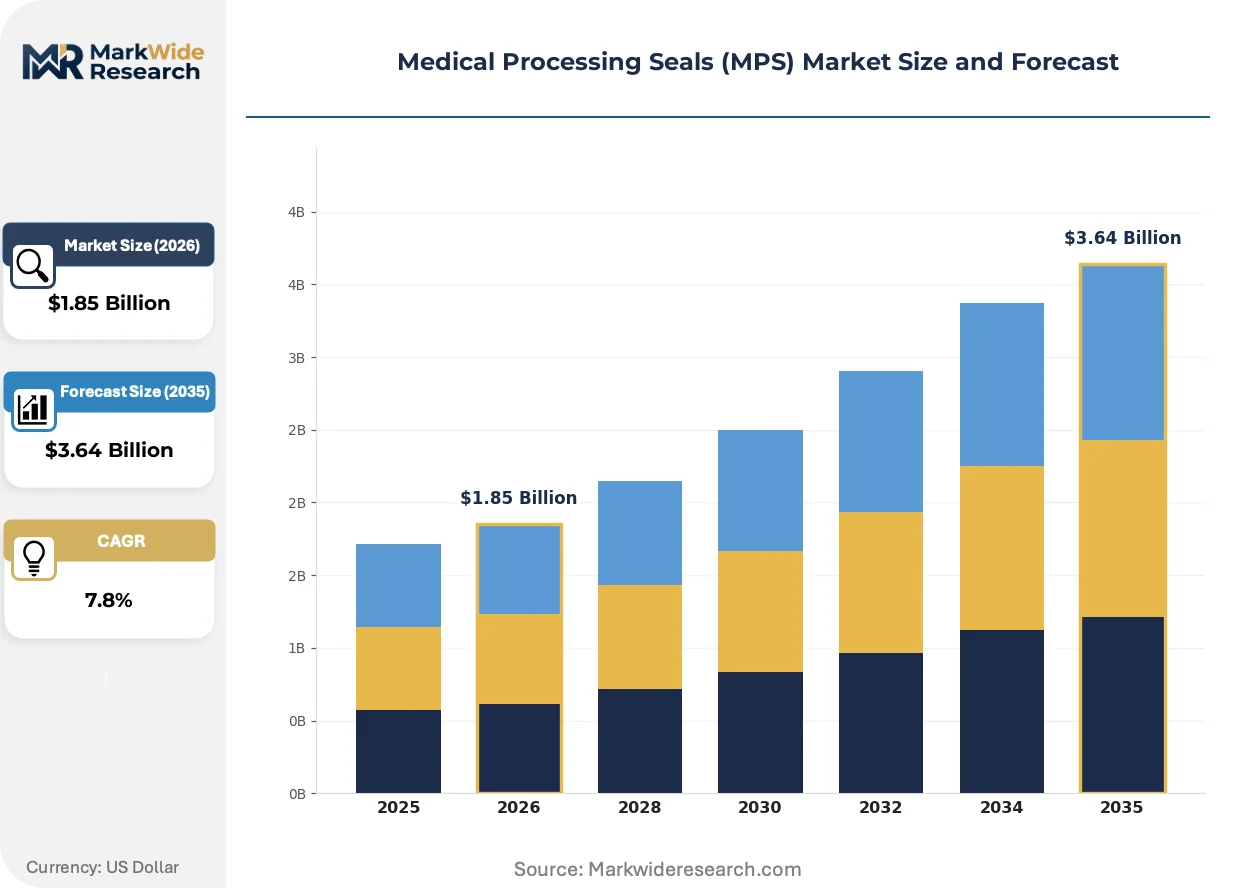
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seal Type: Heat Seal, Adhesive Seal, Disposable Seal, Mechanical Seal Material: Polyethylene, Polypropylene, Rubber, Silicone Application: Pharmaceutical Packaging, Medical Device Manufacturing, Laboratory Use, Sterilization Packaging Type: Blister Packs, Pouches, Tubs, Trays |
| Companies Covered | Minnesota Rubber and Plastics, Parker Hannifin Corp, Trelleborg AB, Apple Rubber Products Inc., Bal Seal Engineering, Inc., IDEX Corporation, Saint-Gobain S.A., Flowserve Corporation, Freudenberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Processing Seals (MPS) Market Strategic Shifts & Innovations
The evolution of medical processing seals is defined by the integration of digital tools into material science and the rising demand for components that support data-driven manufacturing. This shift prioritizes predictive performance and in-process monitoring over purely historical batch validation.
Finite Element Analysis (FEA) and other simulation software are key tools for modeling seal performance under specific thermal and chemical stresses. Medical device and bioprocessing equipment manufacturers are adopting these digital modeling techniques earlier in the design cycle to accelerate development. This adoption of simulation-first design is virtualizing much of the expensive and slow physical prototyping and testing process, compressing product development timelines.
The US FDA’s Process Analytical Technology (PAT) framework encourages the use of real-time monitoring to ensure final product quality in pharmaceutical manufacturing. This regulatory guidance directly stimulates demand for system components, including seals, that can facilitate or embed sensor technology for process control. The aseptic filling and bioprocessing segments are most affected, responding by specifying sensor-compatible components for new equipment builds.
Consolidation of sourcing is altering procurement behavior among large biopharmaceutical manufacturers. They are increasingly seeking to qualify and purchase complete, pre-sterilized fluid path assemblies from a single source, rather than buying individual seals, tubing, and connectors from multiple vendors. This trend is most prominent in North America and Europe, where contract manufacturing organizations use it to simplify their supply chains and reduce validation overhead.
Medical Processing Seals (MPS) Market Segmentation
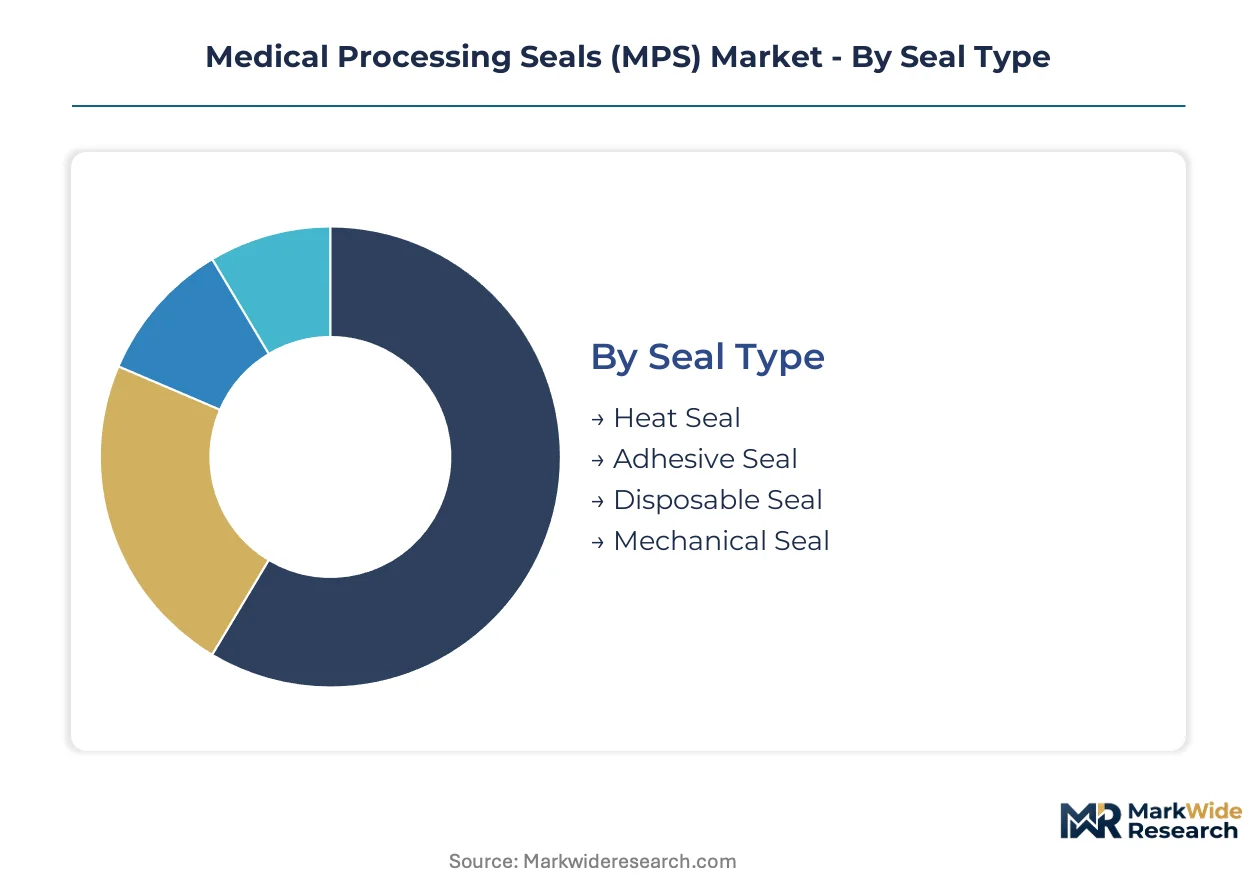
The Medical Processing Seals (MPS) market segments reflect diverse functional requirements across pharmaceutical and medical device manufacturing. Understanding these distinct categories is essential for suppliers to align material science innovations with specific application demands and regulatory compliance. Each segment presents unique technical challenges and commercial opportunities for specialized sealing solutions.
Seal Type:
The market for medical processing seals presents a maturity spectrum, ranging from established technologies to rapidly evolving disposable solutions. Suppliers must balance investment between optimizing existing seal types and developing advanced components for next-generation systems.
- Disposable Seal:These seals are engineered for single-use bioprocessing assemblies, ensuring sterility and eliminating cross-contamination risks in pharmaceutical production. Demand for disposable seals is accelerating with the shift to single-use systems in North America and Europe.
- Mechanical Seal:Mechanical seals maintain integrity in traditional stainless-steel bioprocessing equipment, providing robust sealing under specific pressures and temperatures. These seals are integral to many legacy systems and high-pressure applications in Germany and Japan.
- Heat Seal:Heat seals create a sterile barrier by fusing thermoplastic materials, commonly found in medical packaging and sterile pouches. This sealing method is critical for maintaining product sterility through distribution.
- Adhesive Seal:Adhesive seals utilize biocompatible bonding agents to create a secure, sterile closure, often used in medical device assembly and specialized sterile barrier systems. These seals require careful validation for material compatibility and adhesion strength.
Disposable Seals handle the majority of throughput in emerging bioprocessing applications; Adhesive Seals are the fastest mover on share in specialized device assembly.
Material:
Material selection for medical processing seals is dictated by a complex interplay of biocompatibility, chemical resistance, and cost tier, influencing performance across diverse processing environments. High-purity materials command a premium due to stringent validation requirements.
- Silicone:Silicone materials dominate high-purity applications due to their inertness, thermal stability, and flexibility, making them suitable for critical aseptic connections. This material is essential for biopharmaceutical manufacturing in Ireland and Costa Rica.
- Rubber:Various rubber compounds, including EPDM and FKM, provide robust sealing solutions for general medical equipment and less critical pharmaceutical processes. Rubber seals offer good elasticity and chemical resistance for a range of temperatures.
- Polyethylene:Polyethylene is widely used in disposable medical packaging and components due to its cost-effectiveness, flexibility, and barrier properties. This polymer supports high-volume, single-use applications requiring a sterile barrier.
- Polypropylene:Polypropylene offers good chemical resistance and can withstand autoclaving temperatures, making it suitable for certain medical device components and sterile fluid path applications. It serves as a versatile material for various medical processing needs.
Silicone provides foundational sealing for aseptic bioprocessing; Polyethylene is expanding its market presence quickly in disposable systems.
Application:
The application landscape for medical processing seals is segmented by the specific end-user industry and the type of manufacturing process, each with distinct regulatory and performance demands. Different customer types prioritize varying seal attributes.
- Medical Device Manufacturing:Seals in this segment must meet stringent biocompatibility and mechanical integrity requirements, ensuring the safety and efficacy of medical implants and diagnostic equipment. This application drives demand in specialized manufacturing clusters in Germany and the United States.
- Pharmaceutical Packaging:Seals are critical for maintaining the sterility and integrity of pharmaceutical products, from vials and syringes to blister packs, preventing contamination. This segment requires seals compatible with various sterilization methods and drug formulations.
- Laboratory Use:Seals for laboratory equipment, such as bioreactors, filtration systems, and analytical instruments, demand high chemical resistance and precision for accurate experimental results. These seals support research and development activities in academic and industrial settings.
- Sterilization:Seals designed for sterilization processes, including autoclaving, gamma irradiation, or ethylene oxide, must withstand extreme conditions without degradation or loss of integrity. These seals ensure sterile environments for medical tools and components.
Medical Device Manufacturing drives significant volume demand; Pharmaceutical Packaging demonstrates the steepest expansion trajectory due to bioprocessing growth.
Packaging Type:
Segmentation by packaging type highlights the diverse forms medical products take and the specific sealing technologies required to protect them. This category reflects the volume and complexity of the packaging process.
- Blister Packs:Seals for blister packs create individual sterile compartments for pills, capsules, and small medical devices, requiring precise heat sealing to ensure product protection. This packaging type is prevalent in over-the-counter pharmaceuticals.
- Pouches:Flexible pouches utilize seals for sterile barrier systems, commonly used for surgical instruments, catheters, and disposable medical supplies. These seals must maintain integrity during transport and storage.
- Tubs:Seals for tubs secure larger medical devices or bulk sterile components, often involving lid-sealing technologies to prevent contamination. Tubs are frequently used for hospital supplies and procedure kits.
- Trays:Trays with seals provide protection for delicate or multiple medical items, requiring robust sealing to ensure the sterility of the contained products until point of use. This packaging is common for sterile procedure trays.
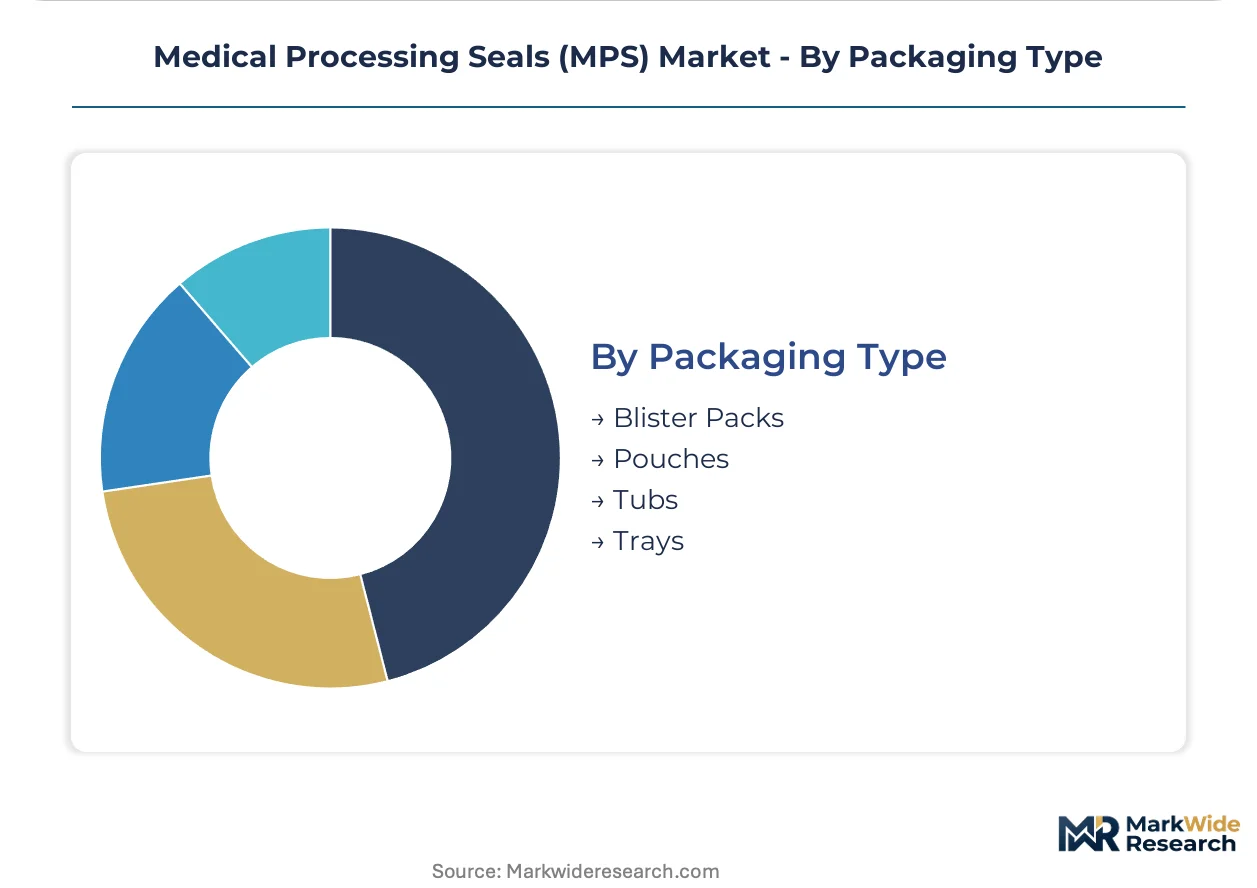
Blister Packs represent a mature, high-volume segment; Pouches are gaining share at an accelerated pace due to increased demand for disposable medical supplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for medical processing seals varies in elasticity; high-value bioprocessing applications exhibit lower price sensitivity, while high-volume single-use systems face intense cost pressures. This dynamic shapes regional investment in advanced sealing technologies. Specialized manufacturing clusters globally demonstrate distinct procurement behaviors.
United States
Medical device manufacturing and biopharmaceutical production drive substantial demand for high-purity seals. US FDA requirements for material biocompatibility dictate stringent validation protocols for all seal components. The Boston and San Francisco Bay Area clusters concentrate significant bioprocessing research and advanced medical device development.
Germany
High-value medical device manufacturing and precision engineering create strong demand for specialized seals. The European Union's Medical Device Regulation (MDR) mandates extensive material validation for market access. Manufacturing clusters in Bavaria and North Rhine-Westphalia focus on advanced medtech production and pharmaceutical packaging solutions.
Ireland
Biopharmaceutical manufacturing, particularly single-use systems, generates significant volume demand for disposable seals. European Medicines Agency (EMA) guidelines influence the selection and qualification of seals for sterile drug production. Dublin and Cork host major pharmaceutical and biotechnology hubs, emphasizing aseptic processing components.
Japan
Advanced medical device manufacturing and pharmaceutical packaging applications necessitate high-performance seals. PMDA regulations prioritize product purity and long-term stability for medical components and drug containers. The Tokyo and Osaka regions are centers for sophisticated R&D and precision manufacturing of medical equipment.
Costa Rica
Medical device manufacturing for export fuels demand for specialized seals in Costa Rica. Conformance with US FDA requirements is paramount for market access for components produced here. Free trade zones near San José have become a hub for medical device assembly, requiring validated sealing solutions.
Medical Processing Seals (MPS) Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the medical processing seals market. The market exhibits a tiered structure, with specialized firms focusing on high-performance materials and larger entities offering broader portfolios. Strategic archetypes include material science innovators, broad engineering solution providers, and high-volume commodity suppliers. Key competitive moves involve strategic partnerships for complex assemblies and targeted M&A for niche technology acquisition.
Within the high-performance segment, Trelleborg AB exemplifies expertise in advanced polymer solutions for critical aseptic connections. Parker Hannifin Corp leverages its broad engineering capabilities across pharmaceutical packaging and device manufacturing, representing a diversified industrial approach. Saint-Gobain S.A. occupies a position among suppliers providing high-performance materials designed for extreme processing environments, anchoring the specialized material science vector. These companies demonstrate distinct approaches to market penetration and value capture.
| Leading Market Players |
|---|
| Minnesota Rubber and Plastics |
| Parker Hannifin Corp |
| Trelleborg AB |
| Apple Rubber Products Inc. |
| Bal Seal Engineering, Inc. |
| IDEX Corporation |
| Saint-Gobain S.A. |
| Flowserve Corporation |
| Freudenberg Group |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized cleanroom manufacturing for medical processing seals drives both supplier investment behavior and premium pricing posture for advanced solutions. This dynamic shapes procurement strategies across pharmaceutical and medical device sectors.
Pricing Analysis
Long-term offtake agreements dominate pricing for custom-engineered seals in bioprocessing applications, reflecting the extensive validation required. Price differentiation stems from ISO 13485 certification levels and application-specific material science expertise. Pricing softness affects high-volume, single-use systems due to raw material volatility, particularly for silicones and fluoropolymers. High-value bioprocessing applications exhibit the least price sensitivity, while commodity single-use seals are most sensitive to cost fluctuations.
Supply Chain Analysis
Specialized contract manufacturers in Ireland and Germany concentrate significant production capacity for medical processing seals, alongside facilities in Costa Rica. The supply chain draws heavily from high-purity silicones and fluoropolymers, making it susceptible to material cost volatility. A structural risk involves the extensive and costly extractables and leachables testing required for new materials. Distribution runs primarily through direct sales channels to medical device OEMs and biopharmaceutical contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical processing seals market is undergoing a platform-economics inflection, driven by the integration of seals into complete, pre-sterilized fluid path assemblies.
For Market Incumbents: Build deep material science moats through continuous R&D in biocompatible polymers. Invest in smart sealing solutions with embedded micro-sensors to provide real-time process data, countering the threat from emerging digital monitoring technologies. Pursue targeted M&A for niche technology firms specializing in advanced material validation or sustainable polymer development. Leverage existing ISO 13485 certification and regulatory expertise as a key lever.
For New Entrants and Emerging Players: Emerging market underpenetration in bioprocessing infrastructure represents a significant white space. Target cell and gene therapy applications with ultra-pure, custom-engineered components, where sterility requirements are exceptionally stringent. Focus on developing sustainable or recyclable single-use seal materials to address growing environmental concerns. A go-to-market angle involves offering rapid prototyping and validation services to accelerate product development cycles for smaller device manufacturers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across advanced polymer research and development for bioprocessing seals. Long-term viability for specialized material science firms remains strong over the next 5-10 years, particularly those with robust intellectual property. Acquisition targets should include vertically integrated mid-cap specialists with strong application engineering capabilities in aseptic processing. A signal to watch is increased M&A activity for companies possessing validated sustainable material portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Polymer R&D | Drives next-generation biocompatible materials for stringent regulatory frameworks like the EU MDR. |
| Single-Source Fluid Path Assembly Partnership | Simplifies procurement and validation for large biopharmaceutical manufacturers, reducing supply chain complexity. |
| Smart Sealing Solution Development | Enables real-time process monitoring in aseptic environments, aligning with US FDA Process Analytical Technology guidelines. |
| Sustainable Biopolymer Investment | Addresses growing environmental concerns from end-users, differentiating offerings in the single-use segment. |
| Niche Technology Acquisition | Secures specialized expertise in areas like micro-sensor integration or advanced material validation protocols. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, complemented by extensive secondary validation. Stakeholders included medical device engineers, pharmaceutical procurement leads, polymer scientists, and regulatory affairs specialists. Secondary data sources comprised US FDA filings, EU MDR guidance documents, ISO 13485 standards, and relevant industry association reports, triangulated through both bottom-up and top-down approaches.
The analytical framework calibrated market sizing and growth rates over the projection horizon. Segmentation dimensions modeled included seal type, material, application, packaging type, and key geographic manufacturing clusters. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical trends and incorporating future market drivers. Industry-specific forecast inputs included single-use system adoption rates and new biopharmaceutical drug approvals.
Practitioners should monitor raw material price volatility and evolving regulatory frameworks for early signals of market shifts. Forecasts reflect assumptions regarding technological advancements and market dynamics across the analysis window. Quarterly review of regulatory updates and bioprocessing investment trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market