
 Sterile Packaging Market | 2026-2036
Sterile Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Packaging Market Intelligence
The shift toward ISO 11607-compliant materials and validation processes is collapsing the distinction between standard and premium medical-grade packaging. This trend benefits scaled producers like Amcor plc, which leverages its global manufacturing footprint to supply compliant materials. DuPont de Nemours Inc. specializes in high-performance materials like Tyvek, essential for applications requiring superior microbial barriers. West Pharmaceutical Services focuses on integrated containment and delivery systems for injectable drugs.
Sterile packaging refers to a system of materials and processes designed to maintain the sterility of a product from the point of sterilization until use. It often involves materials like high-density polyethylene or aluminum foils that can withstand terminal sterilization methods such as gamma irradiation or ethylene oxide. The pharmaceutical and medical device end-user segments constitute the largest share, driven by stringent safety protocols for drugs and implants. Within product types, pouches and trays dominate due to their versatility for a wide range of device sizes and shapes.
Market access is governed by a complex framework of standards, notably ISO 11607, and specific regulations from bodies like the US FDA, the European Medicines Agency, and China's NMPA. These mandates enforce strict validation, documentation, and material traceability, directly influencing product design and manufacturing costs. The critical decision for manufacturers now revolves around investing in automation for validation testing versus outsourcing to specialized labs to ensure compliance.
Market Dynamics
The market's central dynamic is the tension between increasingly stringent global regulations, led by the EU's MDR and ISO 11607, and the concurrent demand for cost-effective solutions from high-volume pharmaceutical and medical device manufacturing hubs in Asia.
Growth Catalysts
- Single-Use Devices:Proliferation of single-use surgical instruments to mitigate infection risk directly boosts demand for sterile pouches and trays, a trend most pronounced in orthopedic and cardiovascular procedures.
- Pharmaceutical Export Hubs:The expansion of drug manufacturing in India and China, targeting export markets, requires packaging compliant with US FDA and EMA standards, elevating material specifications.
- EU Medical Device Regulation (MDR):The regulation's mandate for comprehensive technical documentation and lifecycle management for packaging is forcing an upgrade to higher-performance, fully traceable materials across all device classes.
Market Restraints
- Raw Material Volatility:Unpredictable pricing for petroleum-derived polymers and specialty aluminum foils, key inputs for barrier films, compresses converter margins and introduces supply chain instability.
- Sterilization Limitations:Some advanced barrier materials are incompatible with newer sterilization modalities like vaporized hydrogen peroxide, forcing manufacturers to stick with older methods or undertake costly compatibility studies.
- Specialized Material Sourcing:High-barrier nonwovens and films are produced by a limited number of global suppliers, creating supply concentration risk and limiting negotiation power for packaging manufacturers.
Strategic Opportunities
- Emerging Market Localization:Establishing local production in Southeast Asia and Latin America to serve regional healthcare systems offers growth potential, bypassing complex import logistics for basic sterile supplies.
- Biologic Drug Packaging:Developing specialized containment systems for cell and gene therapies, which require cryogenic temperature resistance and ultra-pure materials, represents a high-value niche.
- Smart Packaging Integration:Incorporating RFID or NFC tags into primary sterile packaging enables enhanced traceability and anti-counterfeiting measures, meeting new regulatory demands for supply chain security.
Industry Challenges
- Compliance Validation Burden:The extensive time and cost required to validate a new packaging material or design against ISO 11607 can create significant delays in bringing new medical devices to market.
- Automation Investment:Implementing automated inspection and validation testing systems to ensure compliance at scale requires substantial capital investment, creating a competitive disadvantage for smaller firms.
- Talent Scarcity:A persistent shortage of packaging engineers with dual expertise in material science and international regulatory affairs, particularly concerning the NMPA and CDSCO, hampers innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Packaging Market |
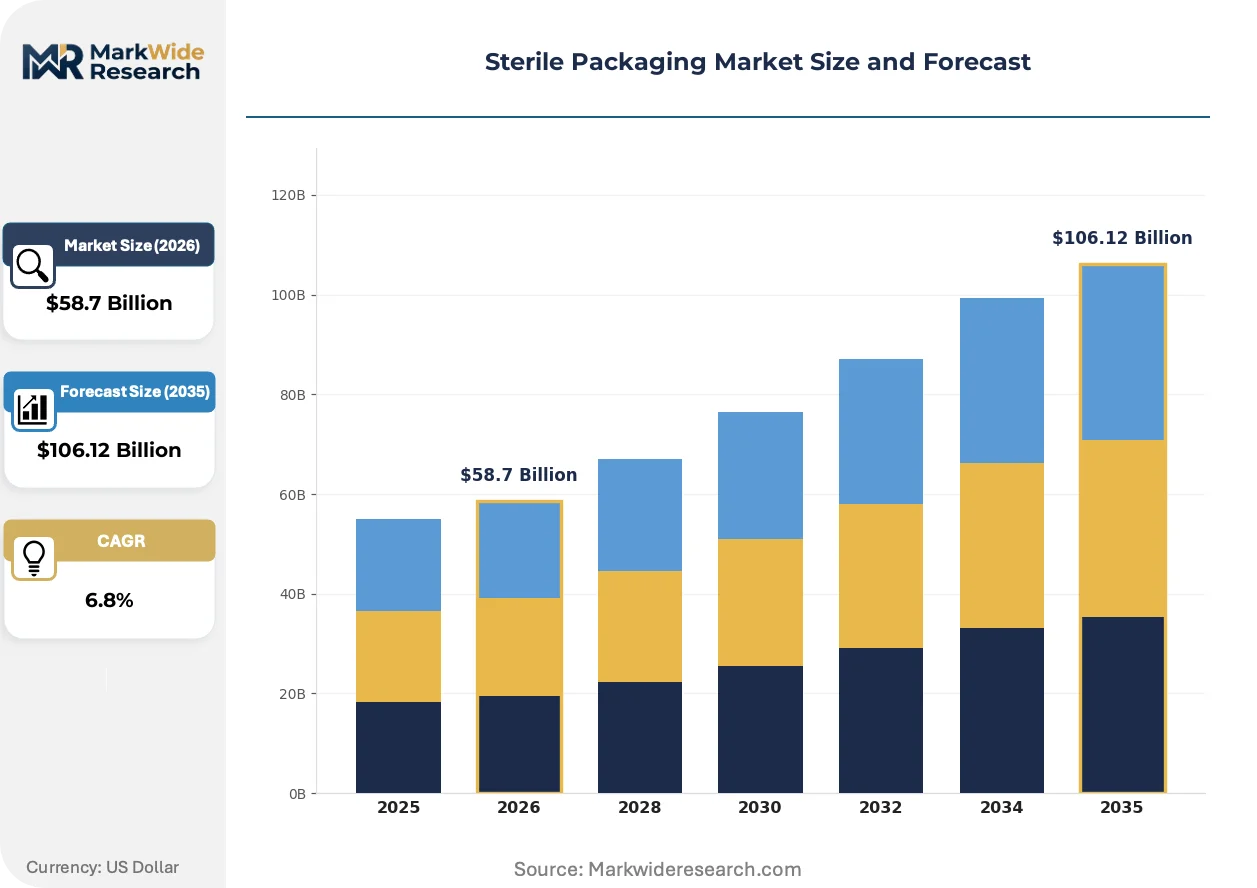
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Trays, Bags, Containers Material: Plastic, Paper, Polyethylene, Aluminum End User: Pharmaceuticals, Food, Medical Devices, Biotechnology Technology: Sterilization, Vacuum Packaging, TPP, Modified Atmosphere |
| Companies Covered | Amcor plc, DuPont de Nemours Inc., West Pharmaceutical Services, Berry Global, Gerresheimer AG, Sonoco, SteriPack Group, Wipak Group, Nelipak Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Packaging Market Strategic Shifts & Innovations
Material science advancements are profoundly changing sterile packaging, driven by a dual mandate for enhanced product protection and regulatory compliance. These innovations are moving beyond simple containment to become integral components of medical device and drug delivery systems.
High-performance coextruded films provide tailored barrier and peel characteristics in a single structure. Medical device manufacturers are adopting these multi-layer materials for packaging complex instruments. This innovation is displacing traditional monolithic plastics and coated papers that offer less specific performance, compressing the market for single-function materials.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for packaging validation and material traceability. Its stringent post-market surveillance mandate impacts packaging design and documentation. Manufacturers of implantable devices are most affected, often requiring complete re-validation of their sterile barrier systems to comply with the new rules.
A notable shift in buying behavior involves sourcing complete, pre-validated sterile barrier systems rather than individual components. This disrupts the traditional model of purchasing from separate suppliers, favoring integrated system providers. The trend is most visible for injectable drug delivery systems, particularly in North America and Europe where regulatory scrutiny is high.
Sterile Packaging Market Segmentation
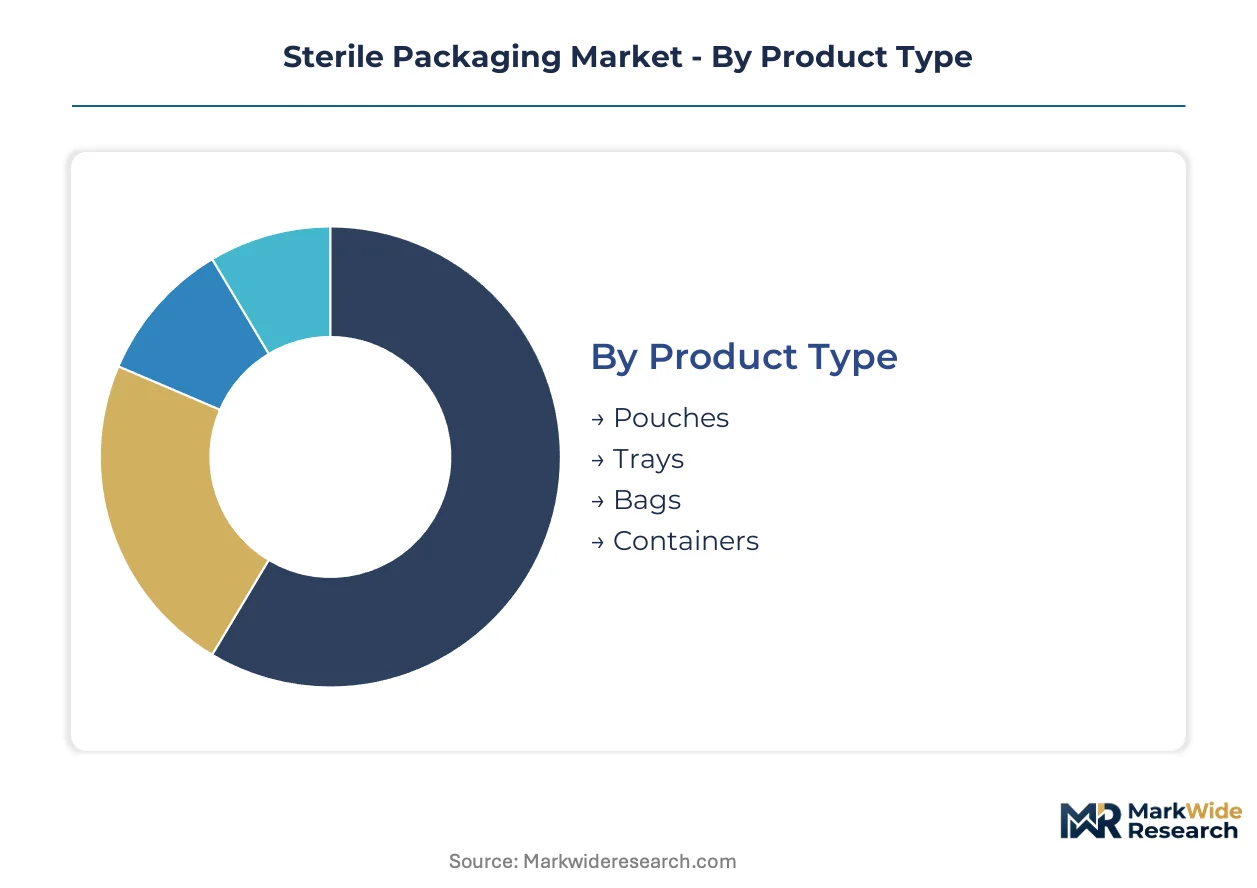
The sterile packaging market's intricate structure reflects diverse requirements across healthcare sectors, influencing material selection, production processes, and regulatory compliance. Understanding these segment dynamics is crucial for manufacturers to align product development with specific end-user demands and evolving global standards.
Product Type:
Margin pools within product types often concentrate in specialized, high-barrier solutions that offer enhanced protection for sensitive medical devices and pharmaceuticals.
- Pouches:These flexible packaging solutions provide excellent barrier properties and are widely used for single-use medical instruments. Demand is concentrating in orthopedic and cardiovascular surgical kits across Europe, driven by stringent EU MDR requirements for individual device sterility.
- Trays:Rigid thermoformed trays offer robust physical protection and precise device containment, particularly for complex surgical tools and implantable devices. Medical device manufacturers in the US require these for their ability to withstand multiple sterilization cycles and maintain product integrity during transit.
- Bags:Sterilization bags facilitate the aseptic transfer of components and bulk pharmaceutical ingredients within controlled environments.
- Containers:Reusable and single-use containers provide durable sterile barriers for larger medical instruments and pharmaceutical compounds.
The dominant share belongs to Pouches, while Trays are closing the gap fastest.
Material:
Supply concentration in high-performance materials dictates pricing power and innovation within the sterile packaging material segment.
- Plastic:Polymers like polyethylene and polypropylene offer versatility, cost-effectiveness, and compatibility with various sterilization methods. Asian pharmaceutical manufacturing hubs are driving demand for plastic films due to their high-volume production needs.
- Aluminum:Aluminum foils provide superior barrier protection against moisture, oxygen, and light, critical for sensitive pharmaceutical products. Global biologic drug manufacturers increasingly specify aluminum laminates for their cryogenic stability and ultra-pure containment properties.
- Paper:Medical-grade papers are breathable, allowing sterilizing agents to penetrate while maintaining a microbial barrier.
- Polyethylene:High-density and low-density polyethylene films are frequently used for their strength, sealability, and chemical resistance.
Material innovation is concentrating on Plastic solutions to meet stringent regulatory demands, while Aluminum maintains a strong presence for high-value applications.
End User:
Application-specific requirements define the performance benchmarks and regulatory hurdles for sterile packaging across different end-user segments.
- Pharmaceuticals:This segment demands packaging that ensures drug stability, integrity, and patient safety, often involving primary packaging for injectable drugs and biologics. India and China's expanding pharmaceutical export activities are elevating demand for packaging compliant with US FDA and EMA standards.
- Medical Devices:Packaging for medical devices must maintain sterility from manufacturing through to the point of use, encompassing single-use instruments and implantable devices. European medical device companies are upgrading their sterile barrier systems to comply with the EU MDR's lifecycle management requirements.
- Food:Sterile packaging in the food industry focuses on extending shelf life and preventing microbial contamination for sensitive products.
- Biotechnology:Specialized packaging for cell therapies and diagnostic reagents requires ultra-pure materials and extreme temperature stability.
The largest revenue contributions originate from Medical Devices and Pharmaceuticals, both driven by evolving regulatory landscapes.
Technology:
Regulatory impact significantly shapes the adoption and development trajectory of sterile packaging technologies, particularly for validation and traceability.
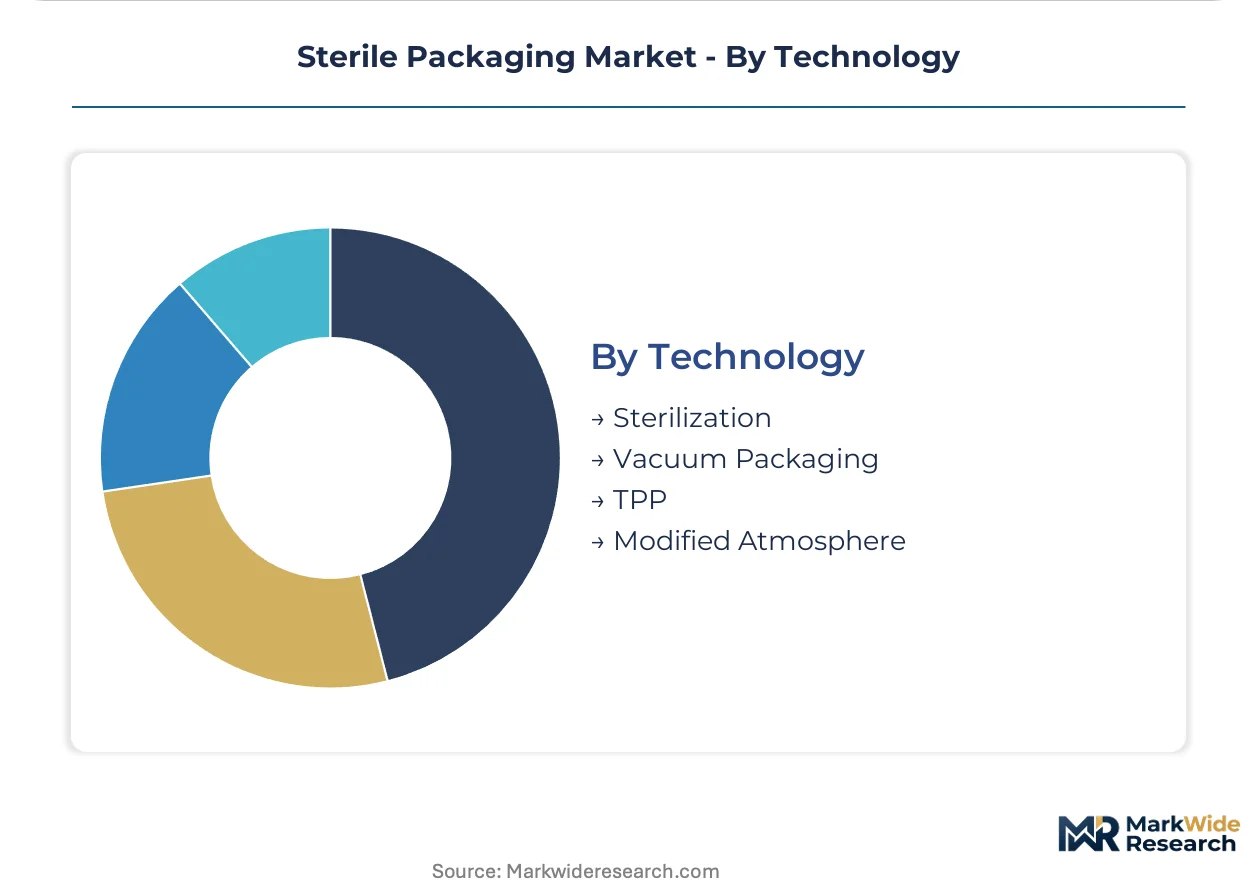
- Sterilization:Technologies like gamma irradiation, ethylene oxide, and vaporized hydrogen peroxide define the compatibility requirements for packaging materials. Manufacturers in Europe are undertaking costly compatibility studies for new barrier materials with existing sterilization modalities.
- Vacuum Packaging:This technology removes air from the package to minimize oxidation and extend product shelf life, especially for certain medical components.
- TPP:Thermoform-Peel Packaging creates rigid trays with peelable lidding, offering convenient aseptic presentation of medical devices.
- Modified Atmosphere:Modified atmosphere packaging controls the gas composition inside the package to inhibit microbial growth and preserve product quality.
Efficiency gains are primarily observed in Sterilization solutions, while TPP is seeing specialized adoption for complex medical devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sterile packaging market exhibits a dynamic interplay between export-oriented manufacturing hubs and import-reliant healthcare systems. High-volume pharmaceutical production in Asia balances against stringent regulatory demands from North American and European markets. This global trade flow necessitates harmonized packaging standards.
United States
United States demand for sterile packaging is shaped by its robust medical device innovation and expanding biologic drug pipeline. US FDA regulations mandate rigorous validation for all sterile barrier systems, especially for implantable devices. Medical device manufacturers in the Boston-Cambridge corridor drive specifications for high-performance packaging materials.
Germany
Germany's market for sterile packaging is propelled by its strong medical technology sector and pharmaceutical manufacturing base. The EU Medical Device Regulation (MDR) requires comprehensive lifecycle documentation for packaging, influencing material selection. Pharmaceutical clusters in Bavaria and North Rhine-Westphalia prioritize packaging compatible with advanced sterilization methods.
India
India's expanding pharmaceutical export activities are a primary driver for sterile packaging, particularly for generic drugs. The country's CDSCO regulations align with international standards, elevating material specifications for export markets. Pharmaceutical manufacturing hubs in Gujarat and Maharashtra are increasing procurement of compliant packaging solutions.
China
Chinese medical device and pharmaceutical manufacturing, particularly for export, significantly boosts sterile packaging consumption. NMPA regulations are tightening, demanding greater material traceability and validation for both domestic and international sales. Manufacturing zones within the Yangtze River Delta are investing in automated packaging lines to meet these standards.
Japan
Japan's sterile packaging market is characterized by a focus on high-quality medical instruments and advanced healthcare solutions. PMDA standards emphasize product integrity and patient safety, influencing packaging design for implantable devices. Medical device producers in the Kansai region are adopting integrated sterile barrier systems.
Sterile Packaging Market Key Industry Players
Listed leaders compete with private specialists across material innovation and global supply chain reach within the sterile packaging market. This market exhibits consolidation among large, diversified packaging conglomerates and fragmentation among numerous niche material suppliers. Strategic archetypes include high-performance material developers, integrated system providers, and regional contract packagers. Capacity expansion, strategic partnerships, and targeted portfolio diversification are dominant competitive moves observed across the industry.
Specialists in high-performance materials include DuPont de Nemours Inc., which exemplifies advanced polymer science for microbial barriers in critical applications. Amcor plc, a global packaging leader, represents scaled production and extensive geographic reach, offering diverse sterile packaging formats for pharmaceutical and medical device clients. West Pharmaceutical Services occupies a position as an integrated containment and delivery system provider, focusing on complex solutions for injectable drugs and biologics. These companies anchor different segments of the value chain, from raw material supply to finished sterile systems, reflecting varied strategic approaches to market access and product development.
| Leading Market Players |
|---|
| Amcor plc |
| DuPont de Nemours Inc. |
| West Pharmaceutical Services |
| Berry Global |
| Gerresheimer AG |
| Sonoco |
| SteriPack Group |
| Wipak Group |
| Nelipak Healthcare |
| Others |
Cost & Logistics Intelligence
Extended lead times for high-barrier films, critical for maintaining product sterility, directly influence pricing power for specialized material suppliers in the sterile packaging market.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for sterile packaging materials. Price differentiation stems from ISO 11607 certification levels and the degree of material customization required for complex medical devices. Pricing softness runs through high-volume generic pharmaceutical packaging due to intense competition from Asian manufacturing hubs. Implantable device manufacturers exhibit the lowest price sensitivity, prioritizing performance and regulatory compliance over cost.
Supply Chain Analysis
Inventory levels for specialized barrier materials, particularly high-performance nonwovens and aluminum foils, remain a critical concern. Geographic supply concentrates in Germany for pharmaceutical packaging and China for high-volume plastic films. The sterile packaging market sources heavily from petroleum-derived polymers and specialty aluminum foils. Single-source vulnerability for advanced barrier materials like Tyvek represents a significant supply chain risk. Distribution runs primarily through direct sales channels to pharmaceutical and medical device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterile packaging market faces a critical constraint in specialized talent, particularly packaging engineers combining material science with international regulatory affairs expertise.
For Market Incumbents: Shield core market share by investing heavily in automated validation testing infrastructure to meet ISO 11607 and EU MDR requirements. Pursue strategic partnerships with material science innovators to secure access to next-generation barrier technologies. Leverage existing global manufacturing footprints to offer complete, pre-validated sterile barrier systems, mitigating compliance burdens for OEMs.
For New Entrants and Emerging Players: Differentiate on specialized material solutions for high-value niche segments like biologic drug packaging requiring cryogenic stability. Target emerging markets in Southeast Asia and Latin America for localized production of basic sterile supplies, bypassing complex import logistics. Offer integrated smart packaging solutions with RFID tags to enhance traceability and anti-counterfeiting measures for pharmaceutical exports.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated growth play because healthcare demand for sterile products is non-discretionary and continuously evolving. Focus acquisition profiles on vertically integrated specialists with strong intellectual property in high-performance barrier materials or advanced validation services. Increased M&A activity among specialized material providers or independent validation laboratories will signal market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Automated Validation | Streamlines ISO 11607 compliance for new packaging designs, reducing time-to-market for medical devices. |
| Expand Biologic Packaging R&D | Develops specialized containment systems for cell and gene therapies, addressing a high-value market need. |
| Localized Production in Southeast Asia | Reduces import complexities for basic sterile supplies, serving regional healthcare systems efficiently. |
| Integrate Smart Packaging Features | Enhances traceability and anti-counterfeiting for pharmaceutical products, meeting regulatory demands. |
| Strategic Sourcing for Polymers | Mitigates raw material volatility risks for high-density polyethylene and polypropylene films. |
Research Approach
A spread of perspectives from medical device engineers, pharmaceutical procurement managers, and regulatory affairs specialists converged on the working assumptions for sterile packaging. Primary interviews were combined with secondary validation from US FDA filings, EMA submissions, ISO standards documentation, and customs trade data for packaging materials. This approach facilitated bottom-up and top-down triangulation of market estimates.
Segmentation by product type, material, end user, technology, and regional regulatory compliance formed the basis of the analytical framework. Market size and growth rates were derived from historical trends and future demand projections across the analysis window. Medical device approval rates and pharmaceutical export volumes served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant shifts in global trade policies or raw material price volatility would require recalibration. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Global Medical Packaging Market