
 Global Procedure Trays Market | 2026-2036
Global Procedure Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Procedure Trays Market Foresight
Sterile supply technician shortages across North American and Western European hospital systems is redrawing competitive positioning among tray manufacturers. Cardinal Health leverages its captive distribution network to sustain direct-to-hospital contracts across the United States. Becton, Dickinson and Company anchors its portfolio through R&D intensity in closed-system drug transfer devices bundled with procedure trays. Medline Industries dominates ambulatory surgical center channels with private-label customizable tray configurations.
Procedure trays are pre-assembled, sterile collections of medical devices, drapes, and consumables configured for specific clinical interventions, typically packaged in polyethylene-film or Tyvek pouches with ethylene oxide or gamma sterilization validation. These assemblies eliminate individual item sterilization cycles and reduce perioperative setup time in operating rooms and procedural suites. Surgical trays lead volume across the product type dimension, while emergency trays represent the fastest-growing segment as pre-hospital and trauma protocols standardize. Among end users, ambulatory surgical centers are displacing hospital outpatient departments as the highest-margin channel for tray suppliers.
The FDA enforces 510(k) premarket notification and quality system regulation compliance for sterile tray assemblies, while the EU MDR mandates unique device identification and post-market surveillance for all class IIa and above procedure kits. ISO 13485 certification has become a non-negotiable market access threshold for suppliers serving both regulated jurisdictions. Stakeholders must monitor evolving sterilization modality restrictions, particularly ethylene oxide emission caps, to anticipate reformulation of tray packaging materials and contract manufacturing relocation.
Market Dynamics
Sterile supply technician shortages across North American and Western European hospital systems are compressing operating room throughput and forcing acute-care facilities toward pre-validated tray formats that eliminate point-of-use assembly labor.
Growth Catalysts
- Surgical Site Infection Protocols:The FDA's updated sterilization validation requirements mandate ethylene oxide residual testing and bioburden documentation, accelerating hospital conversion from in-house sterilization to vendor-certified tray assemblies.
- Integrated Delivery Networks:United States hospital systems negotiate multi-year supply contracts that bundle procedure trays with pharmaceutical distribution, locking in volume commitments through captive distribution channels.
- Tyvek-to-Recyclable Film Transition:European healthcare procurement directives prioritize polyethylene-film pouches with gamma sterilization over ethylene oxide methods, creating material specification pull-through across EU member states.
Market Restraints
- Ethylene Oxide Emission Caps:The EPA's tightened EtO emission standards for sterilization facilities force contract manufacturers toward gamma or electron-beam alternatives, requiring capital-intensive equipment retooling at sterilization service providers.
- Medical-Grade Polymer Concentration:Supply of pharmaceutical-grade polyethylene and polypropylene concentrates among Gulf Coast petrochemical producers, exposing tray manufacturers to feedstock allocation disruptions from hurricane-season production outages.
- Reusable Surgical Instrument Competition:German hospital purchasing cooperatives evaluate metal instrument reprocessing systems against single-use tray configurations, threatening volume erosion in orthopedic and laparoscopic procedure categories.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:United States outpatient facilities in Florida, Texas, and Arizona pursue customizable private-label tray configurations that match procedure-specific physician preference cards, displacing hospital outpatient departments as the highest-margin channel.
- EU MDR Unique Device Identification:The European Union Medical Device Regulation's traceability mandates create first-mover advantage for suppliers with ISO 13485-certified manufacturing and automated serialization infrastructure.
- Closed-System Drug Transfer Integration:Convergence of hazardous drug handling protocols with chemotherapy procedure trays enables bundling of containment devices with sterile field assemblies, capturing oncology infusion center spend.
Industry Challenges
- Sterile Supply Technician Certification Bottlenecks:North American hospital systems face twelve-to-eighteen-month training pipelines for certified registered central service technicians, constraining tray inspection and release capacity.
- Legacy Enterprise Resource Planning Integration:Hospital materials management systems require custom API development to consume real-time tray utilization data from supplier portals, delaying demand-signal transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Procedure Trays Market |
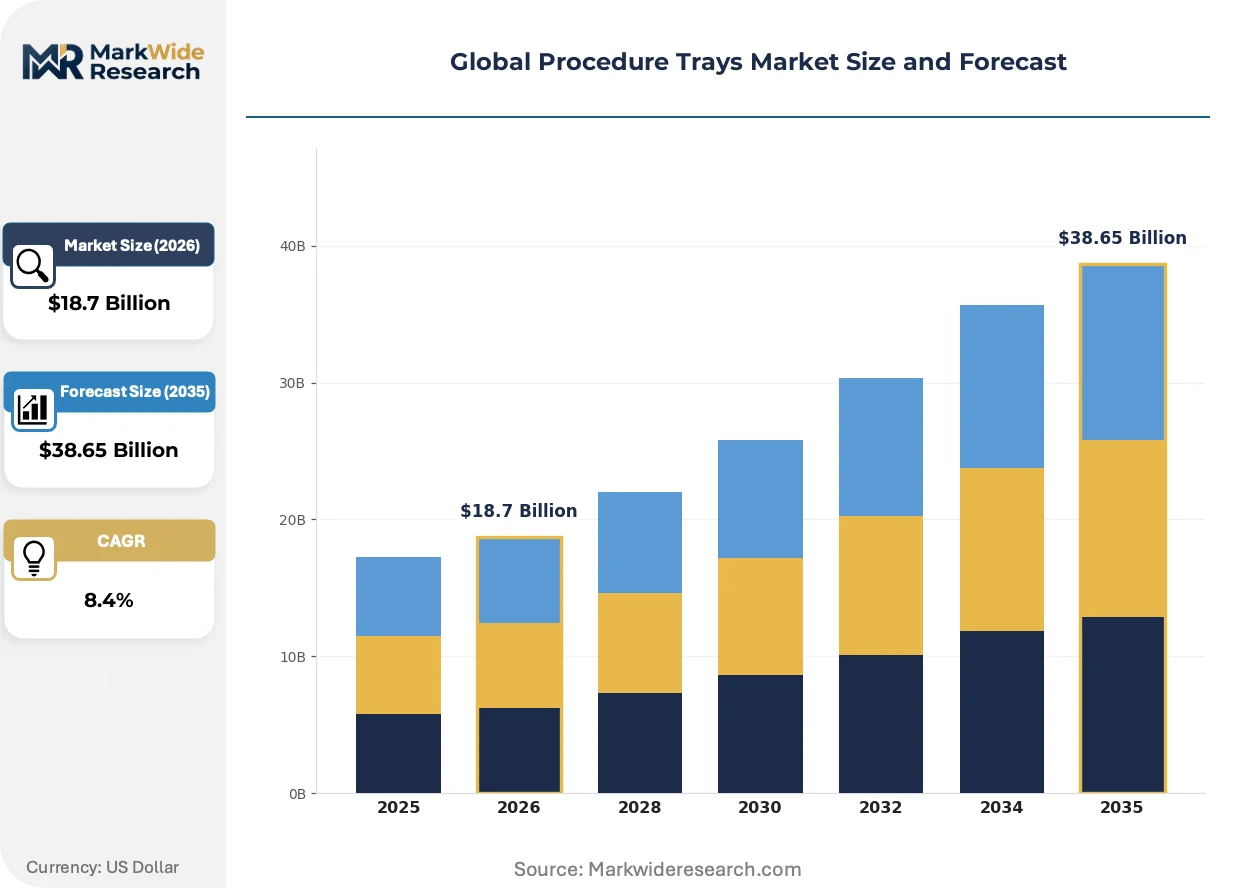
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Trays, Diagnostic Trays, Emergency Trays, Sterilization Trays, Customizable Trays Application: Cardiology, Orthopedics, General Surgery, Dermatology, Urology End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics Distribution Channel: Direct Sales, Medical Distributors, E-commerce Platforms, Third-Party Logistics |
| Companies Covered | Cardinal Health, Owens & Minor, Becton, Dickinson and Company, Medline Industries, Baxter International, B. Braun SE, Teleflex Incorporated, Boston Scientific, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Procedure Trays Market Shifts & Advancements
Tray configuration software and sterilization modality alternatives are compressing product development cycles while regulatory serialization mandates restructure supplier-hospital data exchange protocols.
Biodegradable polymer films derived from polylactic acid and polyhydroxyalkanoates are entering pilot programs at academic medical centers in California and Massachusetts. Surgical services departments evaluate compostable pouch structures against conventional polyethylene for environmental compliance reporting. Material performance is bifurcating the supplier base between sustainability-positioned entrants and incumbent petroleum-based film producers.
The EU Medical Device Regulation's post-market surveillance requirements for class IIa kits mandate annual clinical evidence updates and vigilance reporting to competent authorities. Manufacturers serving France, Germany, and Italy must maintain notified body relationships for technical file reviews beyond initial conformity assessments. Emergency tray suppliers face compressed timelines for adverse event documentation compared with elective surgical tray categories.
Hospital value analysis committees now require total cost-of-ownership modeling that incorporates waste disposal, labor assembly time, and infection-related readmission risk. United States integrated delivery networks in the Midwest and Southeast substitute standardized tray formats for physician-specific custom kits, overriding individual surgeon preference cards through supply chain governance committees.
Global Procedure Trays Market Segmentation
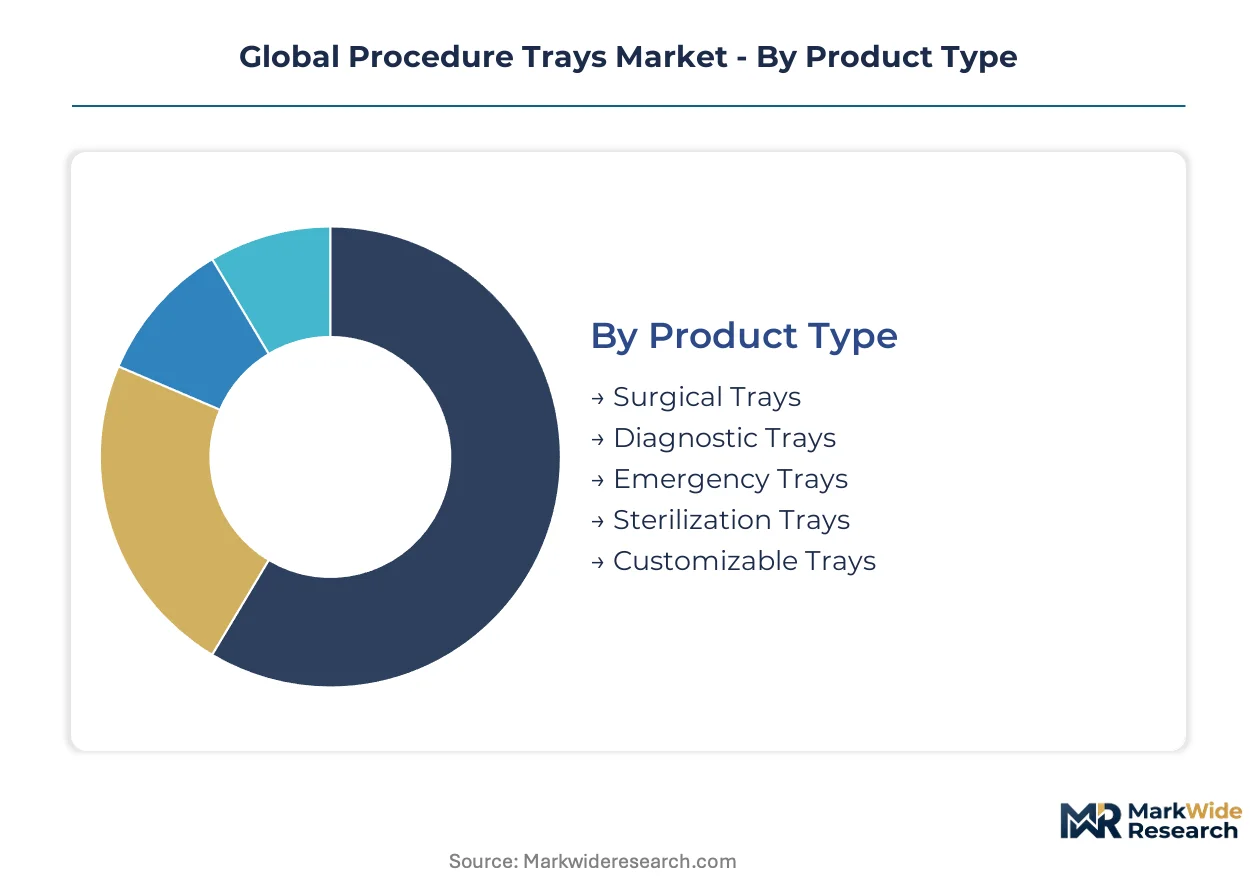
Procedure tray manufacturers configure product portfolios around intervention-specific risk profiles and sterilization validation requirements. Segment boundaries shift as integrated delivery networks consolidate purchasing across cardiology, orthopedics, and emergency service lines.
Product Type:
Reusable metal instrument reprocessing systems threaten volume across polyethylene-based disposable configurations, particularly in German and Japanese hospital purchasing cooperatives evaluating total cost-of-ownership models.
- Surgical Trays:Pre-assembled sterile collections of scalpels, forceps, drapes, and suction devices configured for specific operative interventions, typically gamma-sterilized in Tyvek or polyethylene-film pouches. United States hospital systems in the Midwest and Southeast drive procurement through value analysis committees overriding individual surgeon preference cards.
- Emergency Trays:Rapid-deployment assemblies for trauma and pre-hospital protocols containing airway management tools, vascular access devices, and hemorrhage control supplies. Florida, Texas, and Arizona ambulatory surgical centers and emergency medical services standardize configurations to compress field-to-facility transfer times.
- Diagnostic Trays:Specimen collection and biopsy instrument arrays for laboratory and imaging-guided procedures.
- Sterilization Trays:Rigid container systems for reusable instrument reprocessing workflows in central sterile supply departments.
- Customizable Trays:Modular configurations allowing physician-specific preference card matching for orthopedic and laparoscopic specialties.
Surgical Trays retain volume leadership; Emergency Trays hold the steepest expansion curve.
Application:
Reimbursement compression in elective categories is redirecting manufacturer R&D investment toward outpatient-compatible formats that reduce procedure time and same-day discharge risk.
- Cardiology:Catheterization and electrophysiology procedure kits containing guidewires, introducer sheaths, and hemostasis management devices. German and French hospitals integrate these with closed-system drug transfer protocols for anticoagulant handling under EU MDR traceability mandates.
- Orthopedics:Arthroscopy and joint replacement instrument assemblies with bone cement mixing systems and powered handpiece drapes. United States ambulatory surgical centers in Florida and Texas displace hospital outpatient departments for these high-margin configurations.
- General Surgery:Open and laparoscopic procedure kits spanning appendectomy to cholecystectomy interventions.
- Dermatology:Biopsy and excision instrument sets for office-based surgical procedures.
- Urology:Cystoscopy and nephrostomy tray configurations for stone management and stent placement.
Orthopedics commands premium pricing tiers; Cardiology demonstrates the most rapid outpatient migration.
End User:
Laboratory certification bottlenecks and technician training pipelines constrain throughput expansion across diagnostic and clinical settings differently.
- Hospitals:Acute-care facilities with centralized sterile processing departments managing high-volume surgical schedules through vendor-managed inventory programs. United States integrated delivery networks negotiate multi-year contracts bundling trays with pharmaceutical distribution through captive channels.
- Ambulatory Surgical Centers:Outpatient facilities requiring customizable private-label configurations matching physician preference cards with compressed turnaround requirements. These centers in Florida, Texas, and Arizona generate the highest margin realization for tray suppliers.
- Diagnostic Laboratories:Independent and hospital-affiliated testing facilities consuming specimen collection and processing tray formats.
- Specialty Clinics:Dermatology, urology, and pain management practices with procedure-specific kit requirements.
Hospitals retain procurement volume dominance; Ambulatory Surgical Centers deliver the sharpest margin expansion.
Distribution Channel:
Consolidation among medical-surgical distributors is compressing intermediary margins and forcing direct engagement models for high-volume hospital accounts.
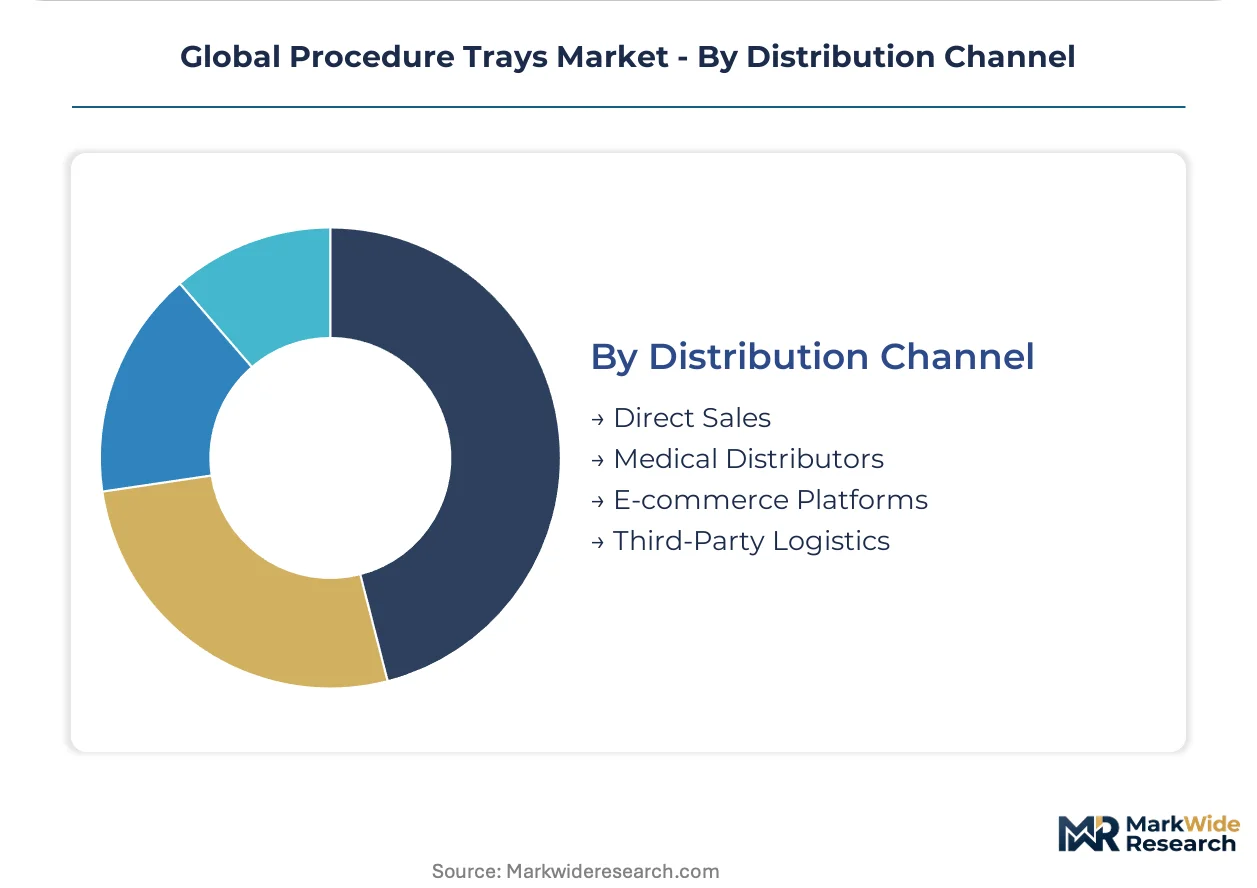
- Direct Sales:Manufacturer field representatives contracting directly with United States integrated delivery networks and German hospital purchasing cooperatives, capturing demand signals through real-time utilization data feeds and custom API integration with hospital ERP systems.
- Medical Distributors:Cardinal Health and regional wholesalers maintaining inventory positions for mid-tier hospitals and specialty clinics.
- E-commerce Platforms:Digital procurement portals serving independent practices and smaller ambulatory facilities.
- Third-Party Logistics:Temperature-controlled sterilization validation and last-mile delivery services for just-in-time tray replenishment.
Direct Sales commands contract value concentration; E-commerce Platforms climb fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States hospital systems prioritize vendor-managed inventory and multi-year bundled contracts, while European purchasers emphasize material traceability and sterilization modality compliance under stricter emission regulations.
United States
Integrated delivery networks in the Midwest and Southeast drive procurement through value analysis committees that override individual surgeon preference cards with standardized tray formats. The FDA enforces 510(k) premarket notification and updated ethylene oxide residual testing requirements. Cardinal Health leverages its captive distribution network to sustain direct-to-hospital contracts across Florida, Texas, and Arizona ambulatory surgical centers.
Germany
Hospital purchasing cooperatives evaluate metal instrument reprocessing systems against single-use tray configurations, threatening volume erosion in orthopedic categories. The EU Medical Device Regulation mandates unique device identification and post-market surveillance for class IIa and above procedure kits. B. Braun SE anchors its position through manufacturing clusters in the Melsungen region with ISO 13485-certified infrastructure.
France
Acute-care facilities integrate closed-system drug transfer protocols with chemotherapy procedure trays under hazardous drug handling mandates. ANSM vigilance reporting requirements compress timelines for adverse event documentation in emergency tray categories. The Paris-Saclay medical technology corridor hosts sterilization validation service providers serving Benelux export markets.
Japan
Metropolitan hospital systems in Tokyo and Osaka adopt pre-packaged sterile kits to address perioperative nursing shortages and compress operating room turnover. PMDA quality system regulation compliance requires bioburden documentation and gamma sterilization validation for imported tray assemblies. The Kansai region maintains concentration of central sterile supply department automation vendors.
United Kingdom
NHS procurement frameworks prioritize polyethylene-film pouches with gamma sterilization over ethylene oxide methods to meet carbon reduction targets. The Medicines and Healthcare products Regulatory Agency enforces vigilance reporting aligned with EU MDR transitional arrangements. London teaching hospitals pilot biodegradable polymer films derived from polylactic acid for environmental compliance reporting.
Global Procedure Trays Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the procedure trays market. The upper tier commands multi-year supply contracts through captive distribution channels and bundled pharmaceutical distribution arrangements. Specialist manufacturers occupy position through customizable private-label configurations for ambulatory surgical centers and procedure-specific physician preference card matching. Dominant competitive moves include backward integration into sterilization validation services and geographic expansion through notified body relationships for EU MDR technical file reviews.
Among United States-based integrated distributors, Cardinal Health exemplifies the captive-channel archetype through direct-to-hospital contract structures. Medline Industries occupies a position within the private-label customization tier, serving ambulatory surgical center channels with modular tray configurations. Becton, Dickinson and Company anchors the R&D-intensive specialist segment, bundling closed-system drug transfer devices with sterile field assemblies for oncology infusion centers.
| Leading Market Players |
|---|
| Cardinal Health |
| Owens & Minor |
| Becton, Dickinson and Company |
| Medline Industries |
| Baxter International |
| B. Braun SE |
| Teleflex Incorporated |
| Boston Scientific |
| Mölnlycke Health Care |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day sterilization validation queues at contract facilities concentrate pricing leverage among incumbent tray manufacturers with captive ethylene oxide and gamma capacity, compressing margins for second-tier suppliers dependent on third-party sterilization service providers. This lead-time bottleneck reinforces multi-year offtake contracts between United States integrated delivery networks and vertically integrated distributors, locking in volume commitments that insulate top-tier suppliers from spot-market polyethylene-film pricing volatility.
Pricing Analysis
Long-term offtake agreements dominate procurement between United States hospital systems and tray manufacturers, with three-year bundled contracts locking in pharmaceutical distribution alongside sterile kit supply. Price differentiation hinges on ISO 13485 certification tier and customization depth for physician preference card matching, with ambulatory surgical centers in Florida and Texas commanding premium-mid-economy pricing differentiation for modular configurations. Pricing pressure stems from German hospital purchasing cooperatives evaluating reusable metal instrument reprocessing systems against disposable alternatives. Academic medical centers demonstrate lowest price sensitivity due to total cost-of-ownership modeling requirements, while independent specialty clinics face acute budget constraints.
Supply Chain Analysis
Gulf Coast petrochemical corridor concentration creates chokepoint exposure for medical-grade polyethylene and polypropylene feedstock, with hurricane-season production outages disrupting tray film supply to North American contract manufacturers. Raw material sourcing draws from United States, Germany, and China for polymer concentrates, sterilization validation equipment, and automated packaging machinery. Single-source vulnerability concentrates in ethylene oxide sterilization facilities facing EPA emission cap enforcement. Distribution runs through captive direct-sales channels for high-volume hospital accounts and medical-surgical distributors for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procedure tray markets sit in early-cycle expansion as ambulatory surgical center penetration accelerates and EU MDR traceability mandates force hospital system consolidation around certified suppliers. Pre-packaged sterile kit adoption is displacing in-house sterilization workflows across North American and Western European acute-care facilities.
For Market Incumbents: Compound market position through backward integration into gamma sterilization validation services, capturing capacity constrained by EPA ethylene oxide emission caps. Deepen hospital system partnerships through real-time utilization data feeds and custom API integration with enterprise resource planning systems. Defend against German purchasing cooperative evaluation of reusable instrument reprocessing by embedding total cost-of-ownership analytics into value analysis committee presentations.
For New Entrants and Emerging Players: Differentiate on biodegradable polymer film configurations for United Kingdom and California academic medical centers piloting compostable pouch structures for environmental compliance reporting. Target ambulatory surgical center channels in Arizona and Texas with private-label customizable tray configurations matching procedure-specific physician preference cards. Pursue direct-to-facility digital procurement platforms serving independent specialty clinics outside integrated delivery network capture.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because sterile supply technician certification bottlenecks and EU MDR compliance costs are structurally advantaging scaled manufacturers with notified body relationships and automated serialization infrastructure. Acquisition target archetype: ISO 13485-certified regional manufacturers with established hospital system contracts in Germany, France, or United States Midwest corridors. Signal to watch: EPA enforcement actions accelerating ethylene oxide facility closures and forcing sterilization modality migration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Certification | Notified body relationships unlock France, Germany, and Italy hospital procurement frameworks under post-market surveillance mandates. |
| Gamma Sterilization Capacity Expansion | EPA emission caps on ethylene oxide force modality shift and reward early movers with validated electron-beam infrastructure. |
| Biodegradable Film Pilot Programs | United Kingdom NHS carbon reduction targets and California environmental compliance reporting create sustainability-positioned entry wedge. |
| Direct-to-Hospital ERP Integration | Real-time tray utilization data feeds enable vendor-managed inventory programs locking out distributor intermediaries. |
| Ambulatory Surgical Center Channel Capture | Florida, Texas, and Arizona outpatient facilities generate highest margin realization and displace hospital outpatient departments. |
Research Methodology
Operator-level perspectives from sterile supply technicians, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork across United States integrated delivery networks, German hospital purchasing cooperatives, and French acute-care facilities combined with secondary validation through FDA 510(k) filings, EU MDR notified body technical file databases, hospital procurement contract registries, and ISO 13485 certification records. Bottom-up tray volume modeling and top-down healthcare expenditure triangulation converged on segment-level estimates.
Sensitivity analysis across sterilization modality adoption curves, ambulatory surgical center expansion rates, and polymer feedstock pricing volatility shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application specialty, end-user facility class, and distribution channel structure, with regional regulatory cluster differentiation for FDA, EU MDR, and PMDA jurisdictions. CAGRs derived from procedure volume growth, tray penetration rates, and average selling price trajectories calibrated against hospital capital expenditure surveys and surgical services department budget forecasts.
Material uncertainties — EPA ethylene oxide enforcement intensity, EU MDR transitional arrangement extensions, Gulf Coast hurricane season severity — sit outside the modeled envelope. Forecasts reflect assumptions regarding technician certification pipeline recovery and sterilization service provider capacity expansion. Revision becomes warranted when ambulatory surgical center reimbursement compression crosses thresholds forcing facility closures or when biodegradable film performance validation fails to meet bioburden containment standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Ethylene-Vinyl Acetate [EVA] Infusion Bags Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Healthcare Packaging Market