
 Middle East and Africa Parenteral Packaging Market | 2026-2036
Middle East and Africa Parenteral Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Parenteral Packaging Market Foresight
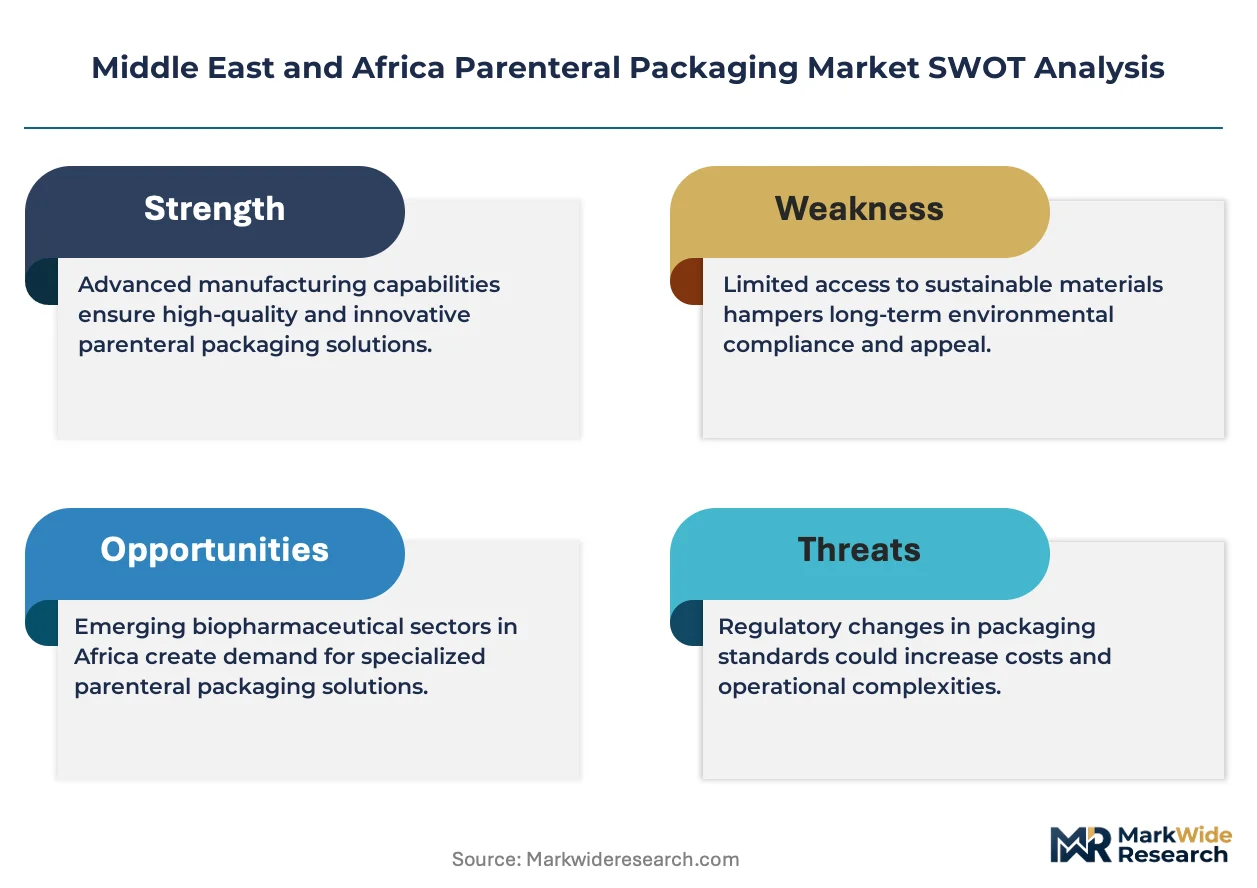
The EU Green Deal's extraterritorial sustainability reporting pressure is rebalancing procurement criteria for European-headquartered pharmaceutical companies operating African and Middle Eastern manufacturing sites. Gerresheimer AG anchors glass primary packaging supply through its established Middle Eastern distribution architecture. West Pharmaceutical Services differentiates via elastomer and closure system specialization for biologic drug containment. SGD Pharma competes on molded glass vial capacity serving contract manufacturers across North Africa.
Middle East and Africa Parenteral Packaging encompasses sterile containers, closures, and delivery systems designed for drugs administered via injection or infusion, typically manufactured from borosilicate glass or pharmaceutical-grade polymers with validated endotoxin limits and particulate controls. These systems maintain sterility, dosage accuracy, and chemical stability for liquid, lyophilized, or powder formulations across hospital, clinic, and home care settings. Plastic and polypropylene materials are gaining share in infusion bag applications where weight reduction and breakage resistance outweigh traditional glass preferences. The biologics end user segment commands premium positioning due to stringent protein stability requirements and escalating biosimilar production across the region.
South Africa's Medicines Control Council, Saudi Arabia's SFDA, and Egypt's Drug Authority enforce escalating serialization and track-and-trace mandates that reshape packaging line investments and vendor qualification timelines. The WHO prequalification program and African Medicines Regulatory Harmonization initiative further compress technical documentation standards for suppliers seeking public procurement access. Stakeholders must monitor regulatory convergence velocity between national authorities and harmonization frameworks to anticipate qualification cost trajectories and localization incentives.
Market Dynamics
Biologics cold-chain expansion across Gulf Cooperation Council states is compressing qualification timelines for container closure systems while tightening endotoxin and particulate specifications. Saudi Arabia's SFDA serialization mandates and South Africa's Medicines Control Council harmonization with ICH standards are forcing packaging line retrofits and vendor requalification cycles.
Growth Catalysts
- WHO Prequalification Program:The WHO prequalification pathway accelerates market access for parenteral packaging suppliers targeting African public procurement contracts, compressing documentation timelines for borosilicate glass and elastomer closure systems.
- Biosimilar Manufacturing Surge:Contract manufacturers in Egypt's 10th of Ramadan City and Morocco's Casablanca pharmaceutical zones are expanding lyophilized drug capacity, driving demand for validated vial and stopper configurations.
- Ready-to-Use (RTU) Formats:RTU syringes and cartridges are displacing traditional bulk packaging in Saudi Arabian hospital systems, reducing compounding errors and cutting pharmacy preparation time.
Market Restraints
- Pharmaceutical-Grade Polymer Feedstock Volatility:Cyclo-olefin polymer (COP) and cyclic olefin copolymer (COC) resin prices fluctuate with propylene and naphtha feedstock costs, squeezing margins for plastic primary packaging converters.
- Glass Tubing Supply Concentration:Borosilicate glass tubing production concentrates in European and Asian manufacturing clusters, exposing Middle Eastern and African fill-finish operations to extended lead times and freight cost spikes.
- Aluminum Substitution Threat:Multi-layer polymer films and high-barrier plastics are encroaching on aluminum overwrap applications in large-volume parenteral bags, particularly in weight-sensitive home infusion segments.
Strategic Opportunities
- Underpenetrated North African Contract Manufacturing:Tunisia's offshore pharmaceutical parks and Algeria's import-substitution industrial zones offer greenfield capacity for parenteral packaging localization serving Maghreb and Sub-Saharan markets.
- Connected Packaging Integration:Near-field communication (NFC) and radio-frequency identification (RFID) tags embedded in secondary packaging are converging with serialization mandates to enable real-time cold-chain monitoring.
- SFDA Localization Incentives:Saudi Arabia's National Strategy for Industry and Advanced Manufacturing offers tariff relief and preferential procurement access for domestic parenteral packaging production.
Industry Challenges
- Container Closure Integrity Validation:Demonstrating microbial ingress resistance and seal integrity for novel elastomer formulations requires extended stability studies and method development, stretching R&D timelines.
- Cleanroom Infrastructure Capex:ISO 14644-1 Class 7 and Class 8 cleanroom construction for vial washing, depyrogenation, and sterilization operations demands substantial capital deployment with multi-year payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Parenteral Packaging Market |
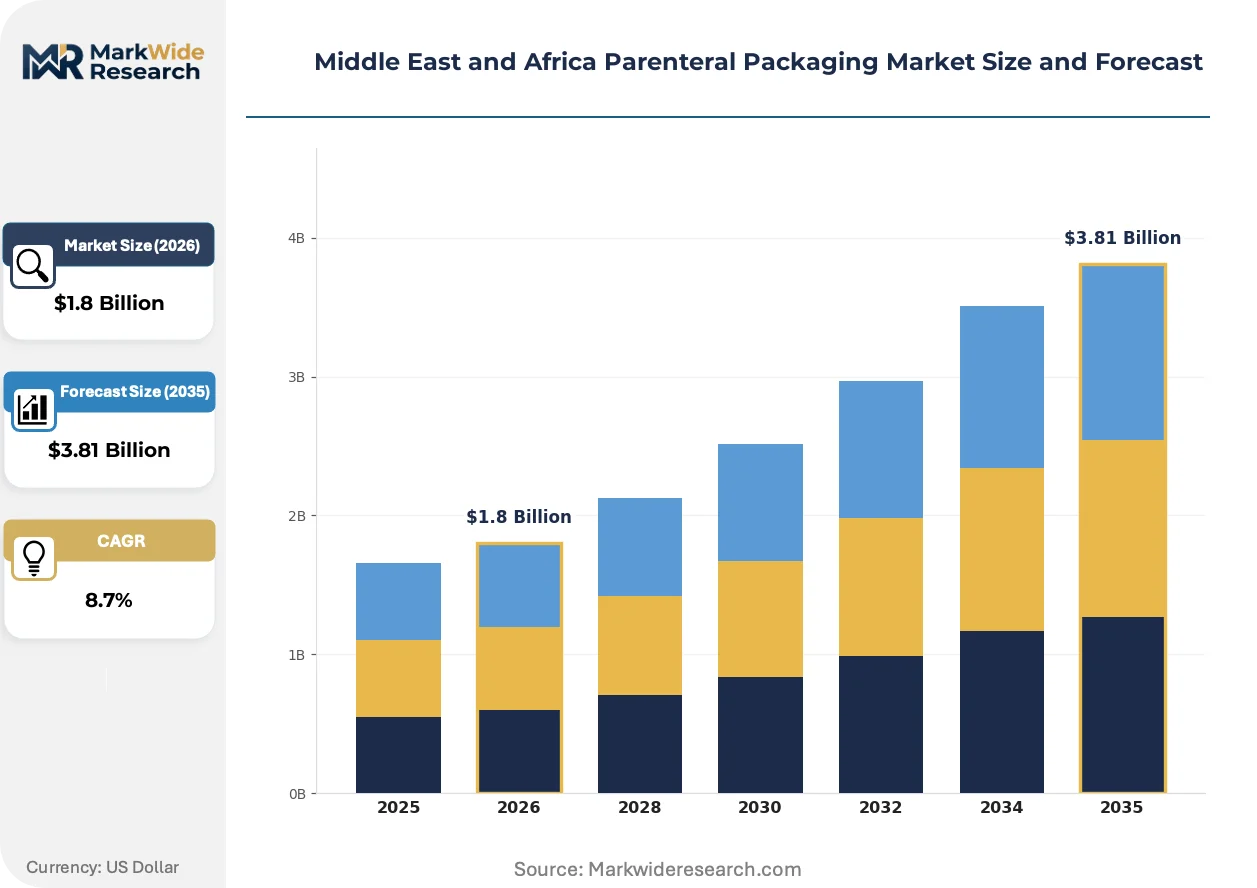
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Ampoules, Infusion Bags Material: Glass, Plastic, Polyethylene, Polypropylene Application: Hospital, Clinic, Home Care, Laboratory End User: Pharmaceuticals, Biologics, Contract Manufacturers, Medical Device Companies |
| Companies Covered | Amcor plc, AptarGroup, Inc., Gerresheimer AG, Schott AG, Berry Global, Inc., West Pharmaceutical Services, Nipro Corporation, Stevanato Group S.p.A., SGD Pharma, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Parenteral Packaging Market Shifts & Advancements
Polymer-based primary packaging is displacing glass in select parenteral applications where breakage resistance and design flexibility outweigh traditional material preferences. Regulatory pressure on extractables and leachables is simultaneously accelerating material science investment.
Ready-to-use (RTU) nested vial and syringe formats are integrating into high-speed fill-finish lines across Egyptian and Saudi contract manufacturing organizations. Biologics producers are adopting these formats to eliminate glass-to-glass contact during line loading, reducing particulate generation and cutting changeover downtime. The technology is integrating sterile barrier integrity directly into the nested tub configuration, collapsing separate component handling steps.
South Africa's Medicines Control Council alignment with ICH Q3D elemental impurity guidelines and the EU's revised Annex 1 sterile manufacturing standards are tightening extractables testing protocols for elastomer and plastic primary packaging. Suppliers must now submit comprehensive chemical characterization data across multiple solvent systems and accelerated aging conditions. Biologic drug manufacturers in King Abdullah Economic City are prioritizing vendors with pre-validated extractables libraries to compress qualification timelines.
Hospital and clinic buyers are consolidating parenteral packaging procurement through group purchasing organizations and centralized pharmacy committees, displacing fragmented distributor-led purchasing. Saudi Arabia's National Unified Procurement Company and South Africa's public sector tender systems are concentrating volume with suppliers offering integrated closure-vial-label configurations. This concentration is most visible in oncology and biologic infusion segments where medication error prevention drives standardization mandates.
Middle East and Africa Parenteral Packaging Market Segmentation
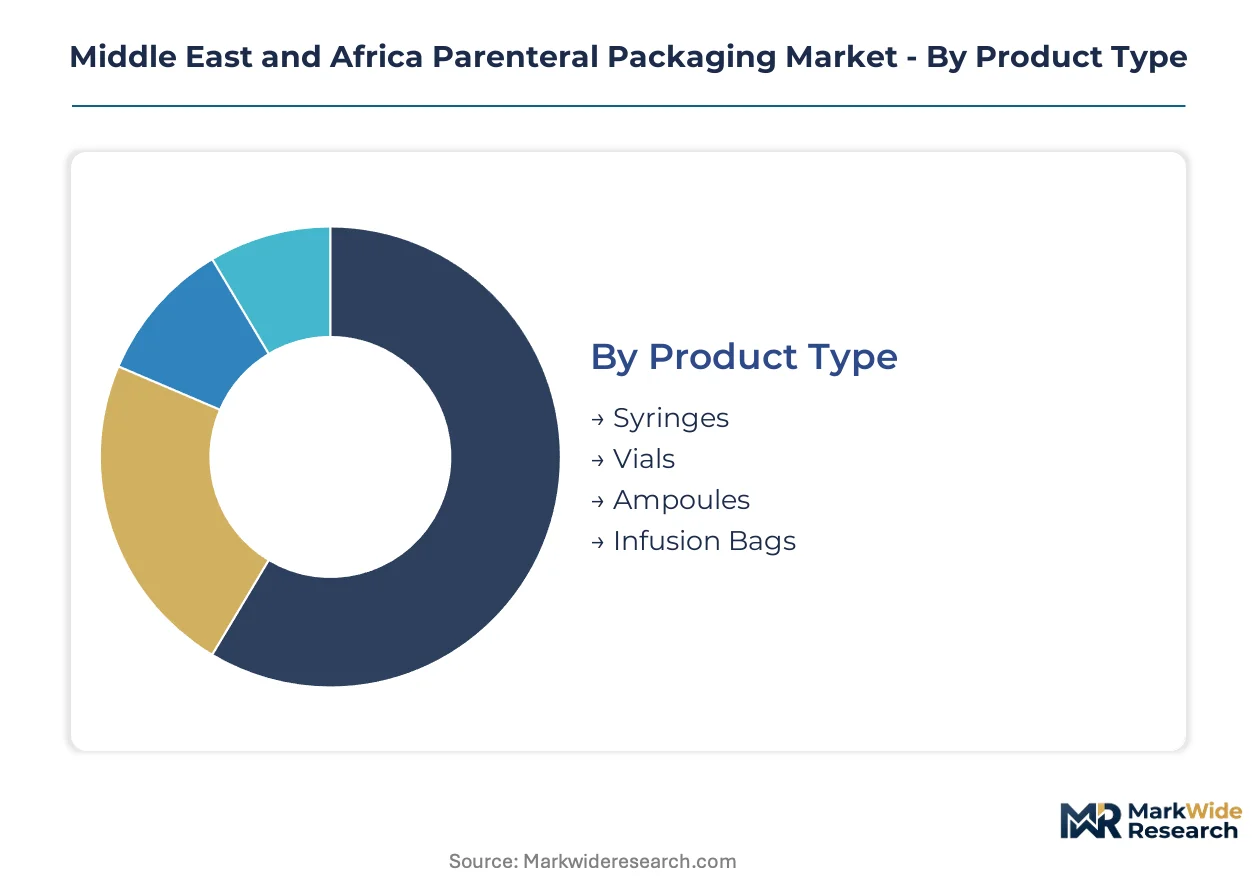
Parenteral packaging selection across the Middle East and Africa hinges on cold-chain compatibility, regulatory serialization readiness, and fill-finish line integration. Each segmentation dimension reveals distinct procurement hierarchies among Saudi biologics clusters, Egyptian contract manufacturers, and South African hospital systems.
Product Type:
Buyers prioritize container closure integrity validation and line speed compatibility when selecting primary packaging formats for sterile injectables.
- Syringes:Ready-to-use prefillable syringes integrate nested tub configurations that eliminate glass-to-glass contact during line loading. Demand concentrates in Saudi Arabia's King Abdullah Economic City biologics facilities where pharmacy error reduction drives standardization.
- Vials:Borosilicate glass vials with validated elastomer closures dominate lyophilized drug containment. Egyptian contract manufacturers in 10th of Ramadan City are expanding molded glass capacity to serve biosimilar production.
- Ampoules:Single-dose glass ampoules retain niche positioning in emergency medicine and anesthetic applications across North African hospital systems.
- Infusion Bags:Large-volume parenteral bags shift toward multi-layer polymer films in home infusion segments where weight reduction outweighs traditional glass preferences.
Volume sits with vials; growth tilts toward syringes.
Material:
Material selection trades off extractables profile certainty against breakage resistance and design flexibility in container closure systems.
- Glass:Borosilicate tubing offers proven chemical inertness and barrier properties for protein-based therapeutics. South Africa's Medicines Control Council alignment with ICH Q3D guidelines tightens elemental impurity testing protocols for glass primary packaging.
- Plastic:Cyclo-olefin polymers enable break-resistant designs for portable injection devices. Moroccan pharmaceutical zones favor plastic vials for temperature-sensitive logistics across the Maghreb.
- Polyethylene:Low-density polyethylene films serve secondary packaging and overwrap functions in infusion bag applications.
- Polypropylene:Polypropylene resins form rigid container bodies and closure components with validated endotoxin limits for sterile drug contact.
Glass commands revenue concentration; plastic gains share fastest in portable delivery formats.
Application:
Site-of-care administration requirements dictate packaging format complexity and secondary labeling specifications.
- Hospital:Centralized pharmacy compounding drives demand for RTU nested configurations and integrated closure-vial-label systems. Saudi Arabia's National Unified Procurement Company concentrates volume with standardized oncology and biologic infusion packaging.
- Clinic:Outpatient injection settings favor single-unit packaging with tamper-evident features and simplified preparation protocols.
- Home Care:Patient self-administration requirements push break-resistant polymer designs and intuitive delivery mechanisms in Gulf Cooperation Council markets.
- Laboratory:Research and diagnostic applications sustain demand for bulk non-sterile containers and customizable closure configurations.
Hospital procurement dominates volume; home care applications expand most quickly with biosimilar self-injection trends.
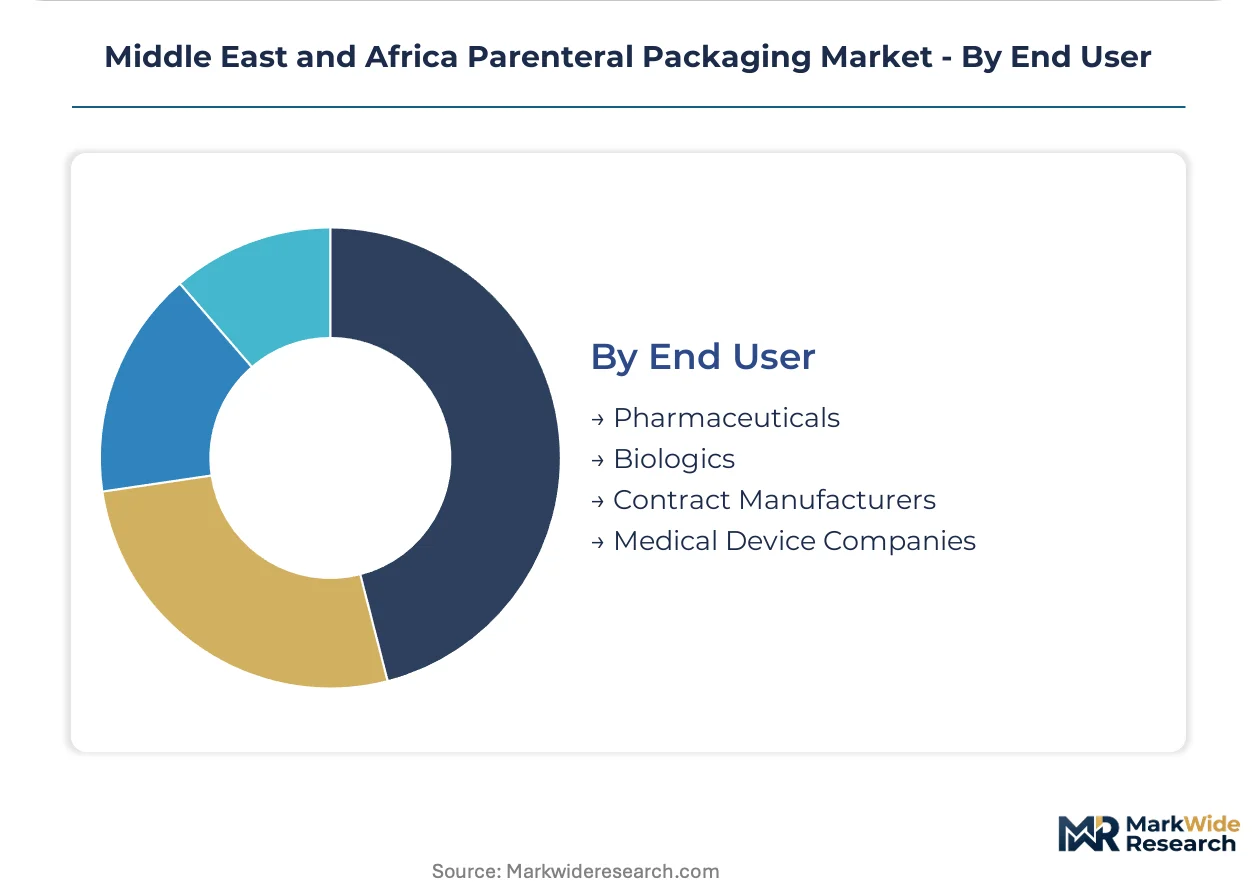
End User:
End-user technical specifications diverge sharply between mass-market generics and high-value biologics containment requirements.
- Pharmaceuticals:Small-molecule injectable manufacturers prioritize cost-efficient glass vial and rubber stopper combinations across high-volume antibiotic and analgesic production.
- Biologics:Protein stability demands drive premium positioning for pre-validated extractables libraries and specialized elastomer formulations. King Abdullah Economic City producers compress vendor qualification timelines through pre-approved containment systems.
- Contract Manufacturers:Egyptian and Moroccan fill-finish operations seek flexible packaging configurations serving multiple client specifications with rapid changeover capability.
- Medical Device Companies:Combination product developers integrate prefilled syringes and cartridges into auto-injector and pen delivery platforms for chronic disease management.
Pharmaceuticals anchor volume scale; biologics capture margin concentration with qualification-intensive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City anchors pharmaceutical packaging demand across the Middle East and Africa, with Saudi Arabia's biologics cluster driving container closure system procurement at scale. Egypt's contract manufacturing zones and South Africa's regulatory harmonization create complementary demand poles. Regulatory serialization mandates and cold-chain infrastructure investments reshape vendor qualification timelines from the Gulf to the Maghreb.
Saudi Arabia
SFDA serialization mandates and biologics cold-chain expansion compress vendor qualification timelines for elastomer and glass containment systems. The National Strategy for Industry and Advanced Manufacturing offers tariff relief for domestic parenteral packaging production. King Abdullah Economic City concentrates fill-finish capacity where producers prioritize pre-validated extractables libraries.
Egypt
Contract manufacturers in 10th of Ramadan City expand lyophilized drug capacity, driving demand for validated vial and stopper configurations. The country's drug authority enforces escalating track-and-trace mandates that reshape packaging line investments. Egyptian pharmaceutical zones serve as export hubs for Maghreb and Sub-Saharan markets with cost-efficient glass and rubber stopper combinations.
South Africa
The Medicines Control Council's alignment with ICH Q3D elemental impurity guidelines tightens testing protocols for glass primary packaging. Public sector tender systems concentrate volume with suppliers offering integrated closure-vial-label configurations. Gauteng and Western Cape provinces host hospital systems adopting ready-to-use nested formats to reduce pharmacy compounding errors.
Morocco
Casablanca pharmaceutical zones favor plastic vials for temperature-sensitive logistics across the Maghreb region. The country's industrial acceleration plan supports import-substitution for parenteral packaging serving domestic and West African markets. Tangier-Med port infrastructure enables re-export of polymer-based primary packaging to European contract manufacturers.
United Arab Emirates
MOHAP regulatory frameworks align with Gulf Cooperation Council harmonization standards for sterile manufacturing. Dubai's pharmaceutical free zones attract regional headquarters for packaging distributors serving African markets. Jebel Ali port logistics support just-in-time delivery of borosilicate glass tubing to fill-finish operations across the GCC.
Middle East and Africa Parenteral Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification intensity and extractables validation capabilities. The vendor base stratifies between integrated glass-elastomer-closure system suppliers and specialized component converters. Three archetypes dominate: full-system integrators, material-specific specialists, and regional distribution anchors. Competitive moves concentrate on strategic partnerships for cold-chain validation and capacity expansion in underpenetrated North African markets.
Among European-anchored system integrators, Gerresheimer AG and SGD Pharma exemplify the full-containment archetype through established Middle Eastern distribution architectures. West Pharmaceutical Services occupies a distinct position as an elastomer and closure specialist serving biologic drug containment requirements. These three companies represent the premium-tier vector where qualification-intensive procurement and pre-validated extractables libraries determine vendor selection.
| Leading Market Players |
|---|
| Amcor plc |
| AptarGroup, Inc. |
| Gerresheimer AG |
| Schott AG |
| Berry Global, Inc. |
| West Pharmaceutical Services |
| Nipro Corporation |
| Stevanato Group S.p.A. |
| SGD Pharma |
| Others |
Supply & Pricing Matrix
Specialized cleanroom technicians in Egypt's 10th of Ramadan City pharmaceutical corridor create labor-cost differentials that widen pricing-tier spreads between premium biologics containment systems and commodity glass vial configurations. These workforce concentrations enable Egyptian contract manufacturers to undercut Saudi and UAE fill-finish operations on standard rubber stopper and molded glass combinations while King Abdullah Economic City biologics facilities absorb premium pricing for pre-validated elastomer formulations.
Pricing Analysis
Yield-guaranteed pricing anchors the biologics segment where protein stability failures trigger catastrophic batch losses. Three-tier pricing structure across premium, standard, and economy levels separates ICH Q3D-compliant pre-validated systems from basic USP Class VI configurations and non-certified commodity alternatives. Cost compression in the economy tier intensifies because Egyptian and Moroccan converters compete on volume scale for antibiotic and analgesic manufacturers. Contract manufacturers in North African pharmaceutical zones exhibit highest price sensitivity; Saudi biologics producers prioritize qualification speed over unit cost.
Supply Chain Analysis
Direct-to-CMO channels handle hyperscale demand from Egyptian and Saudi contract manufacturers while distributor-led procurement serves fragmented North African hospital systems. Borosilicate glass tubing production concentrates in Germany, China, and India; elastomer formulation expertise clusters in France, Italy, and Japan. Raw material dependencies include pharmaceutical-grade propylene for cyclo-olefin polymers, naphtha derivatives for glass melting, and halobutyl rubber for closure systems. Single-source vulnerability pervades the glass tubing segment where Middle Eastern fill-finish operations lack captive melting capacity. Distribution runs through Dubai's Jebel Ali pharmaceutical free zones for GCC markets and Tangier-Med port infrastructure for Maghreb re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-to-use nested vial and syringe formats are displacing traditional bulk packaging across Middle Eastern and African fill-finish operations, compressing vendor qualification timelines and reshaping procurement hierarchies. This technology transition favors suppliers with pre-validated extractables libraries and ISO 14644-1 cleanroom infrastructure.
For Market Incumbents: Anchor market position through backward integration into borosilicate glass tubing supply and captive elastomer formulation capacity. Defend against polymer substitution threats by embedding sterile barrier integrity directly into nested tub configurations. Prioritize SFDA localization certification to capture Saudi tariff relief and preferential procurement access. For New Entrants and Emerging Players: Begin with underpenetrated Tunisian offshore pharmaceutical parks and Algeria's import-substitution industrial zones where parenteral packaging localization remains nascent. Target contract manufacturing organizations in Morocco's Casablanca pharmaceutical zone seeking flexible packaging configurations with rapid changeover capability. Pursue WHO prequalification pathway acceleration to unlock African public procurement contracts. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap elastomer specialists given biologics cold-chain expansion across Gulf Cooperation Council states. Long-term viability centers on suppliers with pre-validated extractables libraries and ICH Q3D compliance capabilities. Monitor SFDA serialization mandate enforcement velocity as inflection indicator for packaging line retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Infrastructure Expansion | ISO 14644-1 Class 7 certification unlocks Saudi biologics procurement at King Abdullah Economic City. |
| Extractables Library Pre-Validation | ICH Q3D-compliant chemical characterization data compresses vendor qualification timelines for biologics manufacturers. |
| WHO Prequalification Pathway | Accelerated documentation access opens African public sector tender systems for borosilicate glass containment. |
| Backward Integration into Glass Tubing | Captive borosilicate supply insulates against European and Asian production cluster lead time volatility. |
| Connected Packaging Integration | NFC and RFID convergence with SFDA serialization enables real-time cold-chain monitoring for temperature-sensitive biologics. |
Research Methodology
SFDA regulatory filings, WHO prequalification databases, and Egyptian Drug Authority track-and-trace mandate documentation formed the secondary backbone for market sizing and compliance trajectory analysis. Primary interviews with fill-finish operations directors, pharmaceutical packaging procurement managers, regulatory affairs leads at Saudi biologics manufacturers, and elastomer formulation R&D heads validated demand assumptions and qualification timeline estimates. Bottom-up volume triangulation across Egyptian contract manufacturing zones, Saudi biologics clusters, and South African hospital systems converged with top-down pharmaceutical production forecasts.
Historical trendline analysis of parenteral packaging procurement patterns across the analysis window informed baseline capacity utilization and pricing trajectory assumptions. The analytical framework segmented demand by product type, material composition, end-user technical specifications, and regional regulatory cluster. CAGRs were derived from weighted growth projections across biologics cold-chain expansion, biosimilar manufacturing surge, and ready-to-use format adoption curves. Forecast inputs incorporated SFDA localization incentive penetration rates and African Medicines Regulatory Harmonization initiative implementation velocity.
Underlying measurement precision varies by segment; biologics containment systems and pre-validated elastomer configurations carry tighter precision than commodity glass vial and rubber stopper combinations. Forecasts reflect assumptions regarding regulatory convergence velocity, polymer feedstock cost stability, and cleanroom infrastructure deployment timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
North America Medical Devices Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Syringe Trays Market