
 Global Computer to Plate Printing System Market | 2026-2036
Global Computer to Plate Printing System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer to Plate Printing System Market Intelligence
ISO 12647 process control certification is rotating the basis of competition from machine speed to output consistency and color accuracy. This standard forces printers to invest in systems that guarantee repeatable quality. Heidelberger Druckmaschinen AG leverages its strong position in integrated pressroom solutions to bundle CTP systems. Screen Holdings Co., Ltd. specializes in high-resolution thermal platesetters, while Eastman Kodak Company differentiates with its SONORA process-free plate technology.
A computer-to-plate printing system is an imaging technology that transfers a digital file directly onto a printing plate, bypassing the traditional film-to-plate step. These systems use lasers or inkjet heads to expose or etch images onto aluminum plates at resolutions often exceeding 2400 DPI. Thermal platesetters remain the dominant product type due to their reliability and high-quality output for commercial printing. The packaging application, however, represents the fastest-growing segment, driven by demand for customized labels and folding cartons.
Regulatory frameworks increasingly influence CTP technology choices, particularly regarding chemical usage and disposal. Europe's REACH regulation, the US EPA's rules on volatile organic compounds, and China's MEE directives on industrial waste push manufacturers toward chemistry-free or low-chemistry plates. This environmental pressure directly impacts R&D priorities for plate and equipment suppliers. The key decision for printing houses now centers on balancing the upfront investment in newer, greener CTP technology against the long-term operational savings and compliance benefits.
Market Dynamics
The central dynamic is the industry-wide push towards sustainable printing, driven by regulations like Europe's REACH and China's MEE directives. This force compels investment in process-free plates, shifting competition towards environmental compliance and operational efficiency over raw machine speed.
Growth Catalysts
- Packaging Sector Demand:Adoption within the packaging industry for high-quality labels, folding cartons, and flexible packaging is a primary catalyst. Consumer goods brands require consistent, high-resolution graphics that CTP systems provide.
- Environmental Regulations:Mandates such as Europe's REACH and US EPA rules on volatile organic compounds create a strong incentive for printers to switch to process-free or low-chemistry plates, boosting demand for compliant systems.
- Manufacturing Hubs:The concentration of export-oriented manufacturing in regions like China's Pearl River Delta drives localized demand for efficient, high-volume CTP systems to support the production of consumer goods.
Market Restraints
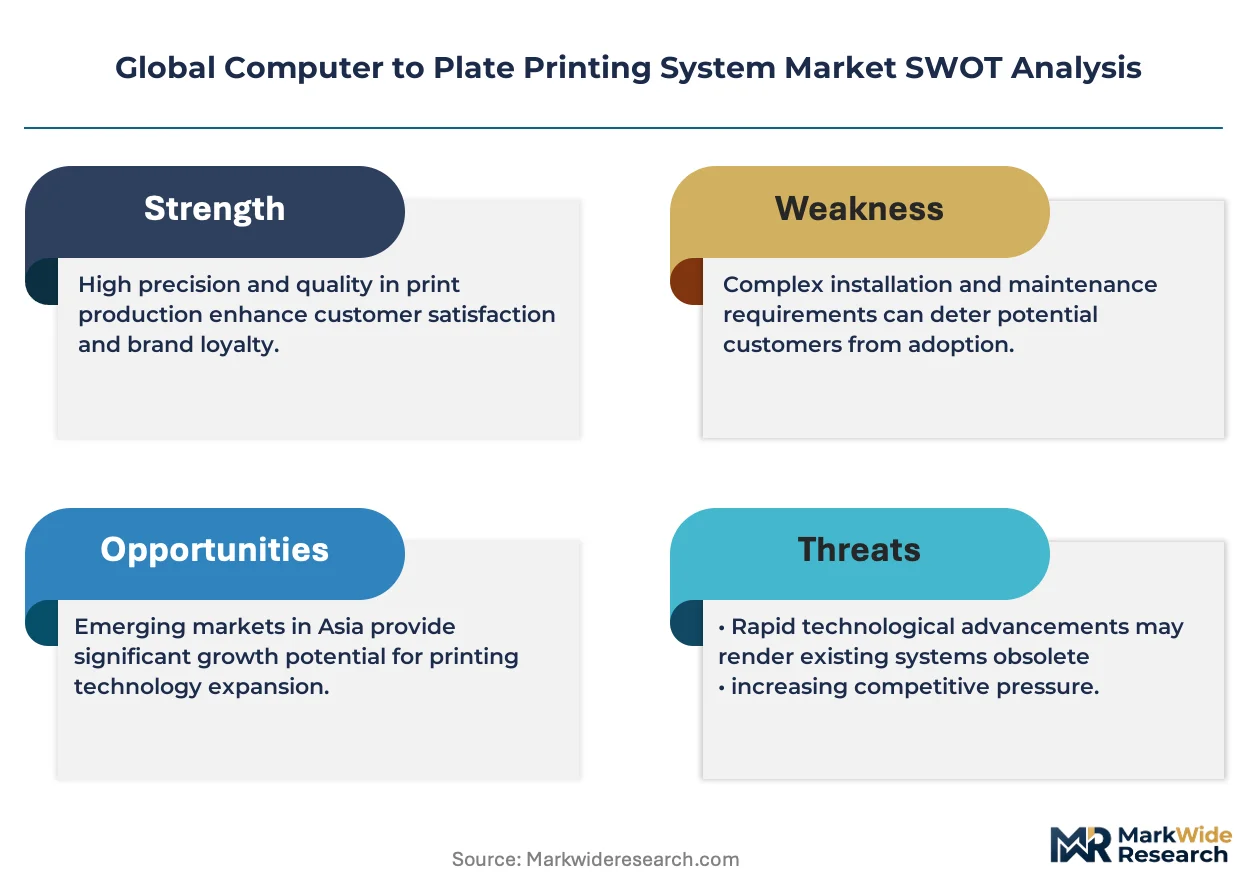
- High Capital Expenditure:The significant upfront investment required for advanced thermal CTP systems and platesetters presents a substantial barrier to entry for small and medium-sized printing businesses.
- Substitution by Digital Presses:For short-run print jobs, the increasing speed and quality of digital printing presses offer a viable plateless alternative, bypassing the need for CTP technology entirely.
- Input Material Volatility:Fluctuations in the global price of high-grade aluminum, the primary raw material for printing plates, introduce cost uncertainty and can compress profit margins for plate manufacturers and printers.
Strategic Opportunities
- Industrial Printing Applications:Expanding CTP technology for use in non-traditional sectors, such as decorative surface imaging or printed electronics, offers new avenues for market growth beyond commercial and packaging printing.
- Automation and AI Integration:Opportunities exist for vendors to develop CTP systems fully integrated with AI-powered pre-flight checks, robotic plate loading, and automated press-side quality controls.
- Emerging Market Penetration:Rapid industrialization and manufacturing growth in Southeast Asian countries, including Vietnam and Indonesia, present an underpenetrated market for modern CTP installations.
Industry Challenges
- Skilled Technician Scarcity:A shortage of pre-press operators with the specialized skills to manage modern, networked CTP workflows and color management software hinders efficient plant operation and technology adoption.
- Legacy System Integration:Connecting new CTP devices with older printing presses and disparate management information systems often leads to complex compatibility issues, implementation delays, and workflow disruptions.
- Certification Burden:Achieving and maintaining ISO 12647 certification is a resource-intensive process, requiring continuous investment in process control, calibration equipment, and staff training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer to Plate Printing System Market |
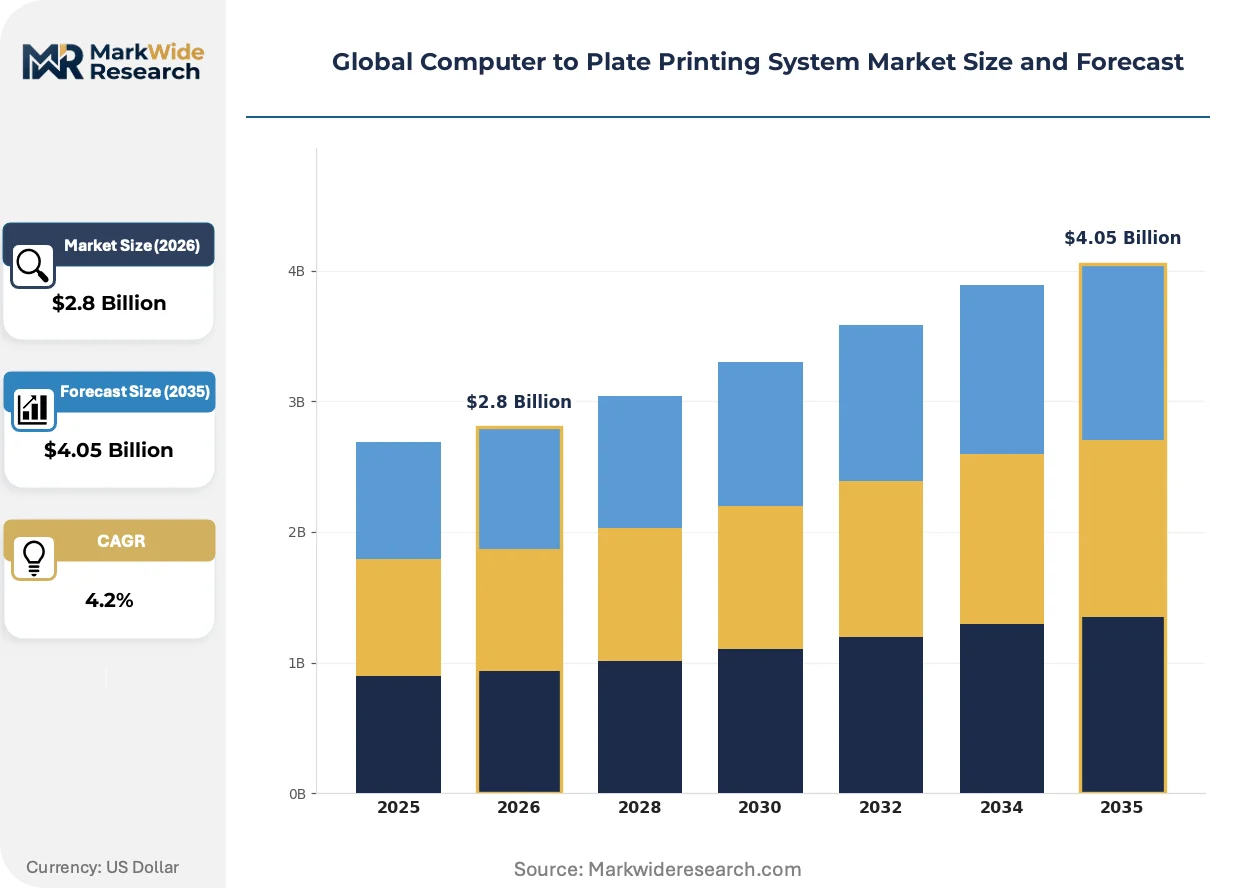
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Platesetter, Violet Platesetter, UV Platesetter, Infrared Platesetter, Inkjet Platesetter Technology: Thermal Imaging, Laser Imaging, Inkjet Imaging, UV Imaging, Violet Laser Imaging Printing Application: Packaging, Publication, Commercial Printing, Labels, Security Printing End User Type: Printing Houses, Advertising Agencies, Packaging Firms, Label Manufacturers, Security Printers |
| Companies Covered | Screen Holdings Co., Ltd., Esko, Eastman Kodak Company, Konica Minolta, Inc., Xeikon International, Fujifilm Holdings Corporation, Agfa-Gevaert Group, DuPont de Nemours, Inc., Heidelberger Druckmaschinen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer to Plate Printing System Market Strategic Shifts & Innovations
Technology within the computer-to-plate market is pivoting from speed-centric metrics toward integrated, automated workflows. This evolution is driven by a dual mandate for greater sustainability and certifiable output quality, fundamentally altering research and development priorities for equipment and plate suppliers.
Process-free plate technology eliminates the need for chemical developers, wash gum, and water in the pre-press stage. Commercial printers and packaging converters are adopting it to reduce their environmental footprint and simplify compliance. This technology is supplanting traditional wet-processed plates, thereby streamlining pre-press operations, reducing waste, and lowering total resource consumption in the print facility.
Europe's REACH regulation, which governs the registration, evaluation, and authorization of chemical substances, directly impacts the formulations used in plate coatings and processing chemistry. This forces plate manufacturers to reformulate products or seek safer alternatives to remain compliant for market access. The European commercial printing market is most affected, accelerating R&D investment into chemistry-free technologies to mitigate regulatory risk.
A distinct preference shift toward certified suppliers is evident among global brand owners, particularly in regulated industries. These buyers increasingly mandate that their print partners hold ISO 12647 certification to guarantee color consistency and quality across international marketing campaigns and packaging lines. This trend is most visible in the pharmaceutical and luxury consumer goods sectors in North America and Europe.
Global Computer to Plate Printing System Market Segmentation
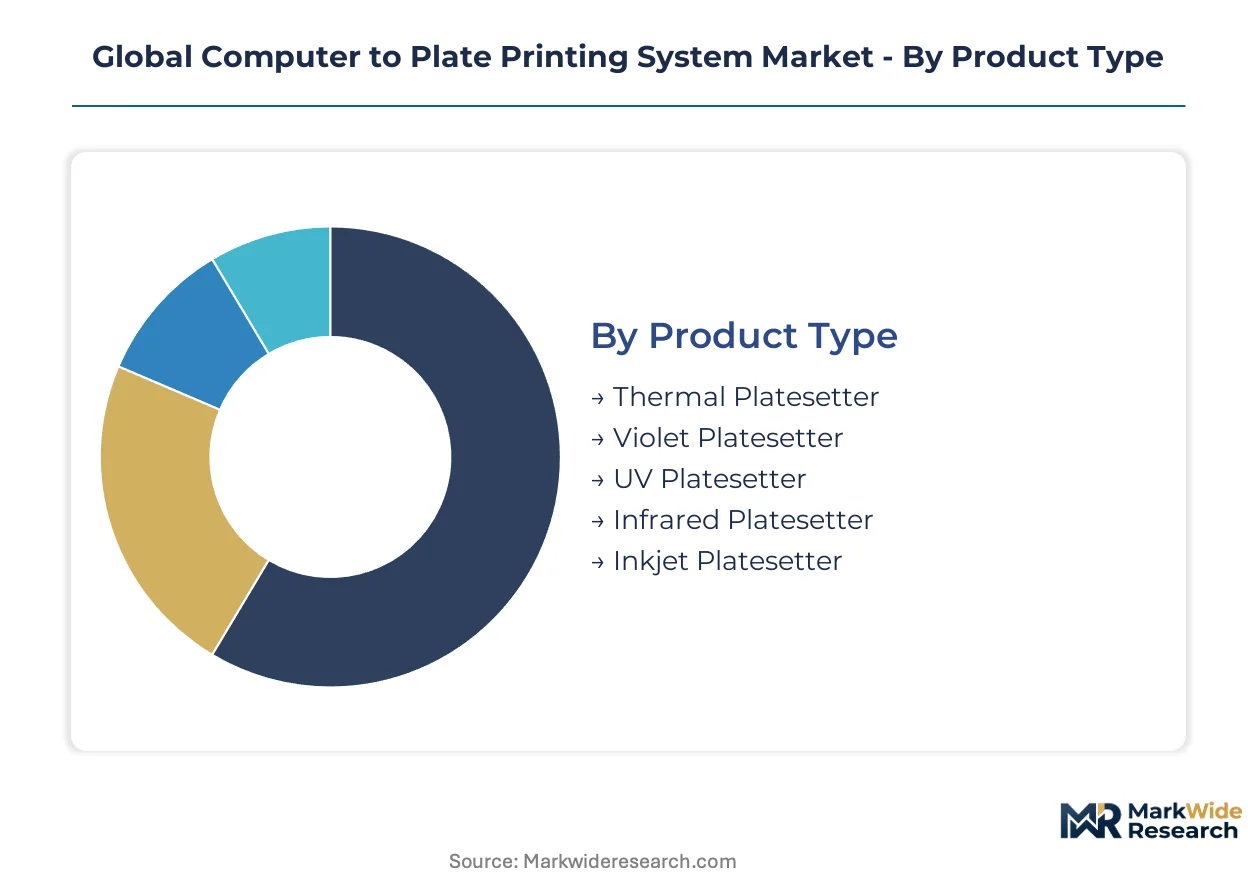
Understanding the Global Computer to Plate Printing System Market requires a detailed segmentation analysis. This breakdown clarifies the varied demands and technological preferences across different industry verticals. It helps identify specific growth pockets and competitive battlegrounds for CTP manufacturers and service providers.
Product Type:
Margin pools within the product type category often concentrate around advanced imaging capabilities and plate compatibility.
- Thermal Platesetter:These systems use heat-sensitive plates, offering high resolution and stability for commercial and packaging print. Demand is strong in Germany and Japan for demanding offset applications.
- Violet Platesetter:Utilizing violet laser diodes, these platesetters employ photopolymer plates, providing a cost-effective entry point for many smaller commercial printers. Adoption is notable in emerging markets seeking balance between cost and quality.
- UV Platesetter:UV platesetters use ultraviolet light to expose plates, often favored for their compatibility with conventional plate materials.
- Infrared Platesetter:Infrared platesetters leverage infrared lasers for plate exposure, known for their precision in specific industrial print jobs.
- Inkjet Platesetter:Inkjet platesetters apply liquid photopolymer directly to plates, offering flexibility for short-run and specialized applications.
Thermal Platesetter technology holds significant installed capacity globally. Violet Platesetter technology is rotating up the share rankings, particularly in cost-sensitive segments.
Technology:
Application focus dictates technology choice, aligning system capabilities with specific output requirements across print disciplines.
- Thermal Imaging:This technology uses thermal lasers to ablate or cross-link plate coatings, ensuring sharp dot reproduction and chemical stability. It is critical for high-volume commercial printing in North America.
- Laser Imaging:Encompassing various laser types, this technology offers precise image transfer onto plates, enabling fine detail and consistent quality across diverse print jobs. Large printing houses in France prioritize this for consistent brand color.
- Inkjet Imaging:Inkjet imaging systems deposit ink directly onto plate substrates, providing a flexible and often chemistry-free platemaking process.
- UV Imaging:UV imaging employs ultraviolet light sources for plate exposure, widely used for its compatibility with traditional photopolymer plates.
- Violet Laser Imaging:Violet laser imaging utilizes violet diodes for exposing photopolymer plates, balancing speed and cost for many print operations.
Thermal Imaging remains a performance benchmark. Inkjet Imaging is expanding most quickly due to its process-free advantages.
Printing Application:
Customer type significantly influences the CTP system features and plate characteristics required for various printing applications.
- Packaging:This application demands high-resolution CTP plates for intricate graphics on folding cartons, flexible packaging, and labels. Brands in China's Pearl River Delta drive demand for consistent color across product lines.
- Commercial Printing:This segment covers brochures, magazines, and marketing collateral, requiring CTP systems that deliver sharp text and vibrant images efficiently. European commercial printers require ISO 12647 compliance for output consistency.
- Publication:Publication printing, including newspapers and books, relies on CTP for rapid plate production and cost-effective, high-volume runs.
- Labels:Label production utilizes CTP for variable data, short runs, and high-quality graphics on diverse substrates for consumer goods.
- Security Printing:Security printing applications, such as banknotes and official documents, demand specialized CTP systems for anti-counterfeiting features and micro-text.
Packaging applications generate substantial revenue. Labels applications are gaining share fastest driven by customization trends.
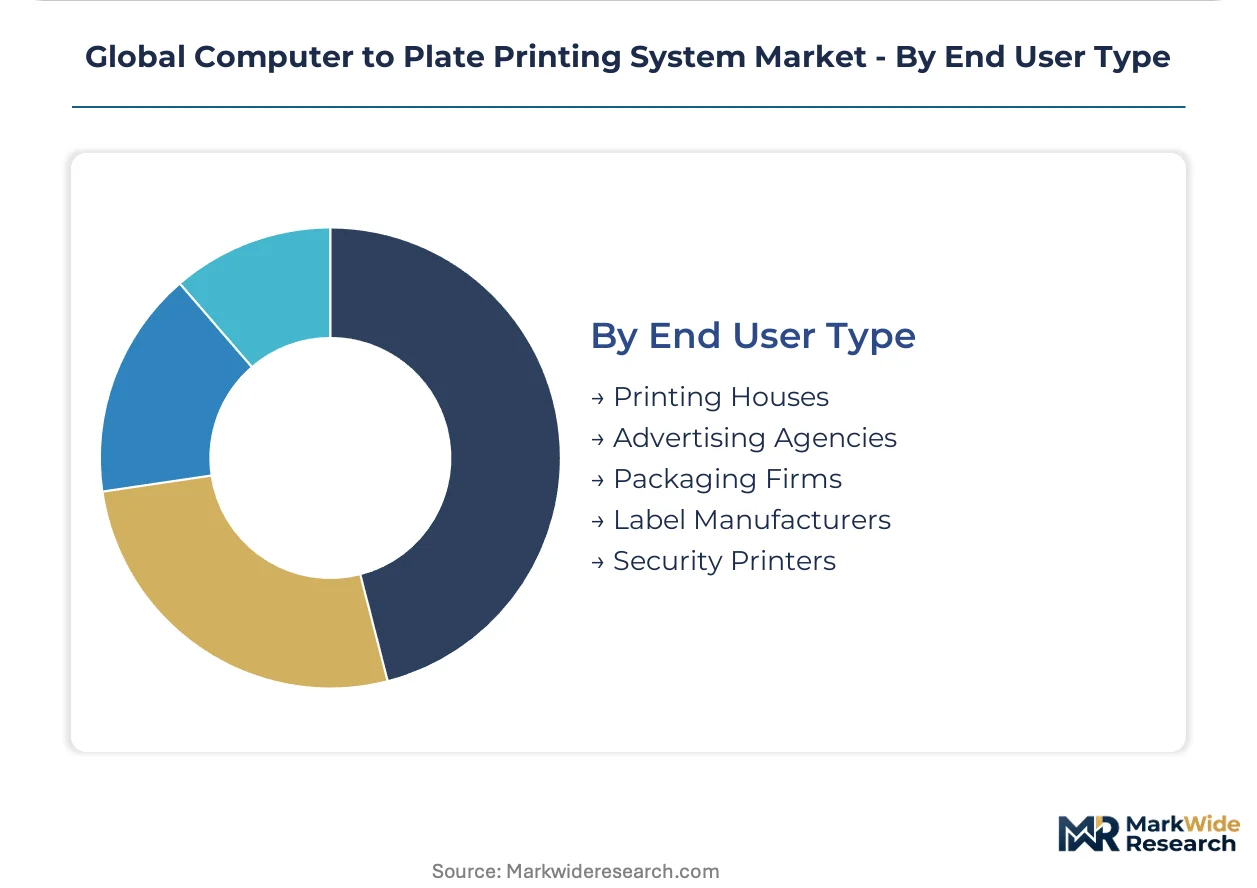
End User Type:
Volume requirements and operational scale largely determine the type and capacity of CTP systems adopted by various end-user types.
- Printing Houses:These entities are the largest adopters of CTP systems, utilizing them for a wide range of offset printing jobs from commercial to publication. Investment cycles are long, focusing on automation for efficiency in the US.
- Packaging Firms:Specialized in producing packaging materials, these firms leverage CTP for high-quality graphics on cartons, flexible packaging, and rigid containers. Demand from consumer brands in Southeast Asia is a key driver.
- Advertising Agencies:Advertising agencies often outsource printing but influence CTP technology choices through their demanding creative specifications and client requirements.
- Label Manufacturers:Label manufacturers depend on CTP for rapid plate changes, short runs, and precise color registration on various label substrates.
- Security Printers:Security printers require highly specialized CTP systems to create plates with intricate designs and overt/covert security features.
Printing Houses represent the largest installed base. Packaging Firms show the steepest expansion trajectory for CTP adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy initiatives across various nations influence CTP system adoption. Environmental regulations and industrialization programs drive demand for advanced printing technologies. These frameworks encourage investment in sustainable and efficient platemaking solutions.
United States
Demand for high-volume commercial printing and packaging applications drives CTP system installations. The US EPA's rules on volatile organic compounds incentivize printers to adopt process-free plates. Major printing houses in cities like Chicago and New York prioritize thermal imaging for consistent output quality.
Germany
Sophisticated offset applications in commercial and packaging sectors require high-resolution CTP systems. Europe's REACH regulation compels manufacturers to develop chemistry-free plate technologies. Industrial clusters in North Rhine-Westphalia and Bavaria focus on precision engineering for demanding print jobs.
China
The extensive manufacturing and export of consumer goods fuel demand for efficient CTP systems. China's MEE directives on industrial waste push for low-chemistry and process-free plate solutions. The Pearl River Delta region concentrates high-volume production of labels and flexible packaging.
Japan
Japanese commercial printers require precise CTP systems for high-quality output in publication and commercial segments. METI initiatives support advanced manufacturing and environmental technologies in the printing sector. Printing firms in Tokyo and Osaka invest in thermal platesetters for precise dot reproduction.
Vietnam
Rapid industrialization and manufacturing growth drive CTP adoption for packaging and labels. Government incentives for foreign direct investment attract printing and packaging firms. Ho Chi Minh City and Hanoi are emerging as hubs for modern CTP installations supporting export-oriented production.
Global Computer to Plate Printing System Market Key Industry Players
Player mix skews toward established technology providers and specialized equipment manufacturers. The market shows a tiered structure, with a few large integrated solution providers alongside numerous niche players. Strategic archetypes include full-suite pressroom integrators, thermal platesetter specialists, and process-free plate innovators. Dominant competitive moves involve strategic partnerships for workflow integration and continuous R&D into sustainable plate technologies.
Among the prominent entities, Heidelberger Druckmaschinen AG exemplifies a full-suite pressroom integrator, leveraging its broad portfolio for bundled CTP solutions. Screen Holdings Co., Ltd. represents a thermal platesetter specialist, focusing on high-resolution output for commercial applications. Eastman Kodak Company anchors the process-free plate innovation segment with its SONORA technology. These companies collectively illustrate the diverse approaches to CTP system development and market engagement.
| Leading Market Players |
|---|
| Screen Holdings Co., Ltd. |
| Esko |
| Eastman Kodak Company |
| Konica Minolta, Inc. |
| Xeikon International |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert Group |
| DuPont de Nemours, Inc. |
| Heidelberger Druckmaschinen AG |
| Others |
Cost & Logistics Intelligence
High-volume CTP system utilization in China's Pearl River Delta establishes significant scale economies, which in turn shape both supply concentration and underlying price floors for plates and equipment.
Pricing Analysis
ISO 12647 certification level creates the primary spread in CTP system and plate pricing. The dominant pricing model for large printing houses involves contract-based long-term offtake agreements, while smaller operations often use per-unit transactional pricing. Price differentiation stems from the level of after-sales service bundling offered by integrated solution providers like Heidelberger Druckmaschinen AG. Pricing softness in certain segments reflects the increasing substitution by digital presses for short-run jobs. Small and medium-sized printing businesses exhibit the highest price sensitivity, whereas pharmaceutical and luxury goods brands prioritize consistent quality over cost.
Supply Chain Analysis
Germany and Japan anchor the production of advanced thermal platesetters, while the United States contributes significantly to process-free plate innovation. The supply chain draws from global sources for high-grade aluminum, specialized plate coatings, and precision laser diodes. Commodity price volatility for aluminum represents a significant structural risk, impacting plate manufacturers and end-users. Distribution primarily runs through direct sales channels from equipment manufacturers to large printing houses, supplemented by specialized distributors serving smaller market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Computer to Plate Printing System market is at a platform-economics inflection, driven by the integration of CTP systems with AI-powered pre-press and automated quality controls across the print workflow ecosystem.
For Market Incumbents: Shield core market share by continuously investing in process-free plate technology, exemplified by Eastman Kodak Company's SONORA. Consolidate market position through strategic bundling of CTP systems with broader pressroom solutions, a strength of Heidelberger Druckmaschinen AG. This approach counters the threat of digital press substitution and regulatory shifts by leveraging R&D into sustainable plate technologies and ISO 12647 certification.
For New Entrants and Emerging Players: Specialized expertise for integrating new CTP devices with legacy printing presses represents a service-layer gap where incumbents under-serve. Target emerging markets such as Vietnam for modern CTP installations, focusing on packaging and labels. Pursue industrial printing applications like decorative surface imaging as a white-space opportunity. A viable go-to-market angle involves offering comprehensive service contracts that include integration support and operator training.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers of chemistry-free plate technology and integrated automation software solutions. The long-term viability of this market depends on sustainability mandates and the unwavering demand for consistent quality in packaging. An ideal acquisition target archetype includes mid-sized innovators specializing in inkjet CTP or advanced plate coatings. The signal to watch for inflection is the accelerated adoption rate of chemistry-free plates within regulated European and Chinese markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: New Process-Free CTP Plates | Introduces environmentally compliant solutions, reducing chemical waste and operational costs for printers. |
| Platform Integration: CTP Systems with AI-Powered Pre-Press | Enhances workflow automation and accuracy, addressing the scarcity of skilled pre-press technicians. |
| Geographic Expansion: Penetration into Southeast Asian Markets | Captures demand from rapid industrialization and export-oriented manufacturing in countries like Vietnam. |
| Strategic Partnership: With Packaging Firms for Customized Solutions | Aligns CTP capabilities with the growing demand for high-resolution graphics on folding cartons and flexible packaging. |
| Green Manufacturing Transition: Investment in Chemistry-Free Plate Production | Mitigates regulatory risks from Europe's REACH and China's MEE directives on chemical usage. |
Research Approach
Operator-level perspectives from pre-press operators, printing house owners, packaging converters, CTP equipment engineers, and plate material suppliers anchored the qualitative base for this analysis. This primary fieldwork was validated against secondary data sources, including industry association reports, patent databases, corporate financial filings, and regulatory body publications from EPA, REACH, and MEE. The methodology employed a combination of bottom-up and top-down triangulation to ensure data robustness.
Sensitivity analysis framed the quantitative assessment, modeling market dynamics across the analysis window. The analytical framework segmented the market by product type, technology, printing application, end-user type, and geographic region. Compound annual growth rates were derived through a rigorous statistical approach, incorporating industry-specific forecast inputs such as aluminum price trends and regulatory enforcement intensity. Digital press adoption rates also informed the model's projections.
Material uncertainties — including geopolitical trade tensions, raw material supply disruptions, and unexpected regulatory shifts — sit outside the modeled envelope, reflecting inherent market complexities. Forecasts reflect assumptions documented through extensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Digital Paper System Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Commercial Printer Market
Printing Technology
Large Format Printer Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Digital Presses Market
Printing Technology
US Print on Demand Market
Printing Technology
Digital Production Printer Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Barcode Printers and Consumables Market