
 Roll to Roll Printing Market | 2026-2036
Roll to Roll Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Roll to Roll Printing Market Analysis
Software-defined color management and predictive maintenance subscriptions is broadening what equipment vendors monetize beyond hardware sales. HP Inc. leverages its cloud-connected print analytics to lock in recurring revenue from commercial label converters. Mimaki Engineering anchors its competitive stance through deep specialization in UV-curable inkjet systems for industrial textile applications. Durst Phototechnik differentiates by controlling the full imaging chain from RIP software to single-pass printheads, reducing downstream integration costs for packaging printers.
Roll to roll printing is a continuous web-fed manufacturing process where flexible substrates—typically polyester film, coated paper, or woven fabric—move through sequential deposition, patterning, and curing stations at speeds exceeding 100 meters per minute, enabling mass production of functional layers for packaging graphics, electronic circuits, and decorative surfaces. Inkjet technology leads in short-run customization and variable-data applications where digital front-ends eliminate plate costs, while flexography dominates high-volume flexible packaging where anilox roller metering delivers consistent ink transfer at economies of scale. Electronics applications represent the fastest-growing segment as conductive nanoparticle inks enable roll-to-roll fabrication of flexible printed circuit boards and thin-film transistor backplanes.
FDA regulations on indirect food contact materials govern substrate and ink formulations for packaging applications in the United States, while REACH compliance in Europe restricts certain phthalate plasticizers and heavy metal pigments used in vinyl printing. The EU F-Gas Regulation is additionally accelerating solvent recovery system investments among gravure and flexographic converters operating across Germany and Italy. Stakeholders must weigh capital allocation between digital inkjet retrofitting and legacy press modernization as energy efficiency standards tighten and brand owners demand batch-level traceability.
Market Dynamics
The EU Green Deal's binding targets for sustainable packaging materials are redirecting capital toward water-based ink systems and recyclable substrates, compressing technology refresh cycles across the installed base of gravure and flexographic presses.
Growth Catalysts
- Flexible Electronics Manufacturing:Samsung Display and LG Display operate large-area OLED manufacturing clusters in South Korea using roll-to-roll vapor deposition methods. Printed sensor and photovoltaic film production is scaling web-fed processes for functional layer deposition.
- EU Green Deal Packaging Mandates:Binding sustainability targets are redirecting capital toward water-based ink systems and recyclable substrates. Brand owners are retrofitting legacy presses to meet circular economy compliance timelines.
- Digital Inkjet Variable Data:Short-run customization demands from pharmaceutical and food label converters are eliminating plate costs through digital front-ends. Web-fed inkjet systems enable batch-level traceability without press changeover downtime.
Market Restraints
- Specialized Equipment Capex Concentration:Single-pass printhead arrays and precision web-handling systems require concentrated capital deployment. Regional equipment vendors dominate aftermarket service revenue streams.
- Raw Material Input Volatility:Conductive nanoparticle inks depend on silver and copper commodity markets. Electrode material cost swings compress margin structures for flexible printed circuit board producers.
- REACH Chemical Restrictions:ECHA regulations on phthalate plasticizers and heavy metal pigments constrain formulation flexibility. Vinyl printing applications face reformulation costs and supply qualification delays.
Strategic Opportunities
- India Packaging Print Expansion:FSSAI food contact regulations are formalizing substrate safety standards. Domestic flexible packaging converters are investing in gravure modernization to serve multinational brand owner specifications.
- Photovoltaic Film Integration:Roll-to-roll perovskite and organic photovoltaic deposition is converging with barrier film lamination. Equipment vendors can extend into turnkey thin-film solar manufacturing lines.
- EU F-Gas Regulation Compliance Services:Solvent recovery system investments are accelerating among German and Italian converters. Engineering services for emissions compliance represent recurring revenue beyond hardware sales.
Industry Challenges
- Mechatronics Skill Scarcity:Precision web tension control and register adjustment require specialized technician training. Equipment vendors face extended commissioning timelines due to qualified field service engineer shortages.
- FDA Indirect Food Contact Certification:Substrate and ink formulation approvals for US packaging applications involve 18-24 month validation cycles. Reformulation to eliminate mineral oil saturated hydrocarbons requires complete supply chain requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll to Roll Printing Market |
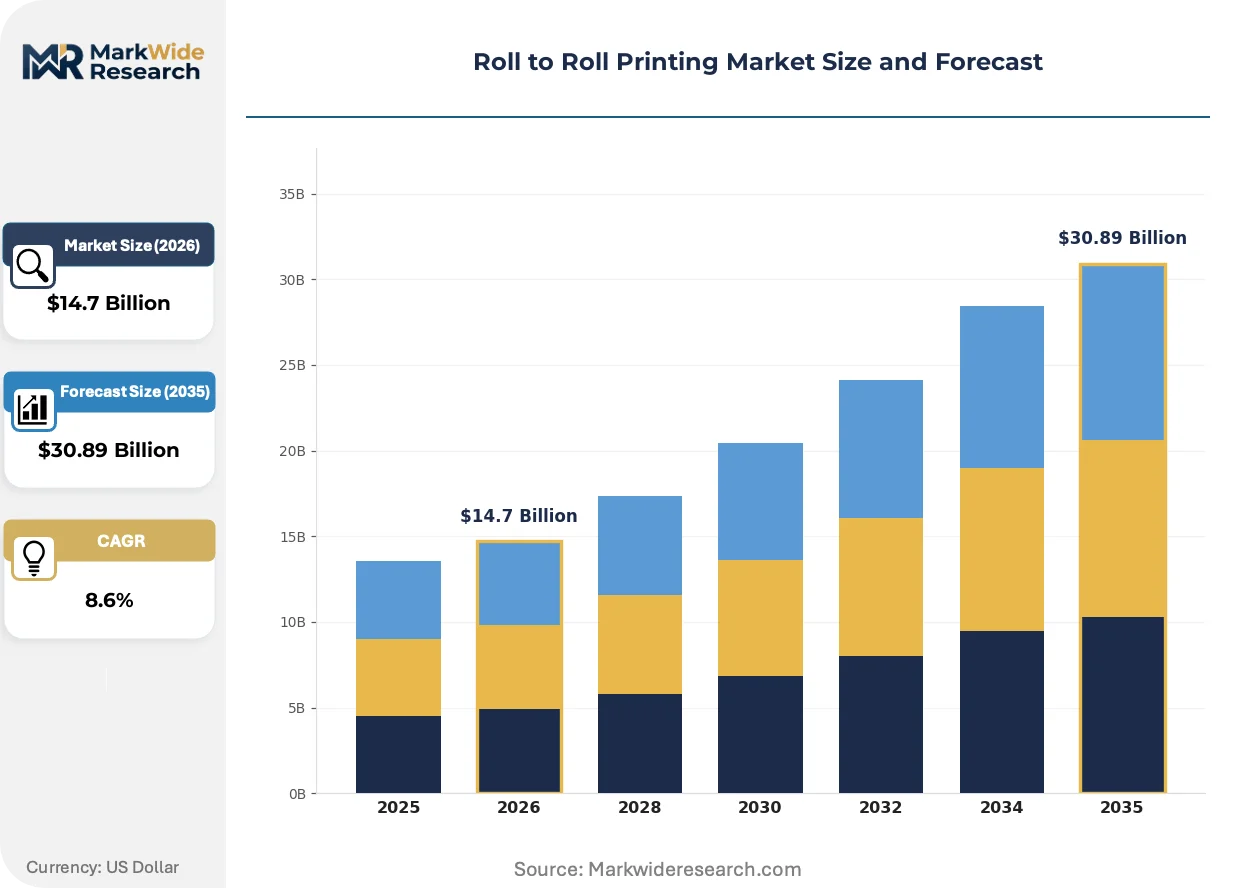
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Flexography, Gravure, Inkjet, Screen Printing Application: Packaging, Labels, Textiles, Electronics End User: Consumer Goods, Automotive, Healthcare, Retail Material: Film, Paper, Vinyl, Fabric |
| Companies Covered | HP Inc., Epson America, Canon Solutions America, Mimaki Engineering, Roland DG Corporation, Durst Phototechnik, Kornit Digital, Agfa-Gevaert Group, Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll to Roll Printing Market Emerging Trajectories
Software-defined color management and predictive maintenance subscriptions are broadening equipment vendor monetization beyond hardware sales, locking in recurring revenue from commercial label converters and packaging printers.
Single-pass inkjet array technology is consolidating competitive positioning among packaging equipment vendors. High-speed piezoelectric printhead architectures now match flexographic throughput for medium-run folding carton work. Folding carton converters in North America and Europe are adopting these systems to eliminate plate inventory and reduce job changeover intervals from hours to minutes.
REACH chemical restrictions and the EU F-Gas Regulation are forcing solvent recovery system investments across German and Italian gravure converters. The industrial consequence is accelerated consolidation among smaller printing houses unable to fund emissions compliance infrastructure. Flexible packaging segments serving snack food and confectionery brands are most affected, with converters pooling capital through regional equipment cooperatives.
Brand owner procurement teams are unbundling after-sales service contracts from initial equipment purchases. Converters now source predictive maintenance analytics and spare parts through third-party channels rather than captive vendor programs. This behavioral shift is most visible in North American label markets, where HP Inc. cloud-connected print analytics face independent software vendor competition for recurring revenue streams.
Roll to Roll Printing Market Segmentation
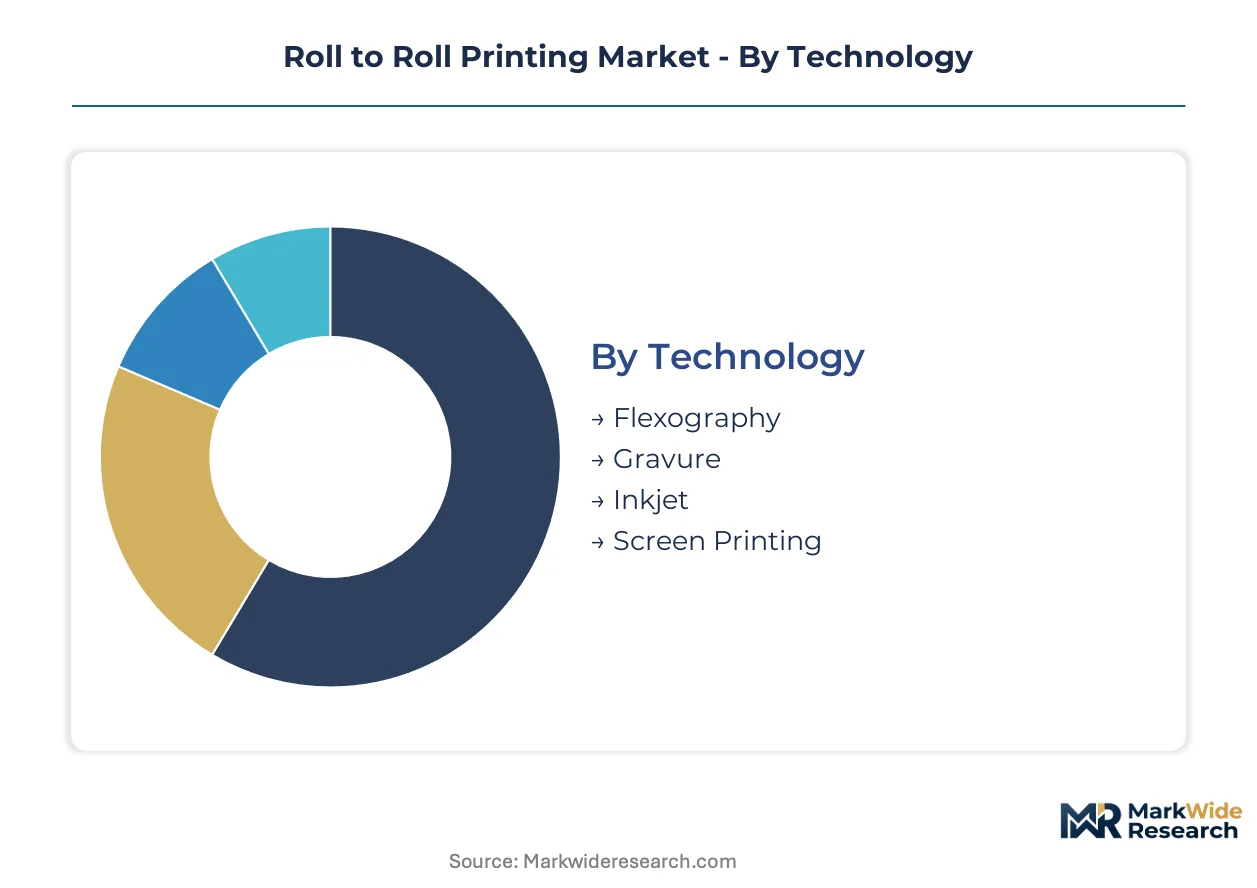
Roll to roll printing technology selection determines capital intensity, run economics, and regulatory compliance pathways. Substrate-material pairings and end-use specifications create distinct equipment configuration clusters that vendors target with specialized ink systems and web-handling architectures.
Technology:
Print mechanism selection governs speed, resolution, and job-changeover flexibility across converter operations.
- Inkjet:Piezoelectric drop-on-demand systems deposit UV-curable or aqueous inks without plate costs. Pharmaceutical label converters in Germany leverage digital front-ends for batch-level traceability mandated by the EU Falsified Medicines Directive.
- Flexography:Anilox roller metering delivers consistent ink transfer at web speeds exceeding 300 meters per minute. Snack food packaging converters in the United States deploy central impression drum presses to serve Walmart and Target volume specifications.
- Gravure:Engraved cylinder cells achieve high-density pigment deposition for decorative laminate applications. Italian converters serving luxury cosmetics brands maintain cylinder inventory for long-run fragrance packaging work.
- Screen Printing:Squeegee-driven stencil systems deposit thick-film conductive pastes for flexible circuit applications. South Korean electronics manufacturers integrate rotary screen modules into OLED electrode production lines.
Mature deployment sits with flexography. Newer deployment is concentrated in inkjet.
Application:
End-use functional requirements split equipment investments between commodity graphics and precision functional layer deposition.
- Electronics:Roll-to-roll vapor deposition and printed silver nanoparticle patterning enable flexible printed circuit boards and thin-film transistor backplanes. Samsung Display and LG Display manufacturing clusters in South Korea anchor demand for precision web-handling systems.
- Packaging:Barrier film lamination and high-definition graphics serve food, beverage, and personal care brand owners. German converters retrofit gravure lines with solvent recovery systems to meet EU F-Gas Regulation compliance timelines.
- Labels:Pressure-sensitive adhesive substrates and variable-data printing support pharmaceutical serialization and logistics tracking. FDA 21 CFR Part 11 requirements drive validation protocols for US-based contract converters.
- Textiles:Pigment inkjet and reactive dye systems print directly onto woven polyester and cotton webs. Italian and Turkish converters serve fast-fashion brand owner demands for shortened design-to-delivery cycles.
Electronics applications are climbing the fastest as conductive ink formulations mature.
End User:
Procurement specifications from multinational brand owners dictate substrate safety certifications and print durability standards.
- Consumer Goods:Unilever and Procter & Gamble packaging specifications require mineral oil saturated hydrocarbon elimination from recycled paperboard substrates. Converters face 18-24 month supply chain requalification cycles.
- Healthcare:FDA indirect food contact and EU 10/2011 plastic regulations govern blister pack and medical device pouch printing. Serialization mandates for pharmaceutical labels demand vision-inspected inkjet systems.
- Automotive:Interior trim films and capacitive touch sensor overlays require abrasion-resistant UV coatings. German tier-one suppliers specify gravure-printed polycarbonate decorative layers for instrument cluster applications.
- Retail:Point-of-sale display graphics and loyalty card production favor short-run digital inkjet economics. Variable data integration with CRM systems drives demand for cloud-connected print analytics.
Healthcare procurement is the most specification-intensive. Retail volumes are the most price-sensitive.
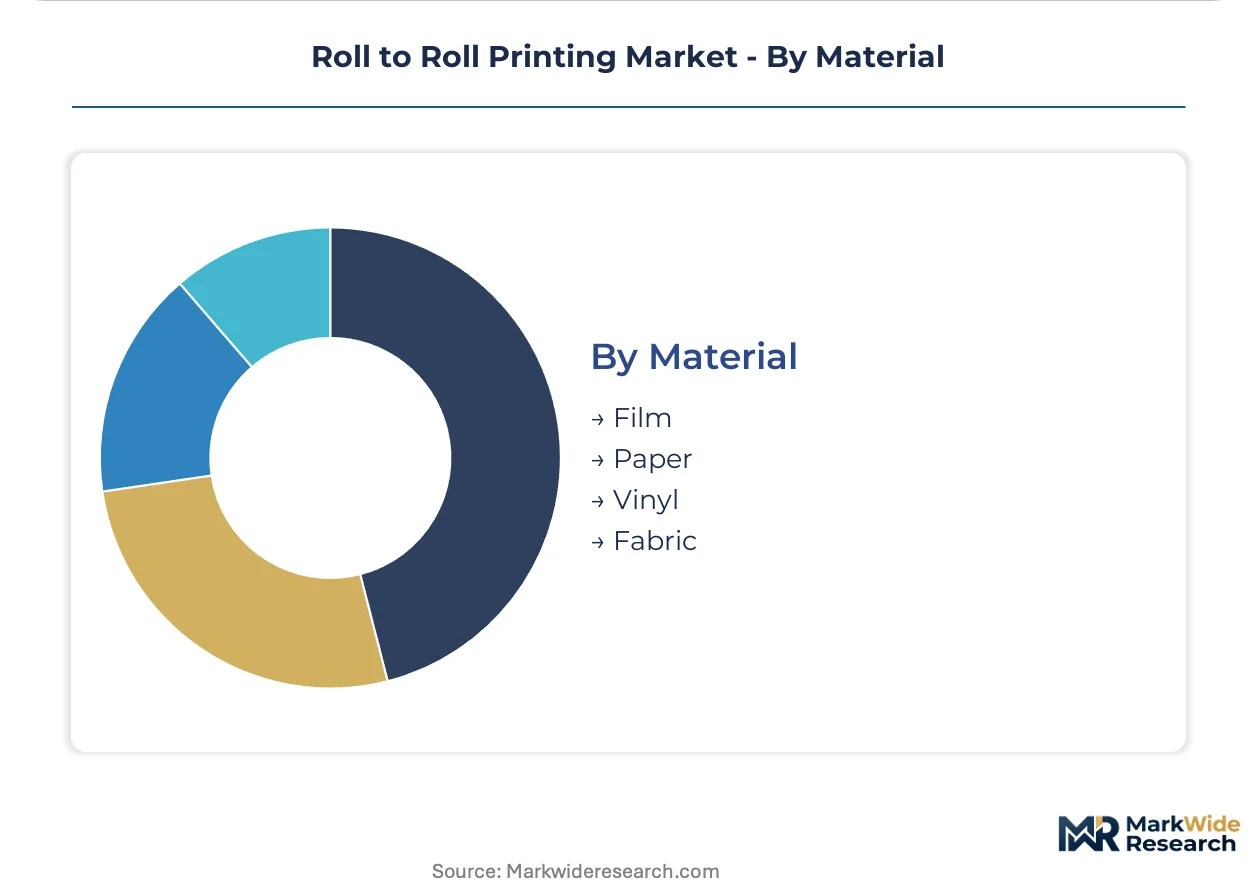
Material:
Substrate surface energy and thermal stability determine ink adhesion, drying energy, and downstream converting compatibility.
- Film:Biaxially oriented polypropylene and polyethylene terephthalate webs dominate snack food flexible packaging. South Korean and Japanese resin suppliers qualify optical-grade films for display component manufacturing.
- Paper:Clay-coated and uncoated kraft stocks serve folding carton and corrugated pre-print applications. EU Green Deal circular economy targets accelerate migration toward recyclable mono-material paper structures.
- Vinyl:Calendered and cast polyvinyl chloride films support outdoor signage and vehicle wrap graphics. ECHA REACH restrictions on phthalate plasticizers force reformulation toward non-phthalate alternatives.
- Fabric:Woven polyester and cotton textiles receive pigment and reactive dye inkjet printing for apparel and home furnishing applications. Italian converters specialize in silk and wool substrates for luxury brand owner collections.
Film substrates command premium pricing. Paper volumes are expanding fastest under sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suwon and Paju host the densest concentration of roll-to-roll OLED manufacturing capacity worldwide. Samsung Display and LG Display operate adjacent vapor deposition clusters that anchor precision web-handling equipment demand across South Korea.
South Korea
Flexible display manufacturing consumes the majority of high-precision roll-to-roll vapor deposition systems. MFDS pharmaceutical serialization mandates accelerate variable-data inkjet adoption for domestic label converters. The Gyeonggi-do corridor surrounding Seoul concentrates equipment vendor technical service operations.
Germany
Gravure converters serving luxury cosmetics packaging drive solvent recovery system retrofits. EU F-Gas Regulation compliance deadlines force capital allocation toward emissions control infrastructure by 2027. The Baden-Württemberg industrial belt hosts specialized anilox roller manufacturers and press automation integrators.
United States
Food label converters face FDA 21 CFR Part 11 validation requirements for pharmaceutical serialization contracts. Folding carton producers in the Midwest adopt single-pass inkjet arrays to serve Walmart and Target volume specifications. Chicago and Milwaukee anchor domestic gravure cylinder engraving and press rebuild services.
Italy
Luxury fragrance and cosmetics packaging converters maintain engraved cylinder inventories for long-run decorative laminate work. ECHA REACH restrictions on phthalate plasticizers force vinyl printing reformulation toward non-phthalate alternatives. The Lombardy region around Milan concentrates high-end flexible packaging design and pre-press services.
India
Domestic flexible packaging converters invest in gravure modernization to serve multinational brand owner specifications. FSSAI food contact regulations formalize substrate safety standards for snack food and confectionery applications. The Gujarat industrial corridor between Ahmedabad and Vadodara attracts imported press installations serving pan-Indian distribution networks.
Roll to Roll Printing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors. Equipment vendors with captive printhead manufacturing and precision mechatronics capabilities hold structural advantages in single-pass array architectures. Three archetypes dominate: diversified imaging conglomerates with software-defined service layers, specialized inkjet system fabricators with deep UV-curable formulations expertise, and precision web-handling specialists serving electronics deposition applications. Competitive moves concentrate on predictive maintenance subscription bundling and solvent recovery system integration partnerships.
Within the diversified imaging tier, HP Inc. and Xerox Corporation anchor positions through cloud-connected print analytics platforms. Mimaki Engineering and Durst Phototechnik exemplify specialized inkjet fabricators with differentiated control over imaging chain components. Roland DG Corporation occupies a position bridging commercial signage and industrial textile applications. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| HP Inc. |
| Epson America |
| Canon Solutions America |
| Mimaki Engineering |
| Roland DG Corporation |
| Durst Phototechnik |
| Kornit Digital |
| Agfa-Gevaert Group |
| Xerox Corporation |
| Others |
Supply Flow & Price Mechanics
Brand owner mandates for mineral oil saturated hydrocarbon elimination in recycled paperboard substrates force converters into 18-24 month supply chain requalification cycles, compressing margin structures and redirecting procurement toward certified mono-material suppliers with pricing power.
Pricing Analysis
Margin tightening in mid-tier equipment reflects overcapacity in legacy gravure and flexographic press installations. Three-tier pricing structure across premium single-pass inkjet arrays, standard central impression drum flexography, and economy retrofit kits differentiates on throughput speed and predictive maintenance bundling. Price differentiation hinges on EU F-Gas Regulation compliance certification and FDA indirect food contact validation status. Cost-down pressure on standard-tier systems accelerates because regional equipment cooperatives pool capital for shared solvent recovery infrastructure. Retail-facing label converters exhibit highest price sensitivity; OLED manufacturing clusters in South Korea show lowest sensitivity due to yield-critical precision requirements.
Supply Chain Analysis
Freight cost volatility for precision mechatronics components from Japan and Germany elevates total landed cost for web-handling systems. Manufacturing concentration centers on South Korea for vapor deposition chambers, Germany for anilox rollers and press automation, and Italy for gravure cylinder engraving. Silver and copper nanoparticle inks draw from commodity metals markets with pronounced electrode material cost swings. Single-source vulnerability sits with piezoelectric printhead arrays from specialized Japanese suppliers. Distribution runs through captive vendor technical service networks rather than third-party channels, locking converters into aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around equipment vendors with integrated printhead manufacturing and predictive maintenance platforms, as REACH chemical restrictions and emissions compliance timelines force smaller printing houses toward acquisition or exit.
For Market Incumbents: Deploy predictive maintenance subscription bundling to capture recurring revenue from commercial label converters facing FDA 21 CFR Part 11 validation requirements. Acquire solvent recovery system integrators in Germany and Italy to anchor EU F-Gas Regulation compliance service revenue. Deepen captive supply of piezoelectric printhead architectures to defend against independent software vendors competing for cloud-connected print analytics contracts.
For New Entrants and Emerging Players: Launch via equipment cooperative partnerships serving Indian flexible packaging converters modernizing gravure lines for FSSAI food contact compliance. Target photovoltaic film deposition equipment for perovskite and organic solar manufacturing, where barrier film lamination convergence creates turnkey line opportunities. Penetrate through software-defined color management modules that unbundle from incumbent hardware-locked ecosystems.
For Investors and Strategic Acquirers: Re-rating potential sits with precision web-handling specialists serving electronics deposition applications given Samsung Display and LG Display capacity expansion in South Korea. Long-term viability favors vendors controlling full imaging chain from RIP software to single-pass printheads. Monitor MFDS pharmaceutical serialization mandate enforcement as inflection indicator for variable-data inkjet demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Bundling | HP Inc. cloud-connected print analytics lock in recurring revenue from commercial label converters. |
| Solvent Recovery System Integration | German and Italian gravure converters meet EU F-Gas Regulation compliance deadlines through retrofit partnerships. |
| Single-Pass Inkjet Array Development | Piezoelectric printhead architectures match flexographic throughput for medium-run folding carton work. |
| Conductive Nanoparticle Ink Formulation | Printed silver and copper pastes enable roll-to-roll fabrication of flexible printed circuit boards. |
| Precision Web-Handling System Specialization | South Korean OLED manufacturing clusters anchor demand for vapor deposition equipment vendors. |
Methodological Framework
Independent corroboration across equipment vendor technical documentation, EU regulatory filings, and pharmaceutical converter validation protocols underwrites the qualitative findings. Primary interviews with press automation integrators, gravure cylinder manufacturers, flexible packaging procurement leads, and OLED manufacturing operations directors combined with secondary validation from SEC equipment supplier filings, ECHA REACH restriction updates, and FDA 21 CFR Part 11 guidance documents. Bottom-up installed base analysis and top-down capital expenditure tracking triangulate market sizing.
Comparable-period anchoring to historical equipment shipment data and retrofit investment cycles frames the projection horizon. Segmentation dimensions span print mechanism technology, end-use application, substrate material pairing, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and brand owner specification change velocity. Forecast inputs incorporate EU Green Deal packaging mandate timelines and conductive ink formulation maturity curves.
Commodity metals price volatility, REACH chemical restriction scope expansion, and mechatronics technician scarcity are the dominant revision risks. Forecasts reflect documented assumptions on technology refresh cycle acceleration and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Printing Machinery Market
Printing Technology
Cloud Print Market
Printing Technology
Photo Printing Market
Printing Technology
Digital Paper System Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
RFID Printer Market
Printing Technology
North America Commercial Printing Market
Printing Technology
ID Card Printers Market
Printing Technology
Card Printers Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Industrial Printer Market
Printing Technology
Print on Demand Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Digital Presses Market