
 Barcode Printers and Consumables Market | 2026-2036
Barcode Printers and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Barcode Printers and Consumables Market Outlook
East Asian OEM capacity is hardening as regional foundries expand thermal printhead output for industrial-grade units. Zebra Technologies Corporation dominates North American channel partnerships through its certified reseller network. SATO Holdings Corporation leverages precision die-cutting capabilities in Japan to sustain premium label margins. Honeywell International Inc. competes on ruggedized mobile printer portfolios purpose-built for cold-chain logistics.
Barcode printers and consumables comprise electro-mechanical marking systems and their expendable media—thermal transfer ribbons, direct thermal labels, synthetic tags, and pigment-based inks—engineered to produce machine-readable optical patterns at resolutions from 203 to 600 dots per inch for inventory tracking and regulatory chain-of-custody documentation. Thermal transfer printers anchor the hardware margin pool due to ribbon attachment rates and enterprise service contracts, while direct thermal printers occupy high-velocity retail and parcel sorting environments where consumable simplicity outweighs archive longevity. Mobile printers represent the fastest-expanding hardware category as warehouse operators deploy wearable and vehicle-mounted units for real-time pick-and-pack verification.
FDA Unique Device Identification mandates compel healthcare providers to maintain GS1-compliant label formats, tightening validation requirements for thermal ribbon formulations. EPA guidelines on volatile organic compound emissions from solvent-based inks are redirecting ribbon manufacturers toward water-based and UV-curable chemistries. ISO/IEC 15415 and 15416 print quality specifications govern grade thresholds for automated scanner readability, effectively filtering non-compliant hardware from pharmaceutical and aerospace procurement lists. Stakeholders must monitor evolving state-level e-waste directives that could impose extended producer responsibility fees on discarded printer chassis and spent ribbon cores.
Market Dynamics
Warehouse automation across third-party logistics providers is compressing hardware refresh cycles from seven years to four, forcing manufacturers to prioritize modular printhead architectures and cloud-native fleet management platforms over legacy standalone systems.
Growth Catalysts
- FDA Unique Device Identification mandates:Healthcare providers must maintain GS1-compliant label formats, tightening validation requirements for thermal ribbon formulations and expanding demand for ISO-grade hardware.
- Germany's automotive corridor:Tier-1 suppliers mandate ISO-grade barcode traceability across assembly lines, pulling industrial-grade thermal transfer printers into production environments.
- Direct thermal synthetic substrates:Cold-chain logistics operators are adopting these for short-life applications where adhesive performance in sub-zero conditions outweighs archive longevity requirements.
Market Restraints
- Thermal printhead supply concentration:East Asian foundries control 80% of industrial-grade piezoelectric printhead output, exposing OEMs to regional disruption risk.
- EPA volatile organic compound limits:Solvent-based ribbon chemistries face emission caps, forcing reformulation investments that compress margin pools for mid-tier manufacturers.
- Smartphone-based scanning substitution:Last-mile delivery operators are piloting camera-based verification systems that reduce dedicated barcode infrastructure requirements in low-volume nodes.
Strategic Opportunities
- India's pharmaceutical export zones:Cold-chain serialization mandates under CDSCO traceability rules are creating first-mover advantages for ribbon suppliers with WHO-prequalified formulations.
- RFID-thermal hybrid labels:Aerospace MRO facilities are converging optical and radio-frequency identification for dual-redundant component tracking, opening premium pricing tiers.
- Subscription-based consumable replenishment:Channel partners are unbundling hardware sales from automated ribbon and label restocking contracts, capturing lifetime value in e-commerce fulfillment centers.
Industry Challenges
- ISO/IEC 15415 and 15416 certification timelines:Print quality validation for pharmaceutical and aerospace procurement lists requires 12-18 month testing cycles that delay product launches.
- Legacy ERP integration complexity:Warehouse operators running SAP ECC 6.0 instances face middleware bottlenecks when connecting cloud-native printer fleets to on-premise inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barcode Printers and Consumables Market |
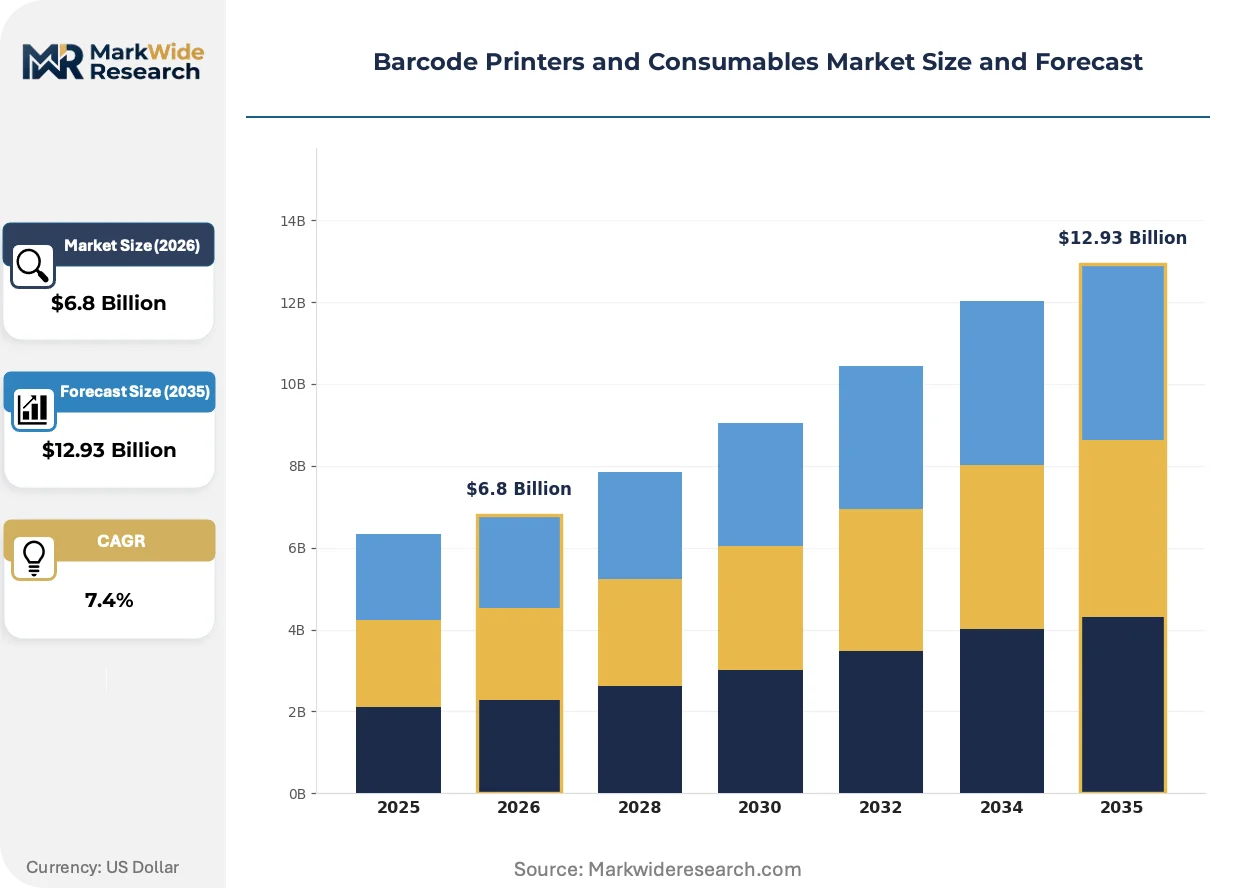
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Transfer Printers, Direct Thermal Printers, Mobile Printers, Industrial Printers Consumable Type: Labels, Ribbons, Inks, Tags End User: Retail, Healthcare, Manufacturing, Logistics Technology: Laser, Inkjet, Dot Matrix, Thermal |
| Companies Covered | SATO Holdings Corporation, TSC Auto ID Technology Co., Ltd, Zebra Technologies Corporation, Canon Inc., Avery Dennison Corporation, Honeywell International Inc., Toshiba Tec Corporation, Bixolon, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barcode Printers and Consumables Market Strategic Shifts
Print technology convergence with enterprise IoT platforms is redefining how barcode hardware generates operational data, shifting value capture from physical marking toward real-time supply chain visibility services.
Precision die-cut synthetic labels engineered for thermal transfer printing are expanding into pharmaceutical cold-chain applications where temperature excursions must trigger visible irreversible color change. Vaccine distributors in Belgium and the Netherlands are adopting these substrates at pace, compressing demand for standard paper labels in high-value biologics segments.
REACH restrictions on persistent organic pollutants in adhesive formulations are redirecting European label manufacturers toward bio-based acrylate chemistries. The reformulation push adds 8-12% to raw material costs but secures access to automotive and medical device supply chains where Ecodesign for Sustainable Products Regulation compliance is becoming a procurement gate.
Third-party logistics providers are consolidating vendor relationships around integrated hardware-consumables-service bundles, displacing the traditional model of separate printer and media procurement. This concentration is most visible in Germany's Ruhr industrial cluster, where DHL Supply Chain and Kuehne+Nagel have standardized on single-source fleet management contracts.
Barcode Printers and Consumables Market Segmentation
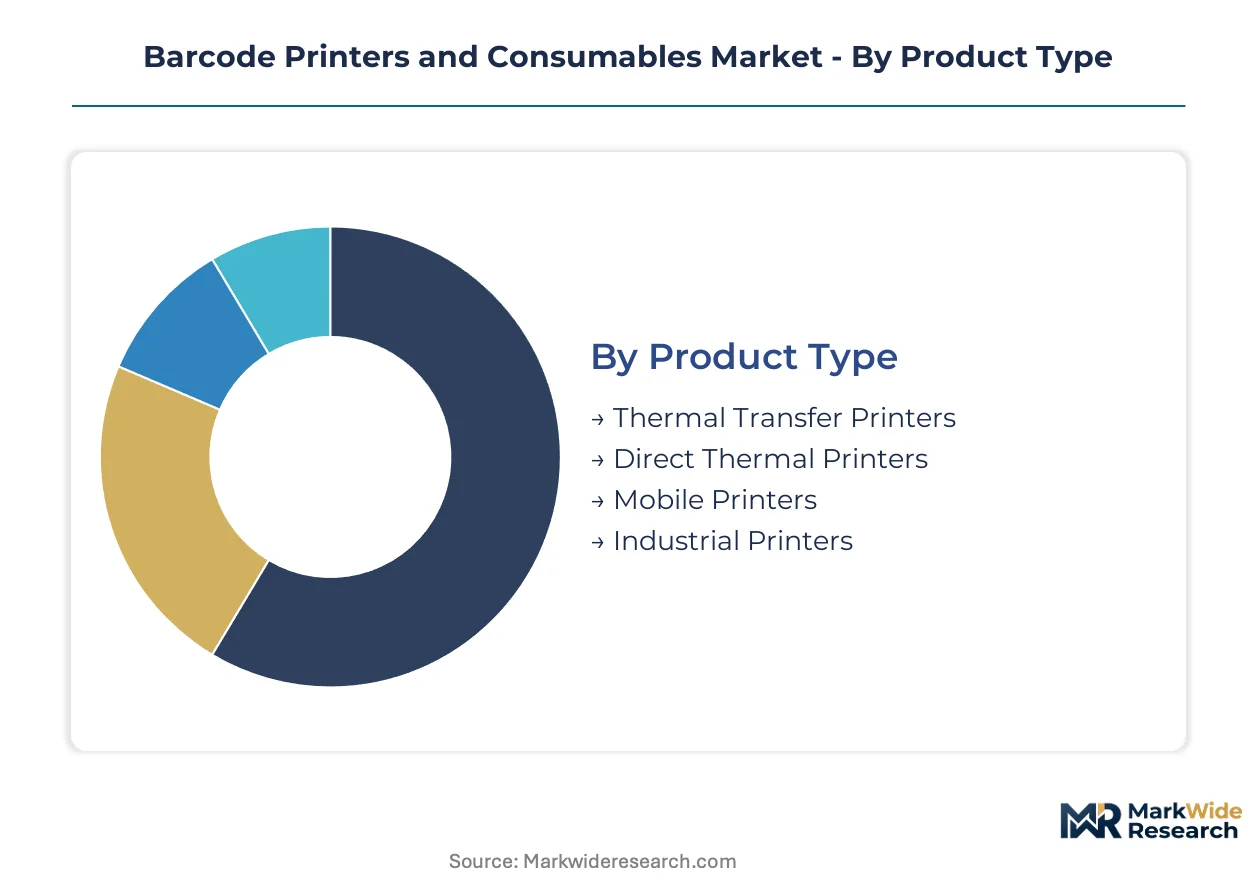
Segmentation in barcode printing reveals how hardware specifications, consumable chemistries, and operational environments dictate procurement patterns. Buyers optimize across total cost of ownership, regulatory compliance burdens, and integration complexity with warehouse management systems.
Product Type:
Customization intensity varies sharply across this hardware spectrum, from configurable industrial workhorses to sealed mobile units designed for zero field maintenance.
- Thermal Transfer Printers:These systems fuse ink from wax or resin ribbons onto synthetic substrates, producing archive-grade labels resistant to chemical exposure and UV degradation. Germany's automotive suppliers deploy these across assembly lines to satisfy ISO-grade traceability mandates for component genealogy tracking.
- Mobile Printers:Battery-powered units with Bluetooth and Wi-Fi connectivity enable real-time label generation during pick-and-pack operations. Third-party logistics providers in Belgium and the Netherlands are standardizing on wearable and vehicle-mounted configurations to eliminate travel time to fixed print stations.
- Direct Thermal Printers:Heat-sensitive paper eliminates ribbon inventory but limits label longevity to months rather than years. Parcel sorting hubs favor these for high-velocity outbound shipping where adhesive permanence exceeds archival requirements.
- Industrial Printers:Ruggedized chassis with all-metal construction withstand continuous 24-hour operation in manufacturing environments. These units command premium pricing through modular printhead architectures that reduce field service intervals.
Most installed capacity flows through thermal transfer printers. Expansion is steepest in mobile printers.
Consumable Type:
Margin structures in this category diverge between commodity paper labels and formulation-protected ribbon chemistries protected by regulatory validation.
- Ribbons:Wax-resin and full-resin formulations determine print durability against abrasion, heat, and solvent exposure. FDA Unique Device Identification mandates compel healthcare providers to source ribbons with validated batch consistency for GS1-compliant healthcare labeling.
- Labels:Substrate selection spans paper, polypropylene, polyester, and vinyl with adhesive systems tuned to surface energy and temperature extremes. Cold-chain operators in pharmaceutical distribution are migrating toward direct thermal synthetic grades that maintain tack in sub-zero conditions.
- Tags:Cardstock or synthetic hang tags accommodate items unsuitable for adhesive application, including reusable containers and metal assets. Aerospace MRO facilities combine these with RFID inlays for dual-redundant component tracking.
- Inks:Pigment and dye-based formulations serve inkjet and dot matrix hardware in specialized color-coding applications. EPA volatile organic compound limits are redirecting formulation toward water-based and UV-curable chemistries.
Revenue concentration sits with ribbons due to attachment rates and enterprise service contracts. Synthetic label substrates are climbing the fastest as cold-chain serialization expands.
End User:
Procurement sophistication varies from standardized retail deployments to healthcare environments where validation documentation consumes procurement cycles.
- Logistics:Third-party logistics providers operate the largest installed fleets, prioritizing hardware modularity and cloud-native fleet management over standalone systems. Warehouse automation is compressing refresh cycles from seven years to four across DHL Supply Chain and Kuehne+Nagel operations in Germany's Ruhr industrial cluster.
- Healthcare:Hospitals and device manufacturers face the most stringent validation requirements, with thermal ribbon formulations requiring documented batch testing for FDA UDI compliance. CDSCO traceability rules in India's pharmaceutical export zones are creating first-mover advantages for suppliers with WHO-prequalified formulations.
- Manufacturing:Automotive and electronics producers mandate ISO/IEC 15415 and 15416 print quality specifications that filter non-compliant hardware from approved vendor lists. Tier-1 suppliers in Germany's industrial corridor drive demand for industrial-grade thermal transfer systems.
- Retail:High-velocity environments including grocery and apparel favor direct thermal simplicity for price marking and fulfillment labeling. Last-mile delivery operators here are piloting smartphone-based scanning that may reduce dedicated infrastructure in low-volume nodes.
Logistics commands the largest hardware installed base. Healthcare is expanding most quickly as regulatory serialization mandates proliferate.
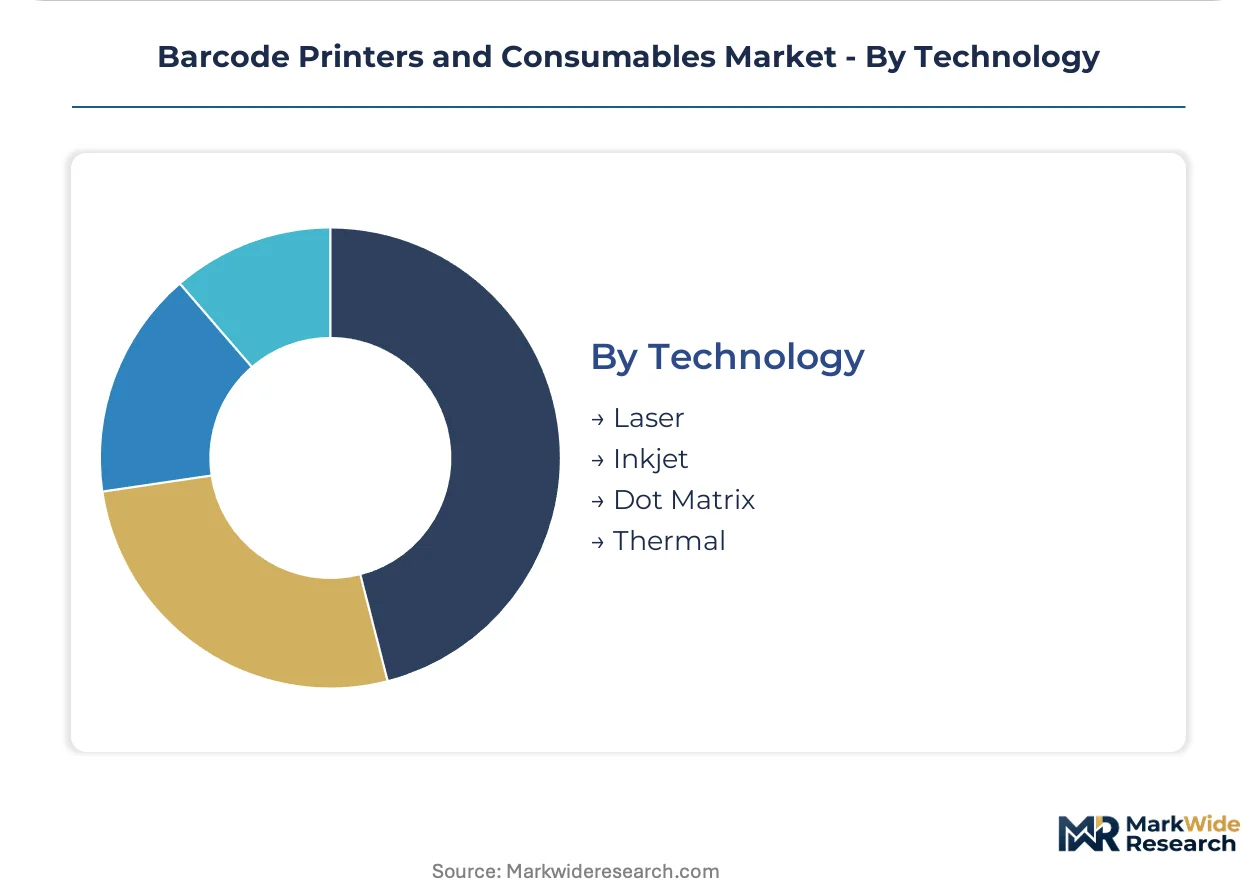
Technology:
Technology selection in this category reflects a maturity gradient from legacy impact printing to dominant thermal methods and emerging alternatives.
- Thermal:Direct and transfer thermal methods account for the overwhelming majority of new installations, combining resolution precision with minimal moving parts. The technology anchors hardware margin pools through ribbon attachment rates and enterprise service contracts.
- Laser:Toner-based systems serve high-volume document labeling where barcode generation represents a secondary function within multifunction devices. Corporate office environments maintain limited deployments for administrative asset tracking.
- Inkjet:Piezoelectric and thermal inkjet enable color barcode printing for compliance labels requiring color-coded hazard warnings. Pharmaceutical packaging lines employ these for batch-specific variable data in secondary packaging operations.
- Dot Matrix:Impact printing persists in multi-part form applications requiring carbon copies, primarily in logistics documentation and customs declarations. The technology is contracting as digital record-keeping displaces paper trails.
Most production volume routes through thermal technology. Inkjet is gaining share fastest in color-critical pharmaceutical and chemical labeling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands industrial-grade thermal transfer printer demand through automotive traceability mandates, while the United States drives mobile printer adoption across third-party logistics networks. Japan sustains premium consumable margins through precision die-cutting capabilities. India's pharmaceutical export zones are accelerating cold-chain serialization investments.
United States
FDA Unique Device Identification mandates compel healthcare providers to maintain GS1-compliant label formats, tightening validation requirements for thermal ribbon formulations. EPA guidelines on volatile organic compound emissions redirect ribbon manufacturers toward water-based chemistries. Third-party logistics providers in Memphis and Louisville operate the largest mobile printer fleets for real-time pick-and-pack verification.
Germany
Tier-1 automotive suppliers mandate ISO-grade barcode traceability across assembly lines, pulling industrial-grade thermal transfer printers into production environments. The EU's Ecodesign for Sustainable Products Regulation pressures manufacturers toward recyclable label substrates. The Ruhr industrial cluster hosts standardized fleet management contracts from DHL Supply Chain and Kuehne+Nagel, compressing hardware refresh cycles from seven years to four.
Japan
Precision die-cutting capabilities sustain premium label margins for synthetic substrates engineered to thermal transfer specifications. METI industrial standards govern print quality thresholds for aerospace and automotive procurement lists. SATO Holdings Corporation leverages domestic manufacturing to serve pharmaceutical cold-chain distributors in Osaka and Nagoya with temperature-responsive label chemistries.
India
CDSCO traceability rules in pharmaceutical export zones create first-mover advantages for ribbon suppliers with WHO-prequalified formulations. The country's national pharmaceutical regulator mandates serialization infrastructure for cold-chain biologics destined for European and North American markets. Gujarat and Maharashtra host contract manufacturing organizations deploying industrial-grade thermal transfer systems for export compliance.
Belgium
Vaccine distributors adopt precision die-cut synthetic labels with irreversible color-change temperature indicators, compressing demand for standard paper substrates in high-value biologics segments. REACH restrictions on persistent organic pollutants in adhesive formulations redirect manufacturers toward bio-based acrylate chemistries. The Port of Antwerp serves as a consolidation hub for pharmaceutical cold-chain labeling specifications across Benelux distribution networks.
Barcode Printers and Consumables Market Competitive Environment
East Asian producers anchor one tier through thermal printhead foundry capacity; North American and European specialists hold differentiated positions through channel partnerships and precision consumable engineering. The vendor base organizes around three strategic archetypes: diversified industrial technology conglomerates with barcode divisions, pure-play identification specialists with deep consumable formulation expertise, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include backward integration into printhead manufacturing and cloud-native fleet management platform development.
Within the diversified technology tier, Zebra Technologies Corporation and Honeywell International Inc. occupy positions defined by North American channel density and ruggedized hardware portfolios. SATO Holdings Corporation exemplifies the precision consumable specialist archetype through its Japan-based die-cutting capabilities and pharmaceutical-grade ribbon formulations. TSC Auto ID Technology Co., Ltd. represents regional scale fabrication, leveraging proximity to East Asian thermal printhead supply chains for cost-optimized industrial printer output.
| Leading Market Players |
|---|
| SATO Holdings Corporation |
| TSC Auto ID Technology Co., Ltd |
| Zebra Technologies Corporation |
| Canon Inc. |
| Avery Dennison Corporation |
| Honeywell International Inc. |
| Toshiba Tec Corporation |
| Bixolon |
| Seiko Epson Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-validated ribbon formulations and commodity wax-resin alternatives manifests in both pricing stratification and supply chain configuration. Premium thermal transfer consumables command sustained margins through batch-traceability documentation and WHO-prequalified status, while standard-grade products compete on volume scale through East Asian foundry relationships.
Pricing Analysis
Distributor margin layers in thermal transfer ribbons separate validated pharmaceutical-grade formulations from commodity industrial supplies. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/IEC 15416 certification status, FDA UDI compliance documentation, and regional logistics costs. Cost compression in standard-grade wax-resin ribbons is intensifying because East Asian OEMs are expanding captive printhead capacity. Healthcare procurement committees exhibit lowest price sensitivity due to regulatory validation requirements, while third-party logistics providers in high-volume parcel sorting show highest sensitivity to per-label economics.
Supply Chain Analysis
ISO-grade certification gating restricts pharmaceutical ribbon supply to facilities with documented batch consistency protocols and FDA establishment registration. Manufacturing concentrates in Japan, Germany, and South Korea for precision die-cutting and thermal printhead fabrication. Raw material flows draw from Taiwanese semiconductor-grade ceramics for printhead substrates, Belgian petrochemical feedstocks for synthetic label adhesives, and Chinese rare-earth processing for thermal transfer coatings. Single-source vulnerability in piezoelectric printhead foundries exposes OEMs to regional disruption risk. Distribution runs through certified reseller networks in North America and direct OEM relationships in European automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in barcode hardware and consumables rests on cloud-native fleet management adoption and synthetic substrate premiumization in cold-chain logistics. Ribbon suppliers capturing WHO-prequalified status and temperature-responsive formulation patents will extract pricing power from regulatory serialization mandates.
For Market Incumbents: Extend cloud-native printer fleet management platforms to capture recurring service revenue and lock in third-party logistics provider relationships. SATO Holdings Corporation and Zebra Technologies Corporation should deepen backward integration into thermal printhead manufacturing to reduce East Asian foundry dependency. Defensive consolidation around RFID-thermal hybrid label capabilities counters smartphone-based scanning substitution in last-mile delivery nodes. For New Entrants and Emerging Players: CDSCO traceability rules in India open a window for ribbon suppliers with WHO-prequalified formulations to establish first-mover positions in pharmaceutical export zones. Target cold-chain serialization infrastructure in Gujarat and Maharashtra contract manufacturing organizations. Precision die-cut synthetic labels with irreversible temperature indicators represent the most penetrable premium segment. Go-to-market execution should leverage direct technical sales to aerospace MRO facilities seeking dual-redundant RFID-optical tracking. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier consumable manufacturers lack FDA validation documentation and ISO-grade certification capabilities. Long-term viability favors specialists with captive die-cutting technology and pharmaceutical-grade ribbon formulation expertise. Acquisition target archetype: regional European label fabricators with REACH-compliant bio-based adhesive capabilities and automotive supply chain relationships. Watch for inflection when EPA volatile organic compound enforcement accelerates water-based chemistry adoption and displaces solvent-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Fleet Management Platform | DHL Supply Chain and Kuehne+Nagel contracts in Germany's Ruhr cluster demonstrate platform consolidation value capture. |
| Backward Integration into Printhead Manufacturing | East Asian foundry concentration risk motivates OEMs to secure captive thermal printhead supply. |
| WHO-Prequalified Ribbon Formulation | CDSCO traceability rules in India's pharmaceutical export zones reward validated batch consistency documentation. |
| Bio-Based Adhesive Chemistry Transition | REACH restrictions on persistent organic pollutants redirect European manufacturers toward Ecodesign-compliant substrates. |
| RFID-Thermal Hybrid Label Development | Aerospace MRO facilities in Belgium and the Netherlands adopt dual-redundant tracking for component genealogy. |
Study Parameters
Bottom-up logistics and healthcare procurement modeling reconciled against top-down thermal printhead and consumable supply tracking forms the analytical core of this study. Primary interviews with warehouse operations directors, biomedical engineering managers at hospital systems, automotive Tier-1 supplier procurement leads, and pharmaceutical cold-chain logistics coordinators combined with secondary validation from FDA UDI guidance documents, EPA volatile organic compound emission databases, ISO/IEC 15415 and 15416 certification registries, and EU Ecodesign for Sustainable Products Regulation implementation notices. Triangulation across these sources ensures segment-level volume estimates align with supply-side manufacturing capacity disclosures.
Input-output matrices map thermal printer hardware shipments against ribbon attachment rates and label substrate consumption patterns across the projection horizon. Segmentation dimensions include product type, consumable chemistry grade, end-use industry vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to hardware refresh cycle compression observed in third-party logistics automation deployments and pharmaceutical serialization mandate implementation timelines. Forecast inputs incorporate thermal printhead foundry capacity expansion announcements and REACH-compliant adhesive reformulation cost trajectories.
Revisions become necessary when FDA UDI enforcement intensity shifts, EPA emission rulemaking accelerates solvent-based chemistry phaseouts, or East Asian foundry disruption alters thermal printhead availability. Forecasts reflect documented assumptions regarding warehouse automation adoption rates and cold-chain serialization infrastructure buildout. A model refresh is warranted upon material change in EU Ecodesign regulation scope or CDSCO traceability rule expansion to additional pharmaceutical export categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
US Print on Demand Market
Printing Technology
Variable Data Printing Market
Printing Technology
Digital Presses Market
Printing Technology
Print on Demand Market
Printing Technology
Managed Print Services Market
Printing Technology
Printing Machinery Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Card Printers Market
Printing Technology
Digital Production Printer Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Digital Franking Machine Market