
 Large Format Printer Market | 2026-2036
Large Format Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Large Format Printer Market Intelligence
EU F-Gas Regulation is broadening the cost-of-entry calculus for solvent and UV-curable large format printer imports into European markets. HP Inc. leverages its latex ink portfolio to preempt compliance-driven substitution cycles, while Mimaki Engineering Co., Ltd. specializes in UV-led flatbed configurations that sidestep fluorinated gas containment requirements. Canon Inc. anchors its competitive stance through piezoelectric printhead manufacturing scale across Asian supply nodes.
Large format printers are industrial-grade output devices engineered to print on media exceeding 24 inches in width, employing piezoelectric, thermal, or electrophotographic deposition technologies to achieve resolutions up to 2,400 dpi for banners, textiles, and technical drawings. Inkjet systems dominate installed base volumes due to lower capital thresholds and substrate versatility, whereas UV-curable platforms command premium positioning in rigid-media signage where instant curing eliminates drying infrastructure. Latex technology is displacing solvent alternatives in fleet refresh cycles as environmental compliance tightens across North American and European print service provider networks.
FDA indirect food contact rules, EPA NESHAP standards for hazardous air pollutants, and EU REACH chemical registration protocols collectively constrain ink formulation choices and equipment certification pathways for manufacturers serving food packaging and indoor display segments. China's GB standards for electronic product safety and MIIT energy efficiency labeling add parallel conformity layers for equipment imported or assembled domestically. Stakeholders must weigh regional regulatory divergence against platform standardization economics when configuring global product lines and aftermarket ink supply chains.
Market Dynamics
Large format printer procurement is consolidating around environmental compliance mandates, with solvent-to-latex fleet conversions accelerating across North American and European print service provider networks as VOC thresholds tighten.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated gas containment requirements for solvent and UV-curable systems are redirecting capital expenditure toward latex platforms that bypass containment infrastructure.
- Vehicle wrap industry scaling:China's Guangdong and Zhejiang provinces are expanding production hubs for fleet graphics and commercial vehicle branding.
- UV-LED curing advancement:Instant polymerization on rigid substrates eliminates drying infrastructure, opening signage contracts previously reserved for screen printing.
Market Restraints
- Piezoelectric printhead supply concentration:Asian manufacturing nodes dominate MEMS fabrication, creating single-source vulnerability for precision deposition components.
- EPA NESHAP compliance costs:Hazardous air pollutant controls for solvent-based operations impose capital burdens on mid-sized print service providers.
- Substrate volatility:PVC banner material prices fluctuate with petrochemical feedstock markets, compressing margin predictability for high-volume contract work.
Strategic Opportunities
- Textile printing in China:Domestic apparel and soft signage production is adopting dye-sublimation systems at scale, creating aftermarket ink and service demand.
- Indoor display certification:FDA indirect food contact rules and EU REACH protocols are creating premium tiers for compliant ink formulations in retail environments.
- Hybrid UV-latex convergence:Equipment combining flexible ink adhesion with rigid-substrate capability is opening single-machine contract diversification.
Industry Challenges
- Color management specialization:ICC profiling and RIP software expertise shortages constrain service quality consistency across distributed print networks.
- Legacy solvent infrastructure stranding:Existing drying tunnels and ventilation systems face accelerated depreciation as environmental regulations tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Format Printer Market |
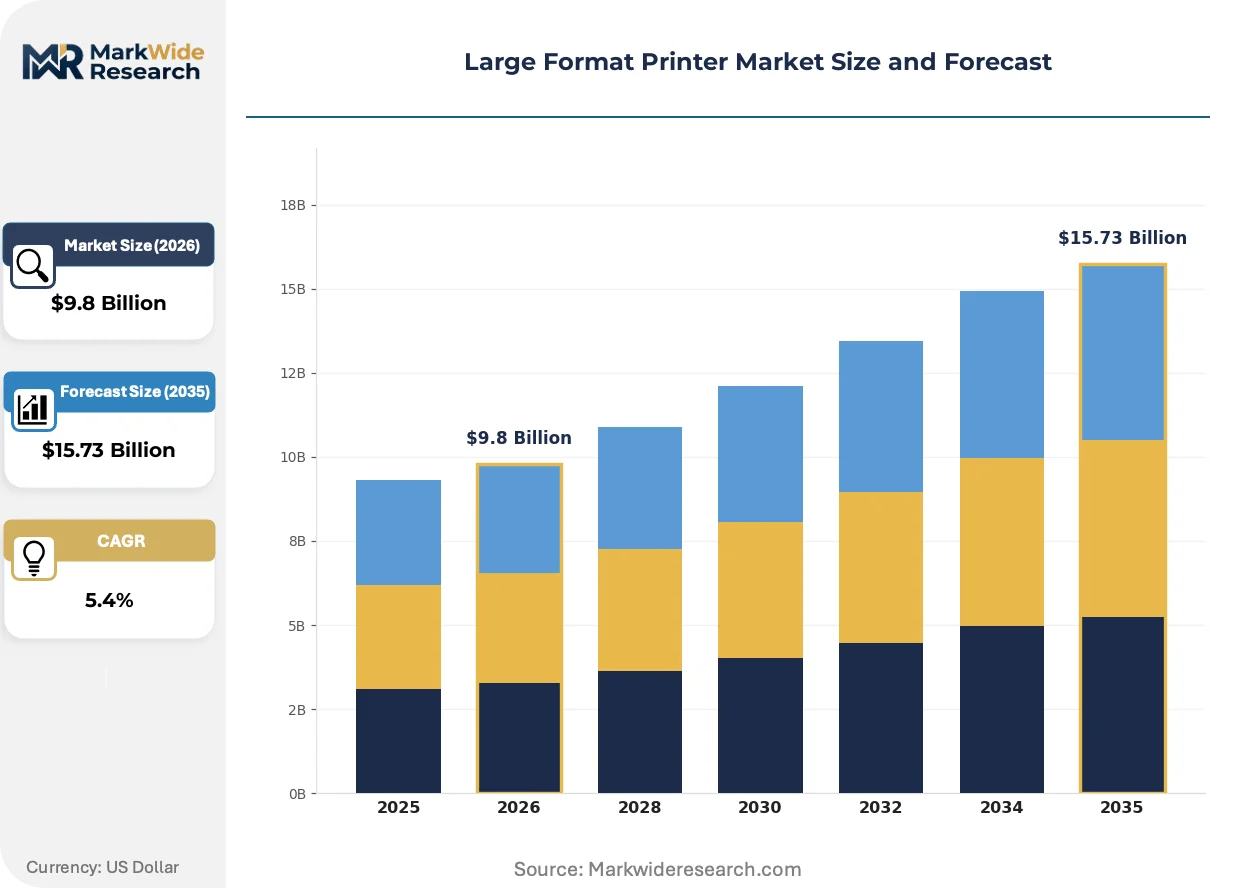
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Dye Sublimation, UV, Solvent, Latex, Thermal Transfer Technology: Piezoelectric, Thermal, Continuous Inkjet, Drop-on-Demand, Electrophotographic, Laser Application: Advertising, Textile Printing, Vehicle Graphics, Architectural Plans, Fine Art, Signage End User: Print Service Providers, Graphic Design Studios, Textile Manufacturers, Vehicle Wrap Specialists, Architects, Museums |
| Companies Covered | Ricoh Company, Ltd., Roland DG Corporation, HP Inc., Mutoh Holdings Co., Ltd., Mimaki Engineering Co., Ltd., Canon Inc., Konica Minolta, Inc., Fujifilm Holdings Corporation, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Format Printer Market Strategic Shifts & Innovations
Active technology substitution is compressing equipment refresh cycles, with environmental compliance and substrate versatility emerging as primary selection criteria over pure speed metrics.
UV-curable inkjet deposition is consolidating market position in rigid-media signage applications. Signage contractors and retail display producers are adopting flatbed configurations for direct-to-substrate printing on acrylic, aluminum composite, and foam board. This technology compression is eliminating the drying infrastructure bottleneck that previously constrained turnaround times for short-run custom work.
REACH chemical registration protocols in Europe are reshaping formulation development priorities. Ink manufacturers must pre-register chemical substances and demonstrate safety profiles for indoor exposure scenarios. Indoor display and retail environment segments are responding by demanding comprehensive certification documentation from equipment and consumable suppliers.
Service contract unbundling is fragmenting traditional vendor-customer relationships. Print service providers are separating hardware acquisition from maintenance and ink supply agreements, treating each as independently negotiable cost centers. This behavior shift is most pronounced in North American commercial printing networks where fleet standardization across multiple locations drives volume-based procurement leverage.
Large Format Printer Market Segmentation
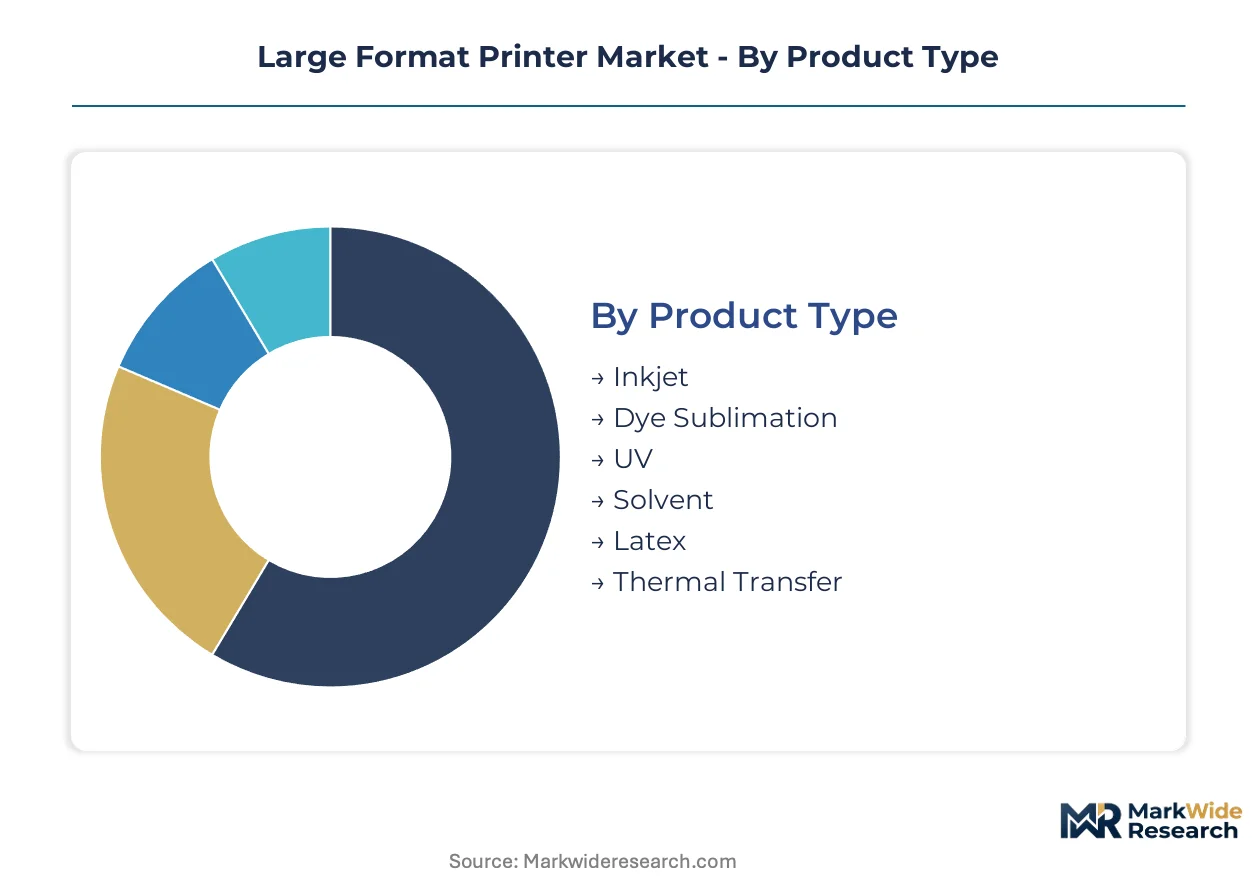
Segmentation in large format printing reveals how environmental compliance and substrate versatility are fragmenting procurement patterns across print service provider networks. Equipment selection increasingly hinges on regional regulatory thresholds rather than pure output speed specifications.
Product Type:
Supply concentration in printhead manufacturing and ink formulation creates divergent margin structures across deposition technologies.
- UV:Photoinitiator-based inks polymerize instantly under LED arrays, enabling direct-to-substrate printing on acrylic and aluminum composite. Guangdong signage contractors are consolidating procurement around flatbed UV configurations to capture retail display contracts requiring sub-24-hour turnaround.
- Latex:Water-based polymer dispersions with pigment encapsulation deliver odorless output suitable for indoor environments. North American and European print service providers are redirecting fleet refresh capital toward latex platforms as EPA NESHAP and EU F-Gas Regulation tighten solvent emission thresholds.
- Inkjet:Piezoelectric drop-on-demand systems dominate installed base volumes through lower capital entry points and substrate flexibility.
- Dye Sublimation:Heat-activated dye transfer penetrates polyester fibers for soft signage and apparel applications.
- Solvent:VOC-intensive formulations face accelerated depreciation as environmental compliance costs mount.
- Thermal Transfer:Wax or resin ribbon melting suits barcode and technical labeling with limited color gamut requirements.
UV absorbs the bulk of installed capacity in rigid-media signage; latex is expanding most quickly among fleet refresh cycles.
Technology:
Cost tier differentiation separates precision deposition systems from volume-oriented thermal alternatives.
- Piezoelectric:MEMS-fabricated printheads with variable droplet control achieve resolutions up to 2,400 dpi through mechanical deformation of ceramic actuators. Asian manufacturing nodes in Japan and South Korea dominate precision component fabrication, creating supply chain concentration for high-end textile and fine art applications.
- Drop-on-Demand:Selective droplet ejection eliminates recirculation infrastructure, reducing maintenance complexity for mid-volume print service providers.
- Thermal:Resistive heating elements vaporize ink for low-cost desktop and entry-level wide-format systems.
- Continuous Inkjet:Recirculating fluid systems suit high-speed industrial coding with limited color requirements.
- Electrophotographic:Toner-based imaging delivers consistent solids for technical drawings and architectural plans.
- Laser:Electrostatic drum charging supports monochrome CAD output with minimal consumable variability.
Piezoelectric platforms command premium positioning in quality-sensitive segments; drop-on-demand configurations are climbing the fastest among cost-optimized installations.
Application:
Volume concentration in outdoor advertising is diverging from margin-rich specialty segments.
- Signage:Rigid and flexible substrate output for retail environments, trade shows, and outdoor media encompasses banner vinyl, foam board, and corrugated plastic. Zhejiang province vehicle wrap specialists are scaling dye-sublimation and latex capacity to serve domestic fleet branding demand.
- Textile Printing:Direct-to-fabric and transfer-based systems address soft signage, apparel decoration, and interior décor with water-based or disperse ink chemistries.
- Advertising:High-volume poster and billboard production prioritizes throughput over color fidelity.
- Vehicle Graphics:Cast vinyl application requires conformable films and specialized laminates for curved surfaces.
- Architectural Plans:Monochrome and color CAD output demands dimensional accuracy over gamut breadth.
- Fine Art:Archival pigment inks on cotton rag or canvas serve museum and gallery reproduction requirements.
Signage absorbs the bulk of installed capacity; textile printing is gaining share fastest as domestic production scales in China.
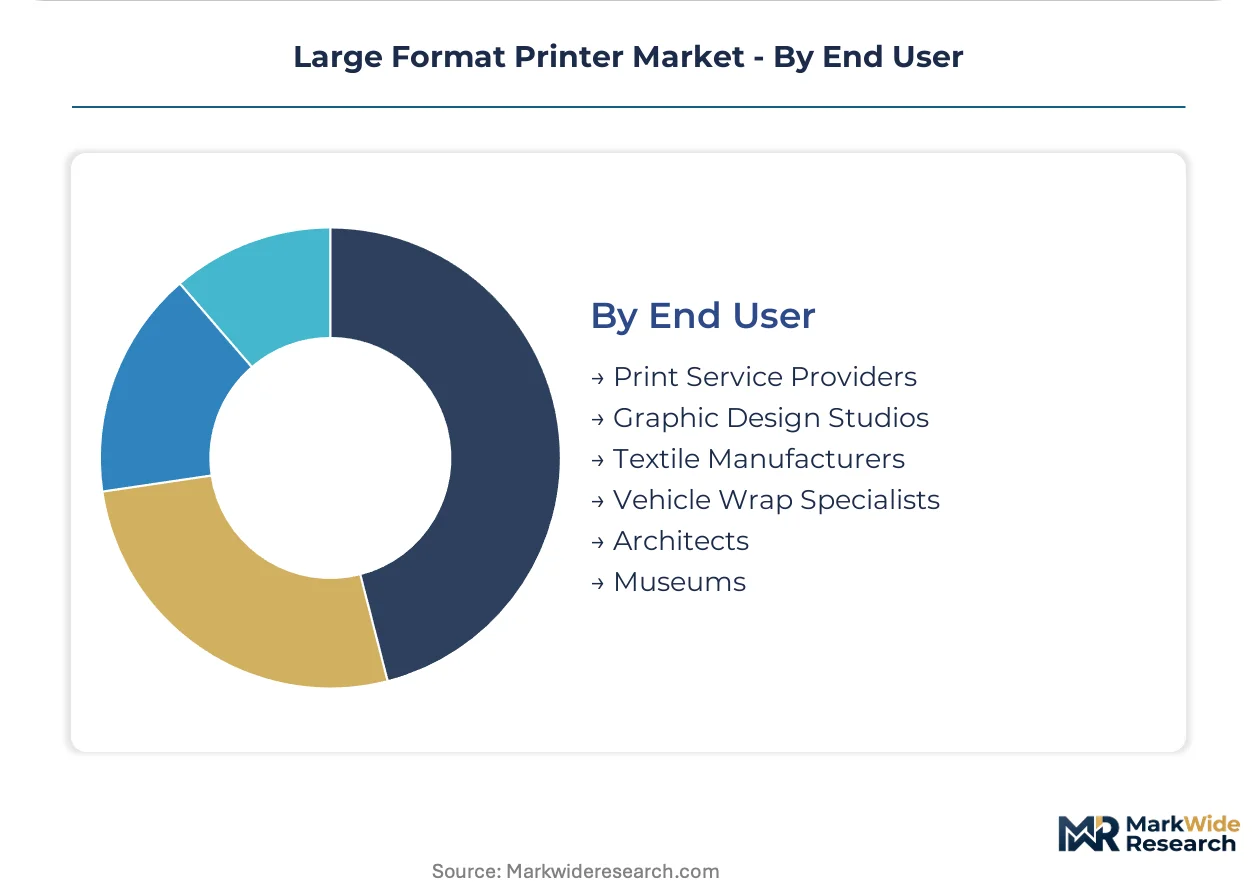
End User:
Customer type determines service contract structure and aftermarket ink attachment rates.
- Print Service Providers:Multi-machine fleet operators negotiate volume-based consumable agreements and unbundled maintenance contracts. North American networks are standardizing across locations to consolidate procurement leverage.
- Vehicle Wrap Specialists:Dedicated installation shops combine printing capability with substrate application expertise.
- Graphic Design Studios:Creative agencies with captive production prioritize color consistency and ICC profiling control.
- Textile Manufacturers:Integrated apparel producers adopt dye-sublimation for fast-fashion sampling and short-run production.
- Architects:Engineering and construction firms require technical document output with plotter-grade dimensional precision.
- Museums:Cultural institutions demand archival certification and limited edition reproduction protocols.
Print service providers absorb the bulk of installed capacity; vehicle wrap specialists are expanding most quickly as commercial fleet branding scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of incremental capacity installations, with textile printing and vehicle wrap production scaling fastest among emerging demand centers. Regulatory divergence across major economies is fragmenting equipment specification requirements and redirecting capital flows toward compliant platform categories.
United States
Print service provider networks in California, Texas, and the Northeast Corridor are accelerating solvent-to-latex fleet conversions. EPA NESHAP standards for hazardous air pollutants impose ventilation and capture infrastructure requirements on solvent-based operations. Chicago-area contract printers are consolidating procurement leverage through multi-location fleet standardization agreements.
Germany
Industrial signage producers in Bavaria and North Rhine-Westphalia prioritize UV-curable flatbed configurations for retail display contracts. EU F-Gas Regulation mandates fluorinated gas containment systems for qualifying equipment categories, elevating compliance costs for solvent and UV-curable imports. Stuttgart automotive branding specialists are scaling latex capacity to serve OEM fleet graphics programs.
China
Domestic textile printing and vehicle wrap industries in Guangdong and Zhejiang provinces are expanding production hub capacity. MIIT energy efficiency labeling and GB standards for electronic product safety add conformity layers for equipment assembled or imported. Shenzhen dye-sublimation operators are capturing soft signage demand from Southeast Asian apparel brands.
Japan
Precision manufacturing clusters in Kanto and Kansai regions sustain demand for piezoelectric printhead fabrication equipment. METI industrial policy supports advanced materials processing capabilities including ceramic actuator component production. Nagoya-area equipment assemblers are integrating MEMS fabrication expertise into next-generation deposition systems.
United Kingdom
London and Southeast England print service providers are unbundling hardware acquisition from maintenance and ink supply agreements. REACH chemical registration protocols constrain indoor display ink formulation choices and certification pathways. Manchester retail environment specialists are demanding comprehensive compliance documentation from equipment suppliers.
Large Format Printer Market Key Industry Players
Japanese producers anchor the precision deposition tier; American and European specialists hold differentiated positions in ink formulation and environmental compliance platforms. Market structure exhibits moderate consolidation around integrated hardware-ink systems vendors, with fragmentation persisting in regional service and aftermarket supply layers. Three archetypes dominate: vertically integrated printhead manufacturers, environmental compliance platform specialists, and unbundled equipment-assemblers. Capacity expansion and strategic technology licensing represent the dominant competitive moves across tier boundaries.
Among Japanese precision component fabricators, Ricoh Company, Ltd., Mimaki Engineering Co., Ltd., and Seiko Epson Corporation occupy positions emphasizing piezoelectric deposition expertise and MEMS manufacturing scale. These entities exemplify the integrated printhead-to-systems archetype that dominates quality-sensitive textile and fine art segments. HP Inc. represents the environmental compliance platform specialist model, leveraging water-based latex chemistry to preempt regulatory substitution cycles in North American and European fleet refresh markets.
| Leading Market Players |
|---|
| Ricoh Company, Ltd. |
| Roland DG Corporation |
| HP Inc. |
| Mutoh Holdings Co., Ltd. |
| Mimaki Engineering Co., Ltd. |
| Canon Inc. |
| Konica Minolta, Inc. |
| Fujifilm Holdings Corporation |
| Seiko Epson Corporation |
| Others |
Cost & Logistics Intelligence
Print service provider network consolidation in North America and Europe concentrates procurement leverage around fleet standardization agreements, anchoring contract-based long-term offtake pricing with volume-based consumable discounts.
Pricing Analysis
Short lead-time premiums apply to UV-curable flatbed configurations serving Guangdong signage contractors facing sub-24-hour turnaround requirements. Three-tier pricing structure across premium piezoelectric systems, standard drop-on-demand platforms, and economy thermal alternatives reflects printhead precision grade and MIIT energy efficiency certification level. Cost compression in solvent-based equipment is intensifying because EPA NESHAP compliance burdens accelerate depreciation. Mid-sized print service providers exhibit highest price sensitivity due to capital constraints, while vehicle wrap specialists in Zhejiang province show lowest sensitivity given margin-rich fleet branding contracts.
Supply Chain Analysis
Piezoelectric printhead fabrication rests on Japanese and South Korean MEMS manufacturing nodes, with ceramic actuator components drawing from Kanto-region precision ceramics suppliers. Water-based latex polymer dispersions and photoinitiator formulations for UV systems hinge on German and Chinese specialty chemical producers. Single-source vulnerability concentrates in MEMS fabrication equipment, where Tokyo Electron and Canon Inc. anchor precision deposition component supply. Distribution runs through authorized dealer networks in North America and direct OEM relationships in China, with aftermarket ink supply increasingly unbundled from hardware acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piezoelectric printhead manufacturing capacity constraints prop equipment pricing power, as Asian MEMS fabrication nodes operate at effective capacity serving quality-sensitive textile and fine art segments.
For Market Incumbents: Lock in piezoelectric printhead supply agreements with Japanese MEMS fabricators to preempt competitor access during fleet refresh cycles. Canon Inc. and Ricoh Company, Ltd. already anchor ceramic actuator production scale; backward integration into photoinitiator formulation secures UV-curable platform margins against REACH-driven chemical registration cost inflation. For New Entrants and Emerging Players: Enter via dye-sublimation textile printing systems serving Southeast Asian apparel brands sourcing from Shenzhen production hubs. China's domestic soft signage demand presents the most penetrable geography, with MIIT energy efficiency labeling requirements creating certification-barrier entry points against unqualified imports. For Investors and Strategic Acquirers: Distressed-cycle entries favor unbundled equipment-assemblers in North American commercial printing networks facing solvent infrastructure stranding. Long-term viability centers on hybrid UV-latex convergence platforms serving single-machine contract diversification. Watch EPA NESHAP enforcement intensity as inflection indicator for accelerated solvent-to-latex substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printhead Manufacturing | Canon Inc.'s captive piezoelectric MEMS fabrication eliminates single-source vulnerability for precision deposition components. |
| Latex Platform Fleet Conversion Programs | HP Inc.'s water-based chemistry preempts EPA NESHAP compliance costs for North American print service provider networks. |
| UV-LED Curing Technology Licensing | Mimaki Engineering Co., Ltd. sidesteps EU F-Gas Regulation containment requirements through LED-array polymerization systems. |
| Dye-Sublimation Capacity Expansion in Guangdong | Zhejiang province vehicle wrap specialists capture domestic fleet branding demand from Southeast Asian apparel brands. |
| Service Contract Unbundling | North American multi-location networks treat hardware, maintenance, and ink supply as independently negotiable cost centers. |
Research Approach
Multi-period observation of equipment refresh cycle timing, fleet standardization patterns, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with print service provider operations directors, OEM procurement managers, aftermarket ink supply executives, and MEMS fabrication equipment specialists. Secondary validation drew from EPA NESHAP enforcement records, EU ECHA REACH registration databases, MIIT energy efficiency labeling disclosures, and customs trade data for large format printer imports. Bottom-up triangulation across installation base surveys and top-down reconciliation against disclosed manufacturer revenue streams ensured cross-verification.
Segment-weighting across deposition technology, substrate application, and end-user archetype dimensions structured the analytical framework across the analysis window. CAGRs derived from logistic diffusion modeling of technology substitution rates, with piezoelectric printhead supply constraints and REACH chemical registration timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA enforcement escalation or MEMS fabrication node disruption scenarios. Projections reflect documented assumptions regarding fleet refresh velocity and regulatory compliance cost pass-through elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
ID Card Printers Market
Printing Technology
RFID Printer Market
Printing Technology
Digital Production Printer Market
Printing Technology
Managed Print Services Market
Printing Technology
Commercial Printer Market
Printing Technology
Photo Printing Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Digital Paper System Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Cloud Print Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Global Microprinting Market
Printing Technology
Web to Print Market
Printing Technology
Oceania Digital Textile Printer Market