
 Digital Fabric Printer Market | 2026-2036
Digital Fabric Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Fabric Printer Market Insights
Shortage of skilled color technicians and digital workflow specialists is redrawing competitive boundaries across the Digital Fabric Printer landscape. Kornit Digital leverages vertical integration from ink formulation to software R&D to sustain premium positioning in direct-to-garment systems. Mimaki Engineering anchors its position through deep specialization in wide-format dye sublimation platforms for sportswear producers. Durst Group competes by controlling high-throughput pigment inkjet architectures designed for industrial textile mills.
A digital fabric printer deposits pigmented or reactive inks directly onto woven or knitted substrates using piezoelectric or thermal inkjet heads, achieving resolutions up to 1200 dpi without analog screen preparation. The equipment eliminates rotary screens and reduces water consumption by replacing wet dye baths with precision droplet deposition. Dye sublimation systems dominate volume in polyester sportswear and home textiles where color fastness requirements are stringent, while direct-to-garment platforms capture margin pools in short-run fashion and customized apparel. Pigment ink technology is displacing reactive chemistry in cotton printing as brands pursue waterless finishing compatible with tighter environmental standards.
EPA regulations on volatile organic compound emissions from solvent-based textile operations shape equipment procurement decisions in the United States, while REACH restrictions on azo dyes and heavy metal pigments redirect formulation roadmaps across European supply chains. China's MEE enforces wastewater discharge limits that accelerate migration from analog to digital pigment systems in the Yangtze River Delta textile belt. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting between eco-solvent, latex, and UV-cured technology platforms.
Market Dynamics
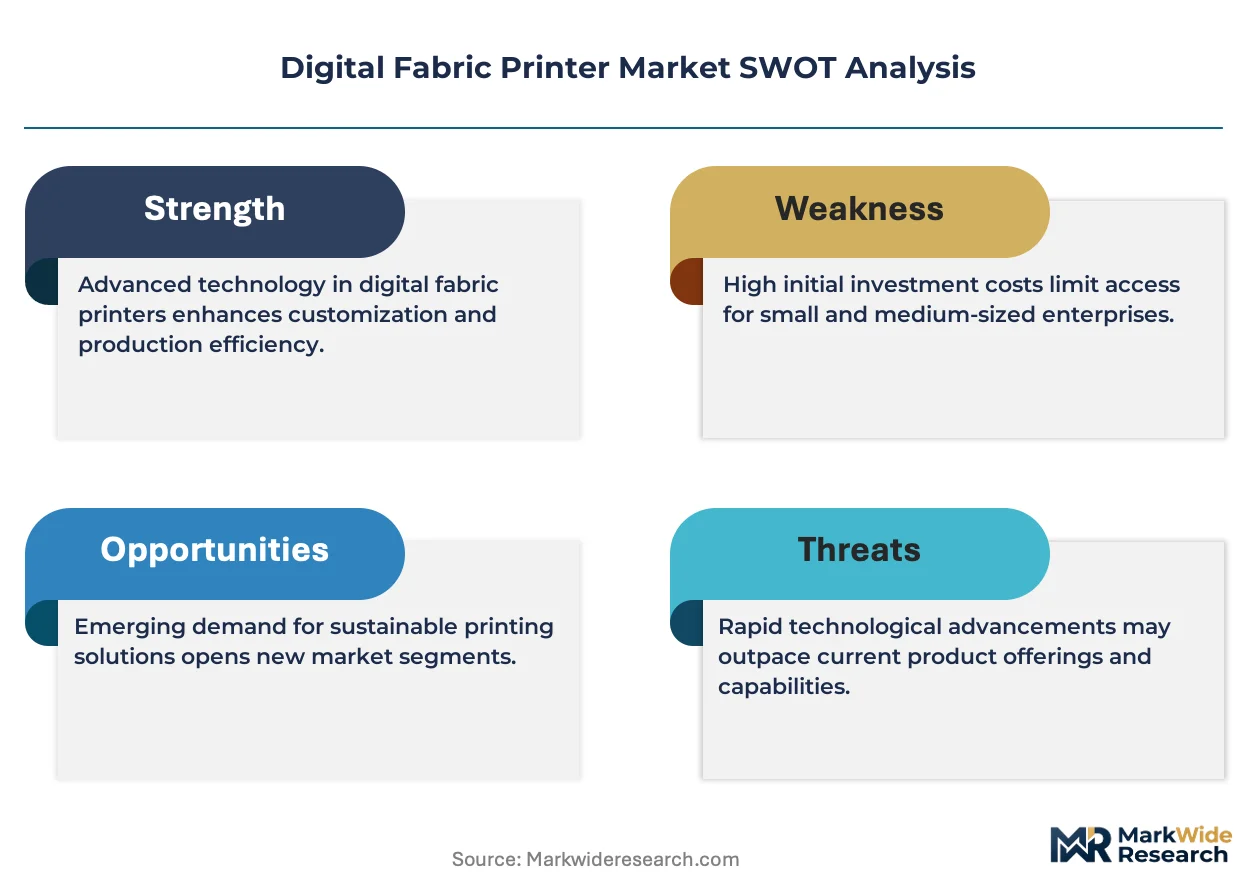
Waterless pigment ink systems are compressing production timelines and eliminating wastewater treatment infrastructure, forcing textile mills to choose between capital-intensive retrofitting or obsolescence as environmental compliance deadlines tighten across manufacturing clusters.
Growth Catalysts
- REACH azo dye restrictions:European apparel brands are redirecting procurement toward digital pigment platforms that bypass banned chromophores entirely, accelerating equipment replacement cycles in Portugal and Turkey.
- Polyester sportswear dye sublimation:Athletic apparel manufacturers in Vietnam and Bangladesh are installing wide-format systems to capture FIFA World Cup and Olympic licensing contracts with sub-48-hour turnaround requirements.
- Guangdong supply chain clustering:Integrated dye chemistry and finishing operations within 50-kilometer radii are reducing logistics costs for digital printer operators by consolidating substrate pretreatment, printing, and heat fixation.
Market Restraints
- Piezoelectric printhead supply concentration:Japanese and German precision ceramics manufacturers control 90% of industrial-grade nozzle arrays, exposing equipment OEMs to 14-week lead time volatility and forex-driven cost spikes.
- Pretreatment chemistry cost structure:Cationic agents for cotton pigment adhesion require specialized formulations that add 12-18% to per-meter processing costs versus reactive dye alternatives.
- Technical limitation in natural fiber gamut:Digital pigment systems cannot yet match the color depth and wash fastness of vat dyes on linen and hemp, constraining adoption in premium home textile segments.
Strategic Opportunities
- India technical textile expansion:The country's PLI scheme for man-made fiber apparel is incentivizing digital printing investments in Tiruppur and Surat to serve automotive upholstery and medical textile export contracts.
- AI-driven color matching convergence:Machine vision systems integrated with spectrophotometers are enabling real-time substrate compensation, reducing technician intervention and first-pass rejection rates.
- Direct-to-consumer platform integration:Shopify and WooCommerce APIs are connecting micro-factories to individual designers, collapsing the traditional wholesaler-distributor-retailer margin stack.
Industry Challenges
- Color technician scarcity:Digital workflow specialists capable of calibrating ICC profiles across mixed fiber batches command 40% salary premiums, constraining mill expansion plans in Indonesia and Egypt.
- Capex intensity for single-pass architectures:Industrial pigment systems with Kyocera or Ricoh print bar arrays require 2.5-4 million dollar investments that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Fabric Printer Market |
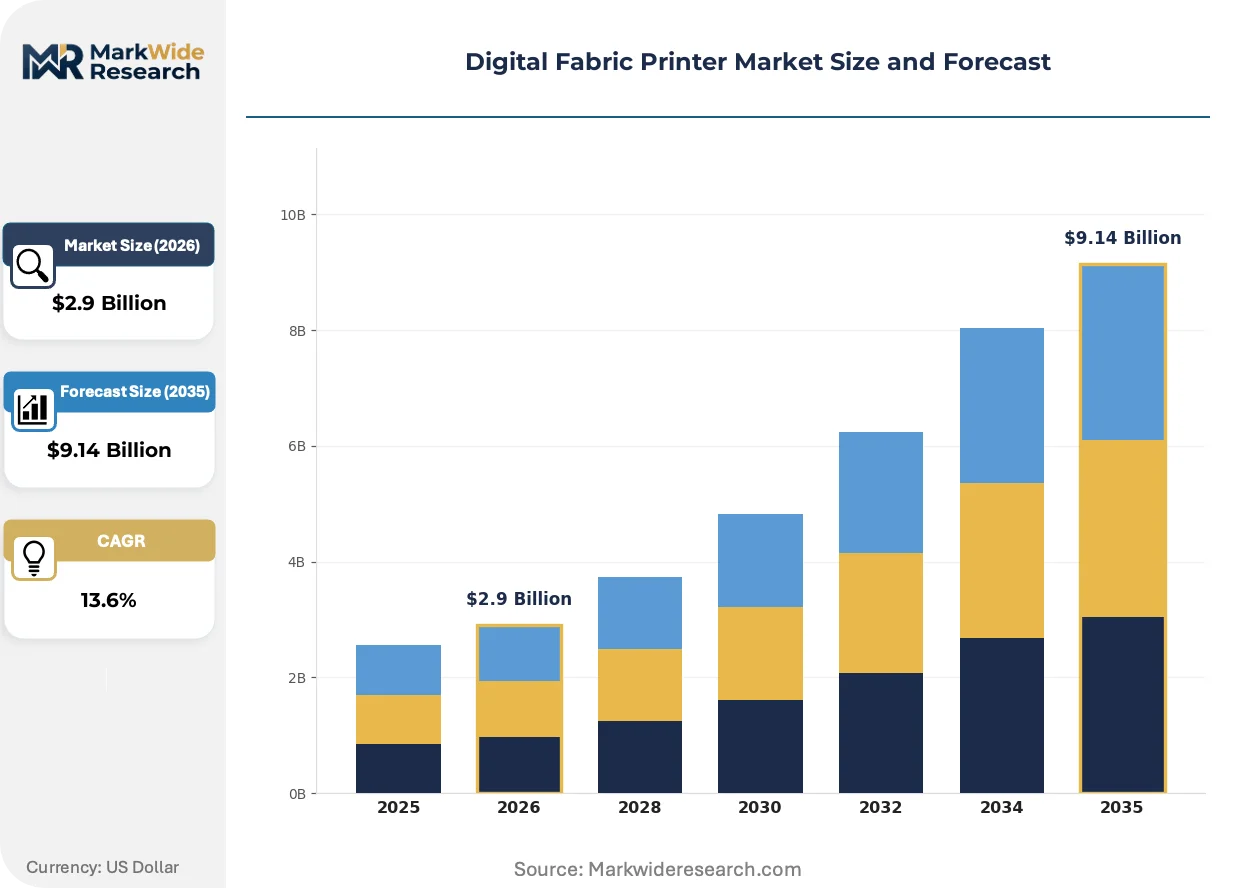
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $9.14 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-to-Garment, Dye Sublimation, Inkjet, Fabric Reactive Technology: Eco-Solvent, UV-Cured, Latex, Pigment End User: Fashion, Home Textiles, Sportswear, Automotive Interiors Size: Small Format, Large Format, Wide Format, Super Wide Format |
| Companies Covered | Kornit Digital, Mimaki Engineering, Seiko Epson Corporation, Durst Group, Roland DG Corporation, Brother Industries, Ricoh Company, Konica Minolta, SPGPrints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Fabric Printer Market Trends and Innovations
Precision droplet control and software-defined color pipelines are compressing the gap between sampling and bulk production, eliminating the traditional moat of analog screen houses while creating new vulnerabilities in intellectual property protection.
Single-pass pigment inkjet arrays with fixed print bar configurations are miniaturizing the physical footprint of industrial textile production. Fast-fashion retailers in Spain and the United Kingdom are deploying these systems in urban micro-factories positioned within 200 kilometers of flagship stores. This geographic compression is collapsing the traditional 12-week offshore sampling cycle into 72-hour domestic turnaround, redefing competitive advantage around proximity rather than labor arbitrage.
EPA volatile organic compound regulations for solvent-based textile operations are forcing equipment procurement decisions toward water-based pigment and latex platforms in the United States. Print service providers in North Carolina and California are retiring eco-solvent wide-format systems ahead of compliance deadlines to avoid penalty exposure. The regulatory pressure is most acute in signage-to-textile conversion shops where legacy equipment depreciation cycles conflict with emission reduction timelines.
Mass customization portals are fragmenting order patterns from thousand-meter bulk runs toward fifty-meter micro-batches with individualized colorways. Digital-native apparel brands in Los Angeles and Berlin are bypassing traditional converter relationships entirely, contracting directly with equipment owners on throughput-sharing arrangements. This disintermediation is most visible in influencer-driven merchandise drops where design-to-door timelines compress below ten days.
Digital Fabric Printer Market Segmentation
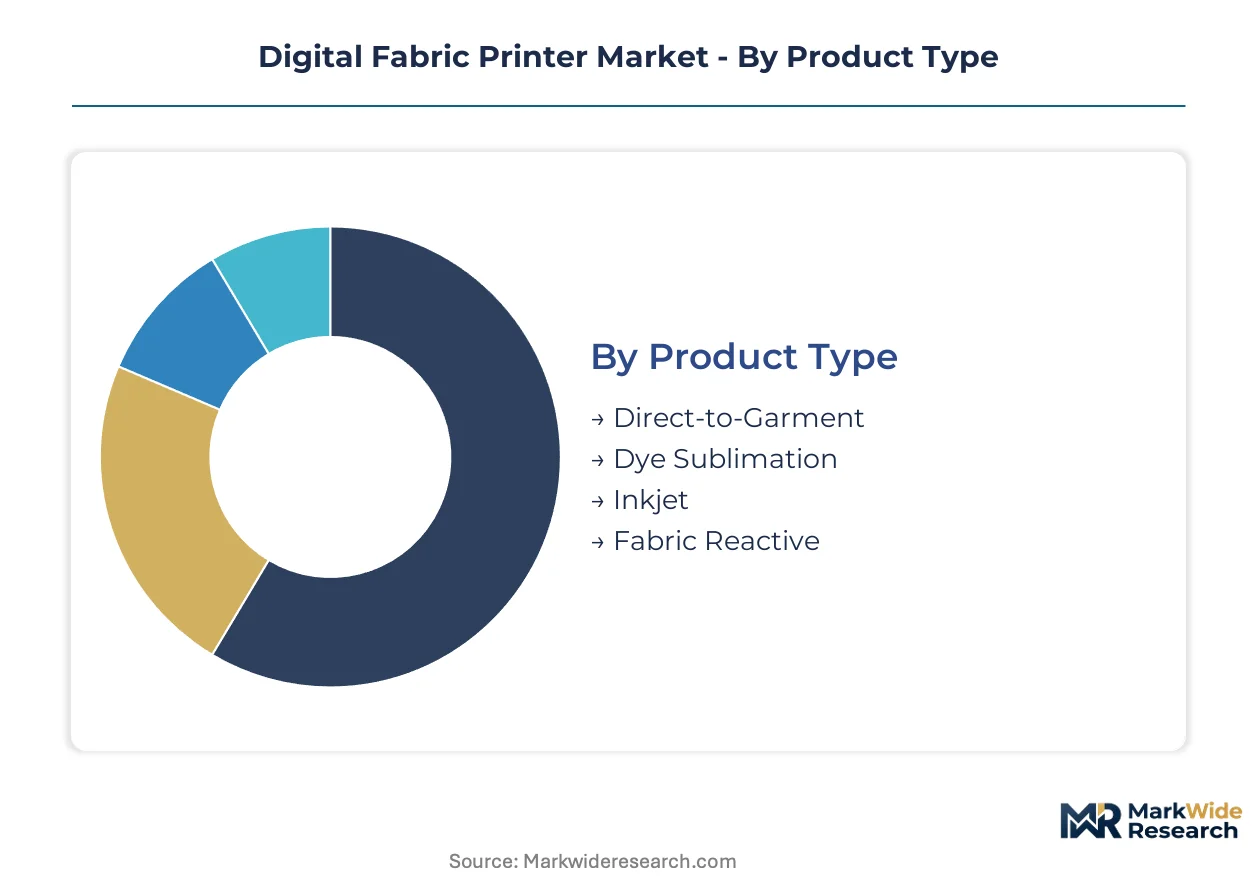
Technology selection in digital fabric printing determines capital intensity, environmental compliance exposure, and addressable substrate range. Segmentation reveals where equipment margins concentrate and which configurations face obsolescence pressure from regulatory shifts.
Product Type:
Margin pools concentrate in systems that eliminate analog screen preparation and compress sampling-to-bulk production timelines.
- Dye Sublimation:Heat-activated disperse dyes transfer from paper to polyester substrates through sublimation at 200°C, achieving permanent color bonding within polymer fibers. Demand clusters in Vietnam and Bangladesh athletic apparel mills serving FIFA and Olympic licensing contracts with sub-48-hour turnaround mandates. The dominant share belongs to Dye Sublimation, while Direct-to-Garment is closing the gap fastest.
- Direct-to-Garment:Piezoelectric heads deposit water-based pigment inks directly onto pre-treated cotton and cotton-blend garments without transfer paper intermediaries. Los Angeles and Berlin micro-factories deploy these systems for influencer merchandise drops with sub-ten-day design-to-door timelines.
- Inkjet:Continuous or drop-on-demand architectures deposit reactive, acid, or disperse chemistries onto rolled fabric substrates.
- Fabric Reactive:Alkaline-fixed dyes form covalent bonds with cellulose fibers in cotton and viscose, requiring steam fixation and extensive washing.
Equipment buyers face stranded asset risk as waterless pigment chemistries displace reactive systems in environmental compliance scenarios.
Technology:
Regulatory pressure on volatile organic compound emissions is resequencing technology adoption curves across manufacturing clusters.
- Pigment:UV-stable particles bind to fiber surfaces through resin encapsulation, eliminating water-intensive fixation and washing stages. Guangdong province mills are migrating to pigment systems ahead of MEE wastewater discharge enforcement in the Yangtze River Delta textile belt.
- Latex:Water-dispersed polymer carriers encapsulate pigments for heat-activated adhesion across cotton, polyester, and blended substrates. North Carolina print service providers are retiring eco-solvent systems ahead of EPA compliance deadlines, redirecting procurement toward latex platforms.
- Eco-Solvent:Glycol ether carriers dissolve resin-bonded pigments for flexible substrate adhesion with lower volatile organic compound profiles than true solvents.
- UV-Cured:Photoinitiator-triggered polymerization instantly fixes inks through ultraviolet exposure, enabling direct printing onto non-porous and rigid substrates.
Pigment systems command the dominant installed base, while Latex platforms are expanding most quickly in regulatory-sensitive North American and European markets.
End User:
Application-specific color fastness requirements and production velocity demands fragment equipment specifications across verticals.
- Sportswear:Polyester-dominant output demands dye sublimation systems with continuous calender fixation for perspiration and abrasion resistance. Bangladesh and Vietnam converters are installing wide-format configurations to capture athletic licensing contracts with compressed turnaround requirements.
- Fashion:Short-run, multi-SKU production favors direct-to-garment and single-pass pigment inkjet for rapid sampling and micro-batch economics. Milan and Tokyo fashion houses are accelerating on-demand adoption to reduce inventory waste and markdown exposure.
- Home Textiles:Linen and hemp substrates for premium bedding and upholstery constrain digital adoption due to pigment gamut limitations versus vat dye depth.
- Automotive Interiors:Technical textiles for seating and headliners require flame-retardant certification and abrasion testing that narrow qualified equipment and ink suppliers.
Sportswear applications hold the dominant equipment share, while Fashion verticals are gaining share fastest through direct-to-consumer platform integration.
Size:
Physical footprint and throughput specifications determine facility location economics and customer addressability.
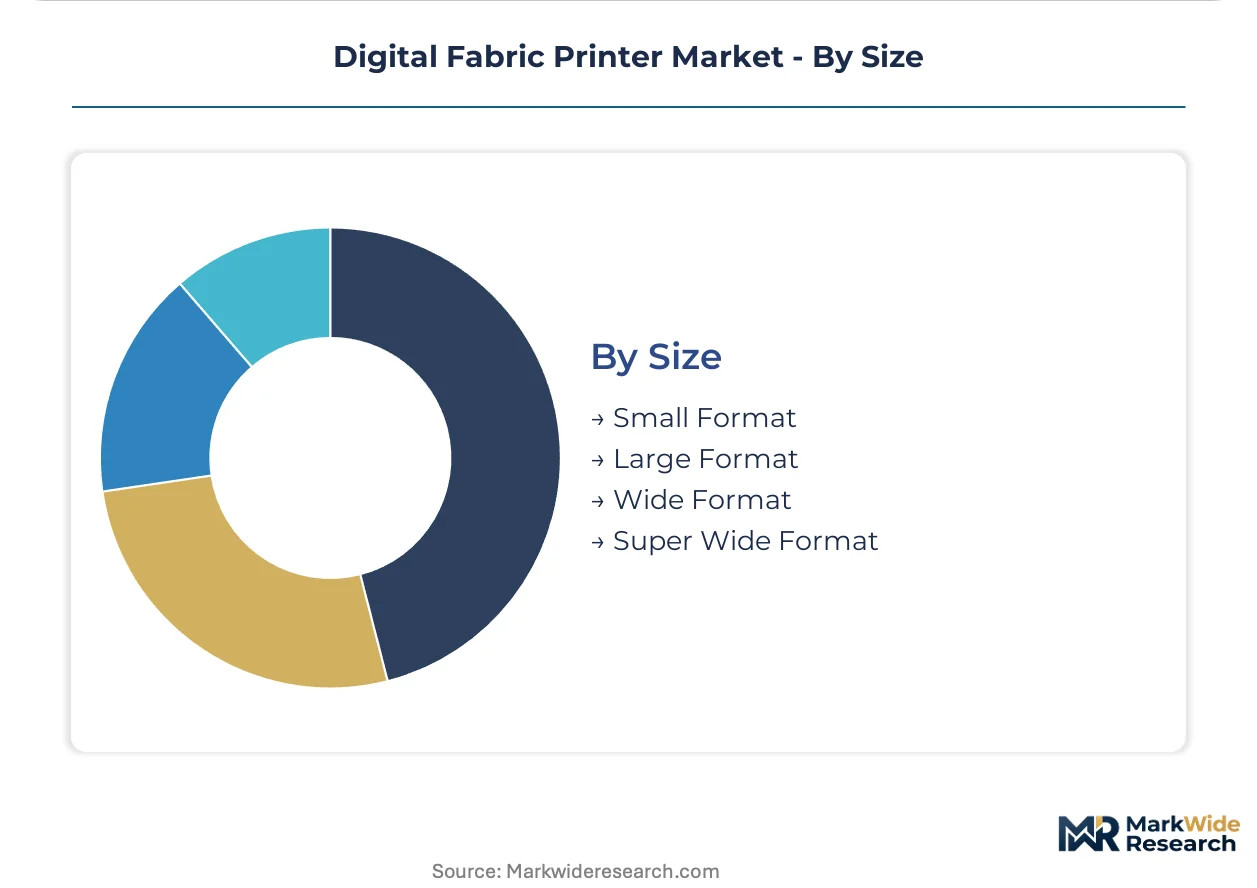
- Wide Format:1.6-3.2 meter print widths balance production velocity with floor space efficiency for mid-volume converters. Tiruppur and Surat technical textile producers under India's PLI scheme are standardizing on wide-format dye sublimation for automotive upholstery and medical textile export contracts.
- Large Format:1.0-1.6 meter widths serve sampling departments and small-batch converters with lower capital barriers.
- Small Format:Sub-1.0 meter desktop and benchtop systems target prototyping, customization shops, and educational institutions.
- Super Wide Format:Exceeding 3.2 meters, these systems address industrial textile mills with continuous roll-to-roll production and integrated pretreatment.
Wide Format configurations dominate current procurement, though Super Wide Format installations are climbing fastest among industrial mill retrofits replacing rotary screen houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes digital fabric printers as integrated production systems within dense supply chain clusters, while Western markets deploy them as standalone assets for on-demand manufacturing and regulatory compliance.
China
Guangdong province mills drive equipment procurement for polyester sportswear and home textile exports. MEE wastewater discharge enforcement in the Yangtze River Delta textile belt accelerates migration from analog dye baths to waterless pigment systems. Shenzhen and Dongguan industrial parks concentrate dye chemistry, pretreatment, and finishing operations within 50-kilometer radii.
United States
North Carolina and California print service providers retrofit facilities to serve fast-fashion micro-factories and direct-to-consumer brands. EPA volatile organic compound regulations for solvent-based textile operations force equipment retirement ahead of compliance deadlines. Los Angeles urban micro-factories position single-pass systems within 200 kilometers of flagship retail stores.
Germany
Technical textile producers in Baden-Württemberg and North Rhine-Westphalia invest in automotive upholstery and medical textile printing capabilities. REACH azo dye restrictions redirect formulation roadmaps toward digital pigment platforms that bypass banned chromophores. Stuttgart industrial corridor clusters equipment R&D with automotive OEM technical centers.
India
Tiruppur and Surat converters expand capacity to capture man-made fiber apparel export contracts. The national PLI scheme for technical textiles incentivizes digital printing investments in automotive upholstery and medical textile segments. Maharashtra industrial zones integrate dye sublimation systems with finishing operations for European brand supply chains.
Japan
Precision ceramics manufacturers in Nagoya and Osaka industrial belts control industrial-grade piezoelectric printhead supply for global equipment OEMs. METI industrial policy supports domestic production of high-throughput nozzle arrays amid 14-week lead time volatility. Tokyo fashion houses accelerate on-demand adoption to reduce inventory waste and markdown exposure.
Digital Fabric Printer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation hinging on ink formulation control, printhead architecture, and software-defined color pipelines. The upper tier commands premium positioning through captive supply of consumables and workflow automation. Three archetypes dominate: vertically integrated platform providers, precision component specialists, and regional system integrators. Competitive moves concentrate on strategic partnerships for geographic expansion and technology licensing for substrate range extension.
Within the integrated platform tier, Kornit Digital and Durst Group exemplify full-stack control from ink chemistry to production software. Mimaki Engineering anchors the precision specialist archetype through deep focus on wide-format dye sublimation architectures. Seiko Epson Corporation represents the component-to-systems expansion model, leveraging printhead manufacturing scale into finished equipment lines. These three occupy positions across distinct margin pools: direct-to-garment customization, industrial textile mills, and mid-volume converter markets respectively.
| Leading Market Players |
|---|
| Kornit Digital |
| Mimaki Engineering |
| Seiko Epson Corporation |
| Durst Group |
| Roland DG Corporation |
| Brother Industries |
| Ricoh Company |
| Konica Minolta |
| SPGPrints |
| Others |
Pricing and Supply Chain Analysis
Fixed print bar array manufacturing at Kyocera and Ricoh facilities generates steep scale economies that concentrate supply-side pricing power among Japanese precision ceramics producers while establishing hard price floors for mid-tier equipment OEMs seeking industrial-grade throughput.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between textile mills and equipment OEMs, with pricing stratifying across premium, standard, and economy tiers based on printhead resolution specifications and bundled software maintenance tiers. Price differentiation rests on ISO 14001 environmental certification status and geographic proximity to Guangdong dye chemistry clusters. Cost compression in standard-tier pigment systems is intensifying because Chinese MEE wastewater enforcement accelerates analog-to-digital migration. Fast-fashion micro-factories in Los Angeles and Berlin exhibit highest price sensitivity due to throughput-sharing revenue models, while automotive upholstery converters in Germany demonstrate lowest sensitivity given flame-retardant certification requirements.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European equipment distributors sourcing printhead arrays from Nagoya industrial belts. Geographic supply concentration centers on Japan, Germany, and China for piezoelectric nozzle arrays, precision motion control systems, and thermal fixation calenders respectively. Raw material dependencies draw from rare earth ceramics for piezoelectric actuators, specialty steel for frame assemblies, and resin precursors for pigment encapsulation. Single-source vulnerability at Japanese printhead manufacturers exposes OEMs to forex-driven cost spikes. Distribution runs through authorized dealer networks for industrial mills and direct-to-manufacturer channels for micro-factory deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital fabric printing sits in early-cycle expansion as waterless pigment chemistry penetration in Guangdong and Los Angeles demonstrates viable path to regulatory compliance without stranded analog assets.
For Market Incumbents: Fortify captive ink formulation capabilities to lock in consumables revenue streams as equipment margins compress from Kyocera printhead supply constraints. Deepen backward integration into pretreatment chemistry to offset cationic agent cost premiums threatening converter adoption rates. Prioritize certification investment for REACH azo dye compliance to preempt European brand procurement shifts. For New Entrants and Emerging Players: Lead with AI-driven color matching software as a standalone wedge into mid-tier converter markets where technician scarcity constrains mill expansion. Target India's technical textile segment under PLI scheme incentives as the most penetrable geography given automotive upholstery contract growth in Tiruppur and Surat. Deploy SaaS-tiered pricing to bypass capital intensity barriers for Indonesian and Egyptian converters. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision component specialists with printhead architecture control over pure-play system integrators vulnerable to supply concentration. Long-term viability across the projection horizon hinges on formulation-to-software integration depth rather than hardware throughput specifications alone. Acquisition target archetype: regional system integrators with captive dye chemistry relationships in Vietnam or Bangladesh. Signal to watch: Kyocera or Ricoh capacity announcements indicating printhead supply constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Pigment Ink Formulation Expansion | Captures consumables revenue from REACH-driven reactive dye displacement in Portugal and Turkey. |
| Single-Pass Architecture Deployment | Compresses physical footprint for Los Angeles urban micro-factories within 200 kilometers of retail. |
| AI Color Matching Integration | Reduces technician intervention for Indonesian mills facing 40% salary premiums for digital specialists. |
| Guangdong Supply Chain Clustering | Consolidates pretreatment, printing, and fixation within 50-kilometer radii for logistics cost reduction. |
| Direct-to-Consumer Platform APIs | Connects micro-factories to Shopify and WooCommerce for influencer merchandise drops. |
Research Methodology
Desk research of trade customs data, SEC equipment manufacturer filings, and MEE regulatory enforcement records preceded structured interviews with textile mill operations directors, digital workflow technicians, dye chemistry formulators, and printhead procurement managers at OEMs. Primary fieldwork captured installation timelines, utilization rates, and compliance cost structures across manufacturing clusters. Secondary validation drew from Guangdong industrial park surveys, REACH formulation databases, and EPA emission compliance tracking. Bottom-up equipment shipment data triangulated against top-down textile converter capacity estimates.
Variance decomposition across technology, substrate, and end-use dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured dye sublimation, direct-to-garment, and pigment inkjet configurations crossed with sportswear, fashion, and technical textile applications. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline mapping, and licensing contract velocity indicators. Forecast inputs incorporated MEE wastewater enforcement timelines and PLI scheme incentive disbursement patterns.
The analysis sits within stated boundaries; outcomes outside sustained REACH azo dye restriction enforcement or abrupt printhead supply disruption would require recalibration. Forecasts reflect documented assumptions regarding waterless pigment chemistry adoption curves and single-pass architecture cost reduction trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Cloud Print Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
Digital Printing Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Commercial Printer Market
Printing Technology
Managed Print Services Market
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
ID Card Printers Market
Printing Technology
Large Format Printer Market
Printing Technology
Variable Data Printing Market
Printing Technology
Professional Printers Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Global Cloud Printing Services Market