
 Industrial Inkjet Printer Market | 2026-2036
Industrial Inkjet Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Inkjet Printer Market Outlook
Buyer consolidation among multinational packaging converters is realigning procurement patterns toward vendor-managed service contracts and consolidated fleet standards. Domino Printing Sciences plc leverages its European service infrastructure to anchor long-term supply agreements with consolidated food and beverage groups. Videojet Technologies Inc. competes through North American channel density and rapid-response technical coverage. Squid Ink Manufacturing, LLC specializes in cost-optimized systems for mid-tier converters seeking coding reliability without premium overhead.
An industrial inkjet printer is a non-contact digital printing system that propels microscopic droplets of ink through piezoelectric or thermal actuation onto substrates at resolutions typically exceeding 300 dpi, enabling variable-data coding, marking, and decoration across porous and non-porous surfaces in production-line environments. Continuous inkjet systems retain dominant installed-base share in high-speed beverage and pharmaceutical coding where uptime tolerance approaches zero. UV inkjet segments capture expanding margin pools in electronics and automotive decoration where substrate diversity and instant-cure requirements exclude slower drying technologies. Drop-on-demand architectures gain traction in textile and short-run packaging applications where image quality flexibility outweighs pure velocity.
FDA serialization mandates for pharmaceutical packaging and EPA emissions frameworks for solvent-based inks shape equipment specification requirements across North American manufacturing facilities. REACH chemical restrictions and EU Green Deal decarbonization targets in Europe accelerate water-based and UV-cured technology substitutions. Stakeholders must monitor regulatory divergence between FDA track-and-trace enforcement and ECHA substance restrictions when configuring platform roadmaps and ink chemistry portfolios.
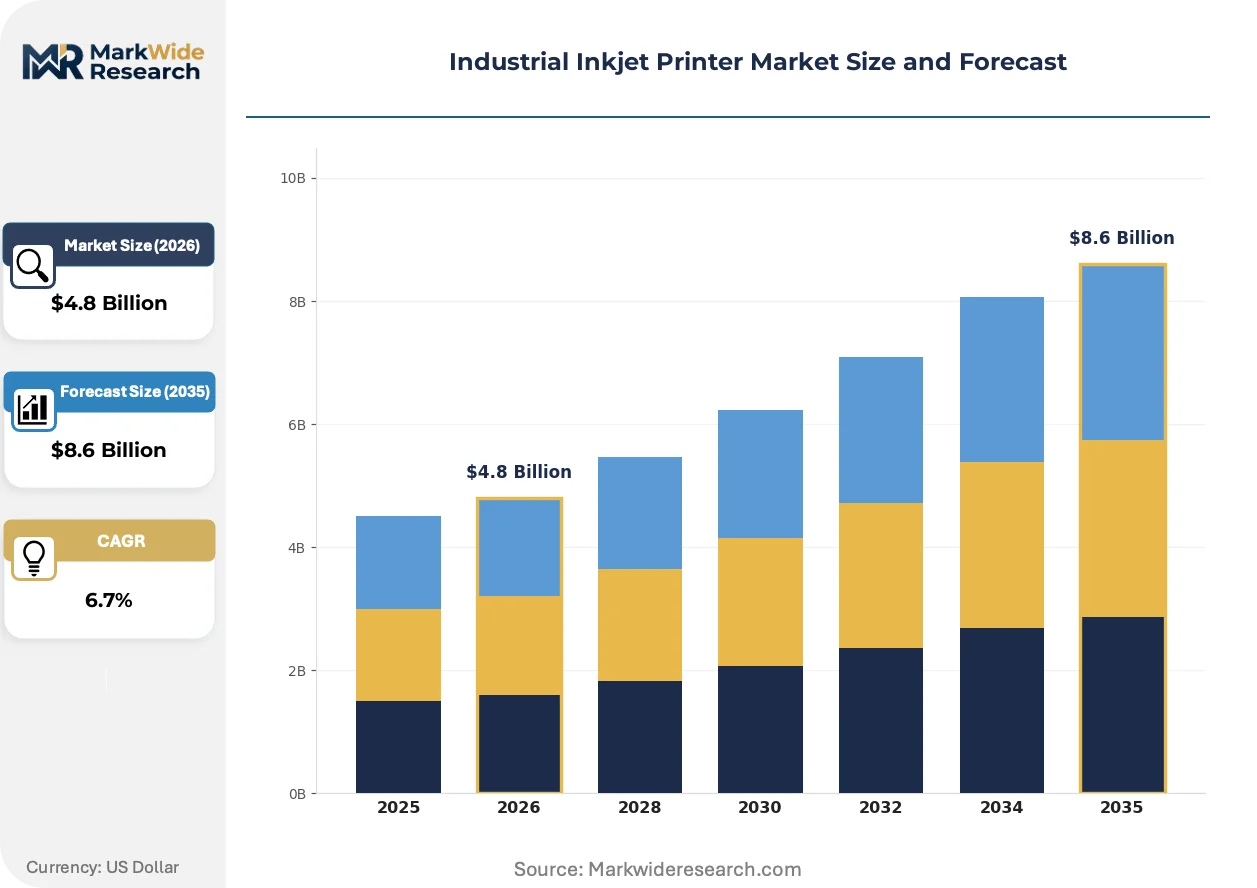
Market Dynamics
UV-cured inkjet architectures are compressing installed-base economics for solvent-based continuous systems as pharmaceutical and electronics converters prioritize instant-cure throughput over legacy drying infrastructure. REACH chemical restrictions and FDA serialization mandates are simultaneously accelerating fleet replacement cycles across European and North American production facilities.
Growth Catalysts
- REACH chemical safety mandates:European packaging converters face compulsory substitution of solvent-based chemistries, directing capex toward UV-cured and water-based inkjet platforms that eliminate hazardous air pollutants from production lines.
- Pharmaceutical serialization rules:Regulatory bodies in Germany and the United States enforce unit-level track-and-trace requirements, mandating high-resolution variable-data coding equipment with zero-defect verification protocols.
- Automotive part marking:Component traceability requirements for electric vehicle battery packs and powertrain assemblies are expanding demand for durable, heat-resistant inkjet marking systems capable of surviving assembly-line thermal stress.
Market Restraints
- Piezoelectric printhead supply concentration:Precision MEMS fabrication capacity clusters among Japanese and German component specialists, creating single-source vulnerability for drop-on-demand system manufacturers.
- UV ink raw material volatility:Photoinitiator and monomer feedstock prices fluctuate with petrochemical derivative markets, compressing margin predictability for ink formulators serving price-sensitive converter segments.
- Substrate compatibility limitations:Low-surface-energy plastics and silicone-coated films resist UV ink adhesion without costly corona or plasma pretreatment, restricting addressable application scope in flexible packaging.
Strategic Opportunities
- Textile digital decoration:Rotary screen displacement in European and East Asian apparel hubs creates white space for high-speed single-pass inkjet systems with reactive dye and pigment ink chemistries.
- EU Green Deal decarbonization targets:Carbon border adjustment mechanisms and embodied emissions reporting obligations favor water-based inkjet adoption over thermal drying processes in corrugated and folding carton production.
- Convergence of machine vision and print verification:Integrated camera-based defect detection and automatic nozzle compensation are enabling closed-loop quality assurance that reduces waste and reprint rates in pharmaceutical coding.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of piezoelectric drive electronics, ink circulation systems, and UV LED curing modules demands cross-functional expertise that outpaces vocational training pipeline output in manufacturing regions.
- Legacy PLC integration complexity:Brownfield production lines running proprietary communication protocols require costly middleware development to synchronize inkjet controllers with existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Inkjet Printer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Inkjet, Drop-on-Demand, Thermal Inkjet, UV Inkjet End User: Packaging, Textiles, Electronics, Automotive Technology: Solvent-Based, Water-Based, UV-Cured, Eco-Solvent Application: Labeling, Coding, Marking, Decoration |
| Companies Covered | Hitachi Industrial Equipment Systems Co., Ltd., Squid Ink Manufacturing, LLC, Videojet Technologies Inc., Leibinger GmbH & Co. KG, Matthews International Corporation, Domino Printing Sciences plc, Linx Printing Technologies Ltd., Inkatronic, Markem-Imaje SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Inkjet Printer Market Strategic Shifts
Single-pass inkjet architectures are collapsing the throughput gap with analog printing processes while enabling lot-size-one economics previously unattainable in high-volume packaging environments. Three convergent developments are restructuring equipment specification and procurement patterns across end-use verticals.
Single-pass array configurations are decentralizing print engine architecture away from centralized drum or cylinder mechanisms toward modular stationary print bars. European corrugated converters adopting these systems achieve 300-meter-per-minute speeds without mechanical registration limitations. The technology is decentralizing capital deployment models by enabling incremental capacity expansion through print bar addition rather than full press replacement.
EU Green Deal F-Gas Regulation and accompanying national carbon budgets are accelerating phase-out of solvent-based drying systems in favor of UV LED and electron beam curing. German automotive suppliers now specify instant-cure inkjet for interior trim decoration to eliminate thermal oven energy consumption. Electronics contract manufacturers in the Czech Republic and Hungary are retrofitting existing lines with UV LED modules to preempt carbon border adjustment exposure.
Converter procurement departments are consolidating vendor relationships around outcome-based service agreements that bundle equipment, consumables, and predictive maintenance. Large food and beverage groups in France and Spain now specify total-cost-per-code metrics rather than capital expenditure thresholds. This reconfiguration is most visible in pharmaceutical packaging, where serialization compliance liability has shifted risk preference toward vendor-managed uptime guarantees over equipment ownership.
Industrial Inkjet Printer Market Segmentation
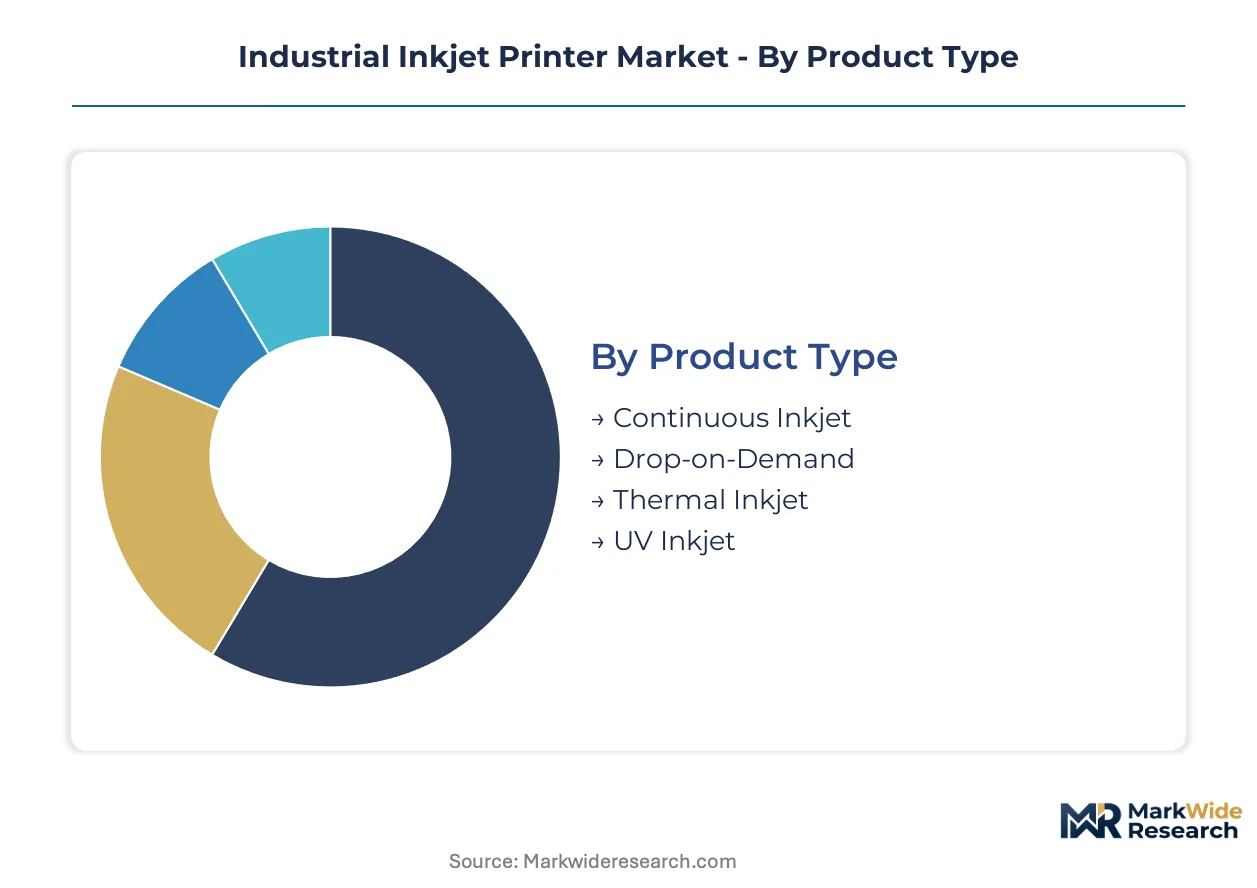
Industrial inkjet printer procurement decisions hinge on substrate compatibility, regulatory chemistry constraints, and production velocity requirements. Segmentation reveals how technology choices cascade through end-use specifications and application demands.
Product Type:
Buyers prioritize uptime tolerance and image quality flexibility when selecting between continuous and drop-on-demand architectures.
- Continuous Inkjet:Propels electrically charged ink droplets through a piezoelectric modulation chamber at velocities exceeding 50 meters per second, enabling uninterrupted high-speed coding on curved and irregular surfaces. Pharmaceutical bottling lines in Germany specify these systems for 24/7 serialization compliance with zero-defect verification protocols mandated by national pharmaceutical regulators.
- Drop-on-Demand:Activates individual nozzles through thermal or piezoelectric pulses, depositing variable droplet volumes for grayscale imaging and substrate-specific ink deposition. Textile converters in Italy and Spain favor piezoelectric variants for reactive dye compatibility on natural fiber blends where colorfastness requirements exclude thermal inkjet heat damage.
- Thermal Inkjet:Vaporizes ink through resistive heating elements, ejecting microdroplets without mechanical actuation complexity. Compact footprint suits desktop packaging prototyping and short-run label production.
- UV Inkjet:Cures photopolymer inks instantly through LED or mercury arc exposure, eliminating drying infrastructure. Electronics manufacturers in the Czech Republic specify these for instant-cure decoration of heat-sensitive polycarbonate housings.
Continuous Inkjet leads on scale; UV Inkjet leads on momentum.
End User:
Regulatory intensity and substrate diversity create divergent specification requirements across vertical applications.
- Packaging:Corrugated converters and folding carton producers demand coding systems that integrate with existing folder-gluer and die-cutting lines. REACH chemical restrictions in Europe are accelerating water-based and UV-cured substitutions for solvent-based flexographic pre-print.
- Electronics:Printed circuit board manufacturers and device assemblers require micron-level deposition accuracy for solder mask patterning and component marking. FDA-registered medical device facilities in the United States specify these systems for UDI compliance on implantable hardware.
- Automotive:Powertrain and battery pack producers specify heat-resistant ink chemistries surviving thermal cycling from -40°C to 150°C. German automotive suppliers now mandate instant-cure inkjet for interior trim to eliminate thermal oven energy consumption under EU Green Deal carbon budgets.
- Textiles:Rotary screen displacement in European apparel hubs creates demand for single-pass systems with reactive dye and pigment ink chemistries.
Packaging dominates installed base; Electronics expands most quickly.
Technology:
Chemistry selection directly determines emissions compliance, energy consumption, and substrate adhesion performance.
- UV-Cured:Photoinitiator-triggered polymerization enables instant curing without thermal drying, eliminating volatile organic compound emissions. German automotive and Czech electronics manufacturers specify these systems to preempt carbon border adjustment exposure.
- Water-Based:Pigment or dye dispersions in aqueous carriers suit porous substrates with minimal environmental permitting burden. EU Green Deal decarbonization targets favor these over thermal drying processes in corrugated production.
- Solvent-Based:Aggressive organic carriers penetrate non-porous films and coated stocks where water-based alternatives fail to wet out. REACH chemical safety mandates are compressing addressable market scope in European packaging.
- Eco-Solvent:Glycol ether formulations reduce hazardous air pollutant content while retaining substrate penetration for vinyl and banner applications.
Water-Based retains volume leadership; UV-Cured gains share fastest.
Application:
Resolution requirements and data variability distinguish functional coding from aesthetic decoration specifications.
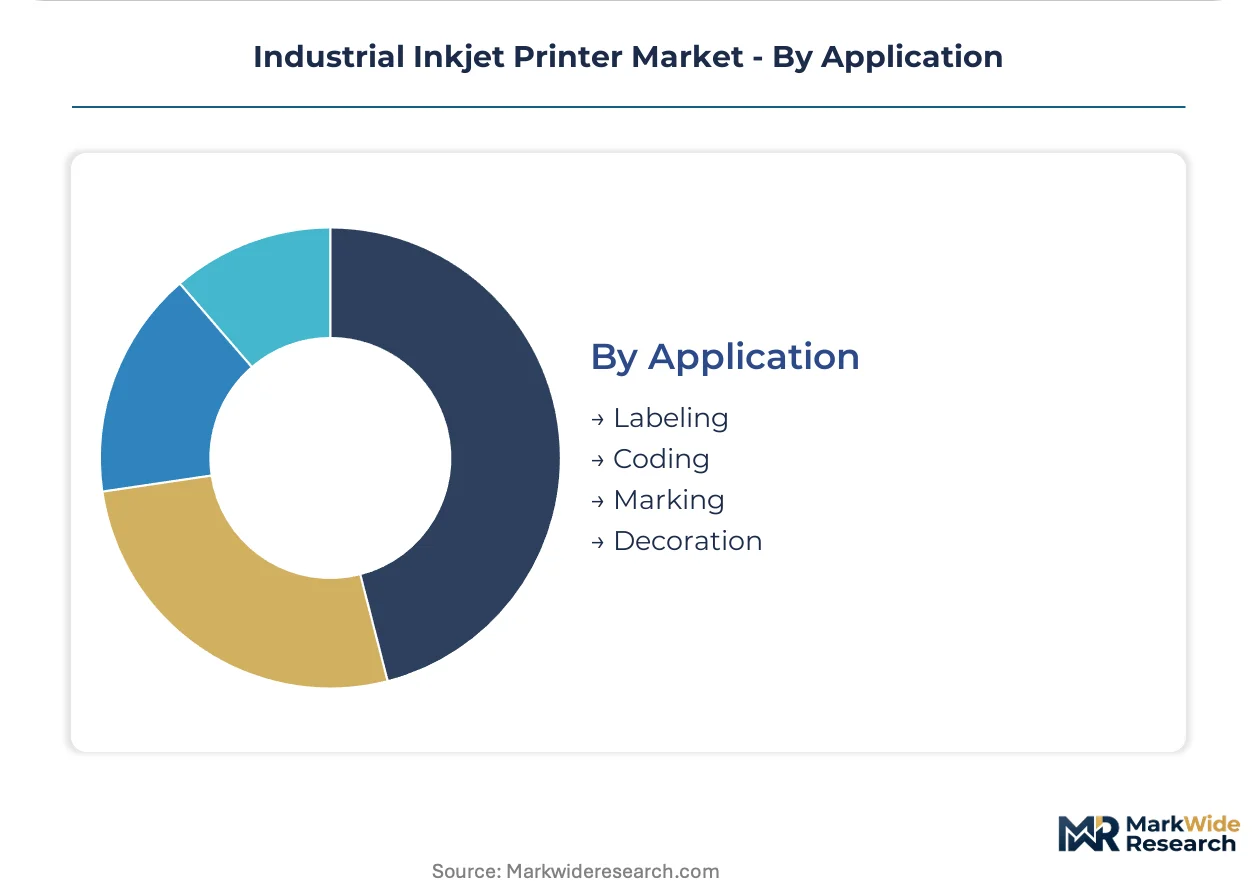
- Coding:Variable-data serialization at 300+ dpi enables unit-level track-and-trace for pharmaceutical and food safety compliance. FDA and EMA serialization mandates are standardizing equipment specifications across North American and European manufacturing facilities.
- Marking:Permanent identification on metal, glass, and engineered plastics withstands abrasion, chemicals, and thermal stress. Automotive battery pack producers specify these systems for component traceability through assembly-line thermal cycling.
- Labeling:Pressure-sensitive adhesive application and direct-to-package printing displace pre-printed label stock in short-run and versioned production.
- Decoration:Full-color imaging and specialty effects enhance brand differentiation in premium packaging and consumer electronics housings.
Coding commands the largest equipment footprint; Decoration climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and pharmaceutical sectors drive tighter coding specifications than the United States, where FDA serialization mandates and EPA emissions frameworks shape distinct procurement patterns.
Germany
Automotive battery pack traceability and pharmaceutical serialization dominate equipment specifications. REACH chemical restrictions and EU Green Deal carbon budgets compel UV-cured system adoption. Bavarian automotive suppliers specify instant-cure inkjet for interior trim decoration to eliminate thermal oven energy consumption.
United States
FDA track-and-trace enforcement for pharmaceutical packaging and EPA emissions controls for solvent-based inks direct fleet replacement cycles. Food and beverage groups consolidate vendor relationships around outcome-based service agreements. Midwestern pharmaceutical manufacturing clusters in Illinois and Michigan standardize on high-resolution variable-data coding systems.
China
Electronics contract manufacturing and textile digital decoration expand addressable demand for single-pass inkjet architectures. Dual carbon goals and MIIT industrial efficiency standards accelerate UV LED curing module retrofitting. Yangtze River Delta electronics hubs in Jiangsu and Zhejiang provinces prioritize instant-cure decoration for heat-sensitive polycarbonate housings.
Japan
Piezoelectric MEMS fabrication concentration creates supply-side leverage for drop-on-demand system manufacturers. METI industrial technology roadmaps support precision manufacturing equipment upgrades. Chubu region precision component clusters around Nagoya anchor printhead component specialization.
United Kingdom
Pharmaceutical serialization compliance and corrugated packaging decarbonization reshape converter procurement priorities. EMA serialization mandates and national carbon budgets favor water-based inkjet over thermal drying processes. Midlands pharmaceutical manufacturing facilities standardize equipment specifications for unit-level track-and-trace requirements.
Industrial Inkjet Printer Market Competitive Environment
Japanese and German producers anchor the precision-component tier; North American and European system integrators hold the service-infrastructure tier. The vendor base organizes around three strategic archetypes: precision MEMS fabricators controlling printhead supply, full-system integrators bundling equipment and consumables, and regional specialists optimizing for mid-tier converter price sensitivity. Consolidation pressures favor vendor-managed service contracts and predictive maintenance bundling over standalone equipment sales.
Within the full-system integrator tier, Domino Printing Sciences plc and Videojet Technologies Inc. exemplify contrasting geographic service strategies, while Hitachi Industrial Equipment Systems Co., Ltd. represents Japanese precision manufacturing heritage. Leibinger GmbH & Co. KG occupies a position within German-engineered continuous inkjet specialization. Squid Ink Manufacturing, LLC sits within the cost-optimized mid-tier segment serving converters seeking coding reliability without premium overhead.
| Leading Market Players |
|---|
| Hitachi Industrial Equipment Systems Co., Ltd. |
| Squid Ink Manufacturing, LLC |
| Videojet Technologies Inc. |
| Leibinger GmbH & Co. KG |
| Matthews International Corporation |
| Domino Printing Sciences plc |
| Linx Printing Technologies Ltd. |
| Inkatronic |
| Markem-Imaje SAS |
| Others |
Value Chain & Pricing Dynamics
Performance-tier bifurcation between pharmaceutical-grade serialization systems and commodity coding equipment manifests in divergent margin structures and supply chain sourcing strategies. Premium tiers command captive ink formulation contracts and dedicated service infrastructure, while mid-tier converters source through distributor networks with minimal aftermarket bundling.
Pricing Analysis
Capacity additions in Chinese electronics manufacturing hubs are reshaping price floors for UV-cured drop-on-demand systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical equipment from automotive marking systems and entry-level coding hardware. Pricing pressure stems from photoinitiator feedstock volatility squeezing ink formulator margins. Mid-tier packaging converters exhibit highest price sensitivity, while pharmaceutical serialization buyers prioritize compliance assurance over capital expenditure thresholds.
Supply Chain Analysis
Piezoelectric MEMS fabrication rests on Japanese and German precision component specialists, with downstream assembly concentrating in China, the Czech Republic, and Mexico. Raw material dependencies span photoinitiator chemicals from BASF and Arkema supply chains, UV LED modules from Seoul Semiconductor and Nichia, and specialty ink monomers from petrochemical derivative markets. Single-source vulnerability in printhead MEMS fabrication creates supply chain risk. Distribution runs through authorized service networks for premium tiers and industrial distributor channels for cost-optimized segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial inkjet printer demand compounds steadily through regulatory compliance mandates that force recurring fleet refresh cycles across pharmaceutical and automotive verticals.
For Market Incumbents: Anticipate margin compression from Asian electronics contract manufacturers entering the mid-tier coding segment through aggressive UV LED module pricing. Defend position by deepening backward integration into piezoelectric MEMS fabrication through partnerships with Nagoya-region component specialists. Prioritize vendor-managed service contract renewals with consolidated European food and beverage groups before competitor channel density improves. For New Entrants and Emerging Players: Direct-to-converter digital sales platforms offer the lowest customer acquisition cost pathway into price-sensitive corrugated converter segments in Spain and Italy. Target textile digital decoration white space in East Asian apparel hubs where rotary screen displacement accelerates single-pass inkjet adoption. Lead with reactive dye chemistry compatibility and rapid technical response capabilities rather than equipment capital cost competition. For Investors and Strategic Acquirers: Consolidation pressure builds where service infrastructure density determines pharmaceutical serialization contract renewal rates. The market supports 5-10 year compound growth through regulatory tailwinds with limited technology obsolescence risk. Target acquisition profile: regional specialists with installed base in automotive battery pack traceability applications. Watch ECHA substance restriction announcements as inflection indicators for accelerated UV-cured technology substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Printhead supply concentration in Japan and Germany creates captive sourcing advantages for system integrators. |
| Vendor-Managed Service Contract Expansion | European food and beverage groups now specify total-cost-per-code metrics rather than capital expenditure thresholds. |
| UV LED Curing Module Retrofit Programs | German automotive suppliers adopt instant-cure systems to eliminate thermal oven energy consumption under EU Green Deal carbon budgets. |
| Reactive Dye Chemistry Development | Italian and Spanish textile converters require piezoelectric compatibility for natural fiber colorfastness without thermal damage. |
| Predictive Maintenance Platform Launch | Integrated camera-based defect detection reduces waste and reprint rates in pharmaceutical serialization environments. |
Study Parameters
Multiple input streams — plant engineer interviews, OEM procurement team discussions, aftermarket service head consultations, and distributor channel partner surveys — were reconciled against secondary validation from SEC filings, customs trade data, and ECHA substance restriction databases. Primary fieldwork captured specification requirements across pharmaceutical serialization, automotive part marking, and electronics decoration verticals. Bottom-up equipment shipment analysis and top-down end-use industry spend estimates were triangulated to converge on market sizing.
Historical shipment trajectories were cross-referenced against expert panel assessments of REACH chemical restriction implementation timelines and FDA track-and-trace enforcement intensity. Segmentation dimensions modeled include product architecture, ink chemistry type, end-use vertical, application function, and regional regulatory cluster. CAGRs were derived from regression analysis of installed base evolution and replacement cycle compression. Industry-specific forecast inputs incorporated EU Green Deal carbon budget allocation patterns and MIIT industrial efficiency standard adoption curves in Chinese electronics manufacturing.
The model assumes a particular technology adoption path; alternative pathways for electron beam curing would alter the outlook if photoinitiator supply constraints accelerate substitution beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and piezoelectric MEMS fabrication capacity expansion. A small set of named triggers — ECHA substance restriction announcements, FDA serialization deadline extensions, and carbon border adjustment mechanism implementation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Web to Print Market
Printing Technology
Global Microprinting Market
Printing Technology
Card Printers Market
Printing Technology
ID Card Printers Market
Printing Technology
Print on Demand Market
Printing Technology
Digital Printing Market
Printing Technology
Print on Demand Software Market
Printing Technology
Digital Paper System Market
Printing Technology
US Print on Demand Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Printing Machinery Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Digital Production Printer Market
Printing Technology
Nordic Commercial Printing Market