
 Digital Presses Market | 2026-2036
Digital Presses Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Presses Market Insights
High-speed single-pass inkjet arrays is rewriting production economics for folding carton and corrugated converters. HP leverages captive ink chemistry development to lock in recurring supply revenue across installed bases. Canon anchors its position through sheet-fed inkjet platforms purpose-built for commercial print houses migrating from offset. Fujifilm dominates narrow-web label segments with UV inkjet configurations that bypass platemaking entirely.
A digital press is a non-impact printing system that transfers ink or toner directly from a digital file onto a substrate without intermediate plates or cylinders, typically achieving resolutions of 600 to 2400 dpi and operating at speeds from 30 to 500 linear meters per minute depending on configuration. Its primary commercial purpose is to enable economically viable production of variable-content, short-to-medium run lengths across packaging, publishing, and marketing collateral. Inkjet press architectures now capture the bulk of new capital expenditure in packaging applications where brand owners mandate lot-level traceability. Electrophotographic press lines retain entrenched positions in transactional and direct-mail workflows where toner-based image quality standards remain institutionalized. Hybrid press configurations that marry flexo units with digital print bars represent the fastest-growing installed base as converters seek to preserve existing substrate handling while adding versioning capability.
FDA food-contact notification requirements and EU REACH compliance on ink constituents shape formulation roadmaps and equipment qualification protocols for press manufacturers serving regulated packaging end users. ECHA substance restrictions on specific photoinitiators in UV-cured inks are forcing inkjet suppliers to reformulate product lines ahead of sunset dates. OSHA lockout-tagout and noise exposure standards govern press installation and factory floor layout decisions in US commercial print facilities. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple geographies that will impose end-of-life collection obligations on digital printing equipment and consumables.
Market Dynamics
Single-pass inkjet architectures are compressing breakeven run lengths for folding carton converters, forcing electrophotographic incumbents to defend installed bases through speed upgrades and ink cost restructuring.
Growth Catalysts
- FDA Food-Contact Notifications:Packaging converters in the United States must validate ink chemistries for direct food contact, creating recurring equipment qualification cycles that favor digital press vendors with captive formulation capabilities.
- EU REACH Substance Restrictions:Sunset dates on specific photoinitiators are accelerating press replacement timelines as converters face reformulation costs on legacy UV inkjet lines.
- Lot-Level Traceability Mandates:Pharmaceutical and food brand owners in Germany and Japan now require serialized packaging, pulling variable data printing capability into corrugated and label production environments.
Market Restraints
- Captive Ink Economics:Proprietary ink formulations from HP and Canon lock converters into single-vendor supply agreements, inflating lifetime operating costs relative to offset chemistry.
- Substrate Handling Limitations:Inkjet arrays struggle with recycled corrugated fiber and metallized films without pretreatment stations, restricting addressable packaging segments.
- Skilled Operator Scarcity:Digital press workflow management requires color science and RIP software expertise that traditional flexo operators rarely possess, lengthening commissioning timelines.
Strategic Opportunities
- Hybrid Press Configurations:Converters in Italy and Spain are retrofitting existing flexo lines with inkjet print bars, preserving capital in substrate handling while adding versioning capability.
- Extended Producer Responsibility Frameworks:Emerging collection obligations for printing equipment and consumables in France and the Netherlands will favor vendors with established recycling infrastructure.
- Water-Based Inkjet Penetration:Food packaging applications in the United Kingdom are migrating from UV-cured to water-based formulations to simplify regulatory compliance and reduce migration risk.
Industry Challenges
- Color Calibration Complexity:Brand color consistency across hybrid production environments demands spectrophotometric verification protocols that many commercial print houses lack.
- Legacy Prepress Integration:Offset workflows with entrenched platemaking departments resist digital job ticketing systems, creating organizational friction during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Presses Market |
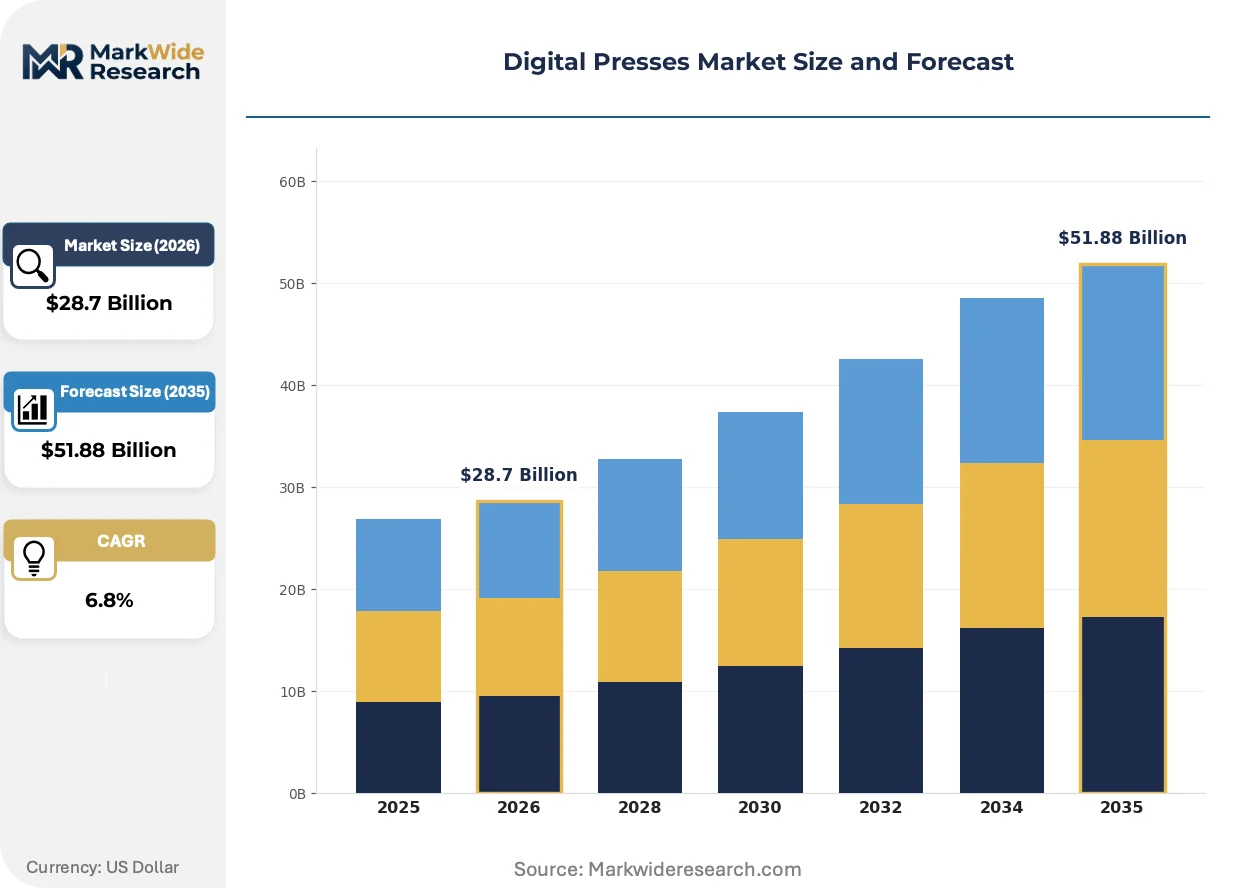
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Press, Electrophotographic Press, Hybrid Press, Digital Offset Press End User: Commercial Printers, In-plant Printers, Packaging Companies, Publishers Application: Packaging, Labels, Commercial Print, Publishing Technology: Variable Data Printing, Web-to-Print, 3D Printing, Print Automation |
| Companies Covered | Hewlett-Packard Development Company, L.P., Canon Inc., Ricoh Company, Ltd., Xerox Corporation, Konica Minolta Inc., Fujifilm Corporation, Seiko Epson Corporation, Mimaki Engineering Co., Ltd., Brother Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Presses Market Trends and Innovations
Equipment vendors are racing to compress total cost of ownership through chemistry-press integration and predictive maintenance architectures that reduce unplanned downtime.
Single-pass inkjet arrays with fixed printhead configurations are collapsing the cost structure for medium-run folding carton production. Folding carton converters in the United States and Germany are adopting these systems at replacement cycle points previously reserved for offset presses. The technology is collapsing minimum efficient scale thresholds, enabling geographic redistribution of packaging production closer to end markets.
EU REACH restrictions on specific photoinitiators in UV-cured inks are forcing formulation roadmaps toward compliant alternatives ahead of 2025 sunset dates. Ink suppliers must requalify product lines under ECHA substance evaluation protocols, extending equipment approval timelines for narrow-web label presses. Narrow-web converters in Poland and the Czech Republic are accelerating press purchases to lock in qualified chemistries before regulatory deadlines.
Brand procurement teams are unbundling hardware acquisition from consumable supply agreements, pressuring vendor margins on captive ink revenue. Commercial print houses in Japan and the United States are negotiating separate contracts for press maintenance, ink supply, and substrate sourcing. This purchasing behavior is most visible in high-volume transactional print segments where toner-based electrophotographic lines face replacement decisions.
Digital Presses Market Segmentation
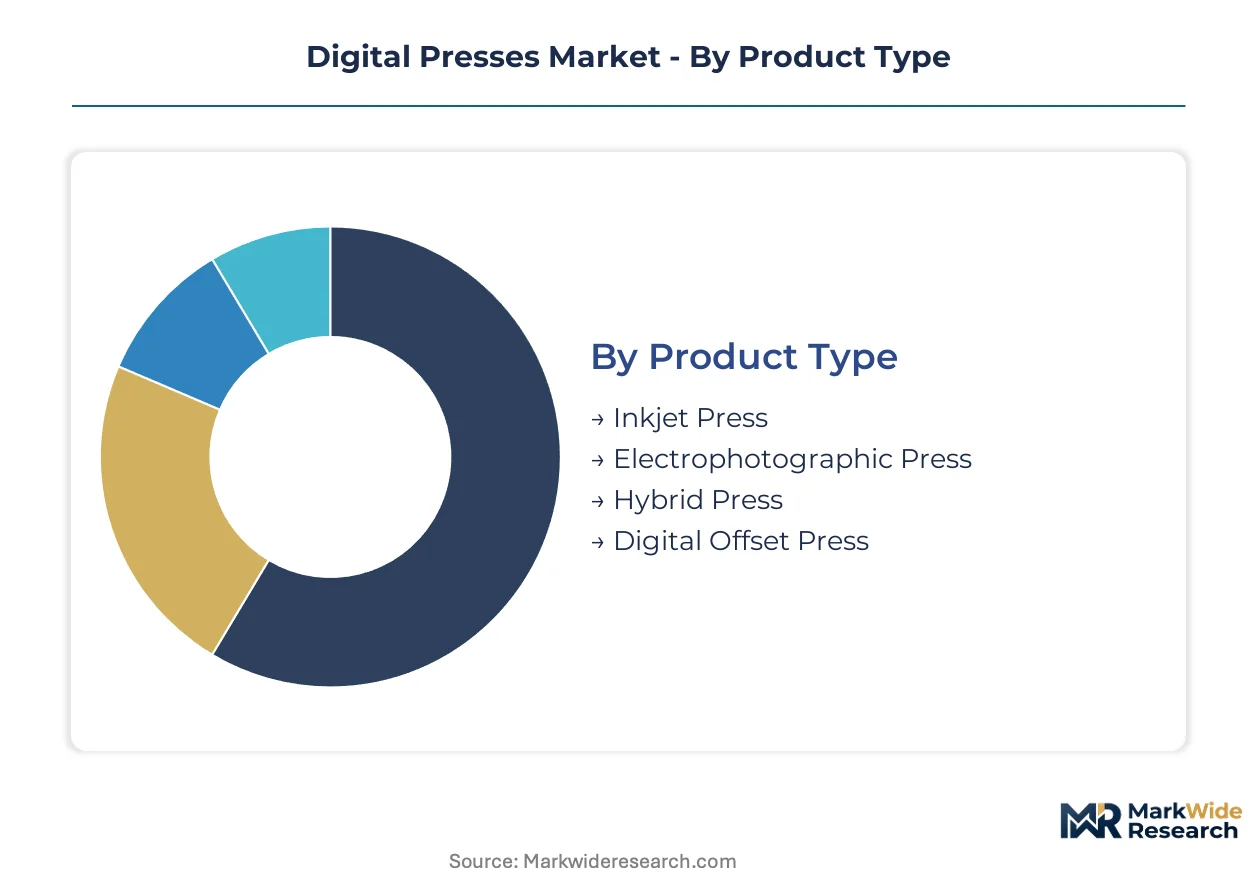
Digital press procurement decisions split sharply across substrate requirements, regulatory exposure, and run-length economics. Each segmentation dimension reveals distinct vendor concentration patterns and technology migration timelines that reshape competitive positioning.
Product Type:
Cost tier alignment determines capital allocation cycles and lifetime operating economics for converters and commercial print houses.
- Inkjet Press:Single-pass architectures with fixed printhead arrays transfer aqueous or UV-curable inks directly onto paper, board, or film substrates at speeds exceeding 150 meters per minute. Folding carton converters in Germany and the United States deploy these systems to collapse breakeven thresholds for medium-run pharmaceutical packaging. FDA food-contact notification requirements favor vendors with captive ink formulation capabilities.
- Electrophotographic Press:Laser-based imaging engines fuse dry toner onto substrates through heat and pressure, delivering institutional-grade consistency for transactional documents and direct mail. Toner-based workflows retain entrenched positions in Japanese and US financial services print operations where image quality standards resist migration. Speed upgrade programs defend installed bases against inkjet displacement.
- Hybrid Press:Configurations marrying flexo print units with digital inkjet bars preserve existing substrate handling infrastructure while adding variable data capability. Italian and Spanish corrugated converters retrofit legacy lines to meet lot-level traceability mandates without full press replacement.
- Digital Offset Press:Liquid toner or waterless offset imaging systems bridge conventional offset quality with digital job changeover speed. Narrow adoption concentrates in high-end commercial print segments where sheet-fed formats and specialty substrates dominate.
Inkjet Press commands the established base. The steepest expansion runs through Hybrid Press.
End User:
Customer type segmentation maps organizational scale, technical sophistication, and procurement leverage against vendor pricing architectures.
- Commercial Printers:Independent print service providers operate multi-technology floors serving brand owners, agencies, and corporate marketing departments. Short-run personalization demand concentrates in Germany, the United States, and Japan where legacy offset lines undergo retrofit with variable data modules.
- Packaging Companies:Folding carton, corrugated, and flexible film converters face serialized coding mandates from pharmaceutical and food brand owners. EU REACH substance restrictions on photoinitiators accelerate replacement timelines for UV inkjet lines in Poland and the Czech Republic.
- In-plant Printers:Captive print operations within corporations, government agencies, and healthcare systems optimize for document security and turnaround speed rather than unit cost minimization.
- Publishers:Book and periodical producers balance inventory risk against print-on-demand capability, with educational and academic segments showing strongest digital migration.
Commercial Printers anchor volume concentration. Packaging Companies are climbing the fastest.
Application:
End-use destination shapes substrate handling requirements, regulatory compliance burden, and margin capture potential.
- Packaging:Folding carton and corrugated production demands food-contact-safe ink chemistries, lot-level traceability, and compatibility with recycled fiber substrates. Water-based inkjet penetration accelerates in the United Kingdom to simplify FDA and EU regulatory compliance.
- Labels:Narrow-web UV inkjet configurations dominate adhesive label production where plate elimination and versioning capability justify premium equipment cost. Fujifilm retains strong position through reformulation programs addressing ECHA photoinitiator restrictions.
- Commercial Print:Marketing collateral, direct mail, and transactional documents drive electrophotographic toner demand where institutional quality standards persist.
- Publishing:Book production migration to digital remains uneven, with academic and short-run segments leading while mass-market titles retain offset economics.
Labels command technology leadership. Packaging is gaining share fastest.
Technology:
Functional capability layer determines workflow integration complexity and competitive differentiation for equipment vendors.
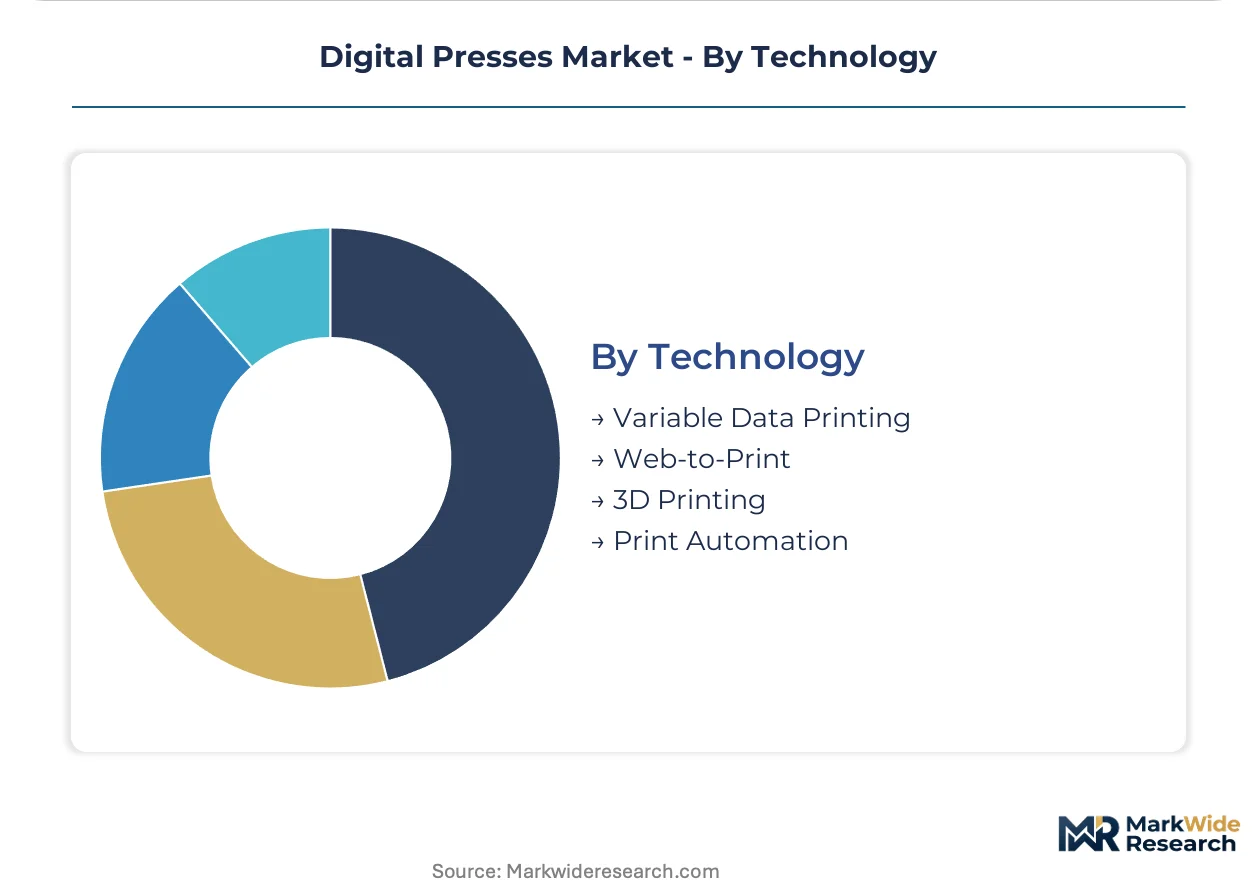
- Variable Data Printing:Real-time image modification enables serialization, personalization, and versioning without stopping production. Pharmaceutical brand owners in Germany and Japan mandate this capability for regulatory compliance.
- Web-to-Print:Browser-based job submission and automated prepress routing reduce manual touchpoints in commercial print workflows. Adoption concentrates in US and Japanese print houses unbundling hardware from software procurement.
- Print Automation:Predictive maintenance architectures and color calibration protocols compress downtime and waste in high-volume operations.
- 3D Printing:Additive manufacturing for packaging prototypes and short-run tooling remains peripheral to mainstream digital press markets.
Variable Data Printing anchors functional requirements. Web-to-Print is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in digital press equipment favor machinery-producing economies, with Germany and Japan running consistent surpluses in high-end inkjet systems while the United States remains a net importer of narrow-web label configurations.
United States
FDA food-contact notification requirements drive recurring equipment qualification cycles among folding carton converters. OSHA lockout-tagout standards govern factory floor layouts for commercial print facilities in Illinois and Wisconsin. Chicago-area packaging clusters accelerate adoption of single-pass inkjet arrays to serve pharmaceutical brand owners demanding lot-level traceability.
Germany
Short-run personalization demand concentrates among commercial printers retrofitting legacy offset lines with variable data modules. EU REACH substance restrictions on photoinitiators accelerate replacement timelines for UV inkjet installations. The Baden-Württemberg industrial corridor hosts converter operations migrating toward water-based formulations to simplify regulatory compliance.
Japan
Serialized packaging mandates from pharmaceutical and food brand owners pull variable data printing capability into corrugated production environments. METI industrial standards shape equipment certification protocols for narrow-web label presses. Osaka-Kansai manufacturing clusters retain entrenched positions in electrophotographic toner workflows for financial services print operations.
United Kingdom
Food packaging applications migrate from UV-cured to water-based inkjet formulations to reduce migration risk and streamline dual FDA-EU compliance. Extended producer responsibility frameworks impose emerging collection obligations on printing equipment and consumables. Greater Manchester converter operations lead adoption of hybrid press configurations preserving existing substrate handling infrastructure.
Italy
Corrugated converters retrofit existing flexo lines with inkjet print bars to meet lot-level traceability mandates without full press replacement. ECHA reformulation deadlines compress procurement timelines for qualified chemistries ahead of sunset dates. The Emilia-Romagna packaging belt concentrates hybrid system installations serving pan-European pharmaceutical distribution networks.
Digital Presses Market Competitive Landscape
On the supply side, the industry is consolidating around captive ink chemistry capabilities and predictive maintenance architectures. Equipment vendors compete through chemistry-press integration that locks converters into recurring supply revenue streams. Three strategic archetypes dominate: integrated imaging conglomerates with formulation capabilities, specialized inkjet array fabricators, and hybrid system integrators marrying flexo handling with digital print bars. Dominant competitive moves include backward integration into ink constituent supply and geographic expansion through distributor qualification programs.
Among Japanese imaging conglomerates, Fujifilm Corporation and Seiko Epson Corporation exemplify the chemistry-captive archetype, while Hewlett-Packard Development Company, L.P. anchors the integrated hardware-software-services tier. These three occupy positions defined by their control over formulation roadmaps and equipment qualification protocols rather than scale alone. Their competitive posture rests on recurring revenue architectures that resist unbundling pressures from brand procurement teams.
| Leading Market Players |
|---|
| Hewlett-Packard Development Company, L.P. |
| Canon Inc. |
| Ricoh Company, Ltd. |
| Xerox Corporation |
| Konica Minolta Inc. |
| Fujifilm Corporation |
| Seiko Epson Corporation |
| Mimaki Engineering Co., Ltd. |
| Brother Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's escalating container rates compress margins for inkjet printhead assemblies moving from German fabrication facilities to US Midwest converter operations, amplifying price differentiation between vendors with captive chemistry capabilities and those sourcing through third-party distributors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade positioning for FDA food-contact notification compliance, while economy segments serve non-regulated commercial print workflows. Price differentiation hinges on ink formulation lock-in and predictive maintenance bundling. Cost compression in mid-tier electrophotographic lines is intensifying because brand procurement teams unbundle hardware from consumable supply agreements. Packaging converters in Poland and the Czech Republic exhibit highest price sensitivity due to ECHA-driven replacement urgency, whereas Japanese financial services print houses show lowest sensitivity given institutional quality requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for piezoelectric printhead components and UV photoinitiator precursors. Manufacturing concentrates in Japan, Germany, and South Korea for high-resolution inkjet arrays, while China anchors consumable formulation at scale. Raw material dependencies draw from specialty chemical feedstocks, semiconductor-grade silicon substrates, and precision-machined nozzle plates. Single-source vulnerability runs through photoinitiator suppliers facing ECHA sunset deadlines. Distribution runs through authorized dealer networks with direct OEM relationships for press qualification and installation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital presses market functions as a defensive-moat arena where regulatory entrenchment creates durable switching costs. FDA and EU REACH compliance protocols lock converters into qualified vendor relationships that resist price-based displacement.
For Market Incumbents: Build captive ink chemistry moats through backward integration into photoinitiator supply and predictive maintenance software ecosystems. Defend against unbundling pressure from brand procurement teams by embedding spectrophotometric color calibration into subscription service tiers. Add capacity in Baden-Württemberg to serve EU REACH-driven replacement cycles.
For New Entrants and Emerging Players: Pursue white-space opportunities in water-based inkjet formulations for UK food packaging applications where regulatory simplification creates adoption pull. Target hybrid press retrofits in Italy and Spain where converters seek versioning capability without full line replacement. Lead with web-to-print workflow integration as the go-to-market angle for commercial print houses resisting digital job ticketing transitions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates seeking to monetize non-core digital press divisions. Long-term viability centers on chemistry-captive revenue architectures rather than hardware shipment cycles. Monitor ECHA substance evaluation timelines as the inflection signal for qualified chemistry scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Constituents | Captive photoinitiator supply secures ECHA compliance ahead of sunset deadlines for narrow-web label presses. |
| Predictive Maintenance Platform Launch | AI-driven downtime reduction strengthens recurring revenue attachment rates among folding carton converters. |
| Hybrid Press Retrofit Partnership | Flexo-inkjet integration preserves Italian converter capital while adding pharmaceutical serialization capability. |
| Water-Based Formulation Requalification | FDA-EU dual compliance simplification accelerates UK food packaging migration from UV-cured systems. |
| Geographic Distributor Qualification | Certified installation networks in Poland and Czech Republic capture ECHA-driven replacement demand. |
Research Methodology
The analysis maps inkjet press architectures, electrophotographic toner systems, hybrid configurations, and digital offset platforms, each validated through converter procurement directors, commercial print house operations managers, ink formulation chemists, and OEM field service engineers. Primary intelligence combines structured interviews with secondary validation against SEC 10-K filings, EU ECHA substance registration databases, FDA food-contact notification records, and Japanese METI equipment certification protocols. Bottom-up segmentation triangulates against top-down market sizing across technology tiers and end-use applications.
Forecasts assume stable regulatory enforcement intensity across the projection horizon, with ECHA sunset dates and FDA notification requirements held at current trajectory. Segmentation dimensions model press type, end-user category, substrate application, and geographic regulatory cluster. CAGRs derive from equipment replacement cycle analysis, consumable attach rate trends, and penetration assumptions for variable data printing in pharmaceutical packaging. Industry-specific inputs include photoinitiator requalification timelines and hybrid retrofit adoption curves in Southern European corrugated markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese inkjet array fabricators or water-based formulation specialists would shift outcomes through accelerated price erosion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Digital Paper System Market
Printing Technology
RFID Printer Market
Printing Technology
Managed Print Services Market
Printing Technology
Retail Printers Market
Printing Technology
Print on Demand Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
ID Card Printers Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Printing Machinery Market
Printing Technology
Cloud Print Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Digital Printing Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Print Equipment Market
Printing Technology
Card Printer Ribbons Market