
 Digital Paper System Market | 2026-2036
Digital Paper System Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Paper System Market Outlook
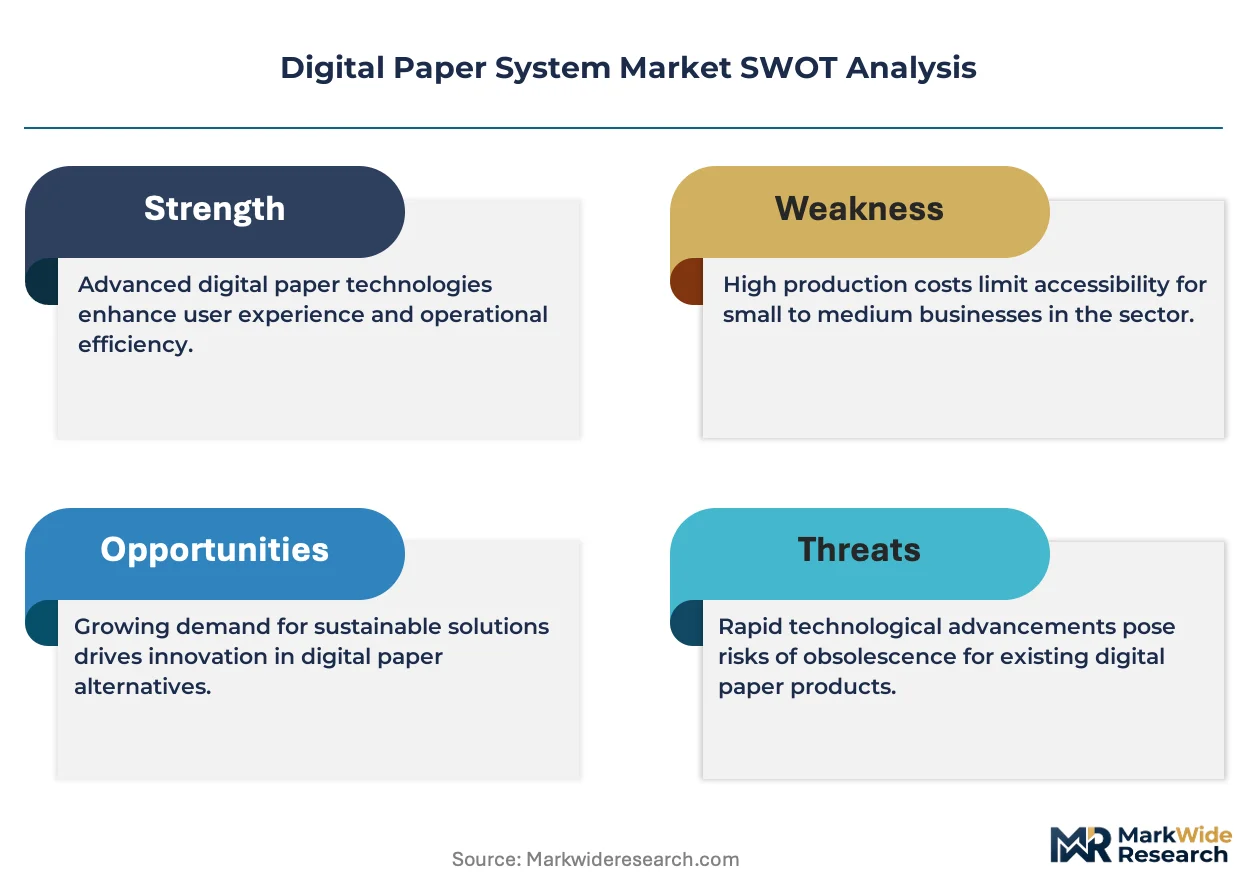
High-resolution E Ink Carta 1200 and 1300 specifications is reorganizing the Digital Paper System Market by setting new baselines for contrast ratio and refresh speed. E Ink Holdings Inc. dominates electrophoretic display supply through captive manufacturing in Taiwan. Sony Corporation leverages its DPT series to anchor professional document workflows in legal and academic institutions. Remarkable AS specializes in minimalist hardware-software integration for distraction-free writing.
A digital paper system combines reflective display technology, typically electrophoretic or cholesteric LCD, with pressure-sensitive digitizer layers to simulate ink-on-paper writing without backlight emission. These devices operate at sub-watt power draws and sustain weeks of battery life, serving professionals who require extensive annotation, sketching, or form-filling away from power sources. E-ink tablet configurations currently lead commercial shipments due to their balance of readability and portability, while cloud-based technology integration is expanding fastest as enterprise IT departments demand seamless document synchronization across endpoints. Smart notepad variants occupy the premium tier where stylus latency below 30 milliseconds justifies higher hardware costs.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU Radio Equipment Directive, and JIS energy efficiency benchmarks in Japan collectively shape product certification timelines and regional launch sequencing. REACH compliance for electronic ink formulations and RoHS restrictions on hazardous substances in display substrates add material sourcing constraints that favor established chemical suppliers. Stakeholders must monitor how ECHA substance-of-very-high-concern listings for specific polymer components could force display stack redesigns and supplier qualification cycles.
Market Dynamics
E Ink Carta 1300 specifications are compressing refresh latency benchmarks and forcing incumbent manufacturers to redesign digitizer stacks around sub-30 millisecond stylus response thresholds.
Growth Catalysts
- ISO 9241-307 readability standards:Japan's adoption of stricter contrast ratio mandates for classroom procurement is pulling E Ink Holdings Inc. display volumes into educational institutions.
- Hybrid workspace normalization:Enterprise IT departments in Germany are consolidating meeting room hardware around single-device annotation and presentation workflows.
- Electrophoretic film manufacturing scale-up:Taiwan's display substrate cluster is reducing module cost curves through captive chemical synthesis of microcapsule suspensions.
Market Restraints
- Indium tin oxide supply concentration:Digitizer layer production depends on sputtering targets sourced predominantly from East Asian refiners, creating input cost volatility.
- Cholesteric LCD technical ceiling:Bistable cholesteric displays suffer from slower grayscale transitions that limit video annotation use cases.
- REACH SVHC listing friction:ECHA substance-of-very-high-concern designations for specific polymer substrates are extending supplier qualification cycles by 8-14 months.
Strategic Opportunities
- Healthcare form digitization:Japan's METI push for paperless clinical trials creates demand for stylus-enabled patient consent workflows.
- Cloud-native synchronization:Enterprise document management APIs are enabling real-time annotation streaming across distributed legal teams.
- South Korea's Gwangju electronics cluster:Underutilized LCD fabrication lines offer conversion potential for cholesteric display pilot production.
Industry Challenges
- Electromagnetic compatibility certification:FCC Part 15 Class B testing for stylus digitizers adds 4-6 months to US market entry timelines.
- Firmware integration complexity:Legacy enterprise content management systems require custom middleware development for pen stroke synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Paper System Market |
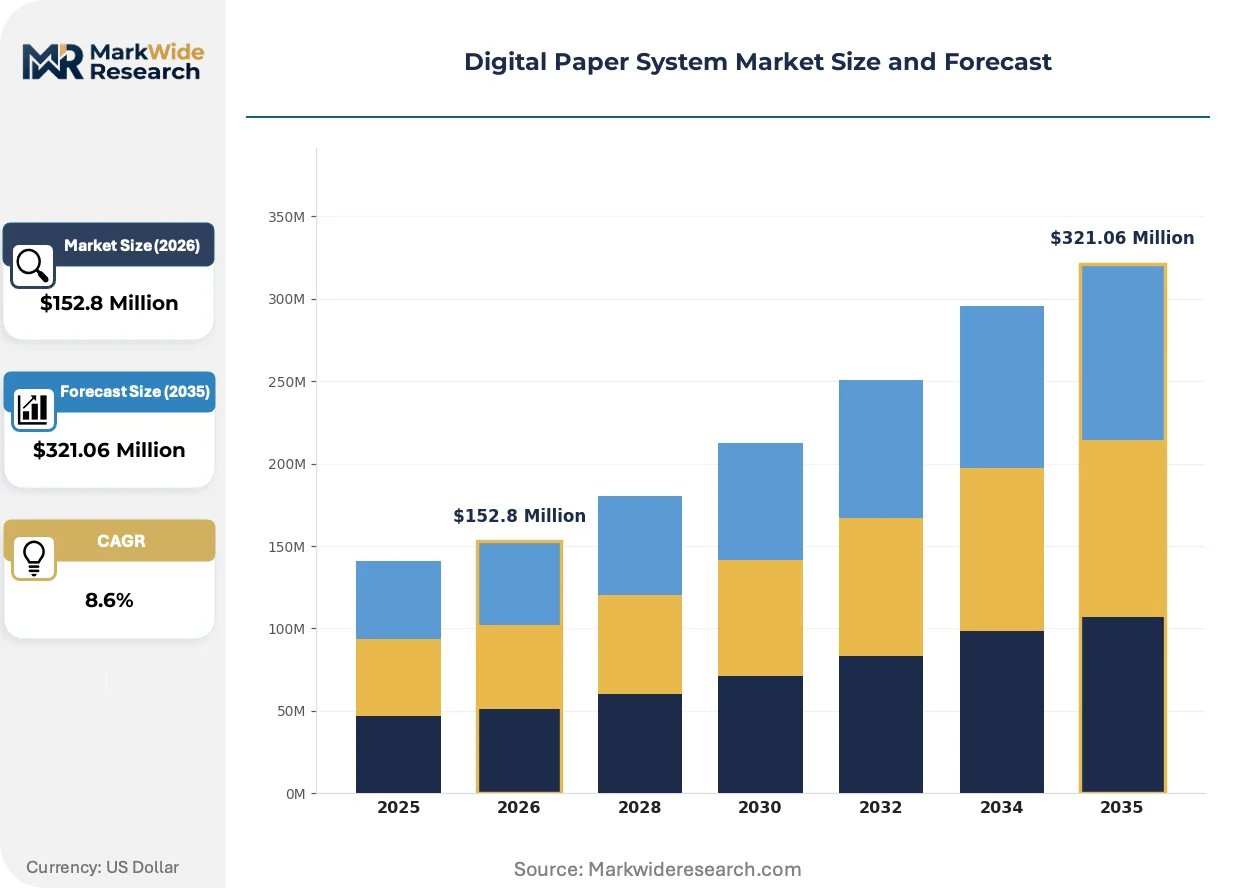
| Market Size in 2026 | $152.8 Million |
| Market Size in 2035 | $321.06 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Notepad, E-ink Tablet, Digital Flip Chart, Virtual Whiteboard Technology: Touchscreen, Inkless Technology, Voice Recognition, Cloud-Based End User: Education, Corporate, Creative Professionals, Consumer Application: Note-taking, Sketching, Document Management, Collaboration |
| Companies Covered | Sony Corporation, E Ink Holdings Inc., Samsung Electronics Co., Ltd., Wacom Co., Ltd., Apple Inc., Microsoft Corporation, LG Display Co., Ltd., Remarkable AS, Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Paper System Market Strategic Shifts
Active stylus latency reduction and cloud-native document pipelines are redefining professional user expectations across legal, academic, and clinical verticals.
Capacitive active pen technology with 4,096 pressure levels and tilt recognition is supplanting resistive digitizer layers in premium digital paper systems. Legal practitioners in German commercial courts are adopting these devices for real-time markup of case files during hearings. The shift is compressing hardware refresh cycles from 5-year replacement windows toward 3-year enterprise lease structures.
Japan's PMDA guidance on electronic source documentation for clinical trials is mandating audit-trail capabilities in stylus input systems. Device manufacturers must implement cryptographic signature binding between pen strokes and timestamped document versions. Pharmaceutical contract research organizations in Osaka and Tokyo are driving specification requirements that cascade into broader enterprise procurement standards.
Subscription-based hardware provisioning with bundled cloud storage is displacing outright purchase models in North American law firms. Managed service providers are inserting themselves between manufacturers and end-users, capturing margin through fleet management and helpdesk support. This channel restructuring is most visible among Am Law 200 firms consolidating vendor relationships under single-source IT procurement frameworks.
Digital Paper System Market Segmentation
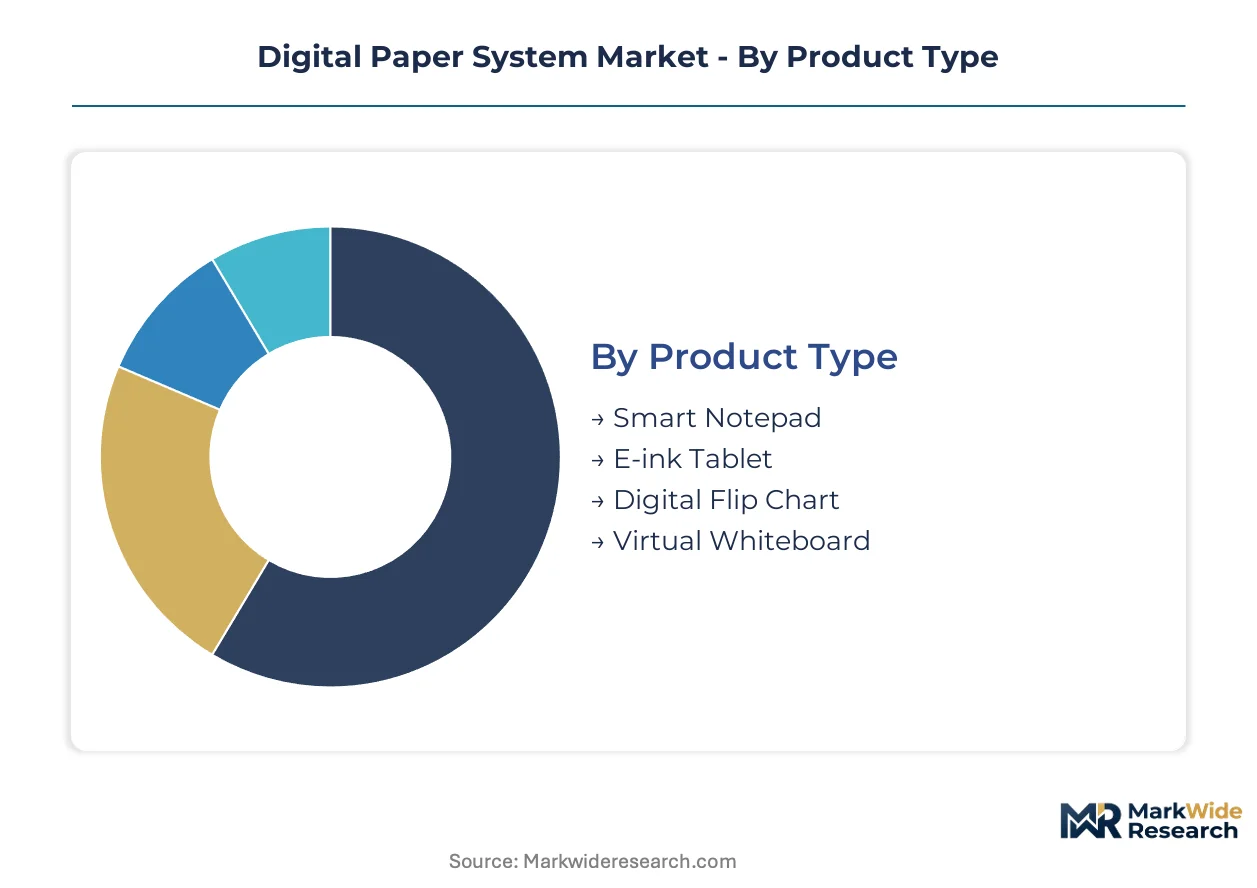
Digital paper systems fragment across four dimensions that reshape procurement patterns and margin capture. Product type determines hardware cost structures and replacement cadence. Technology choices dictate integration complexity with enterprise IT stacks. End-user concentration in Japan and Germany pulls specification requirements toward E Ink readability standards and GDPR-compliant cloud synchronization.
Product Type:
Premium stylus latency specifications concentrate margin pools in professional-grade hardware, while mass-market configurations compete on battery endurance and display size.
- Smart Notepad:Combines electrophoretic display layers with pressure-sensitive digitizers optimized for handwriting recognition below 30-millisecond latency. Legal practitioners in German commercial courts drive procurement volumes for real-time case file markup during hearings, compressing enterprise refresh cycles toward three-year replacement windows.
- E-ink Tablet:Portable form factors with reflective display technology sustaining weeks of battery life on sub-watt power draws. Corporate IT departments in Japan consolidate meeting room hardware around single-device annotation workflows, pulling shipments toward ISO 9241-307 readability compliance.
- Digital Flip Chart:Large-format displays for collaborative brainstorming sessions with cloud-native document pipeline integration.
- Virtual Whiteboard:Wall-mounted systems enabling distributed team synchronization through real-time stroke streaming across endpoints.
The dominant share belongs to E-ink Tablet, while Smart Notepad is closing the gap fastest.
Technology:
Enterprise security requirements and clinical audit-trail mandates are reallocating R&D spend toward cryptographic signature binding and cloud synchronization architectures.
- Cloud-Based:Real-time document synchronization across distributed endpoints through enterprise content management APIs. North American law firms adopting subscription-based hardware provisioning with bundled storage are expanding this segment most quickly, with managed service providers capturing margin through fleet management.
- Touchscreen:Capacitive active pen technology with 4,096 pressure levels and tilt recognition supplanting resistive digitizer layers in premium configurations. Pharmaceutical contract research organizations in Osaka and Tokyo drive specification requirements that cascade into broader procurement standards.
- Inkless Technology:Cholesteric LCD and electrophoretic film manufacturing without traditional ink formulations, constrained by slower grayscale transitions.
- Voice Recognition:Audio input layering for multimodal documentation in clinical and legal settings requiring hands-free operation.
Cloud-Based commands the technology mix by enterprise attach rate, though Touchscreen is gaining ground through stylus precision improvements.
End User:
Procurement authority concentration determines pricing power, with centralized IT departments extracting volume discounts unavailable to fragmented individual purchasers.
- Corporate:Enterprise IT departments in Germany and Japan standardizing meeting room hardware and hybrid workspace tooling. Hybrid workspace normalization is consolidating vendor relationships under single-source procurement frameworks, with FCC Part 15 Class B testing and CE marking requirements shaping regional launch sequencing.
- Education:Classroom procurement in Japan adopting stricter contrast ratio mandates under ISO 9241-307 standards, pulling E Ink display volumes into institutional deployments.
- Creative Professionals:Individual practitioners prioritizing minimalist hardware-software integration for distraction-free sketching and concept development.
- Consumer:Price-sensitive purchasers focused on reading and casual annotation rather than professional document workflows.
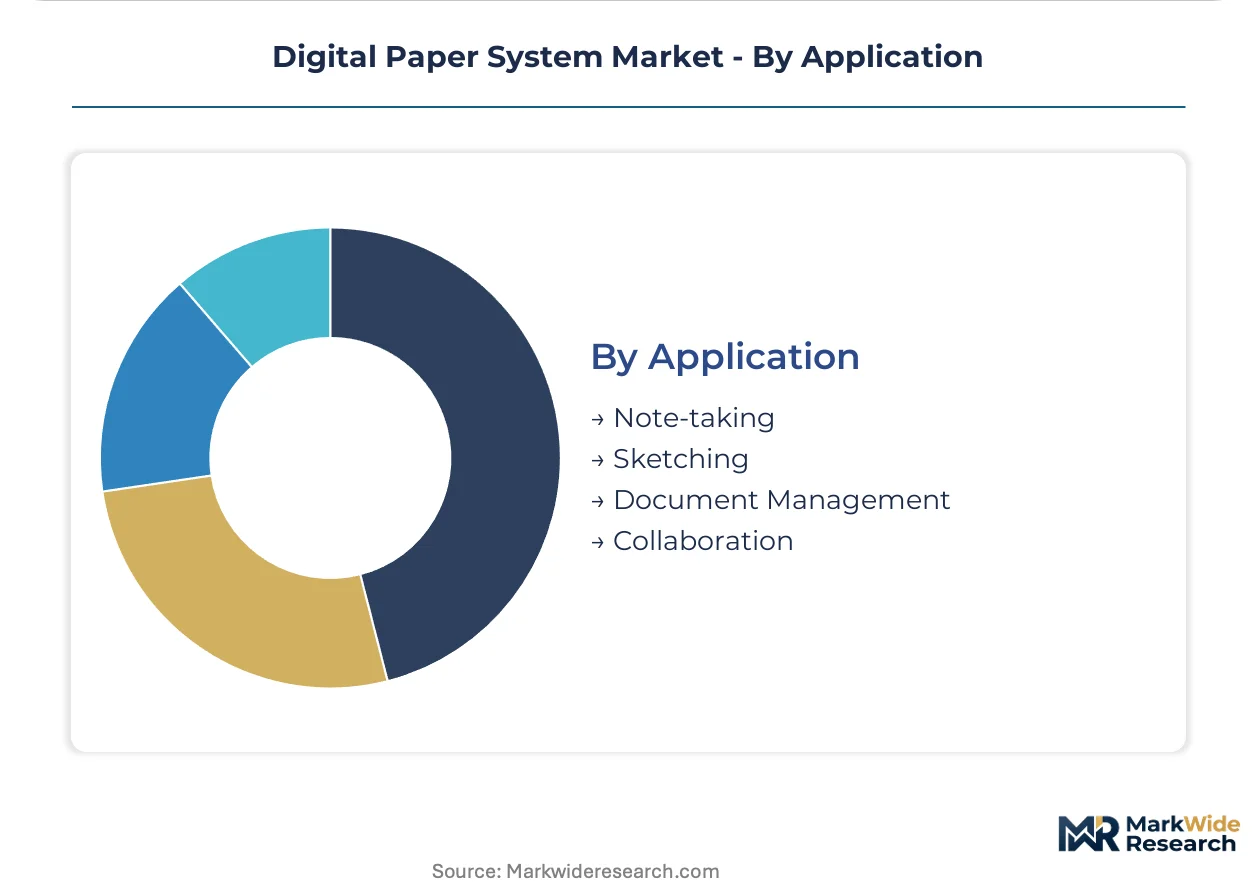
Corporate end users anchor volume commitments, while Education is climbing the fastest on institutional procurement reform.
Application:
Workflow integration depth separates sticky enterprise deployments from disposable consumer use cases, with document management and collaboration commanding recurring revenue streams.
- Document Management:Enterprise content management system integration requiring custom middleware development for pen stroke synchronization. Legacy ECM compatibility constraints extend implementation timelines but lock in long-term contract value.
- Collaboration:Real-time annotation streaming across distributed legal and clinical teams through cloud-native synchronization protocols. Japan's METI push for paperless clinical trials creates demand for stylus-enabled patient consent workflows with cryptographic audit trails.
- Note-taking:Individual capture and organization of handwritten content with optical character recognition indexing.
- Sketching:Creative visualization workflows prioritizing pressure sensitivity and tilt recognition for natural drawing dynamics.
Document Management holds the application share lead, while Collaboration is expanding most quickly on distributed workforce normalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in display substrates and digitizer components concentrate procurement leverage in East Asian manufacturing clusters, while end-user demand pulls finished systems toward professional markets in Germany and Japan. Taiwan and South Korea supply electrophoretic film and indium tin oxide targets to assembly operations across multiple continents. Regulatory fragmentation around electromagnetic compatibility and data protection is forcing staggered product launches that favor established multinationals with compliance infrastructure.
Japan
METI's paperless clinical trial mandates and PMDA electronic source documentation guidance are institutionalizing cryptographic audit-trail requirements for stylus input systems. JIS energy efficiency benchmarks shape classroom procurement specifications, pulling E Ink display volumes into educational deployments. Tokyo and Osaka pharmaceutical contract research organizations drive enterprise-grade feature specifications that cascade into broader corporate procurement standards.
Germany
Enterprise IT departments in Baden-Württemberg and Bavaria are consolidating meeting room hardware around single-device annotation workflows under hybrid workspace normalization. CE marking requirements under EU Radio Equipment Directive and GDPR-compliant cloud synchronization mandates extend product certification timelines. Stuttgart's automotive engineering clusters and Munich's legal services density create concentrated demand for sub-30 millisecond stylus latency specifications.
South Korea
Gwangju's underutilized LCD fabrication lines offer conversion potential for cholesteric display pilot production, while Seoul Capital Area electronics conglomerates integrate digital paper systems into broader smart office portfolios. MFDS medical device regulations intersect with clinical documentation use cases, creating compliance overlap with Japanese PMDA standards. Busan-Ulsan port infrastructure supports component import for domestic assembly and re-export to Southeast Asian markets.
United States
FCC Part 15 Class B electromagnetic emissions testing for stylus digitizers adds 4-6 months to market entry timelines, favoring incumbents with established certification pipelines. HIPAA audit-trail requirements in healthcare and SEC document retention rules in financial services are segmenting demand toward cryptographically bound pen stroke systems. California's technology procurement offices and New York Metro legal services concentration anchor professional-grade volume commitments.
Taiwan
E Ink Holdings Inc.'s captive electrophoretic film manufacturing in Hsinchu Science Park reduces module cost curves through in-house chemical synthesis of microcapsule suspensions. Export-oriented supply relationships with Japanese and German finished goods assemblers concentrate value capture upstream in the display stack. Taoyuan's display substrate cluster faces REACH SVHC listing friction for polymer components that could force supplier qualification cycle extensions.
Digital Paper System Market Competitive Environment
Listed leaders compete with private specialists across hardware-software integration depth, creating a tiered structure where scale advantages in display supply clash with focused user experience optimization. Public electronics conglomerates leverage semiconductor and panel manufacturing breadth against venture-backed private entities prioritizing minimalist design philosophy. Three archetypes dominate: captive display technology owners, enterprise workflow integrators, and distraction-free productivity specialists. Competitive moves center on electrophoretic film supply securing through backward integration and cloud-native synchronization API partnerships with enterprise content management vendors.
Within the captive technology tier, E Ink Holdings Inc. and LG Display Co., Ltd. exemplify substrate-level control strategies that upstream competitors must navigate. Among private specialists, Remarkable AS occupies a position representing hardware-software coherence as a competitive anchor. Sony Corporation sits within the enterprise workflow integrator archetype, leveraging professional document management heritage. Samsung Electronics Co., Ltd. represents the diversified electronics conglomerate model spanning multiple display technologies and end-use segments.
| Leading Market Players |
|---|
| Sony Corporation |
| E Ink Holdings Inc. |
| Samsung Electronics Co., Ltd. |
| Wacom Co., Ltd. |
| Apple Inc. |
| Microsoft Corporation |
| LG Display Co., Ltd. |
| Remarkable AS |
| Xerox Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for electrophoretic film modules lock in supply access for Japanese and German device assemblers while compressing price visibility across the analysis window. These arrangements tether procurement costs to Taiwan's chemical synthesis capacity, creating asymmetric leverage for E Ink Holdings Inc. against downstream hardware integrators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium configurations with sub-30 millisecond stylus latency command price separation based on ISO 9241-307 certification grade and cryptographic audit-trail compliance. Cost compression in standard-tier E-ink tablets intensifies as South Korean LCD conversion capacity ramps. Education procurement committees in Japan exhibit highest price sensitivity, while pharmaceutical contract research organizations show lowest elasticity due to regulatory mandate alignment.
Supply Chain Analysis
Inventory buffers for indium tin oxide sputtering targets stretch lead times across digitizer layer production. Taiwan, South Korea, and Japan concentrate upstream electrophoretic film and display substrate supply. Module assembly draws from microcapsule suspensions, pressure-sensitive digitizer stacks, and polymer substrate films. Single-source vulnerability around E Ink Holdings Inc.'s captive manufacturing in Hsinchu Science Park creates concentration risk. Distribution runs through enterprise IT procurement frameworks and managed service provider channels in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from cyclical trough as hybrid workspace normalization drives enterprise hardware refresh cycles. Corporate IT consolidation around single-vendor meeting room ecosystems provides demand floor stabilization.
For Market Incumbents: Shield proprietary electrophoretic film supply through backward integration into microcapsule chemical synthesis. Cement enterprise workflow lock-in by deepening cloud-native synchronization API partnerships with document management vendors. The threat of cholesteric LCD technical alternatives from South Korean pilot lines demands defensive patent portfolio reinforcement in bistable display architectures. For New Entrants and Emerging Players: Differentiate on healthcare form-digitization specialization targeting Japan's METI paperless clinical trial mandates. White-space exists in mid-tier smart notepad configurations for European legal services firms seeking GDPR-compliant domestic cloud hosting. Go-to-market should route through managed service providers capturing Am Law 200 consolidation windows rather than direct hardware sales. For Investors and Strategic Acquirers: Capital is best deployed toward private specialists with hardware-software coherence and established stylus latency specifications below 30 milliseconds. Long-term viability hinges on cryptographic signature binding capabilities meeting evolving PMDA and FDA electronic source documentation guidance. The signal to watch is ECHA substance-of-very-high-concern listing velocity for polymer substrates, which would force display stack redesigns and supplier qualification cycle extensions favoring incumbents with compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcapsule Synthesis | E Ink Holdings Inc.'s captive Taiwan manufacturing secures cost curve positioning against module competitors. |
| Cryptographic Audit-Trail Certification | Japan's PMDA electronic source documentation guidance mandates timestamped pen stroke binding for clinical trial devices. |
| Cloud-Native Synchronization API Partnership | Enterprise content management vendor integrations enable real-time annotation streaming across distributed legal teams. |
| Cholesteric Display Pilot Production | South Korea's Gwangju underutilized LCD lines offer conversion potential for bistable alternative supply diversification. |
| Managed Service Provider Channel Expansion | North American law firm subscription provisioning captures recurring revenue through fleet management and helpdesk support bundling. |
Study Parameters
A standing panel of enterprise IT procurement officers, pharmaceutical contract research organization document managers, E Ink module supply chain directors, legal technology consultants, and classroom technology coordinators provided ongoing calibration across the study period. Primary interview findings triangulated against secondary sources including FCC Part 15 Class B certification filings, METI energy efficiency benchmark disclosures, ECHA substance-of-very-high-concern registry updates, and enterprise hardware procurement database extracts. Bottom-up shipment estimates from display module suppliers reconciled with top-down enterprise IT spend surveys.
Consistency checks validated volume and value outputs against external benchmarks including electrophoretic film manufacturing capacity disclosures and hybrid workspace hardware adoption surveys. The analytical framework modeled demand across product type, technology architecture, end-user concentration, and application workflow depth throughout the projection horizon. CAGRs derived from segment-level growth rate convergence analysis incorporating stylus latency specification upgrade cycles and institutional procurement reform timelines.
Decision-makers should treat outputs as directional under assumptions of sustained hybrid workspace normalization and stable REACH polymer substrate regulatory status; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Commercial Printer Market
Printing Technology
Photo Printing Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Digital Printing Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Large Character Printers Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Card Printers Market
Printing Technology
RFID Printer Market
Printing Technology
Variable Data Printing Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Digital Franking Machine Market