
 South East Asia Warehouse Automation Market | 2026-2036
South East Asia Warehouse Automation Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Warehouse Automation Market Analytics
Modular system bundling is pivoting buyer procurement from standalone equipment purchases toward integrated automation suites spanning hardware, software, and maintenance. Daifuku Co Ltd leverages its regional manufacturing footprint to anchor large-scale distribution center deployments across Thailand and Vietnam. Swisslog Holding AG competes through deep software-hardware integration in cold-chain and pharmaceutical verticals. Dematic sustains technology leadership in high-throughput sortation systems for e-commerce fulfillment.
South East Asia warehouse automation encompasses the mechanized and software-controlled movement, storage, retrieval, and sorting of goods within distribution and production facilities, typically integrating conveyor networks with programmable logic controllers operating at throughputs exceeding 10,000 units per hour. Its primary purpose is to reduce order cycle times and inventory carrying costs while mitigating labor scarcity in densely populated urban logistics zones. Automated Guided Vehicles and Sortation Systems capture disproportionate investment as e-commerce order profiles fragment toward same-day and next-day delivery windows. AI and Machine Learning segments within the technology dimension are expanding fastest, with demand concentrating where predictive maintenance and dynamic slotting algorithms yield measurable labor productivity gains.
Indonesia's Ministry of Industry, Thailand's Board of Investment, and Singapore's Enterprise Singapore collectively shape market access through Industry 4.0 incentives, automation tax allowances, and smart logistics zone certifications. These frameworks condition capital subsidy eligibility on local content thresholds and workforce reskilling commitments, steering vendor partnership strategies. Stakeholders must monitor evolving national data localization requirements for cloud-connected warehouse management systems, as deployment architecture decisions increasingly determine regulatory compliance costs and cross-border operational scalability.
Market Dynamics
Cross-border e-commerce fragmentation is compressing order cycle time requirements across Indonesian, Vietnamese, and Thai fulfillment networks, forcing operators to reconfigure fixed automation assets for variable throughput profiles.
Growth Catalysts
- ASEAN Single Window:Customs modernization protocols accelerate bonded warehouse automation deployments by reducing clearance friction for third-party logistics providers operating across Indonesia, Vietnam, and Thailand.
- Pharmaceutical cold-chain:Temperature-sensitive biologics distribution demands robotic storage and retrieval systems with continuous environmental monitoring, pulling investment into automated freezer infrastructure.
- Greater Jakarta congestion:Urban logistics bottlenecks and driver availability constraints push fulfillment operators toward autonomous mobile robots for last-meter pallet movement within distribution centers.
Market Restraints
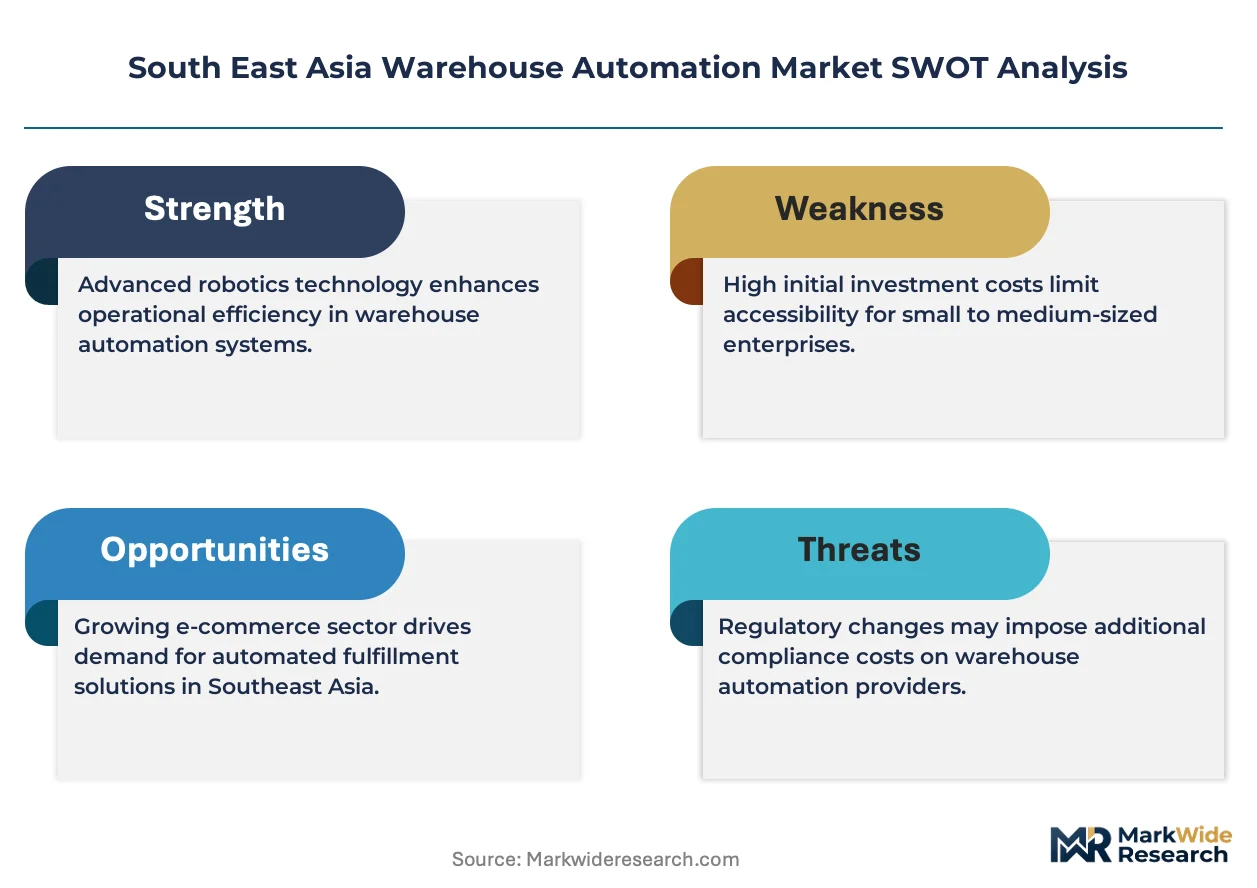
- Steel and aluminum input volatility:Conveyor framework and racking material costs fluctuate with regional commodity pricing, compressing project margin visibility for system integrators.
- Japanese and Korean component concentration:Servo motor and programmable logic controller supply chains cluster in Northeast Asian manufacturing hubs, exposing deployment timelines to shipping lane disruptions.
- Limited local maintenance technician pools:Robotics and automation engineering expertise concentrates in Singapore and Kuala Lumpur, creating service response gaps for Indonesian and Vietnamese installations.
Strategic Opportunities
- Vietnam's northern industrial corridor:Haiphong-Hanoi manufacturing zones remain underpenetrated by large-scale automated distribution centers serving electronics export assembly.
- Predictive maintenance convergence:Machine learning algorithms layered on warehouse management systems enable condition-based servicing of sortation equipment, reducing unplanned downtime.
- Thailand Board of Investment automation incentives:Tax allowances and smart logistics zone certifications subsidize capital expenditure for qualifying Industry 4.0 warehouse upgrades.
Industry Challenges
- Cloud data localization mandates:Indonesian and Vietnamese regulations restrict cross-border data flows for connected warehouse management systems, complicating multi-country operator architectures.
- Legacy WMS integration friction:Proprietary software protocols in existing facilities obstruct seamless communication with new robotic hardware, extending commissioning timelines.
- Workforce reskilling commitments:Government subsidy eligibility conditions require documented training programs for displaced manual handlers, adding administrative overhead to automation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Warehouse Automation Market |
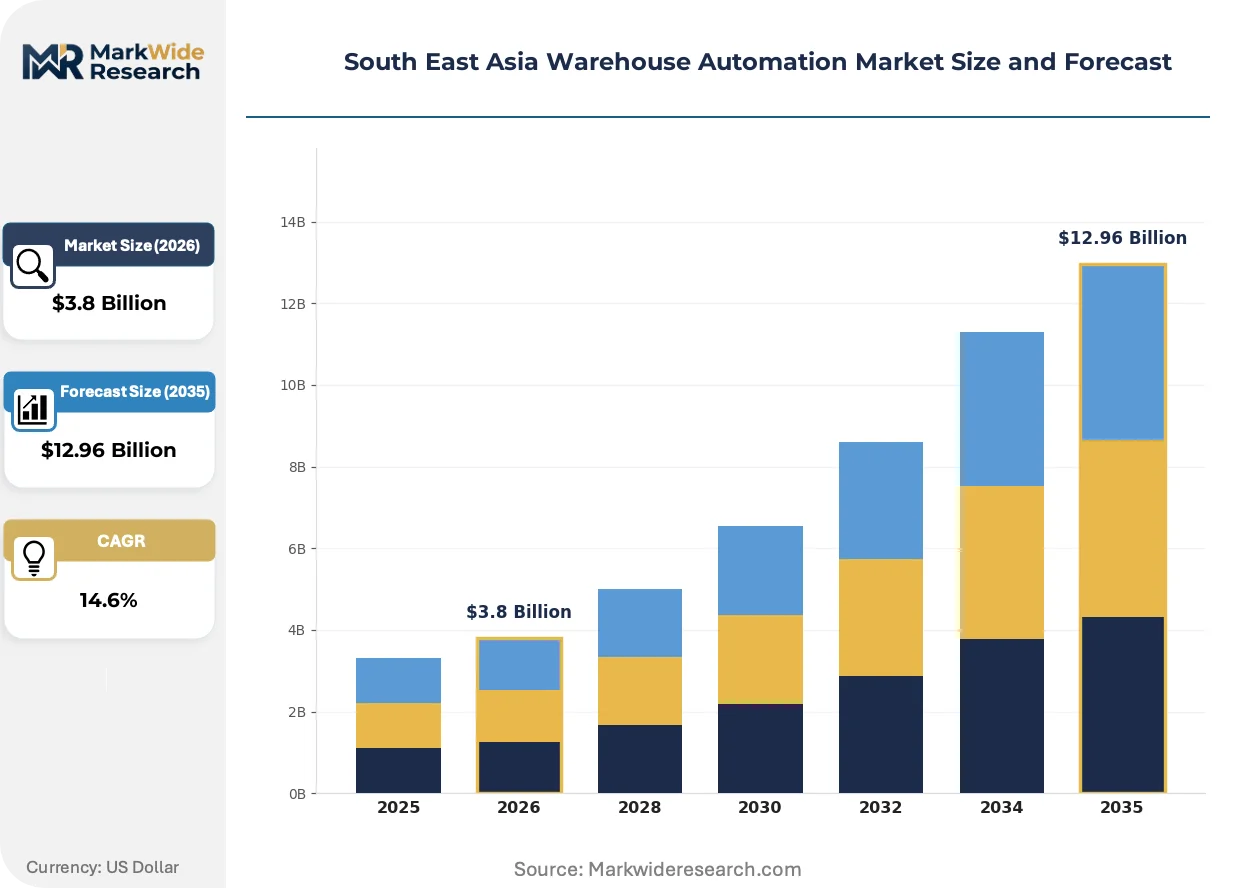
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Conveyor Systems, Sortation Systems Technology: AI, IoT, Machine Learning, Robotics End User: E-Commerce, Manufacturing, Retail, 3PL Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Dematic, Daifuku Co Ltd, Swisslog Holding AG, DF Automation & Robotics Sdn Bhd, ALS Logistic Solutions, PingSpace Sdn Bhd, Omron Corporation, Sun & Siasun Robot Co Ltd, Gen Surv Robotics, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Warehouse Automation Market Evolving Landscape
Artificial intelligence deployment patterns are restructuring how warehouse operators balance fixed infrastructure against variable demand, with software-defined automation displacing hard-coded mechanical systems.
Autonomous mobile robots are decentralizing material flow control within Southeast Asian fulfillment centers. These battery-powered units navigate without fixed conveyor infrastructure, enabling Indonesian e-commerce operators to reconfigure picking zones hourly rather than quarterly. Third-party logistics providers in Bangkok and Ho Chi Minh City are deploying AMR fleets at accelerating velocity, compressing the payback period for flexible automation against traditional fixed sortation.
Indonesia's Ministry of Industry Industry 4.0 certification framework mandates local content thresholds and workforce reskilling commitments for automation tax incentives. This regulatory architecture conditions vendor partnership strategies and steers procurement toward system integrators with established Indonesian manufacturing footprints. Pharmaceutical and cold-chain verticals face the steepest compliance documentation requirements, driving consolidation among certified installation partners.
Same-day delivery promises are fragmenting order profiles and compressing batch sizes for Thai and Vietnamese fulfillment networks. Retailers and marketplace operators are unbundling traditional warehouse management software licenses into modular, usage-based subscriptions that scale with seasonal volume spikes. This procurement pattern shift is most visible in Jakarta's Greater logistics corridor, where congestion costs and labor scarcity accelerate willingness to trade capital ownership for operational flexibility.
South East Asia Warehouse Automation Market Segmentation
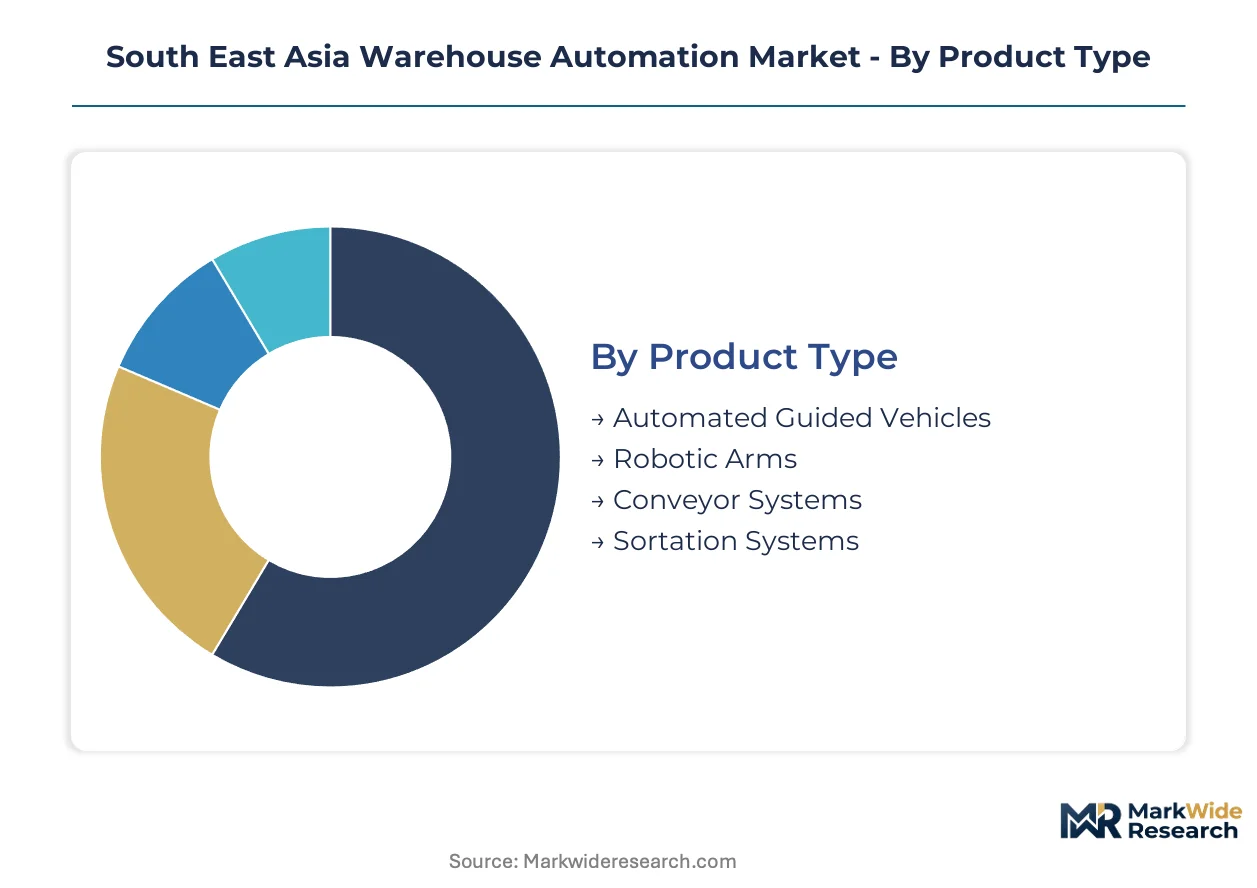
Warehouse automation purchasing in South East Asia fragments across equipment categories, intelligence layers, and operational models. Procurement patterns diverge sharply between multinational third-party logistics providers and domestic e-commerce operators, with each segment demanding distinct integration architectures and service commitments.
Product Type:
The customization-standardization spectrum runs from configurable autonomous fleets to fixed mechanical infrastructure requiring facility-specific engineering.
- Automated Guided Vehicles:Battery-powered units navigate warehouse floors via magnetic tape, laser guidance, or vision systems without fixed path infrastructure. Indonesian e-commerce fulfillment centers in Greater Jakarta deploy AGV fleets for pallet transport to mitigate driver scarcity and congestion-induced delays.
- Sortation Systems:High-throughput mechanical diverters process parcels at speeds exceeding 10,000 units per hour through programmable logic controllers. Thai and Vietnamese cross-border e-commerce hubs concentrate investment here to compress order cycle times for same-day delivery commitments.
- Robotic Arms:Articulated manipulators perform pick-and-place operations for individual SKUs in goods-to-person configurations.
- Conveyor Systems:Belt and roller networks form the backbone of fixed automation infrastructure, connecting receiving docks to storage and shipping zones.
Leading the category by volume: Conveyor Systems. Growing fastest: Automated Guided Vehicles.
Technology:
Cost tiering separates foundational connectivity infrastructure from premium intelligence layers commanding implementation premiums.
- Robotics:Hardware platforms integrating servo motors, sensors, and end-effectors for physical manipulation tasks. Thai pharmaceutical cold-chain facilities deploy robotic storage and retrieval for temperature-sensitive biologics requiring continuous environmental monitoring.
- AI:Predictive algorithms optimize slotting, batching, and labor allocation in real-time. Vietnamese electronics export assembly zones adopt AI-driven warehouse management to align inventory positioning with volatile production schedules.
- Machine Learning:Condition-based maintenance models reduce unplanned downtime on sortation equipment through vibration and thermal pattern recognition.
- IoT:Sensor networks enable equipment connectivity and telemetry collection for operational visibility.
Highest deployment maturity: Robotics. Steepest expansion trajectory: AI.
End User:
Application intensity varies from high-velocity e-commerce fulfillment to synchronized manufacturing supply chains.
- E-Commerce:Order fragmentation toward same-day and next-day delivery compresses batch sizes and multiplies SKU touchpoints. Indonesian marketplace operators automate to offset labor availability constraints in Greater Jakarta's dense logistics corridor.
- 3PL:Third-party logistics providers serve multiple retail clients with divergent throughput profiles, requiring flexible automation that reconfigures seasonally. Bonded warehouse automation accelerates under ASEAN Single Window customs modernization protocols.
- Manufacturing:Production facilities integrate warehouse automation with assembly line feeding for just-in-time component delivery.
- Retail:Omnichannel distribution centers combine store replenishment with direct-to-consumer fulfillment.
Dominant demand source: E-Commerce. Gaining share fastest: 3PL.
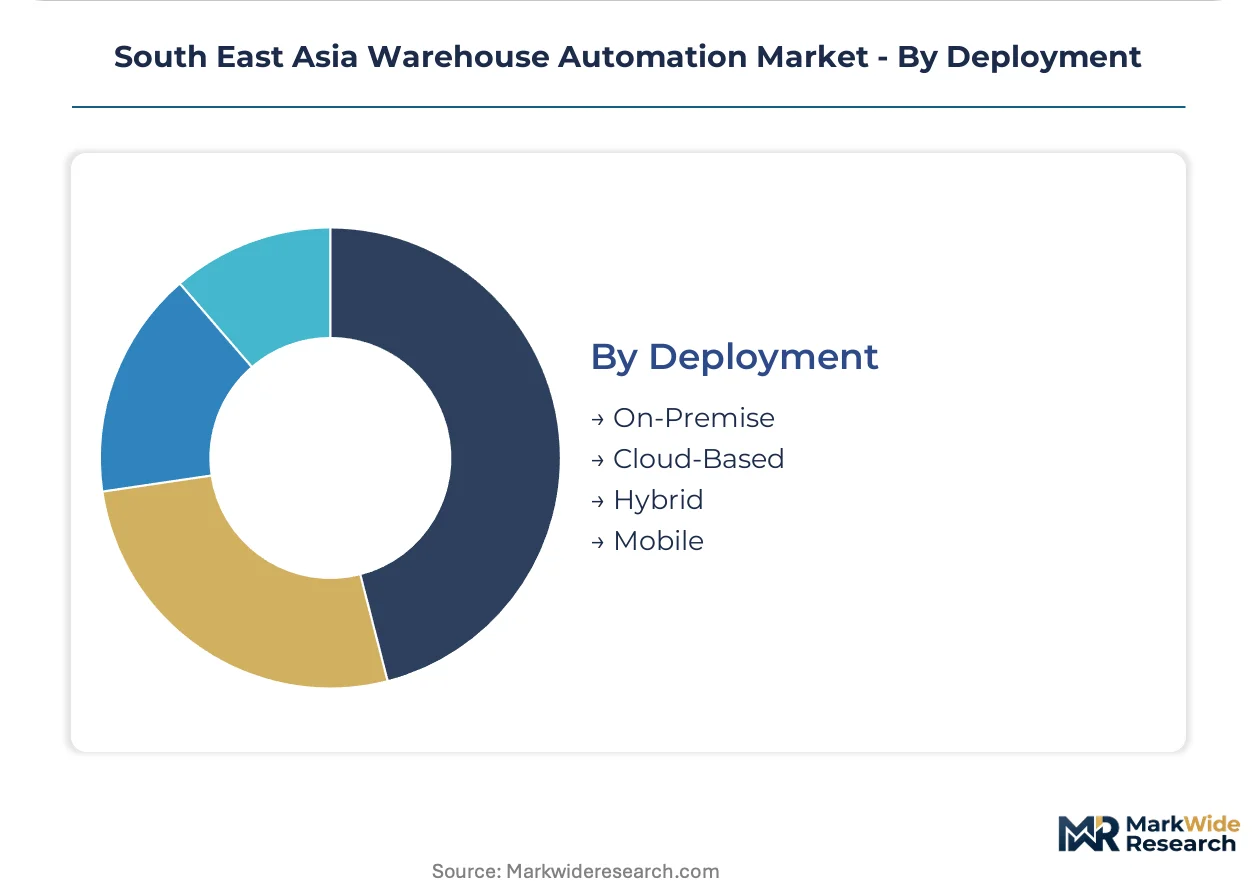
Deployment:
Customer type stratification separates capital-owning operators from those seeking operational flexibility through subscription models.
- Cloud-Based:Warehouse management software hosted on external servers enables multi-site visibility and rapid scaling without on-site IT infrastructure. Indonesian and Vietnamese data localization mandates restrict cross-border data flows, complicating architecture decisions for regional operators.
- Hybrid:Critical control systems remain on-premise while analytics and reporting migrate to cloud environments. Singapore-based regional headquarters favor this model to balance latency requirements with centralized oversight.
- On-Premise:Full local installation maintains data sovereignty and minimizes external connectivity dependencies.
- Mobile:Tablet and handheld interfaces extend warehouse management functionality to floor personnel.
Prevailing architecture: Hybrid. Expanding most quickly: Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of warehouse automation systems concentrates in Northeast Asian manufacturing hubs, while consumption accelerates across Indonesian, Vietnamese, and Thai logistics corridors driven by cross-border e-commerce fragmentation.
Indonesia
Greater Jakarta's logistics corridor faces severe congestion costs and driver availability constraints that push fulfillment operators toward autonomous mobile robots for last-meter pallet movement. Indonesia's Ministry of Industry Industry 4.0 certification framework mandates local content thresholds and workforce reskilling commitments for automation tax incentives. Bekasi and Cikarang industrial zones anchor large-scale distribution center deployments serving domestic marketplace operators.
Vietnam
Electronics export assembly in northern industrial corridors generates synchronized manufacturing supply chain demand for just-in-time component delivery automation. The country's national digital economy framework accelerates customs modernization alongside ASEAN Single Window protocols. Haiphong-Hanoi manufacturing zones remain underpenetrated by large-scale automated distribution centers, creating whitespace for system integrators.
Thailand
Third-party logistics providers expand automated fulfillment capacity to serve cross-border e-commerce platforms operating across mainland Southeast Asia. Thailand's Board of Investment automation incentives provide tax allowances and smart logistics zone certifications subsidizing Industry 4.0 warehouse upgrades. Bangkok metropolitan logistics clusters concentrate bonded warehouse automation deployments benefiting from reduced customs clearance friction.
Singapore
Enterprise Singapore shapes market access through smart logistics zone certifications and automation-focused grant programs conditioning subsidy eligibility on workforce reskilling. The city-state's data center infrastructure supports regional cloud-based warehouse management system architectures despite neighboring data localization mandates. Jurong logistics and Tuas port zones anchor high-throughput sortation investments serving transshipment demand.
Malaysia
Robotics and automation engineering expertise concentrates in Kuala Lumpur and Penang, creating service response capabilities for regional installation and maintenance networks. The country's national logistics master plan incentivizes bonded warehouse automation to capture ASEAN Single Window trade facilitation benefits. Iskandar Malaysia and Port Klang logistics corridors attract capital for cold-chain pharmaceutical automation serving temperature-sensitive biologics distribution.
South East Asia Warehouse Automation Market Competitive Landscape
The competitive structure tilts toward integrated system bundling over standalone equipment sales, with procurement patterns favoring vendors offering combined hardware, software, and maintenance suites. Japanese and Korean component concentration in servo motors and programmable logic controllers exposes deployment timelines to shipping lane disruptions. Two strategic archetypes dominate: multinational integrators leveraging regional manufacturing footprints, and local specialists capturing service proximity advantages. Competitive moves center on modular system architecture development and workforce certification partnerships qualifying clients for government automation subsidies.
Among Japan-based multinationals, Daifuku Co Ltd and Omron Corporation exemplify the integrated system archetype, while Dematic anchors the high-throughput sortation specialization vector. Swisslog Holding AG represents the deep software-hardware integration approach targeting cold-chain and pharmaceutical verticals. DF Automation & Robotics Sdn Bhd occupies a position within the Malaysia-based regional specialist tier, and PingSpace Sdn Bhd sits among emerging local system integrators capturing proximity service advantages in Southeast Asian installation markets.
| Leading Market Players |
|---|
| Dematic |
| Daifuku Co Ltd |
| Swisslog Holding AG |
| DF Automation & Robotics Sdn Bhd |
| ALS Logistic Solutions |
| PingSpace Sdn Bhd |
| Omron Corporation |
| Sun & Siasun Robot Co Ltd |
| Gen Surv Robotics |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between Industry 4.0 compliant integrators and uncertified equipment vendors manifests in both project pricing premiums and component sourcing footprints across Thai and Indonesian deployments. This bifurcation concentrates margin capture with vendors meeting Thailand Board of Investment local content thresholds while compressing returns for pure hardware resellers dependent on Japanese servo motor imports.
Pricing Analysis
Margin tightening in mid-tier system integration reflects steel and aluminum input volatility compressing project visibility for Indonesian conveyor deployments. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels anchors procurement decisions, with pharmaceutical cold-chain buyers least price-sensitive due to biologics compliance requirements. Cost-down pressure on economy tier accelerates because Vietnamese electronics exporters prioritize capital flexibility over ownership.
Supply Chain Analysis
Maintenance technician scarcity in Indonesian and Vietnamese industrial zones extends service response timelines for robotic hardware deployments. Servo motor and programmable logic controller production draws from Japan, South Korea, and Taiwan manufacturing bases, creating single-source vulnerability for ASEAN deployment schedules. Distribution runs through Singapore-based regional headquarters serving multi-country operator architectures despite neighboring data localization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Local maintenance technician scarcity props pricing power for certified installation partners across Indonesian and Vietnamese markets, constraining capacity expansion for automation rollouts.
For Market Incumbents: Anticipate margin compression from modular SaaS-based warehouse management subscriptions displacing perpetual license models in Jakarta's Greater logistics corridor. Defend position by deepening backward integration into predictive maintenance software layers and securing Thailand Board of Investment certification status for bonded warehouse automation eligibility.
For New Entrants and Emerging Players: Capture whitespace in Vietnam's Haiphong-Hanoi electronics corridor where large-scale automated distribution centers remain underpenetrated for just-in-time component delivery. Target 3PL cross-border e-commerce fulfillment as the most penetrable segment, entering through AMR fleet leasing models that trade capital ownership for operational flexibility.
For Investors and Strategic Acquirers: Re-rating potential sits with Malaysian-based regional specialists given Enterprise Singapore workforce reskilling grant access and proximity service advantages across ASEAN installation networks. Monitor ASEAN Single Window customs modernization implementation velocity as the inflection signal for bonded warehouse automation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Workforce Certification Partnership | Indonesia Industry 4.0 compliance unlocks automation tax incentive eligibility for clients. |
| Predictive Maintenance Software Layer | Machine learning algorithms reduce unplanned downtime on Thai sortation equipment. |
| Regional Manufacturing Footprint Expansion | Daifuku's Thailand and Vietnam facilities anchor large-scale distribution center deployments. |
| Modular System Architecture Development | Swisslog's software-hardware integration targets cold-chain pharmaceutical verticals. |
| Smart Logistics Zone Certification | Thailand Board of Investment subsidies offset capital expenditure for qualifying upgrades. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South East Asia warehouse automation assessment. Primary interviews with warehouse operations directors, 3PL procurement leads, system integration engineers, and maintenance service heads combined with Indonesia Ministry of Industry certification databases, Thailand Board of Investment incentive records, and ASEAN Single Window implementation reports. Bottom-up equipment shipment tallies and top-down logistics infrastructure investment flows underwent cross-validation.
Data-stream reconciliation across hardware shipment volumes, software licensing disclosures, and government subsidy award records shaped the analytical framework. Segmentation dimensions spanned equipment category, technology intelligence layer, end-user vertical, and deployment architecture across the projection horizon. CAGRs derived from fitted growth curves on historical automation investment patterns, with cross-border e-commerce order fragmentation velocity and customs modernization timeline serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Indonesian data localization mandate enforcement and Vietnamese electronics export demand cyclicality. Forecasts reflect documented assumptions on ASEAN Single Window rollout pace and steel input cost stabilization. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Asia-Pacific Medical Automation Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Modular Automation and Services Market
Industrial Automation
UV Curing System Market
Industrial Automation
Smart Factory Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Latin America HMI Market