
 Nordic Commercial Printing Market | 2026-2036
Nordic Commercial Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Commercial Printing Market Analytics
Modular print service bundling is hardening across the Nordic region, with buyers increasingly separating design, pre-press, and fulfillment contracts rather than purchasing integrated packages. V-TAB AB leverages its Swedish production network to anchor magazine and catalog volumes. Ålgård Offset specializes in high-volume offset runs for Norwegian publishers. ScandBook Holding competes on short-run digital flexibility for educational titles.
Nordic commercial printing encompasses the production of marketing collateral, publications, and packaging materials using mechanical or digital processes, typically on paper, board, or synthetic substrates at resolutions exceeding 300 lines per inch for commercial-grade output. Its primary purpose is to convert brand and publisher content into physical, distributable formats for consumer engagement. Offset printing still dominates volume across the region due to its cost efficiency on long runs, while digital printing captures margin pools in personalized promotional materials and variable-data labels. Inkjet technology leads technology investment as converters replace aging toner systems for packaging proofs and short-run brochures.
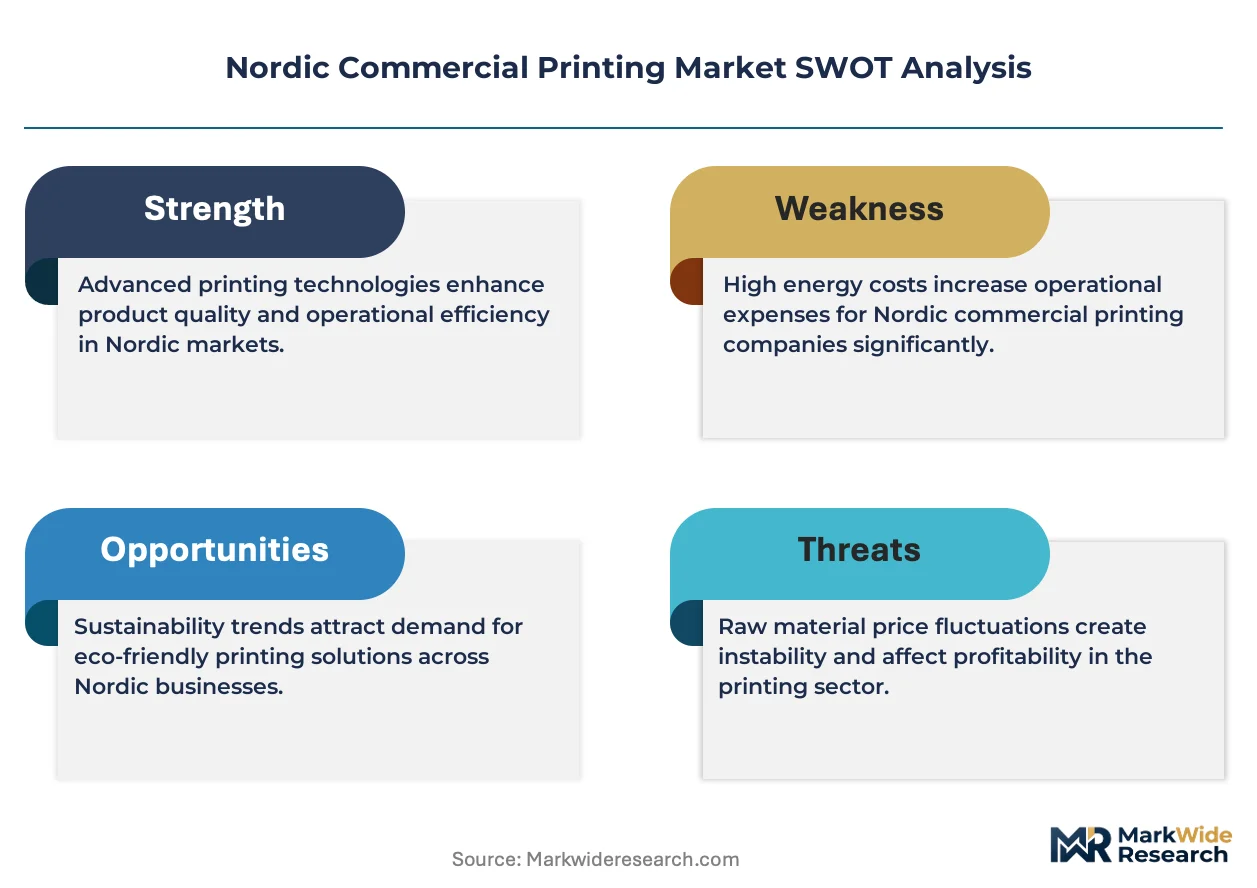
Sweden's Chemical Tax, Norway's Waste Regulation implementation, and Finland's extended producer responsibility frameworks collectively elevate compliance costs for solvent-based workflows while accelerating water-based and UV-curable ink adoption. REACH chemical restrictions across the European Economic Area further constrain substrate and coating choices for export-bound print products. Stakeholders must monitor how carbon border adjustments and evolving Nordic green procurement standards reshape supplier qualification criteria and capital allocation across the value chain.
Market Dynamics
Modular contract unbundling is fragmenting buyer-supplier relationships across the Nordic region, separating design, pre-press, and fulfillment into discrete procurement decisions that reshape margin capture and vendor loyalty.
Growth Catalysts
- Sweden's Chemical Tax:Fiscal pressure on solvent-based workflows accelerates converter migration toward water-based ink systems, creating equipment refresh cycles across Stockholm and Gothenburg production clusters.
- Educational publisher consolidation:Centralized print procurement for school materials generates volume concentration that favors high-efficiency offset operations serving cross-border distribution.
- Inkjet technology maturation:Single-pass inkjet systems for packaging proofs and short-run brochures displace aging toner fleets, opening capacity for variable-data applications.
Market Restraints
- Pulp and paper input volatility:Nordic mills face energy cost pressure that transmits directly to substrate pricing, compressing converter margins on fixed-price catalog contracts.
- REACH chemical restrictions:ECHA compliance burdens for coatings and adhesives constrain export-bound print products, forcing dual-formulation inventories for EEA and non-EEA destinations.
- Digital substitution:Electronic invoicing and digital document workflows displace transactional print volumes in banking and government sectors.
Strategic Opportunities
- Finland's extended producer responsibility frameworks:Packaging waste regulations create certified circular-economy print demand from brand owners seeking compliance-ready suppliers.
- Cross-border retail clustering:Oslo-Stockholm corridor distribution hubs enable consolidated print-to-fulfillment services for pan-Nordic retail chains.
- UV-curable ink convergence:Hybrid inkjet-offset systems capture premium packaging proofing work from cosmetic and pharmaceutical clients requiring rapid turnaround.
Industry Challenges
- Pre-press automation skill gaps:Converters struggle to recruit operators proficient in cloud-based color management and automated imposition workflows.
- Legacy MIS integration friction:ERP upgrades for job costing and inventory tracking stall at mid-size printers with customized legacy codebases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Commercial Printing Market |
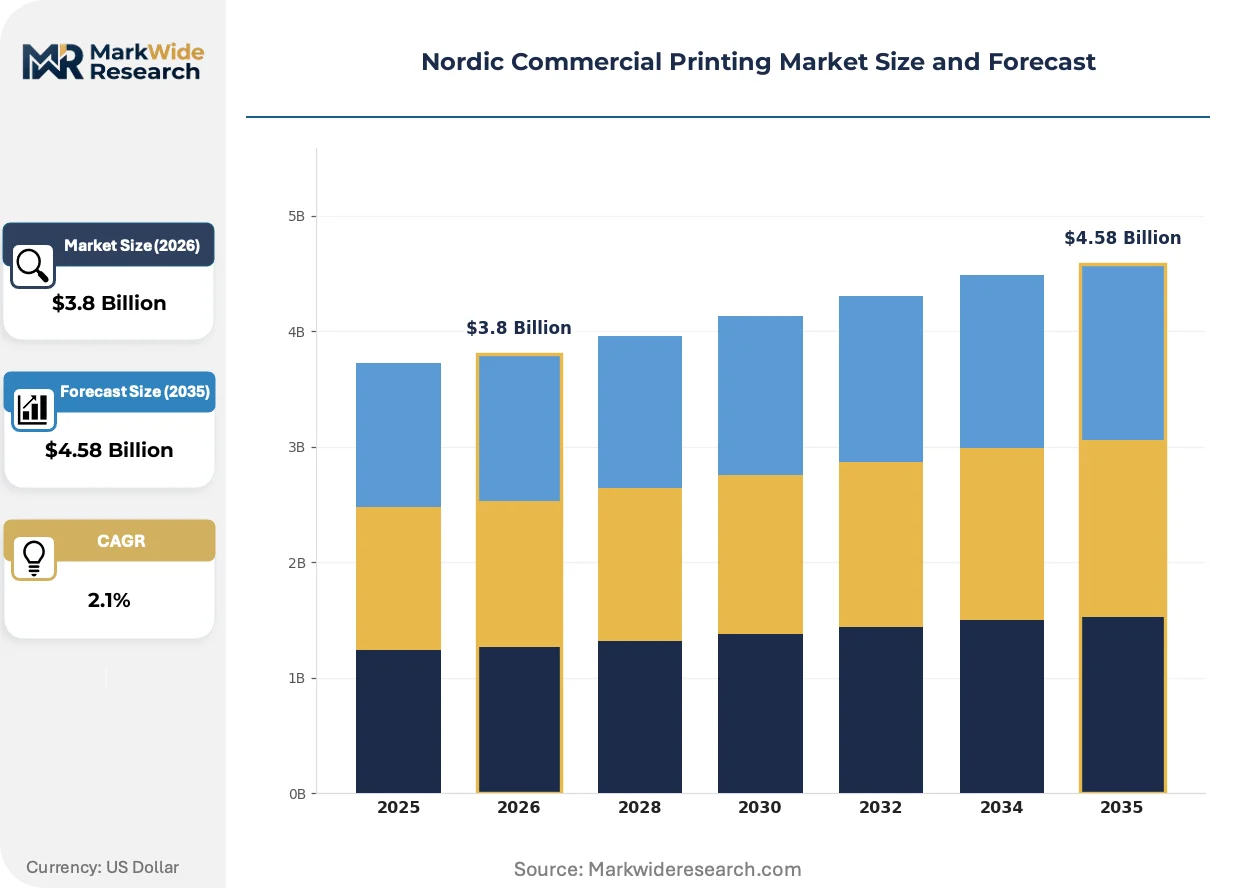
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printing, Offset Printing, Flexographic Printing, Screen Printing Application: Packaging, Promotional Materials, Labels, Brochures End User: Retail, Publishing, E-commerce, Advertising Agencies Technology: Inkjet Technology, Laser Technology, 3D Printing, Variable Data Printing |
| Companies Covered | Amedia Trykk og Distribusjon, V-TAB AB, Ålgård Offset, Bold Printing Group AB, Botnia Print, Gota Media AB, ScandBook Holding, Alma Manu Oy, Aller Tryk A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Commercial Printing Market Evolving Landscape
Technology substitution and regulatory chemistry mandates are rewiring capital allocation across Nordic print converters, with equipment refresh cycles now synchronized to environmental compliance deadlines rather than pure mechanical depreciation.
Single-pass inkjet systems are electrifying short-run packaging and commercial brochure production. Pharmaceutical and cosmetic brand owners in Denmark and Sweden are adopting these platforms for rapid proof-to-production cycles. The technology is electrifying margin capture in segments previously dominated by offset, compressing break-even run lengths by an order of magnitude.
Norway's Waste Regulation implementation tightens producer accountability for print product end-of-life. The framework forces converters to document substrate recyclability and ink deinkability. Magazine and catalog printers serving Norwegian publishers face accelerated certification timelines to maintain qualified supplier status.
Buyers are unbundling historically integrated print service packages. Retail chains now separate creative design, pre-press preparation, and physical fulfillment into distinct vendor relationships. This pattern concentrates most visibly in Sweden, where Stockholm-based procurement teams negotiate modular contracts that prioritize flexibility over single-source accountability.
Nordic Commercial Printing Market Segmentation
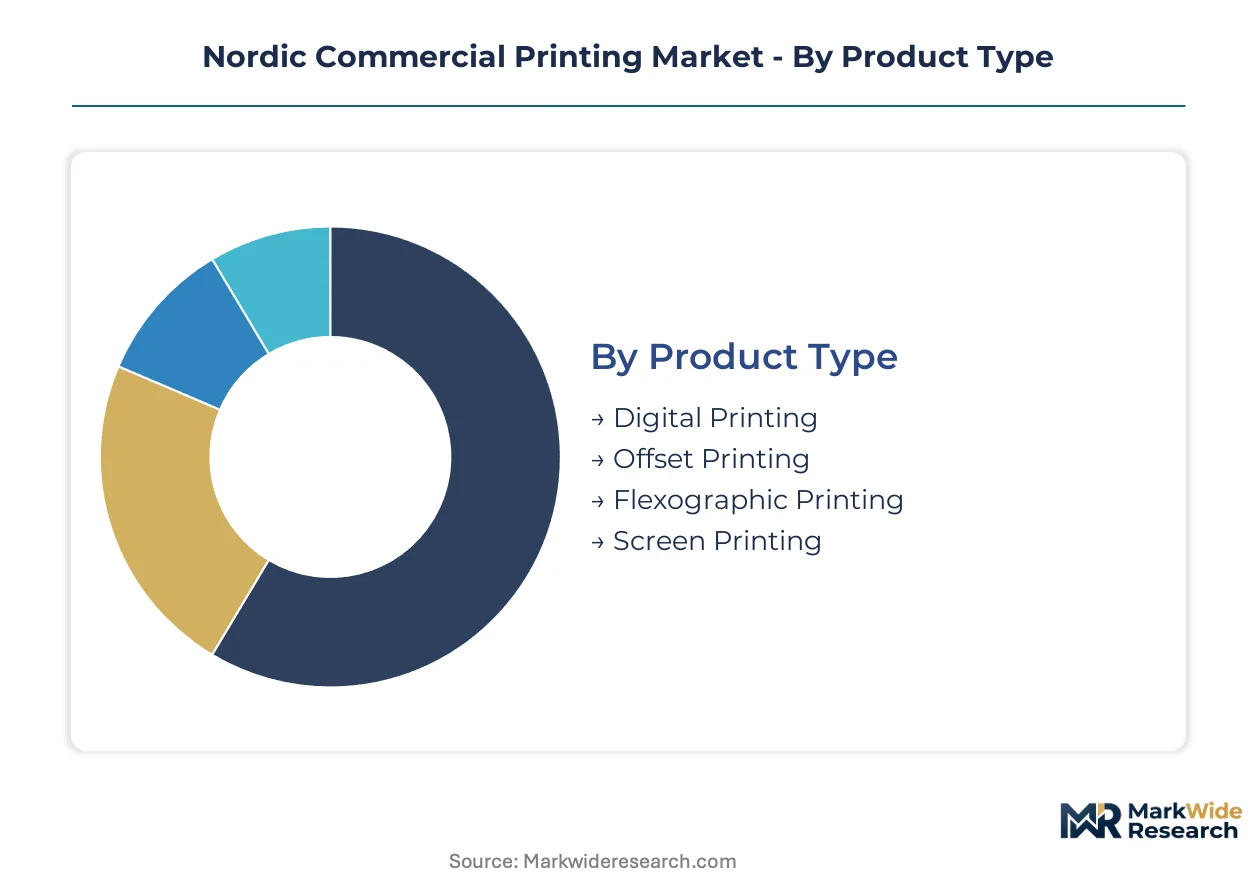
Nordic converters allocate capital across distinct equipment categories and workflow technologies. Segmentation reveals where ink chemistry mandates and run-length economics concentrate investment returns.
Product Type:
Equipment replacement cycles now synchronize with Sweden's Chemical Tax compliance deadlines rather than mechanical depreciation schedules alone.
- Offset Printing:Sheet-fed and web-fed lithographic systems dominate long-run educational and catalog work across Stockholm-Gothenburg production clusters. V-TAB AB anchors regional capacity here, capturing consolidated publisher procurement from cross-border distribution hubs.
- Digital Printing:Electrophotographic and ink-on-paper systems compress break-even run lengths for personalized promotional materials. ScandBook Holding deploys these platforms for short-run educational titles requiring rapid revision cycles.
- Flexographic Printing:Rotary relief printing with photopolymer plates serves corrugated packaging and flexible film substrates for Oslo-Stockholm retail clients.
- Screen Printing:Stencil-based deposition handles heavy ink films on synthetic substrates and specialty promotional items in Danish and Finnish converter facilities.
Offset sits at the top of the volume ranking, with digital climbing the fastest.
Application:
Margin capture varies sharply by end-use, with pharmaceutical and cosmetic proofing commanding premium pricing over commodity catalog work.
- Packaging:Folding carton, corrugated, and flexible film printing for consumer goods brands. Norway's Waste Regulation implementation forces substrate recyclability documentation across this segment.
- Promotional Materials:Variable-data direct mail and point-of-sale displays. Finland's extended producer responsibility frameworks create certified circular-economy demand from brand owners seeking compliance-ready suppliers.
- Labels:Pressure-sensitive and shrink-sleeve formats for food and beverage clients. REACH chemical restrictions constrain adhesive formulations for EEA-exported products.
- Brochures:Commercial collateral and corporate communications. Electronic invoicing adoption in Swedish banking displaces transactional volumes here.
Packaging commands the steepest expansion trajectory as brand owners consolidate pan-Nordic procurement.
End User:
Procurement centralization patterns differ markedly across buyer categories, with retail chains unbundling services while publishers consolidate print runs.
- Publishing:Educational and magazine publishers. Centralized print procurement for school materials generates volume concentration favoring high-efficiency offset operations.
- Retail:Pan-Nordic chains and specialty merchants. Stockholm-based procurement teams negotiate modular contracts separating design, pre-press, and fulfillment.
- E-commerce:Direct-to-consumer brands requiring corrugated shipping boxes and insert cards. Cross-border retail clustering in the Oslo-Stockholm corridor enables consolidated print-to-fulfillment services.
- Advertising Agencies:Creative intermediaries managing campaign production. These buyers increasingly disaggregate historically integrated print service packages.
Publishing retains the largest volume share, though e-commerce is expanding most quickly.
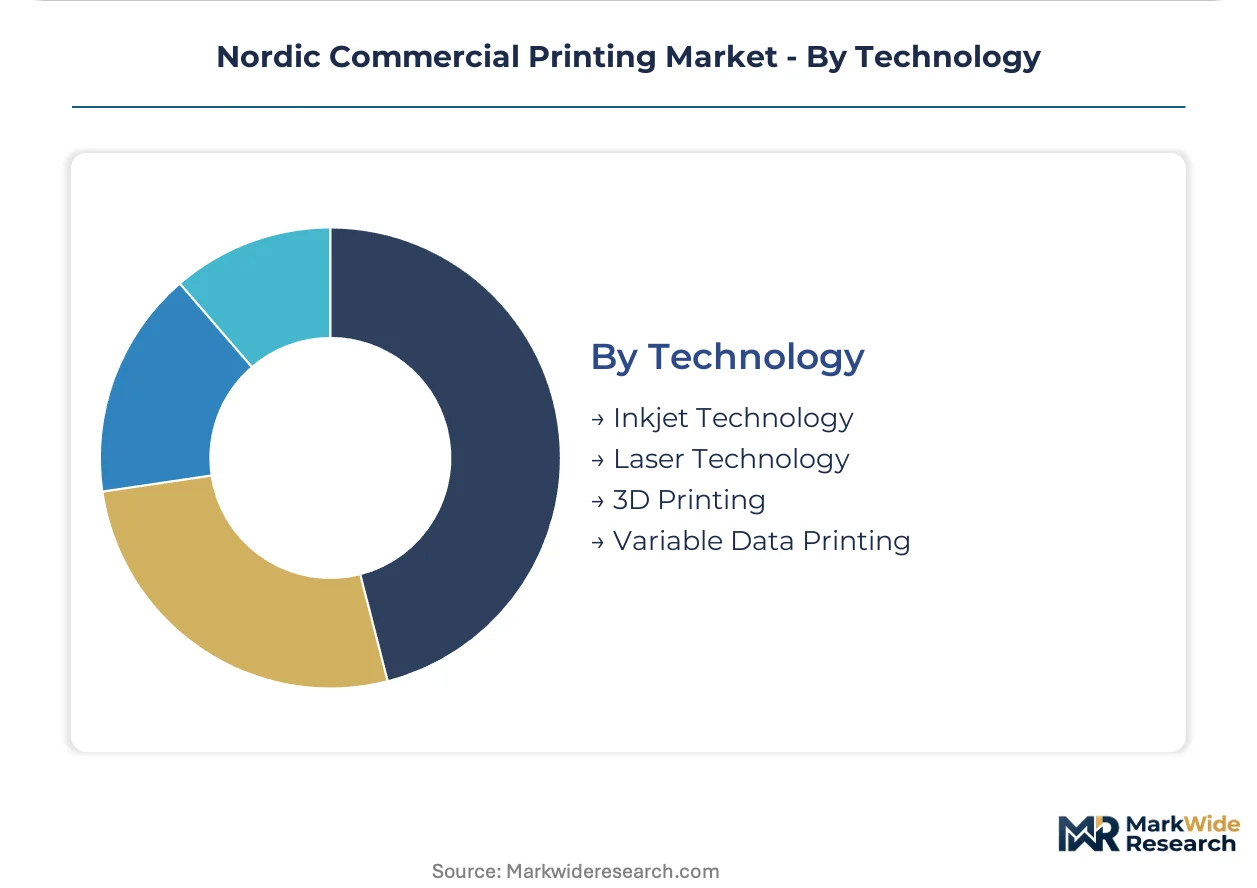
Technology:
Technology substitution rates accelerate where environmental compliance deadlines force premature retirement of solvent-dependent systems.
- Inkjet Technology:Piezoelectric drop-on-demand and continuous inkjet systems. Single-pass inkjet platforms displace aging toner fleets for packaging proofs and short-run brochures.
- Laser Technology:Electrophotographic imaging with dry toner or liquid toner systems. These platforms retain share in transactional document segments despite digital substitution pressure.
- Variable Data Printing:Database-driven personalization engines integrated with digital front-ends. Pharmaceutical and cosmetic brand owners in Denmark and Sweden adopt these for rapid proof-to-production cycles.
- 3D Printing:Additive manufacturing for prototyping and short-run dimensional signage. Limited penetration in commercial print relative to industrial applications.
Inkjet technology leads capital deployment, with variable data printing gaining share fastest among specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial printing took root in the Nordic region during the 19th century, when Copenhagen, Stockholm, and Oslo emerged as publishing centers for newspapers and educational materials. The industry scaled through state-funded schoolbook procurement and cross-border magazine distribution networks.
Sweden
Stockholm and Gothenburg production clusters anchor magazine and catalog volumes for pan-Nordic retail chains. The country's Chemical Tax on electronics and printed goods accelerates converter migration toward water-based ink systems, forcing equipment refresh cycles ahead of mechanical depreciation schedules. V-TAB AB leverages its Swedish production network to capture consolidated publisher procurement from cross-border distribution hubs.
Norway
Oslo-based print procurement teams negotiate modular contracts separating design, pre-press, and fulfillment for retail clients. Norway's Waste Regulation implementation tightens producer accountability for print product end-of-life, forcing converters to document substrate recyclability and ink deinkability. Ålgård Offset specializes in high-volume offset runs for Norwegian publishers clustered around the Oslo-Stockholm corridor.
Finland
Helsinki and Tampere converters serve pharmaceutical and cosmetic brand owners demanding rapid proof-to-production cycles. Extended producer responsibility frameworks for packaging waste create certified circular-economy print demand from brand owners seeking compliance-ready suppliers. Alma Manu Oy operates within this regulatory environment, positioning for premium packaging proofing work.
Denmark
Copenhagen anchors demand for variable-data promotional materials and point-of-sale displays serving pan-Nordic retail chains. Aller Tryk A/S occupies a position within the Danish printing landscape, representing the specialist tier focused on magazine and catalog production. Pharmaceutical and cosmetic brand owners in Denmark adopt single-pass inkjet platforms for rapid turnaround requirements.
Denmark
Copenhagen anchors demand for variable-data promotional materials and point-of-sale displays serving pan-Nordic retail chains. Aller Tryk A/S occupies a position within the Danish printing landscape, representing the specialist tier focused on magazine and catalog production. Pharmaceutical and cosmetic brand owners in Denmark adopt single-pass inkjet platforms for rapid turnaround requirements.
Nordic Commercial Printing Market Competitive Landscape
The competitive structure tilts toward mid-scale specialists rather than integrated conglomerates. Swedish and Norwegian converters dominate volume through long-run offset capacity, while Finnish and Danish players capture margin in short-run digital and packaging proofing segments. Two strategic archetypes define positioning: efficiency-driven offset specialists serving educational publishers, and flexibility-focused digital operators targeting variable-data retail applications. M&A activity concentrates on bolt-on capacity acquisitions in the Stockholm-Oslo corridor, while technology licensing partnerships accelerate inkjet platform deployment.
Among Sweden-based operators, V-TAB AB and Bold Printing Group AB exemplify the scale-driven archetype, anchoring magazine and catalog production through clustered distribution networks. ScandBook Holding represents the flexibility-focused tier, competing on short-run digital capacity for educational titles requiring rapid revision cycles. These three companies illustrate how geographic concentration and technology specialization stratify competitive positioning across the Nordic region.
| Leading Market Players |
|---|
| Amedia Trykk og Distribusjon |
| V-TAB AB |
| Ålgård Offset |
| Bold Printing Group AB |
| Botnia Print |
| Gota Media AB |
| ScandBook Holding |
| Alma Manu Oy |
| Aller Tryk A/S |
| Others |
Value Network & Pricing Analysis
Water-based certification tiers split Nordic converters into compliance-ready premium suppliers and legacy solvent-dependent commodity players, with Sweden's Chemical Tax enforcement widening the cost gap between these camps while reshaping procurement patterns across Stockholm-Oslo corridor distribution hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Nordic commercial print, with REACH-compliant water-based workflows commanding 15-20% premiums over solvent-based alternatives. Price differentiation stems from certification grade and volume scale, with educational publishers leveraging consolidated procurement for standard-tier rates while cosmetic brands absorb premium pricing for rapid-turnaround proofing. Cost compression in economy-tier catalog work is intensifying because pulp and paper input volatility transmits directly from Nordic mills. Retail chains exhibit highest price sensitivity through modular contract unbundling, whereas pharmaceutical clients show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Pulp supply rests on Swedish and Finnish integrated mills, ink chemistry feeds from German and Dutch specialty chemical producers, and digital press components draw from Japanese and German precision engineering clusters. Raw material dependencies span coated paper grades, UV-curable ink formulations, and piezoelectric printhead assemblies. Single-source vulnerability concentrates in high-performance inkjet printhead supply. Distribution runs through Stockholm-Oslo corridor hubs serving cross-border retail clients with consolidated print-to-fulfillment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nordic commercial printing functions as a stable compounder, with regulatory compliance deadlines forcing predictable equipment refresh cycles that sustain replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Lock in water-based workflow certification ahead of tightening ECHA enforcement timelines. Secure long-term pulp supply agreements with Stora Enso or UPM to hedge input volatility. Prioritize backward integration into pre-press automation to capture margin from unbundled design contracts. For New Entrants and Emerging Players: Packaging waste compliance consultants represent the most penetrable channel partner type for market entry. Target Finnish pharmaceutical proofing segments where extended producer responsibility frameworks create certified supplier shortages. Deploy single-pass inkjet platforms on lease-based models to lower capital barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale digital specialists holding REACH-compliant water-based capacity in underserved Danish and Norwegian markets. Five-to-ten-year viability hinges on regulatory chemistry mandates persisting. Watch inkjet printhead supply disruption as inflection indicator for equipment deployment delays.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Ink System Migration | Sweden's Chemical Tax enforcement accelerates converter capital allocation toward compliant workflows. |
| Single-Pass Inkjet Platform Deployment | Pharmaceutical proofing demand in Copenhagen and Stockholm justifies premium equipment investment. |
| Cross-Border Distribution Hub Consolidation | Oslo-Stockholm corridor clustering enables pan-Nordic retail chain contract capture. |
| Pre-Press Automation Acquisition | Modular contract unbundling creates margin pools in cloud-based color management services. |
| Extended Producer Responsibility Certification | Norway's Waste Regulation implementation forces substrate recyclability documentation capabilities. |
Research Methodology
Direct dialogue with plant managers at Nordic offset and digital converters, procurement leads at educational publishers and retail chains, ECHA regulatory affairs specialists, and distribution channel partners grounded this analysis. Secondary validation drew from Swedish Chemicals Agency enforcement disclosures, Finnish packaging waste registry data, Norwegian Waste Regulation implementation guidelines, and EU REACH restriction candidate list updates. Bottom-up equipment installation tracking and top-down pulp consumption modeling enabled triangulation across analysis approaches.
Bottom-up segmentation modeled product type, application, end user, and technology dimensions across the projection horizon, with run-length economics and ink chemistry compliance deadlines as industry-specific forecast inputs. CAGRs were derived through equipment replacement cycle analysis synchronized to regulatory enforcement timelines rather than pure mechanical depreciation schedules.
Revisions become necessary when ECHA expands REACH restriction scope beyond current candidate substances, when Nordic pulp mill energy cost volatility exceeds historical bands, or when single-pass inkjet printhead supply disruption extends equipment lead times. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Web to Print Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Digital Paper System Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Print on Demand Software Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Variable Data Printing Market
Printing Technology
RFID Printer Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
ID Card Printers Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Print on Demand Market
Printing Technology
Commercial Printer Market