
 Retail Printers Market | 2026-2036
Retail Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Printers Market Outlook
Solid-state ink technology is consolidating around piezoelectric MEMS architectures that slash per-page costs versus traditional thermal inkjet assemblies. HP Inc leverages its captive silicon foundry partnerships to lock in nozzle density advantages at consumer price points. Canon Inc anchors its retail position through photolithography-derived printhead precision that sustains margin in photo-specialist channels. Seiko Epson Corporation dominates piezoelectric inkjet with its MicroTFP array technology, controlling the bulk of high-speed label production for e-commerce fulfillment centers.
Retail printers encompass point-of-sale output devices engineered for receipt, label, tag, and transactional document generation, typically operating at 203 to 600 dpi with thermal, impact, or inkjet marking mechanisms designed for 24/7 duty cycles in commercial environments. Thermal printers lead unit shipments across supermarket and quick-service food service deployments where silent, inkless operation reduces maintenance intervals. Inkjet printers represent the fastest-expanding value pool as on-demand color label production displaces pre-printed inventory in e-commerce platform warehouses. Label printers occupy concentrated margin territory in third-party logistics contracts requiring GS1-compliant barcode serialization.
The US EPA Energy Star program and the EU Ecodesign for Sustainable Products Regulation are tightening standby power limits and mandating modular repair access, forcing redesigns of power supply and controller board architectures. China's SAMR enforces GB standard electromagnetic compatibility certifications that gate market entry for imported POS peripheral hardware. Stakeholders must monitor how firmware-locked consumable strategies intersect with emerging right-to-repair mandates across multiple jurisdictions.
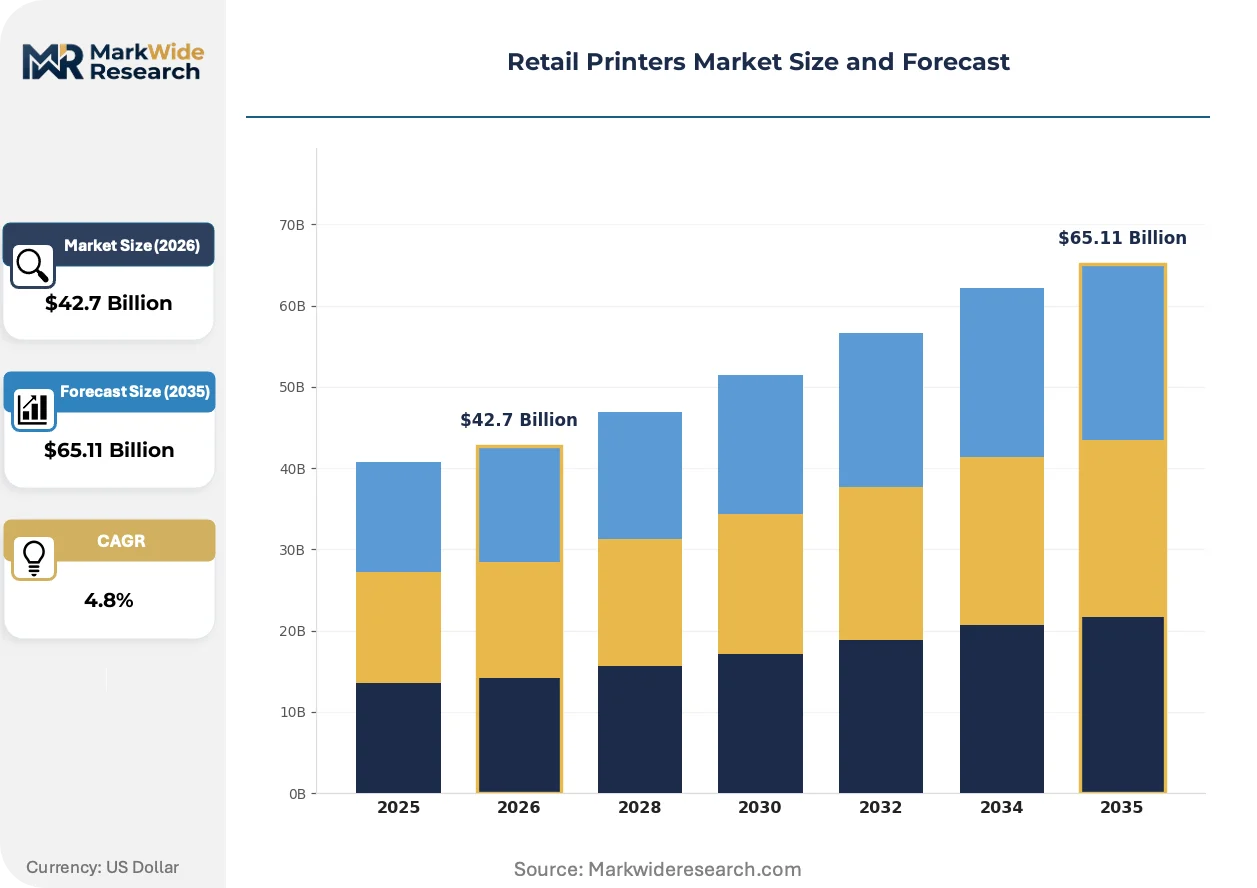
Market Dynamics
Self-service kiosk deployments across grocery and quick-service restaurant chains are compressing printer replacement cycles while piezoelectric MEMS architectures are absorbing thermal inkjet share in high-volume label production.
Growth Catalysts
- E-commerce fulfillment scale:Third-party logistics operators require GS1-compliant barcode serialization for warehouse automation, pulling demand for industrial-grade label printers with 600 dpi resolution and continuous duty cycles.
- EU Ecodesign for Sustainable Products Regulation:Mandates for modular, repairable hardware architectures are forcing redesigns that extend equipment lifespan and create aftermarket service revenue pools for component suppliers.
- Thermal receipt printer refresh:Silent, inkless operation in 24/7 supermarket environments reduces maintenance intervals and drives replacement demand as legacy impact mechanisms reach end-of-life.
Market Restraints
- Silicon nozzle supply concentration:Captive foundry partnerships for piezoelectric MEMS printheads limit second-source availability and create single-supplier risk for high-density nozzle arrays.
- Firmware-locked consumable strategies:Authentication chips on ink and ribbon cartridges face escalating right-to-repair litigation across multiple jurisdictions, threatening recurring revenue models.
- Pre-printed label inventory substitution:Large e-commerce platforms maintain legacy pre-printed label stockpiles that delay on-demand color inkjet adoption in cost-sensitive fulfillment contracts.
Strategic Opportunities
- Tier-two and tier-three China retail networks:Domestic printer brands are capturing share in underpenetrated provincial grocery chains where imported hardware faces SAMR certification delays.
- Photolithography-derived printhead precision:Convergence of semiconductor fabrication methods with inkjet deposition enables sub-picoliter droplet control for photo-specialist retail channels.
- EPA Energy Star standby power limits:Tightening efficiency thresholds create first-mover advantage for power supply redesigns that qualify for federal procurement preference in US government retail contracts.
Industry Challenges
- Electromagnetic compatibility certification timelines:China's SAMR enforcement of GB standard EMC testing gates market entry for imported POS peripherals, extending product launch schedules by 8-14 months.
- Controller board architecture reconfiguration:Modular repair access mandates require complete redesign of integrated electronics layouts, elevating non-recurring engineering costs for legacy product families.
- MEMS process engineering talent scarcity:Piezoelectric actuator fabrication expertise concentrates in semiconductor equipment sectors, constraining printer OEM hiring pipelines for next-generation printhead development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Printers Market |
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $65.11 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Printers, Dot Matrix Printers, Inkjet Printers, Label Printers End User: Small Retailers, Supermarkets, E-Commerce Platforms, Food Service Connectivity: USB, Bluetooth, Ethernet, Wi-Fi Operating Environment: Indoor, Outdoor, Mobile, Point-of-Sale |
| Companies Covered | HP Inc, Canon Inc, Seiko Epson Corporation, Ricoh Company Ltd, Brother Industries Ltd, Konica Minolta Inc, Xerox Holdings Corporation, Kyocera Corporation, Oki Electric Industry Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Printers Market Strategic Shifts
Solid-state ink technology is consolidating around piezoelectric architectures that slash per-page economics, while regulatory pressure on repairability and energy efficiency is rewriting hardware design specifications across all price tiers.
Piezoelectric MEMS printhead technology is absorbing thermal inkjet applications in high-speed label production for e-commerce fulfillment centers. Third-party logistics operators are adopting these systems at accelerated replacement cycles to capture lower total cost of ownership. The structural consequence is compressing margin pools for thermal inkjet component suppliers while elevating nozzle density specifications as a competitive differentiator.
The EU Ecodesign for Sustainable Products Regulation is mandating modular power supply and controller board architectures that enable field repair without specialized tooling. Industrial consequences include extended product development timelines and elevated bill-of-materials costs for separable component designs. High-volume supermarket and quick-service restaurant deployments across Germany, France, and Italy face the most immediate compliance pressure, with OEMs responding through lease-based service models that retain ownership and repair responsibility.
Buyer preference is rotating toward hardware-as-a-service contracts that unbundle equipment acquisition from maintenance and consumable replenishment. Large grocery chains and pharmacy retailers are displacing capital purchase models with per-print pricing structures that transfer obsolescence risk to vendors. This behavioral shift is most visible in North American and Western European markets where corporate sustainability mandates favor circular economy service arrangements over asset ownership.
Retail Printers Market Segmentation
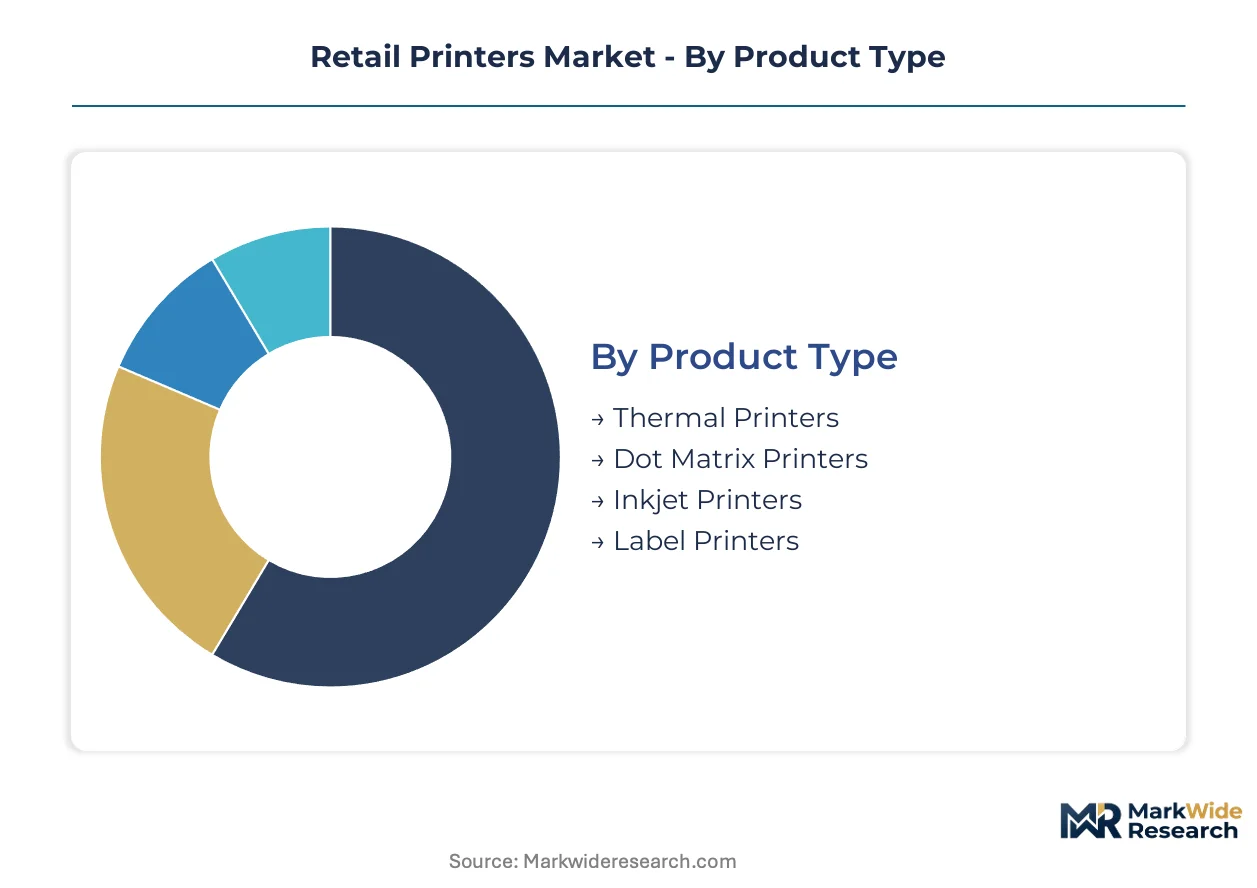
Printer selection in retail environments hinges on duty cycle demands, connectivity infrastructure, and regulatory operating conditions. Segmentation reveals how hardware specifications align with distinct buyer workflows across transaction types and physical settings.
Product Type:
Cost tier separates commodity receipt production from precision labeling applications requiring color fidelity and barcode compliance.
- Thermal Printers:Silent, inkless mechanisms employing heat-sensitive paper for 24/7 supermarket and quick-service restaurant deployments. Demand concentrates in Germany and France where EU Ecodesign standby power limits are compressing replacement cycles for legacy impact hardware.
- Inkjet Printers:Piezoelectric MEMS architectures delivering on-demand color label production at 600 dpi resolution for e-commerce fulfillment centers. Third-party logistics operators in China are absorbing these systems fastest as GS1-compliant serialization replaces pre-printed inventory.
- Dot Matrix Printers:Impact mechanisms retained for multi-part form printing in pharmacy and banking environments requiring carbon-copy documentation.
- Label Printers:Specialized units engineered for continuous duty cycles in warehouse automation, dominating margin pools in third-party logistics contracts.
Volume sits with thermal mechanisms; growth tilts toward inkjet color production systems.
End User:
Application scale determines whether buyers prioritize capital efficiency or total cost of ownership in hardware procurement.
- E-Commerce Platforms:High-volume fulfillment operations requiring industrial-grade 600 dpi label serialization for warehouse automation. China's domestic brands are capturing share in tier-two and tier-three city distribution centers where SAMR certification delays constrain imported hardware.
- Supermarkets:Silent thermal receipt printers deployed at checkout lanes and self-service kiosks across 24/7 operating environments. Chains in Italy face immediate EU Ecodesign modular repair mandates.
- Food Service:Compact thermal units for kitchen ticket printing and customer-facing receipt generation in quick-service restaurant chains.
- Small Retailers:Cost-constrained buyers favoring USB-connected thermal units with minimal maintenance requirements.
Procurement volume clusters with supermarket chains; hardware-as-a-service adoption is climbing fastest among e-commerce fulfillment operators.
Connectivity:
Customer IT maturity dictates whether deployments prioritize plug-and-play simplicity or enterprise network integration.
- Ethernet:Wired infrastructure for fixed POS installations in supermarket and big-box retail environments requiring centralized device management.
- Wi-Fi:Wireless flexibility enabling pop-up retail and temporary event commerce without cabling infrastructure.
- Bluetooth:Short-range pairing for mobile POS tablets in food service and boutique retail settings.
- USB:Direct connection standard for small retailers with minimal IT overhead and single-terminal deployments.
Deployment share favors Ethernet in enterprise retail; Wi-Fi is expanding most quickly in experiential and temporary commerce formats.
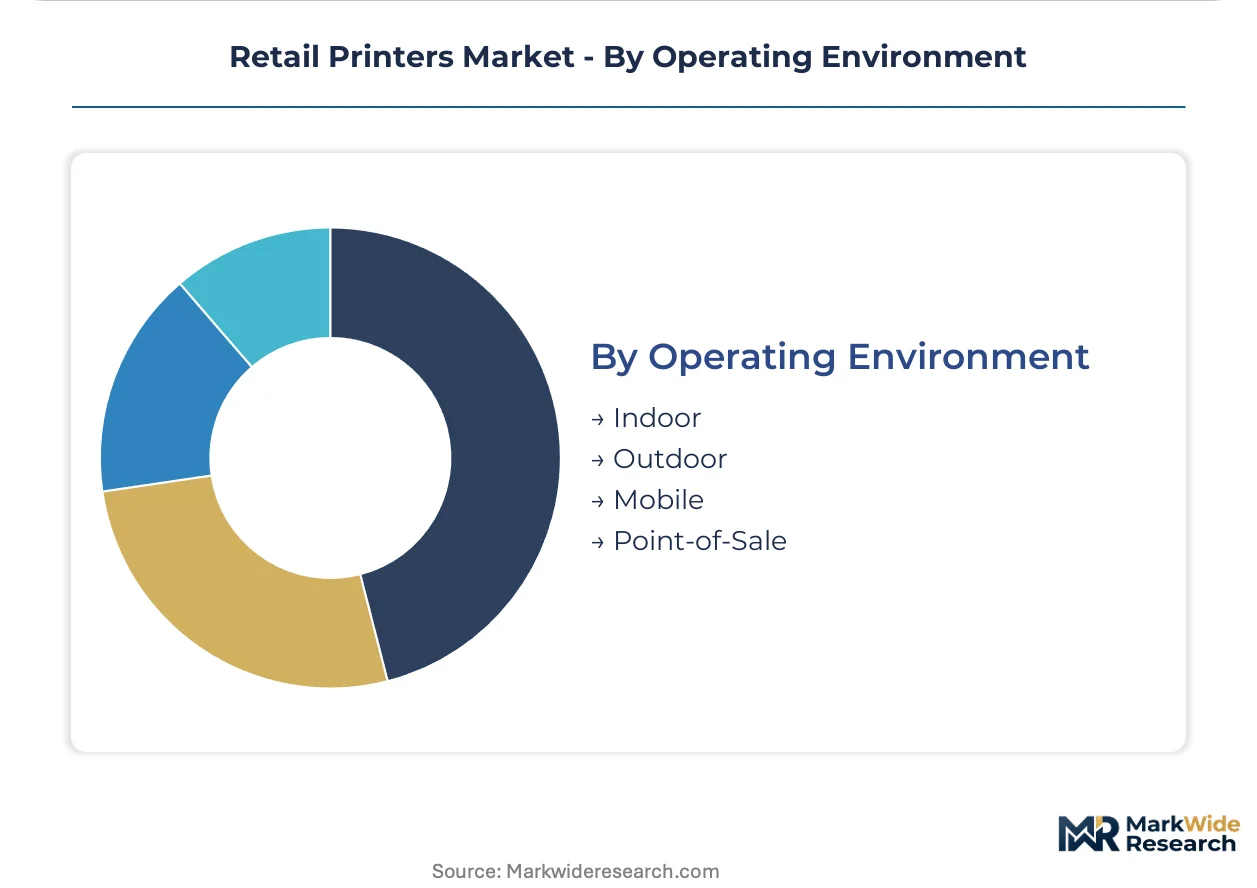
Operating Environment:
Physical placement constraints govern durability specifications and power supply architectures.
- Point-of-Sale:Fixed countertop installations in checkout lanes requiring compact footprints and silent thermal operation.
- Mobile:Battery-powered units for curbside pickup, delivery verification, and pop-up retail workflows.
- Indoor:Climate-controlled environments spanning standard retail floors, back-office inventory stations, and fulfillment mezzanines.
- Outdoor:Weather-resistant enclosures for garden centers, fuel stations, and event commerce requiring extended temperature tolerances.
Installed base concentrates at fixed POS stations; mobile deployments are gaining share fastest in omnichannel fulfillment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest volume of retail printer deployments as domestic brands displace imported hardware in provincial distribution networks. The United States and Germany concentrate premium-tier demand through supermarket modernization programs. Japan and India represent divergent growth vectors shaped by local manufacturing policy and import substitution incentives.
China
Tier-two and tier-three city retail networks are driving thermal printer refresh cycles as domestic manufacturers capture share from delayed SAMR certification timelines for foreign hardware. The State Administration for Market Regulation enforces GB standard electromagnetic compatibility testing that gates entry for imported POS peripherals. Sichuan-Chongqing distribution hubs are absorbing industrial-grade label printers for e-commerce fulfillment centers serving western provinces.
United States
Supermarket chains and quick-service restaurant operators are compressing replacement cycles for legacy impact receipt printers through 24/7 operational demands. The EPA Energy Star program tightens standby power limits that qualify hardware for federal procurement preference. The Southeast region spanning Florida and Georgia is concentrating self-service kiosk deployments in grocery and pharmacy retail formats.
Germany
The EU Ecodesign for Sustainable Products Regulation is forcing modular power supply redesigns for thermal receipt printers deployed across supermarket checkout lanes. Germany's Federal Environment Agency enforces standby power thresholds that accelerate hardware replacement in 24/7 retail environments. The North Rhine-Westphalia industrial corridor hosts refurbishment and component recovery operations for lease-based printer service models.
Japan
Piezoelectric MEMS printhead fabrication expertise concentrates in semiconductor equipment sectors serving high-speed label production for e-commerce fulfillment. METI industrial policy supports domestic manufacturing of precision deposition systems for photo-specialist retail channels. The Kanto region around Tokyo anchors development of sub-picoliter droplet control technologies for on-demand color labeling applications.
India
Small retailers and pharmacy chains are absorbing cost-constrained USB-connected thermal units as import substitution policies favor domestic assembly operations. The Bureau of Indian Standards enforces electromagnetic compatibility certifications that delay market entry for non-compliant hardware. Maharashtra and Gujarat industrial zones are expanding contract manufacturing capacity for entry-level POS peripheral production.
Retail Printers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated control at the high-performance tier and fragmentation in entry-level hardware. The vendor landscape organizes around three strategic archetypes: captive silicon foundry operators, photolithography-precision specialists, and piezoelectric MEMS fabricators. Competitive positioning hardens through M&A activity targeting nozzle density intellectual property and strategic partnerships locking in e-commerce fulfillment contracts.
Within the piezoelectric MEMS tier, Seiko Epson Corporation and Canon Inc exemplify divergent approaches to printhead architecture, while HP Inc occupies a position bridging consumer price points with silicon partnership advantages. Japanese-origin fabricators concentrate precision deposition expertise, whereas US-based players leverage captive supply arrangements for nozzle array production. Ricoh Company Ltd and Brother Industries Ltd sit within the mid-tier specialist category serving regional supermarket and pharmacy retail networks.
| Leading Market Players |
|---|
| HP Inc |
| Canon Inc |
| Seiko Epson Corporation |
| Ricoh Company Ltd |
| Brother Industries Ltd |
| Konica Minolta Inc |
| Xerox Holdings Corporation |
| Kyocera Corporation |
| Oki Electric Industry Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Third-party logistics operators and supermarket chains concentrate procurement volume, anchoring contract-based long-term offtake structures that privilege suppliers with captive nozzle fabrication capabilities.
Pricing Analysis
Volume concentrates in silent thermal receipt printers for 24/7 supermarket deployments, while margin pools cluster in piezoelectric MEMS label printers serving GS1-compliant e-commerce fulfillment. Price differentiation rests on nozzle density specifications and Energy Star certification tiers, with premium tiers commanding position through sub-picoliter droplet precision. Cost compression in entry-level thermal mechanisms is intensifying because domestic Chinese brands are absorbing tier-two and tier-three city share. Small retailers exhibit highest price sensitivity, while e-commerce fulfillment operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from e-commerce fulfillment operators mandate multi-supplier qualification for piezoelectric MEMS printhead arrays, forcing OEMs to qualify secondary nozzle fabricators. Manufacturing concentrates in Japan, Taiwan, and China, with photolithography expertise anchoring in Japanese semiconductor equipment corridors. Raw material dependencies include silicon wafers, piezoelectric ceramics, and thermal paper substrates. Single-source vulnerability concentrates in captive foundry partnerships for high-density nozzle arrays. Distribution runs through OEM direct sales for enterprise accounts and regional distributors serving small retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign modular repair mandates are accelerating consolidation by elevating non-recurring engineering costs beyond mid-tier specialist capacity, forcing weaker players toward exit or acquisition.
For Market Incumbents: Deploy hardware-as-a-service contract structures to lock in e-commerce fulfillment operators before domestic Chinese brands achieve SAMR certification parity. Deepen captive silicon foundry partnerships to defend nozzle density advantages against emerging piezoelectric MEMS specialists. Accelerate power supply redesigns to capture EPA Energy Star procurement preference in US federal retail contracts.
For New Entrants and Emerging Players: Capture tier-two and tier-three China retail networks where SAMR electromagnetic compatibility timelines delay imported hardware entry by 8-14 months. Target pharmacy and small grocery chains in India where Bureau of Indian Standards certification barriers favor domestic assembly operations. Lead with USB-connected thermal units priced below legacy impact printer replacement cycles.
For Investors and Strategic Acquirers: The window for entry favors piezoelectric MEMS printhead specialists with semiconductor fabrication process expertise, as nozzle density intellectual property becomes the primary competitive moat. Watch for inflection when right-to-repair litigation forces firmware-locked consumable strategies toward open-architecture redesigns, compressing recurring revenue multiples for hardware-dependent vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hardware Architecture Redesign | EU Ecodesign compliance extends equipment lifespan and creates aftermarket service revenue pools. |
| Captive Silicon Foundry Partnership | Locked nozzle density advantages at consumer price points defend margin against thermal inkjet displacement. |
| Hardware-as-a-Service Launch | Per-print pricing transfers obsolescence risk to vendors and aligns with corporate sustainability mandates. |
| Photolithography Precision Investment | Sub-picoliter droplet control sustains premium positioning in photo-specialist retail channels. |
| GS1 Compliance Certification | Barcode serialization capability gates entry to third-party logistics contracts with e-commerce platforms. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with POS hardware procurement managers, supermarket operations directors, third-party logistics automation leads, and piezoelectric MEMS fabrication engineers. Secondary sources included EPA Energy Star certification databases, EU Ecodesign implementing measure texts, SAMR GB standard electromagnetic compatibility test reports, and SEC 10-K disclosures from listed printer OEMs. Bottom-up shipment tallies by product type and connectivity tier were reconciled with top-down market value estimates across the analysis window.
Data-stream reconciliation across thermal printer refresh cycles, inkjet adoption curves in e-commerce fulfillment, and hardware-as-a-service contract penetration enabled segmentation modeling by product type, end user, connectivity protocol, and operating environment. CAGRs were derived from fitted growth curves calibrated to replacement cycle compression in supermarket self-service kiosk deployments and piezoelectric MEMS absorption of thermal inkjet label production. Industry-specific inputs included GS1 barcode serialization compliance rates and SAMR certification timeline distributions for imported POS peripherals.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to right-to-repair regulatory enforcement trajectories and piezoelectric MEMS process engineering talent availability. Deviation in EU Ecodesign repairability mandate implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Nordic Commercial Printing Market
Printing Technology
ID Card Printers Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
US Print on Demand Market
Printing Technology
Professional Printers Market
Printing Technology
Digital Production Printer Market
Printing Technology
Web to Print Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
Photo Printing Market
Printing Technology
Cloud Print Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Global Microprinting Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Roll to Roll Printing Market