
 Home Wi-Fi Security Solutions Market | 2026-2036
Home Wi-Fi Security Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Home Wi-Fi Security Solutions Market Foresight
Subscription-based hardware leasing is reshaping competitive entry in home Wi-Fi security, lowering upfront barriers for tenants and small business owners while shifting vendor economics toward recurring revenue. Cisco Systems leverages its enterprise threat-intelligence backbone to anchor premium residential offerings. TP-Link Technologies competes aggressively on manufacturing scale across Asia and Europe. Bitdefender differentiates through AI-powered behavioral detection engines purpose-built for consumer routers.
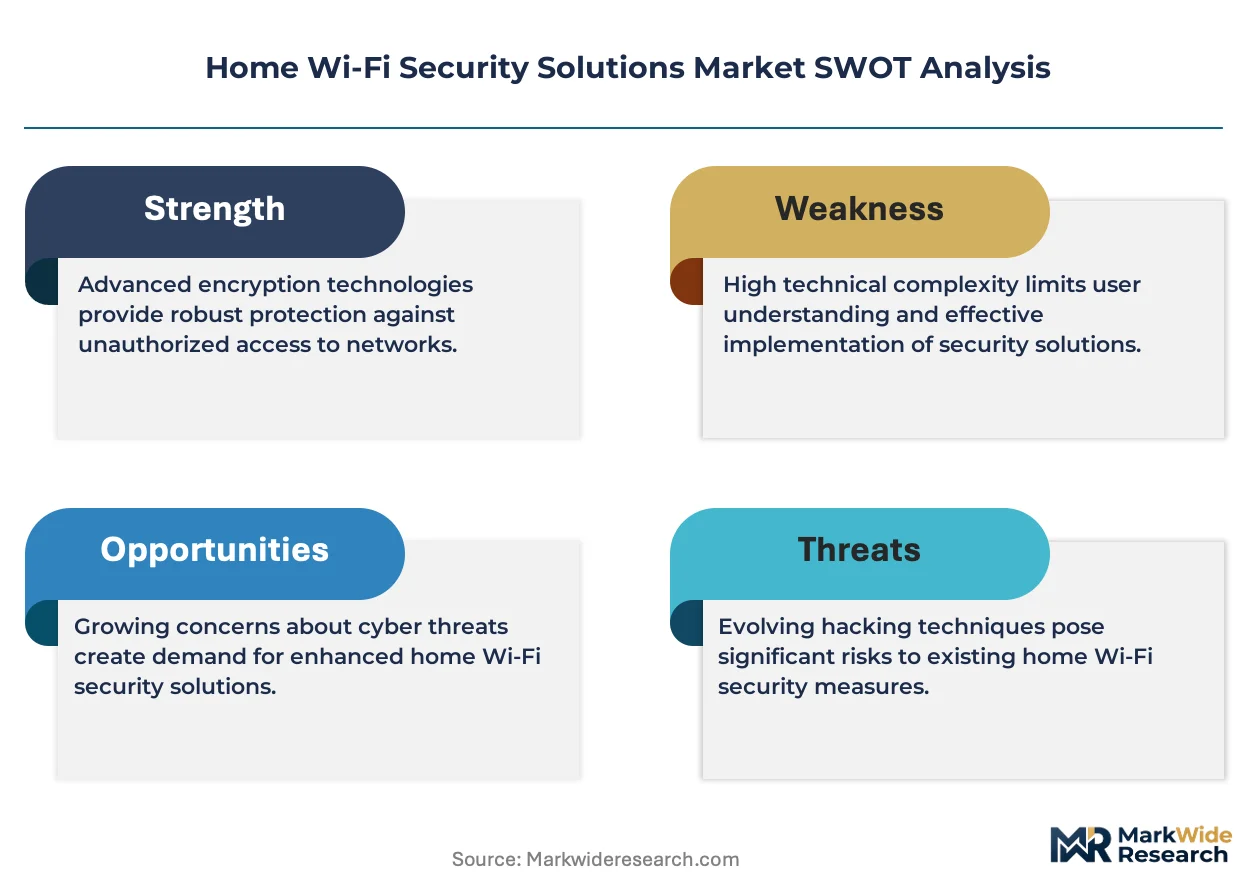
Home Wi-Fi security solutions encompass hardware appliances, embedded software, and cloud-managed services that encrypt traffic, detect unauthorized access, and isolate compromised IoT endpoints using protocols such as WPA3 and AES-256. Their primary purpose is to protect residential and micro-business networks against credential theft, botnet recruitment, and lateral movement by threat actors. Firewall and VPN product types command the largest installed base, though cloud-based deployment is expanding fastest as vendors offload processing to distributed edge infrastructure. IoT protection applications sit at the highest margin tier due to firmware complexity and recurring threat-signature updates.
FCC broadband labeling rules in the United States now require ISPs to disclose security features, indirectly steering subscriber demand toward bundled protection. ECHA chemical restrictions on router plastics and REACH compliance costs affect hardware sourcing for European vendors. Japan's METI cybersecurity framework for consumer devices mandates baseline encryption standards. Stakeholders must weigh whether to absorb regulatory compliance costs or pass them through via tiered service packaging.
Market Dynamics
Subscription-based hardware leasing is restructuring competitive entry economics, collapsing upfront tenant barriers while locking vendors into recurring revenue models that demand continuous threat-intelligence investment.
Growth Catalysts
- Fiber-to-the-home acceleration:Germany, the United States, and Japan are expanding endpoint vulnerability surfaces as gigabit rollouts multiply attack vectors requiring automated segmentation.
- EU AI Act enforcement:Baseline cybersecurity obligations for connected home devices are tightening compliance requirements that vendors must embed at firmware layer.
- Enterprise VPN spillover:Remote-first small business owners are importing zero-trust architectures into residential settings, normalizing hardware-based encryption.
Market Restraints
- REACH chemical compliance:ECHA restrictions on router plastics elevate European hardware sourcing costs and compress margin on entry-tier units.
- Cloud infrastructure concentration:Threat-signature processing dependency on hyperscale edge nodes creates single-point-of-failure exposure for distributed detection services.
- Silicon supply fragility:Advanced encryption chip fabrication concentrates in East Asian foundries, exposing lead-time volatility for WPA3-enabled appliance vendors.
Strategic Opportunities
- IoT protection margin tier:Firmware complexity and recurring signature updates for smart home endpoints command premium pricing relative to baseline firewall offerings.
- FCC broadband labeling:Mandated ISP security disclosure requirements are steering subscriber demand toward bundled protection packages.
- AI-behavioral convergence:Machine learning inference engines deployed at router edge are enabling real-time anomaly detection without cloud round-trip latency.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for resource-constrained router chipsets requires specialized skills that outpace vocational pipeline output.
- Cross-border certification fragmentation:Divergent encryption export controls between jurisdictions elongate product launch timelines for multi-region hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Wi-Fi Security Solutions Market |
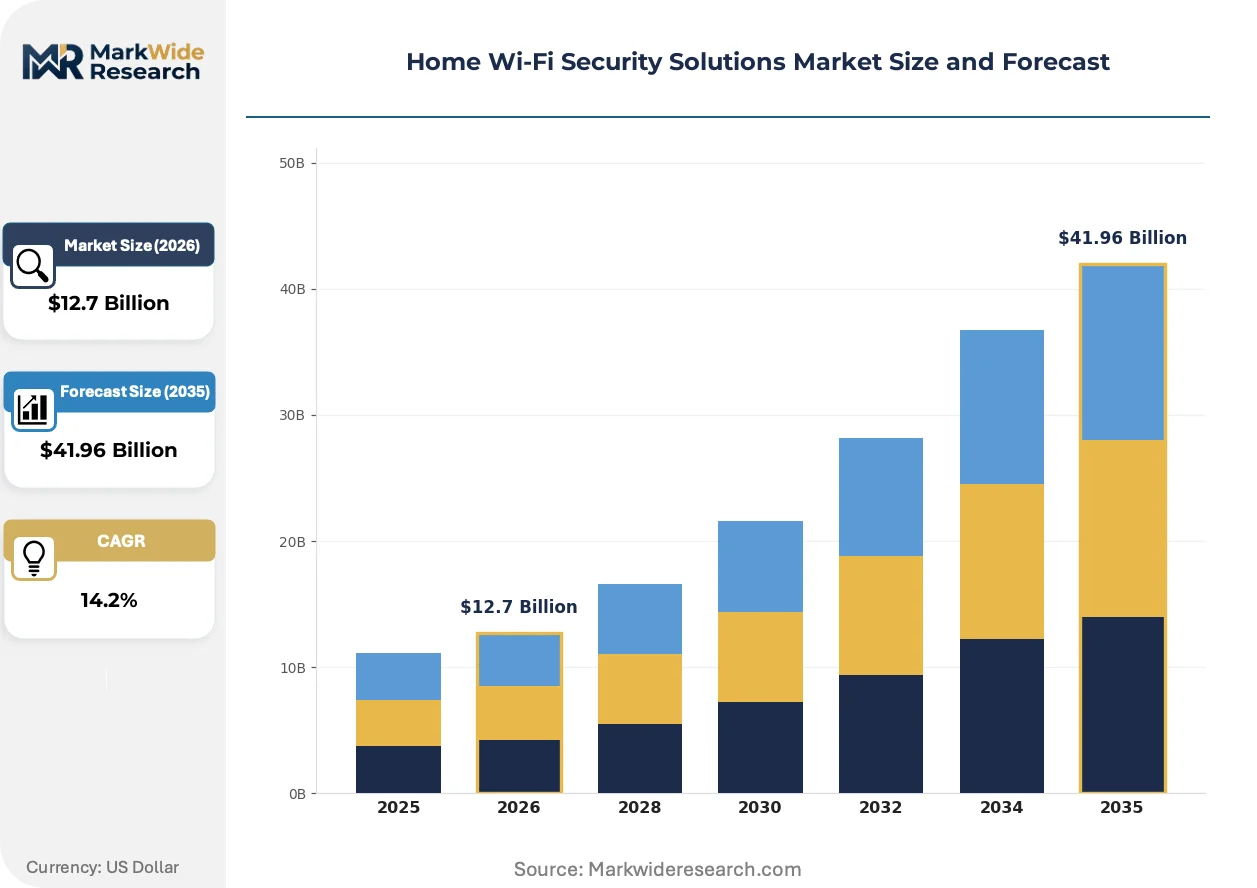
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewall, Intrusion Detection System, VPN, Antivirus Technology: Hardware, Software, Cloud-Based, On-Premises Application: Residential Use, Small Office, Campus Network, IoT Protection End User: Homeowners, Tenants, Small Business Owners, Families |
| Companies Covered | Cisco Systems, Inc., Netgear, Inc., TP-Link Technologies Co., Ltd., Eero LLC, ASUS Tek Computer Inc., D-Link Corporation, Ubiquiti Inc., Bitdefender, Trend Micro Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Wi-Fi Security Solutions Market Shifts & Advancements
Threat detection architectures are relocating processing gravity from centralized clouds toward distributed edge nodes, compressing response latency while fragmenting vendor competitive moats around data-pipeline scale.
AI-powered behavioral analysis is migrating from signature-based pattern matching toward on-device inference models that identify anomalous IoT traffic without external telemetry. Residential gateway manufacturers in Japan and Germany are embedding tensor accelerators into mid-tier chipsets. This migration from cloud-dependent detection is collapsing the latency window for botnet containment from minutes to milliseconds.
METI's cybersecurity framework for consumer devices now mandates baseline encryption standards that disqualify legacy WPA2-only hardware from Japanese retail channels. Vendors must either absorb firmware upgrade engineering costs or abandon shelf presence in the world's third-largest connected-device market. The directive is forcing accelerated end-of-life programs for pre-2023 router inventories.
Hardware-as-a-service contracting is displacing perpetual purchase models among urban rental populations and distributed small business networks. ISPs in the United States are bundling leased security appliances with fiber subscriptions, capturing equipment margin that previously accrued to retail channels. This shift concentrates buyer power among telecommunications carriers and compresses standalone hardware vendor pricing autonomy.
Home Wi-Fi Security Solutions Market Segmentation
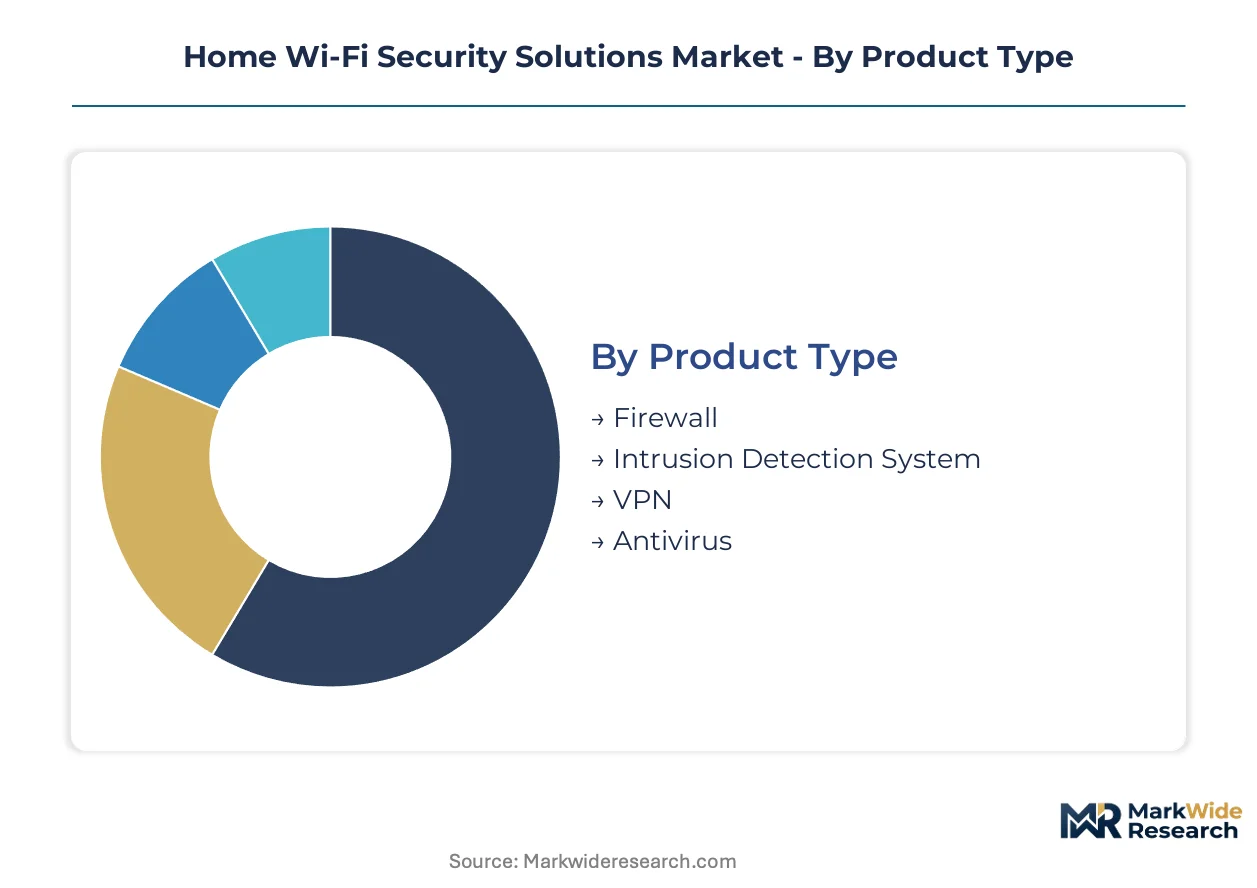
Home Wi-Fi security solutions fragment across four critical dimensions that determine deployment architecture, procurement channels, and vendor margin structure. Each segmentation axis reveals distinct competitive dynamics between appliance manufacturers, cloud service providers, and telecommunications carriers.
Product Type:
Deployment scenarios span from perimeter defense to encrypted tunneling, with each product category addressing specific threat vectors in residential and micro-business environments.
- Firewall:Hardware appliances enforce traffic rules through stateful packet inspection and application-layer filtering. Demand concentrates among small business owners in Germany importing enterprise-grade segmentation into home offices, driven by NIS2 Directive compliance deadlines.
- VPN:Encrypted tunneling solutions route traffic through remote servers to mask IP addresses and bypass geographic restrictions. Remote-first professionals across the United States are normalizing always-on VPN clients, accelerating subscription attach rates to fiber broadband bundles.
- Intrusion Detection System:Signature-based and behavioral monitors alert users to anomalous network activity requiring manual response.
- Antivirus:Endpoint scanning tools detect malware on connected devices through definition databases and heuristic analysis.
The dominant share belongs to Firewall, while VPN is closing the gap fastest.
Technology:
Cost tiers separate capital-intensive hardware ownership from operational expenditure models favoring recurring SaaS contracts.
- Cloud-Based:Threat intelligence and policy management offload processing to vendor-controlled edge infrastructure, enabling seamless updates without user intervention. Japanese households under METI's cybersecurity framework are migrating from on-premises appliances to cloud-managed gateways, eliminating firmware maintenance burdens.
- Hardware:Dedicated appliances with embedded encryption chips provide deterministic performance independent of internet connectivity. German tenants in fiber-connected urban centers prefer leased hardware bundles that transfer obsolescence risk to ISPs.
- Software:Agent-based protection installed on endpoints or existing routers through firmware updates.
- On-Premises:Locally hosted management platforms requiring dedicated server infrastructure within the residence.
Cloud-Based deployments are expanding most quickly, though Hardware retains the largest installed base among security-conscious small business owners.
Application:
Customer type determines feature complexity, with enterprise-derived capabilities filtering down to consumer segments through simplified interfaces.
- IoT Protection:Specialized firmware isolates smart home devices into network segments with restricted lateral movement permissions. Japanese and German markets show concentrated demand as connected appliance penetration exceeds fifty devices per household, triggering automated containment requirements.
- Residential Use:Single-family homes and apartments requiring straightforward protection for personal devices and streaming equipment. United States homeowners responding to FCC broadband labeling rules are prioritizing visible security features in ISP comparison shopping.
- Small Office:Home-based businesses with 2-10 employees needing guest network isolation and compliance documentation.
- Campus Network:Multi-dwelling units and co-living spaces with shared infrastructure requiring tenant-level policy enforcement.
Residential Use commands the dominant share, while IoT Protection is gaining share fastest as device density compounds vulnerability exposure.
End User:
Procurement authority varies across tenure status and organizational scale, fragmenting go-to-market strategies between retail, ISP, and employer channels.
- Small Business Owners:Self-employed professionals and micro-enterprises importing zero-trust architectures from corporate environments. United States remote workers are driving hardware VPN appliance sales as employer security policies extend into home networks.
- Tenants:Rental populations in urban Germany and Japan favoring subscription-based hardware leasing with zero upfront capital commitment, compressing margin for standalone retail vendors.
- Homeowners:Property owners with permanent installation flexibility and higher willingness to purchase perpetual licenses.
- Families:Multi-user households prioritizing parental controls and content filtering over advanced threat detection.
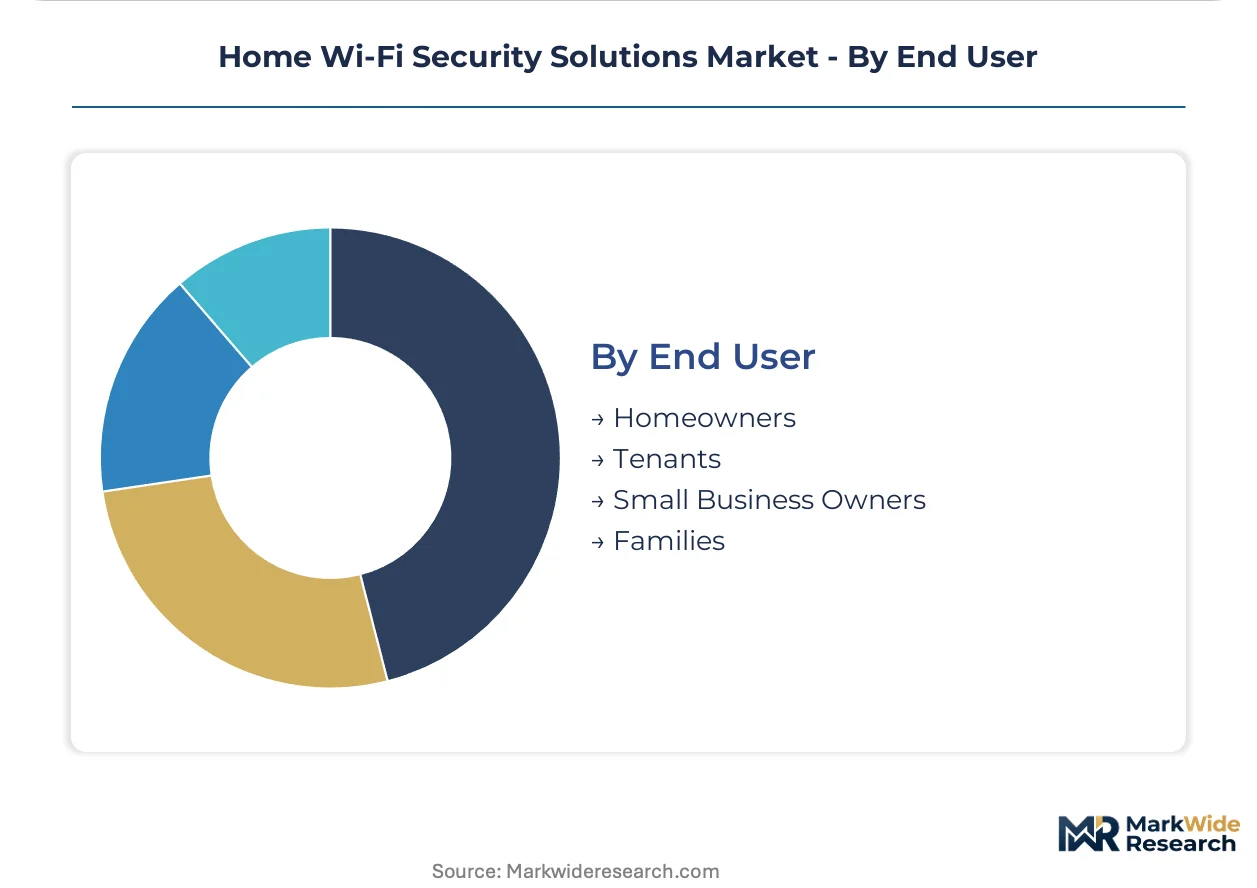
Small Business Owners represent the most valuable segment per account, while Tenants are climbing the fastest as leasing models reshape competitive entry economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in home Wi-Fi security hardware tilt toward net import dependence in Europe and Japan, while the United States maintains near-balanced exchange with selective Asian sourcing for encryption chipsets. Component specialization concentrates in East Asian foundries, forcing Western vendors to absorb currency and logistics volatility.
United States
FCC broadband labeling rules now compel ISPs to disclose security features, steering subscriber comparison shopping toward bundled protection packages. The 2024 infrastructure bill's digital equity provisions accelerate fiber-to-the-home deployment across secondary metros, multiplying endpoint vulnerability surfaces. Austin and Denver clusters host emerging vendors developing AI-native behavioral detection for residential gateways.
Germany
NIS2 Directive compliance deadlines drive small business owners to import enterprise-grade segmentation into home offices, collapsing the distinction between residential and commercial security procurement. ECHA REACH restrictions on router plastics elevate hardware sourcing costs and compress margins on entry-tier units. Munich and Berlin anchor the EU's densest concentration of cybersecurity engineering talent for firmware development.
Japan
METI's cybersecurity framework for consumer devices mandates baseline encryption standards that disqualify legacy WPA2-only hardware from retail channels, forcing accelerated end-of-life programs. Fiber penetration exceeds ninety percent in urban centers, creating saturated markets where vendors compete on IoT protection sophistication rather than connectivity speed. Tokyo-Osaka corridor manufacturers embed tensor accelerators into mid-tier chipsets for on-device inference.
United Kingdom
Post-Brexit regulatory divergence from EU product safety frameworks elongates certification timelines for multi-region hardware vendors. London's fintech density generates concentrated demand for hardware VPN appliances among remote-first professionals handling sensitive financial data. Cambridge cluster researchers advance lightweight cryptographic protocols for resource-constrained IoT endpoints.
South Korea
MFDS-aligned cybersecurity standards for connected medical devices spill over into residential network protection requirements, tightening firmware validation protocols. Government-backed K-Network 2030 initiatives subsidize gigabit router upgrades in apartment complexes, standardizing WPA3 adoption. Seoul Capital Area chaebol affiliates dominate domestic manufacturing while exporting white-label hardware to Southeast Asian markets.
Home Wi-Fi Security Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encryption chipsets and threat-intelligence feeds. The vendor base arranges into three tiers: telecommunications carriers capturing equipment margin through leased appliance bundles; enterprise security incumbents extending threat-intelligence backbones downward; and pure-play residential specialists competing on manufacturing scale. Dominant competitive moves include strategic partnerships between ISPs and hardware vendors, plus portfolio diversification into adjacent IoT protection services.
Within the enterprise-extension archetype, Cisco Systems anchors premium residential offerings through threat-intelligence backbone leverage. TP-Link Technologies occupies a position exemplifying manufacturing-scale competition across Asian and European retail channels. Bitdefender represents the AI-native specialization tier, anchoring behavioral detection engines purpose-built for consumer router deployment. These three patterns illustrate how vendor economics shift toward recurring revenue as subscription-based hardware leasing displaces perpetual purchase models.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Netgear, Inc. |
| TP-Link Technologies Co., Ltd. |
| Eero LLC |
| ASUS Tek Computer Inc. |
| D-Link Corporation |
| Ubiquiti Inc. |
| Bitdefender |
| Trend Micro Incorporated |
| Others |
Supply & Pricing Matrix
The Shanghai-Los Angeles maritime corridor's freight volatility transmits directly into landed costs for WPA3 encryption chipsets, compressing margin on entry-tier hardware while amplifying price spreads between cloud-managed subscriptions and perpetual appliance licenses. This logistics-cost asymmetry rewards vendors with captive Asian manufacturing footprints and penalizes retail-channel distributors dependent on spot-market component procurement.
Pricing Analysis
Small business owners anchor pricing structure across three tiers: premium hardware appliances with embedded AI accelerators, standard cloud-managed gateways, and economy firmware-upgrade licenses for existing routers. Price differentiation hinges on NIS2 Directive certification grade and bundled threat-intelligence update frequency. Pricing pressure stems from ISP bundling programs that capture equipment margin previously accruing to retail channels. Tenants exhibit highest price sensitivity due to zero-upfront leasing preferences, while remote-first professionals handling financial data show lowest sensitivity to hardware VPN premiums.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities anchored in Singaporean banking networks sustain liquidity for encryption-chip procurement during silicon allocation cycles. Geographic supply concentration centers on Taiwan for advanced semiconductor fabrication, China for PCB assembly and plastic molding, and Vietnam for final appliance integration. Raw material dependencies include gallium nitride substrates, AES-256 encryption cores, and REACH-compliant router housings. Single-source vulnerability concentrates in East Asian foundry capacity for WPA3-enabled chipsets. Distribution runs through telecommunications carrier bundling programs, direct-to-consumer e-commerce platforms, and enterprise IT channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from hyperscaler edge-security services that collapse router-based protection into cloud-native residential offerings, requiring defensive architecture decisions.
For Market Incumbents: Insulate recurring revenue streams by deepening captive threat-intelligence infrastructure and accelerating METI-compliant firmware certification for Japanese retail presence. Vertical integration into tensor-accelerator chipset design reduces dependency on Taiwanese foundry allocation cycles. Channel control through ISP-exclusive bundling partnerships defends against Amazon and Google cloud-security encroachment. For New Entrants and Emerging Players: Build out AI-native behavioral detection capabilities targeting the IoT protection tier, where firmware complexity and signature-update subscriptions command premium pricing. The most penetrable white space sits in German small-business NIS2 compliance, where enterprise-grade segmentation demand outpaces incumbent residential product roadmaps. A direct-to-MSP go-to-market angle bypasses carrier-dominated consumer channels. For Investors and Strategic Acquirers: Carve-out targets emerge from enterprise cybersecurity parents seeking to divest consumer-router divisions amid strategic refocusing on zero-trust enterprise architectures. Long-term viability favors vendors with recurring revenue exceeding sixty percent of total sales and captive edge-infrastructure deployment. The signal to watch is FCC broadband-labeling enforcement intensity, which accelerates ISP bundling concentration and compresses standalone hardware vendor exit multiples.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Behavioral Detection Development | Tensor-accelerator embedding in mid-tier chipsets enables millisecond-latency botnet containment without cloud telemetry. |
| ISP Bundling Partnership Expansion | FCC disclosure rules steer subscriber comparison shopping toward carrier-integrated security packages. |
| Backward Integration into Encryption Chipsets | Captive WPA3 core design insulates against East Asian foundry allocation volatility and lead-time compression. |
| IoT Protection Service Tier Launch | Firmware segmentation for fifty-plus device households commands recurring signature-update premiums in Japan and Germany. |
| METI/NIS2 Certification Fast-Track | Baseline encryption compliance accelerates shelf presence in Japanese retail and German small-business procurement channels. |
Research Methodology
The analysis maps firewall appliances, VPN gateways, intrusion detection systems, and IoT protection firmware, each validated through CTOs at residential gateway manufacturers, ISP product managers, cybersecurity firmware engineers, and enterprise IT procurement officers. Primary interview findings were cross-referenced against FCC broadband labeling disclosures, METI cybersecurity framework documentation, EU NIS2 Directive implementation guidance, and SEC filings from publicly traded networking vendors. Bottom-up unit-economics modeling triangulated against top-down addressable-market sizing from fiber-deployment databases.
Assumptions held fixed across the projection horizon include sustained fiber-to-the-home rollout velocity in Germany, the United States, and Japan; steady-state EU AI Act enforcement intensity; and continued hyperscaler cloud-infrastructure concentration. Segmentation dimensions modeled span product type, deployment technology, application use case, and end-user procurement authority. CAGRs were derived from regression-weighted historical attach rates projected against broadband subscriber growth curves and IoT device penetration forecasts. Industry-specific inputs include threat-signature update frequency elasticity and ISP bundling penetration assumptions.
Stress conditions across silicon foundry allocation cycles, REACH chemical compliance cost trajectories, and hyperscaler cloud-security substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and infrastructure deployment cadence. Macroeconomic contraction, accelerated encryption export-control fragmentation, or breakthrough quantum-resistant protocol standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
Data Protection Market
Cybersecurity
Global Breach and Attack Simulation Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Romania Cybersecurity Market
Cybersecurity
Global Mobile Anti Malware Market
Cybersecurity
Smart Grid Cyber Security Market
Cybersecurity
Cybersecure Vehicle Control Unit Gateway Systems Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
DNS Firewall Market
Cybersecurity
South Africa Cybersecurity Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
Greece Cybersecurity Market