
 Global Web to Print Software Market | 2026-2036
Global Web to Print Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Web to Print Software Market Foresight
Modular solution bundling is restructuring buyer choice across the Global Web to Print Software Market, as vendors unbundle design automation from order management to capture price-sensitive print service providers. Xerox Corporation leverages its hardware-software integration to dominate enterprise accounts, while CHILI publish NV anchors its position through advanced template rendering engines for brand management workflows. Electronics For Imaging, Inc. competes on color management fidelity across hybrid cloud deployments.
Web to print software comprises browser-based platforms that connect end users to production print systems through automated prepress workflows, typically supporting PDF/X compliance, ICC color profiling, and JDF-enabled job ticketing for direct-to-press output. The primary commercial purpose centers on eliminating manual prepress intervention while enabling non-designers to configure and order printed materials through self-service portals. Cloud-based deployment leads in new customer acquisition due to lower capital barriers, though on-premise installations retain margin pools among security-sensitive corporate marketing teams. Order management solutions represent the most mature segment, while variable data printing commands premium pricing through personalization capabilities.
The EU's GDPR and the Digital Services Act shape product architecture requirements for data residency and audit trails across European deployments, while the US FDA regulates pharmaceutical labeling workflows that integrate with web-to-print systems for compliant package inserts. ISO 12647 color standards and JDF specifications from CIP4 govern interoperability between software layers and production equipment. Stakeholders must monitor how AI-generated content detection requirements from regulators will force template verification protocols into core platform roadmaps.
Market Dynamics
Cloud migration is compressing deployment cycles across print service providers, while GDPR audit mandates and the EU Digital Services Act force architectural redesigns toward data-resident, verifiable workflow stacks.
Growth Catalysts
- GDPR Compliance Architecture:The EU's data residency and audit trail requirements are accelerating replacement of legacy on-premise installations with cloud-native platforms that embed cryptographic job logging and territorial data sovereignty.
- Variable Data Printing:Brand marketers in retail and pharmaceuticals are deploying personalization engines that merge CRM feeds with template-based composition, driving premium-tier software procurement.
- German Print Cluster Density:Mid-sized print service providers in Baden-Württemberg and Bavaria are consolidating procurement through regional buying cooperatives, creating concentrated demand pools for modular SaaS bundles.
Market Restraints
- Color Management Hardware Dependency:ICC profiling accuracy requires calibrated spectrophotometers and closed-loop ink systems, locking software vendors into hardware partnerships that compress margin flexibility.
- Legacy JDF Integration Debt:CIP4 specification fragmentation across press generations forces costly middleware development for each equipment vintage, slowing cloud-native platform rollout.
- Substitution by Digital-First Communication:Corporate marketing departments in financial services and technology verticals are displacing print volumes with interactive PDF and personalized video, capping addressable market expansion.
Strategic Opportunities
- India's PLI-Backed Manufacturing Labels:Production-linked incentive schemes for electronics and pharmaceuticals are expanding compliant packaging print volumes, creating entry points for audit-capable web-to-print platforms.
- AI Content Detection Mandates:Emerging regulatory requirements for generative-AI watermarking and provenance verification are opening adjacent modules for template authentication and synthetic-media flagging.
- Hybrid Cloud-Edge Deployment:Convergence of containerized microservices with on-premise RIP acceleration is enabling new architectures that satisfy both security-sensitive corporate marketing teams and cost-sensitive commercial printers.
Industry Challenges
- Prepress Automation Skill Collapse:Retirement waves among operators trained on Adobe Acrobat Pro and Esko Automation Engine workflows are creating talent bottlenecks for complex variable-data job setup.
- ISO 12647 Certification Timelines:Color standard compliance requires extended press characterization and proofing correlation cycles, delaying go-live dates for new customer deployments by six to twelve months.
- API Fragmentation Across MIS Systems:Integration complexity with enterprise resource planning platforms from EFI, Heidelberg, and homegrown installations consumes disproportionate implementation engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Web to Print Software Market |
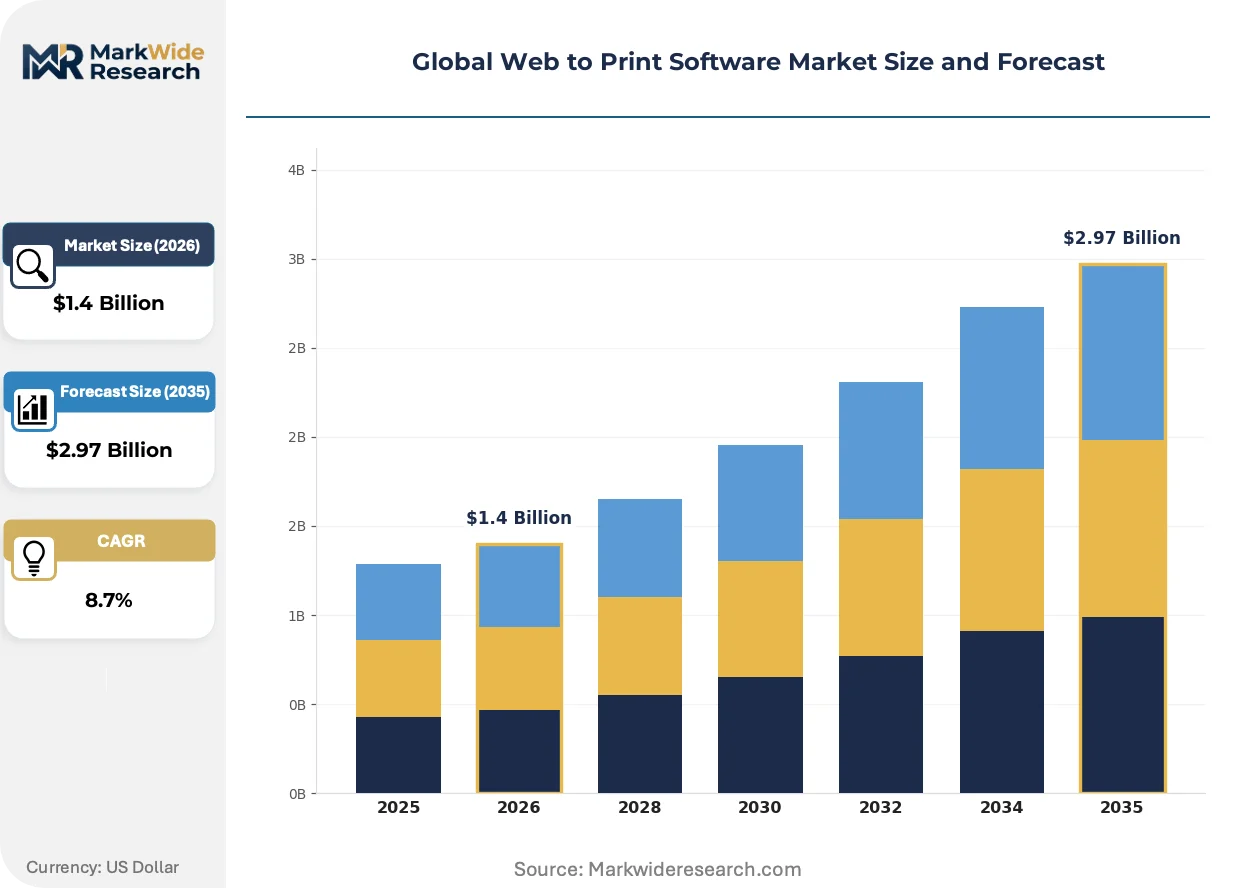
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Managed Services Solution Type: Order Management, Design Automation, Workflow Integration, Variable Data Printing, Brand Management Application: Commercial Printing, Packaging Design, Promotional Materials, Marketing Collateral, Personalized Gifts End User: Print Service Providers, Corporate Marketing Teams, Educational Institutions, Non-Profit Organizations, Event Management Firms |
| Companies Covered | Xerox Corporation, CHILI publish NV, Design'N'Buy, DATATECH SMARTSOFT, INC., Agfa-Gevaert Group, OnPrintShop, Aleyant Systems, LLC, Vpress Ltd., Electronics For Imaging, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Web to Print Software Market Shifts & Advancements
Template rendering engines are absorbing AI-assisted composition capabilities, while regulatory pressure on data provenance is embedding verification protocols into core platform architectures. Buyer expectations are compressing around self-service configurability.
Headless browser-based composition engines are expanding into brand management workflows, separating front-end design interfaces from back-end RIP processing. Marketing teams at consumer packaged goods manufacturers are adopting these decoupled architectures to accelerate localization without IT dependency. This separation is expanding into multi-tenant SaaS platforms that serve distributed franchise networks through centralized template governance.
REACH substance restrictions and the EU AI Act are mandating disclosure of algorithmic decision-making in automated layout systems, forcing vendors to document template variation logic and color substitution rules. Industrial consequence includes mandatory audit logs for pharmaceutical label generation workflows that feed regulated supply chains. German packaging printers serving export markets are responding by pre-certifying platforms through notified body assessments before customer deployment.
Self-service procurement portals are displacing traditional sales-engineer involvement in routine job specification, with mid-market print service providers unbundling design services from production execution. Channel disruption concentrates in North American commercial printing, where marketing procurement platforms like Coupa and SAP Ariba are absorbing web-to-print functionality through API integration. This behavioral shift is most visible in healthcare and higher education verticals, where centralized purchasing mandates favor pre-approved supplier catalogs over direct vendor relationships.
Global Web to Print Software Market Segmentation
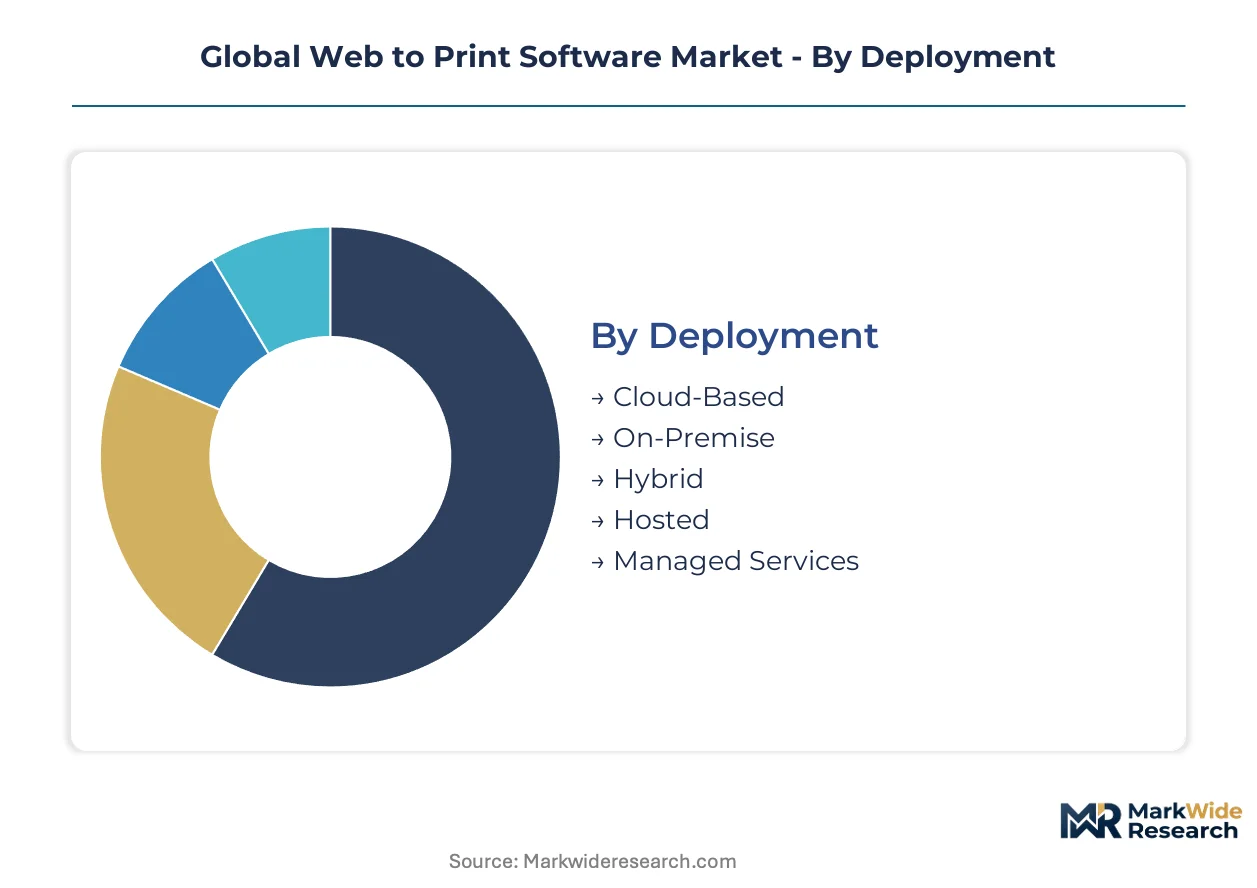
Web-to-print software segmentation reveals how vendor specialization aligns with divergent customer technical debt and compliance postures. Deployment architecture and solution modularity determine pricing power and implementation velocity across buyer tiers.
Deployment:
Supply concentration among hyperscale infrastructure providers is compressing margins for independent SaaS vendors while accelerating feature parity.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute pools eliminate capital expenditure barriers for mid-sized print service providers. German and French commercial printers dominate procurement volumes, driven by GDPR-mandated data residency certifications from vendors.
- On-Premise:Licensed software deployed behind customer firewalls retains favor among pharmaceutical marketing teams subject to FDA 21 CFR Part 11 validation requirements. Security-sensitive corporate legal departments in US financial services sustain this segment despite higher total cost of ownership.
- Hybrid:Containerized orchestration layers split job intake and rendering workloads across cloud edge nodes and local RIP acceleration. Japanese automotive marketing teams leverage this architecture for localized brochure production with centralized brand governance.
- Hosted:Single-tenant dedicated instances in vendor-managed data centers bridge compliance and operational simplicity. Indian pharmaceutical exporters favor this model for CDSCO audit trail requirements without internal IT overhead.
- Managed Services:Fully outsourced platform operations including template maintenance and color profile management. Australian franchise print networks adopt this to offset prepress automation skill shortages.
Cloud-based deployments absorb the bulk of installed capacity; hybrid architectures are expanding most quickly among security-conscious multinationals.
Solution Type:
Customer willingness to pay varies sharply by functional depth, with workflow automation commanding premiums over commodity order capture.
- Order Management:Mature job ticketing, estimation, and production scheduling modules with JDF-enabled press connectivity. North American commercial printers treat this as table stakes, compressing vendor margins through competitive benchmarking.
- Design Automation:Browser-based template configurators with rule-based layout engines and real-time preflight. Brand management teams at consumer packaged goods manufacturers in Germany and Switzerland drive premium-tier procurement for localization velocity.
- Workflow Integration:API middleware connecting web-to-print front ends to MIS, ERP, and fulfillment systems. Mid-market print service providers in Bavaria prioritize this to consolidate vendor relationships.
- Variable Data Printing:CRM-fed personalization engines merging database fields with template composition. Pharmaceutical marketers in the US and EU deploy this for compliant patient communication programs.
- Brand Management:Centralized template governance with version control and distributed franchise access. Quick-service restaurant chains across India leverage this for localized menu production under corporate visual standards.
Order management solutions carry the largest installed base; variable data printing exhibits the steepest expansion trajectory as personalization mandates intensify.
Application:
End-use verticals impose divergent compliance and color fidelity requirements that reshape vendor feature roadmaps.
- Commercial Printing:General-purpose document production including business stationery, reports, and direct mail. Volume concentration among German Mittelstand print houses sustains competitive pricing pressure.
- Packaging Design:Structural design integration with dieline validation and substrate specification workflows. Indian electronics manufacturers under PLI schemes drive demand for audit-capable label generation.
- Promotional Materials:Time-sensitive campaign collateral with rapid turnaround requirements. Event management firms in Dubai and Singapore prioritize this segment for trade show and conference production.
- Marketing Collateral:Brand-compliant brochures, datasheets, and sales tools with localization variants. US technology vendors distribute procurement through SAP Ariba and Coupa platforms.
- Personalized Gifts:Photo books, custom apparel, and commemorative items with consumer-facing design interfaces. Japanese and South Korean consumer markets sustain specialized platform providers.
Commercial printing retains dominant volume share; packaging design is climbing the fastest on regulatory labeling complexity.
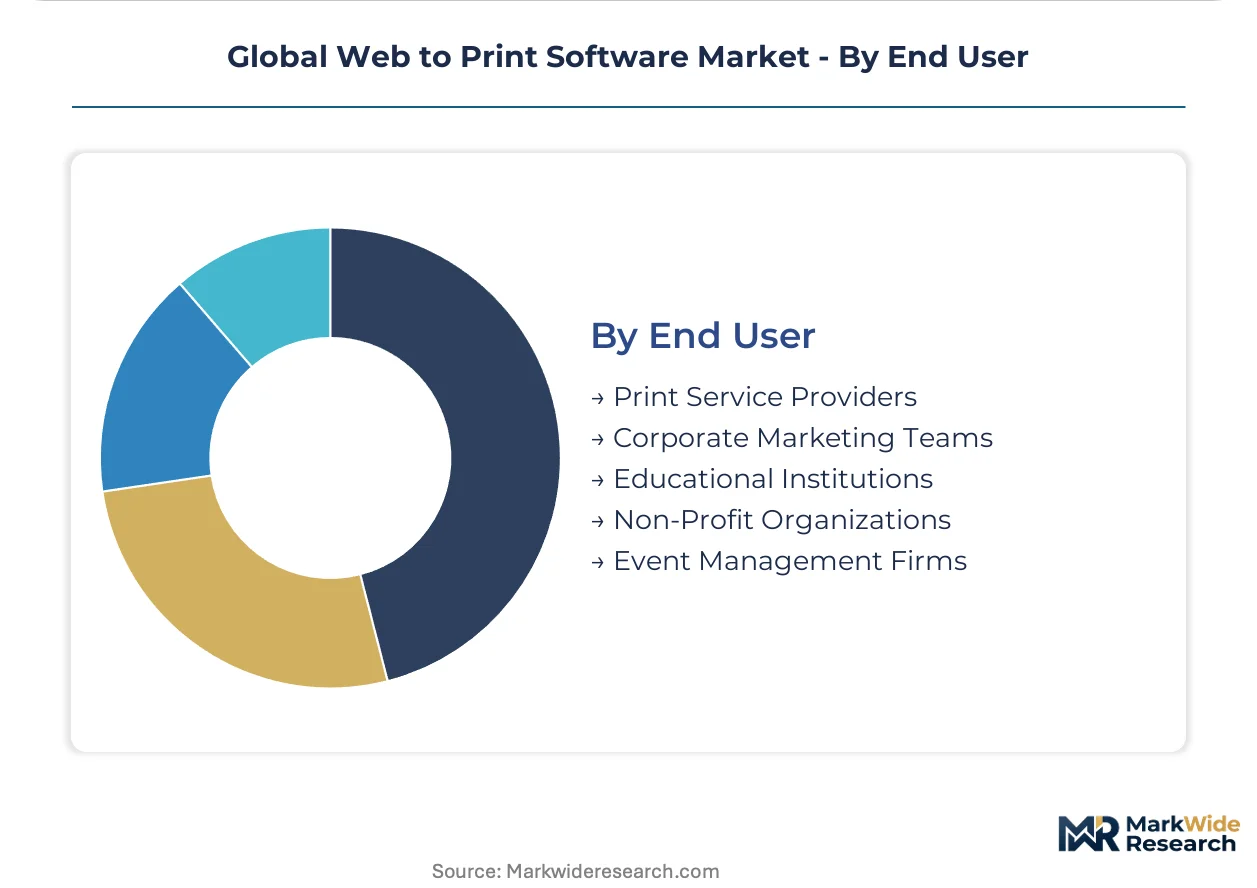
End User:
Procurement authority is shifting from production departments to enterprise marketing and centralized purchasing functions.
- Print Service Providers:Commercial production houses serving B2B and B2C print demand. Consolidation among Baden-Württemberg and Bavarian cooperatives is concentrating vendor negotiation leverage.
- Corporate Marketing Teams:In-house brand departments managing distributed print procurement. US healthcare and higher education verticals favor pre-approved supplier catalogs over direct vendor engagement.
- Educational Institutions:University presses and campus print shops with course material and event production needs. Budget constraints favor open-source and low-cost SaaS alternatives.
- Non-Profit Organizations:Fundraising collateral and awareness campaign production with donor-funded technology budgets. Grant compliance requirements favor auditable workflow platforms.
- Event Management Firms:Temporary and recurring large-format production for conferences, exhibitions, and corporate events. Asia-Pacific convention centers drive seasonal demand spikes.
Print service providers command the largest addressable base; corporate marketing teams are gaining share fastest as self-service procurement displaces traditional sales channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentration diverges sharply from consumption gravity in web-to-print software. Germany generates the highest procurement volumes through mid-sized print service provider clusters, while the United States hosts the largest vendor headquarters concentration. India and Japan represent contrasting growth profiles: India expands through regulatory-driven manufacturing label demand, Japan stabilizes through hybrid cloud-edge adoption.
United States
Corporate marketing procurement platforms absorb substantial web-to-print functionality through API integration with SAP Ariba and Coupa networks. FDA 21 CFR Part 11 requirements sustain on-premise deployments among pharmaceutical marketing teams. Healthcare and higher education verticals in the Northeast and California favor pre-approved supplier catalogs over direct vendor engagement.
Germany
Baden-Württemberg and Bavarian print cooperatives concentrate European demand through regional buying pools for modular SaaS bundles. GDPR data residency certifications and EU Digital Services Act audit mandates accelerate replacement of legacy installations. Mittelstand commercial printers in Stuttgart and Munich drive competitive pricing pressure through consolidated vendor negotiations.
India
PLI schemes for electronics and pharmaceuticals expand compliant packaging print volumes, creating entry points for audit-capable platforms. CDSCO audit trail requirements favor hosted single-tenant deployments among pharmaceutical exporters. Quick-service restaurant chains leverage brand management modules for localized menu production under corporate visual standards.
Japan
Automotive marketing teams deploy hybrid cloud-edge architectures for localized brochure production with centralized brand governance. Consumer markets in Tokyo and Osaka sustain specialized platform providers for personalized gift applications. METI industrial standards influence template verification protocols across export-facing print workflows.
United Kingdom
London-based brand management teams prioritize headless browser-based composition engines for localization velocity without IT dependency. Educational institutions face budget constraints favoring open-source and low-cost SaaS alternatives. Marketing procurement centralization across healthcare and higher education verticals displaces traditional sales-engineer involvement.
Global Web to Print Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Hardware-software integration capabilities separate enterprise account winners from mid-market challengers. Three archetypes dominate: legacy print equipment vendors extending software stacks, independent SaaS specialists with template rendering engines, and workflow integrators bridging MIS systems. M&A activity concentrates on design automation capabilities, while strategic partnerships address color management hardware dependencies.
Within the hardware-integrated tier, Xerox Corporation anchors enterprise positioning through equipment-software bundling. CHILI publish NV and Electronics For Imaging, Inc. exemplify specialized pure-play approaches: the former occupies advanced template rendering for brand management workflows, the latter represents color management fidelity across hybrid deployments. These three entities collectively illustrate how vendor origin—diversified conglomerate versus focused specialist—shapes competitive posture without determining market outcome.
| Leading Market Players |
|---|
| Xerox Corporation |
| CHILI publish NV |
| Design'N'Buy |
| DATATECH SMARTSOFT, INC. |
| Agfa-Gevaert Group |
| OnPrintShop |
| Aleyant Systems, LLC |
| Vpress Ltd. |
| Electronics For Imaging, Inc. |
| Others |
Supply & Pricing Matrix
German Mittelstand print cooperatives in Baden-Württemberg and Bavaria are consolidating procurement through regional buying pools, forcing vendors to unbundle design automation from order management and compressing margin flexibility across modular SaaS offerings.
Pricing Analysis
Margin tightening in mid-market tiers reflects hyperscale infrastructure concentration among AWS, Azure, and Google Cloud, which eliminates capital expenditure barriers while eroding independent vendor pricing power. Three-tier pricing structure across enterprise, professional, and entry-level SaaS bundles dominates, with ISO 12647 certification grade and JDF integration depth serving as primary differentiation drivers. Cost compression accelerates in the commercial printing segment as North American buyers benchmark aggressively through SAP Ariba and Coupa networks. Corporate marketing teams in US healthcare and higher education exhibit lowest price sensitivity due to FDA 21 CFR Part 11 validation requirements, while mid-sized print service providers in Germany show highest sensitivity to per-seat licensing costs.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Amsterdam, and Singapore anchor hub-and-spoke patterns for cloud-native platform delivery, with edge nodes positioned for GDPR-compliant data residency and low-latency RIP processing. Software development concentrates in the United States, Germany, and India, with Indian centers handling template rendering engine optimization and German operations focusing on regulatory compliance modules. The supply chain draws from hyperscale compute infrastructure, spectrophotometer hardware partnerships, and CIP4-certified middleware libraries. Single-source vulnerability in ICC profiling hardware from X-Rite and Konica Minolta creates dependency risk. Distribution runs through direct vendor sales for enterprise accounts and value-added resellers serving mid-market print service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from GDPR audit mandates and the EU Digital Services Act is forcing architectural redesign costs onto weaker vendors, creating acquisition opportunities for well-capitalized platforms with pre-certified compliance stacks.
For Market Incumbents: Deploy cryptographic job logging and territorial data sovereignty features to defend against cloud-native challengers, while deepening spectrophotometer hardware partnerships to lock in color management fidelity advantages. Acquire template rendering specialists to fill AI-assisted composition capability gaps before pure-play specialists capture brand management workflow premiums. For New Entrants and Emerging Players: Launch via API-first integration models targeting India's PLI-backed manufacturing label segment, where CDSCO audit trail requirements favor hosted single-tenant deployments without incumbent lock-in. Target Australian franchise print networks through managed services offerings that offset prepress automation skill shortages, using containerized microservices to bypass legacy JDF integration debt. For Investors and Strategic Acquirers: The window for entry favors hybrid cloud-edge architecture specialists with pharmaceutical compliance credentials, as security-sensitive corporate marketing teams and cost-sensitive commercial printers converge on this deployment model. Watch for AI content detection mandate implementations as inflection indicator for template authentication module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | JDF-enabled connectivity to Heidelberg and EFI MIS systems reduces implementation engineering resource consumption. |
| Acquisition of Specialist Firm | Template rendering engine capabilities from CHILI publish NV-type specialists accelerate brand management workflow penetration. |
| Strategic Partnership | Spectrophotometer hardware alliances with X-Rite lock in ICC profiling accuracy for pharmaceutical label compliance. |
| Geographic Expansion | Hosted single-tenant deployments in India capture PLI scheme manufacturing label volumes with CDSCO audit trails. |
| Product Launch | AI content detection modules address emerging regulatory watermarking and provenance verification requirements. |
Research Methodology
Independent corroboration across CTOs at commercial print houses, IT procurement officers at pharmaceutical marketers, platform engineers at SaaS vendors, and integration specialists at MIS providers underwrites the qualitative findings. Secondary validation draws from SEC filings of diversified conglomerates, CIP4 specification documents, GDPR implementation guidance, and FDA 21 CFR Part 11 validation records. Bottom-up segmentation modeling triangulates against top-down market sizing from cloud infrastructure spend disclosures and print equipment shipment data.
Rate-of-change decomposition across deployment model, organization size, vertical compliance posture, integration complexity, and regional adoption pattern shapes the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Variable data printing penetration rates and cloud migration velocity among German Mittelstand cooperatives serve as key forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for generative-AI watermarking and synthetic-media detection would alter the outlook for template verification module demand. Forecasts reflect assumptions regarding GDPR enforcement intensity and PLI scheme manufacturing label volume expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
GCC Digital Printing Market
Printing Technology
Print on Demand Software Market
Printing Technology
Global Barcode Printer Market
Printing Technology
ID Card Printers Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Web to Print Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Print on Demand Market
Printing Technology
Print Equipment Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Printing Machinery Market
Printing Technology
Automated Document Inserter (ADI) Market