
 Automated Document Inserter (ADI) Market | 2026-2036
Automated Document Inserter (ADI) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Document Inserter (ADI) Market Outlook
REACH compliance is recalibrating the cost-of-entry calculus for European ADI manufacturers, forcing reformulation of adhesives and envelope materials to eliminate restricted substances. Bastian Solutions leverages its North American installed base to sustain aftermarket service revenue across high-throughput distribution centers. KAS Paper Systems anchors its competitive position through specialized engineering for financial-sector document integrity requirements. The Numina Group differentiates via software-integrated controls that synchronize inserter lines with upstream warehouse management platforms.
An automated document inserter is a electromechanical system that folds, inserts, seals, and sorts paper documents into envelopes at speeds ranging from several thousand to over twenty thousand pieces per hour, serving billing, marketing correspondence, and secure mail distribution. Production inserters dominate capital expenditure among direct mail providers due to throughput requirements for campaign volumes, while desktop inserters retain stable replacement demand within small government field offices. High-speed inserters represent the fastest-growing product category as print services consolidate operations and prioritize line-speed optimization over redundant equipment footprints.
FDA 21 CFR Part 11 shapes document traceability requirements for pharmaceutical billing applications, while FCC electromagnetic compatibility standards govern control-system certifications for networked inserter installations. The EU AI Act introduces emerging compliance obligations for machine-learning-based optical character recognition modules that automate document verification. Stakeholders must evaluate whether retrofitting existing fleets or procuring certified next-generation platforms delivers superior total cost of ownership as regulatory scope expands beyond traditional mechanical safety domains.
Market Dynamics
The EU Green Deal is compressing capital planning horizons for ADI procurement across European direct mail operations, forcing equipment refresh cycles to align with energy-efficiency mandates and material-waste reduction targets rather than pure mechanical depreciation schedules.
Growth Catalysts
- Personalized Marketing Demand:Direct mail providers are scaling ADI fleets to handle variable-data print runs that require dynamic document matching at line speed.
- REACH Compliance:Reformulation of adhesives and envelope materials to eliminate restricted substances is creating replacement demand for compliant inserter platforms.
- Postal Automation Infrastructure:Germany's investment in sorting-system compatibility is pulling ADI upgrades across Central European print service networks.
Market Restraints
- Input Cost Volatility:Specialty-grade aluminum framing and precision servo motors face price pressure from concentrated Asian metal suppliers.
- Technical Limitation:Optical character recognition modules struggle with degraded print quality on recycled-stock documents, limiting circular-material adoption.
- Regulatory Friction:FDA 21 CFR Part 11 traceability requirements for pharmaceutical billing extend commissioning timelines by four to eight months.
Strategic Opportunities
- Software-Integrated Controls:Convergence of machine-vision verification with warehouse management platforms creates premium pricing for synchronized inserter lines.
- EU AI Act Positioning:Early certification of machine-learning-based document verification modules captures compliance budgets before enforcement hardens.
- Small Government Field Offices:Desktop inserter replacement cycles in municipal billing departments remain underpenetrated by service-contract models.
Industry Challenges
- Mechatronics Talent Scarcity:Maintenance of high-speed folding mechanisms requires technicians trained in precision timing-belt calibration, a skill set concentrated among aging European specialist workforces.
- Legacy System Integration:FCC electromagnetic compatibility certification for networked inserter controls demands retrofitting of shielding and grounding in facilities with pre-2010 electrical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Document Inserter (ADI) Market |
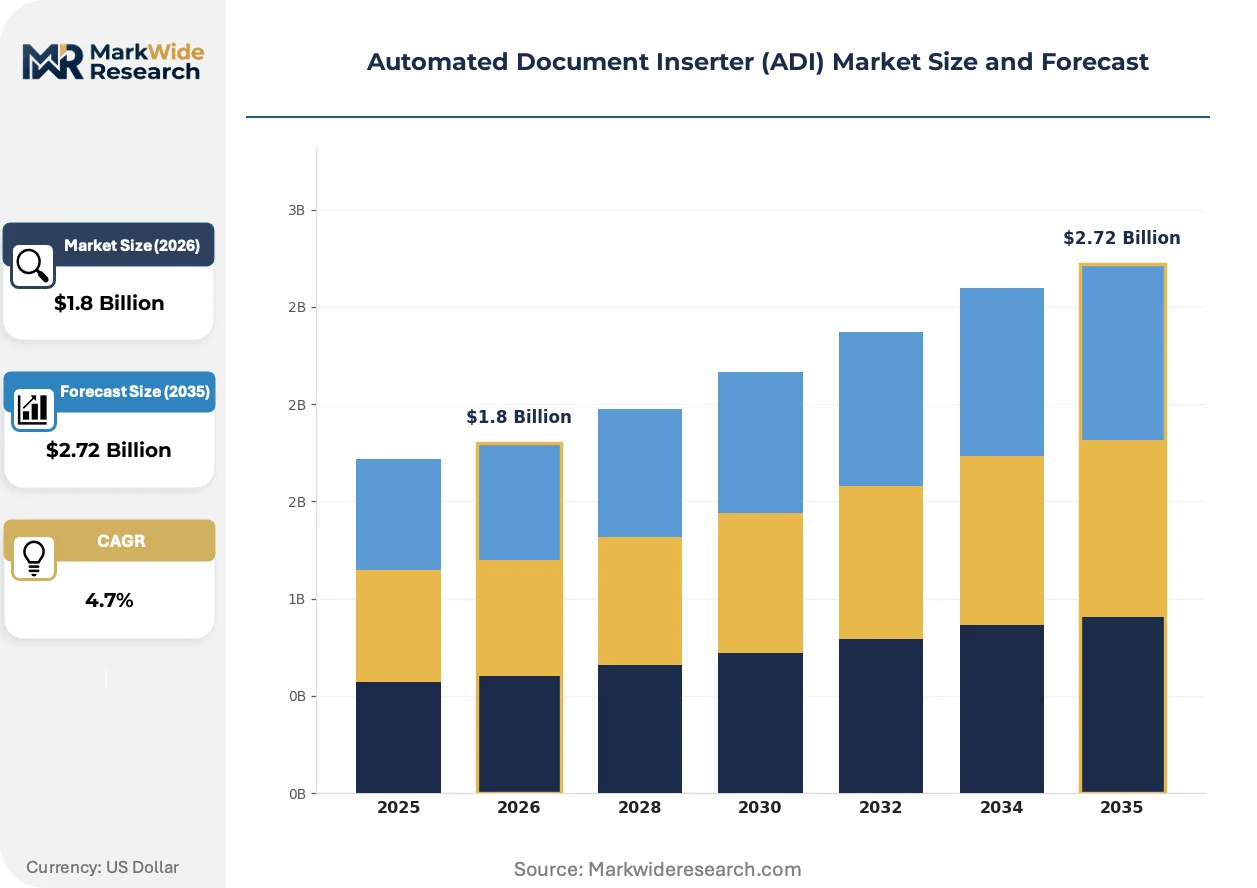
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Inserters, High-Speed Inserters, Letter Fold Inserters, Production Inserters End User: Financial Institutions, Government Agencies, Direct Mail Providers, Print Services Technology: Inkjet, Laser, Digital, Offset Application: Mailing, Billing, Marketing, Document Processing |
| Companies Covered | Inther, Bastian Solutions, The Numina Group, KAS Paper Systems, Neopost, SI Systems, FP Mailing, Integrated Systems Design, Formax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Document Inserter (ADI) Market Strategic Shifts
Machine-learning verification modules and energy-efficiency redesigns are redefining competitive differentiation in ADI procurement, compressing the viable lifespan of purely mechanical platforms.
AI-powered optical character recognition is expanding into document-integrity verification for financial-sector applications. Tier-one banks in Germany and France are piloting systems that match statement contents against customer databases at 18,000 envelopes per hour. This capability is expanding into premium pricing tiers that separate software-integrated vendors from mechanical-only suppliers.
REACH substance restrictions are forcing reformulation of pressure-sensitive adhesives used in envelope sealing. ECHA's 2023 updates to candidate substance listings have disqualified several legacy acrylic formulations. Pharmaceutical mail houses in the Netherlands and Belgium are prioritizing ADI platforms with pre-certified compliant materials to avoid production-line shutdowns.
Consolidation among print service providers is compressing equipment procurement from distributed regional fleets toward centralized high-capacity hubs. Direct mail campaigns that previously ran across twelve mid-speed inserters now execute on three production-grade lines with redundant backup. This concentration is visible most acutely in the UK and German markets where postal rate structures reward volume density.
Automated Document Inserter (ADI) Market Segmentation
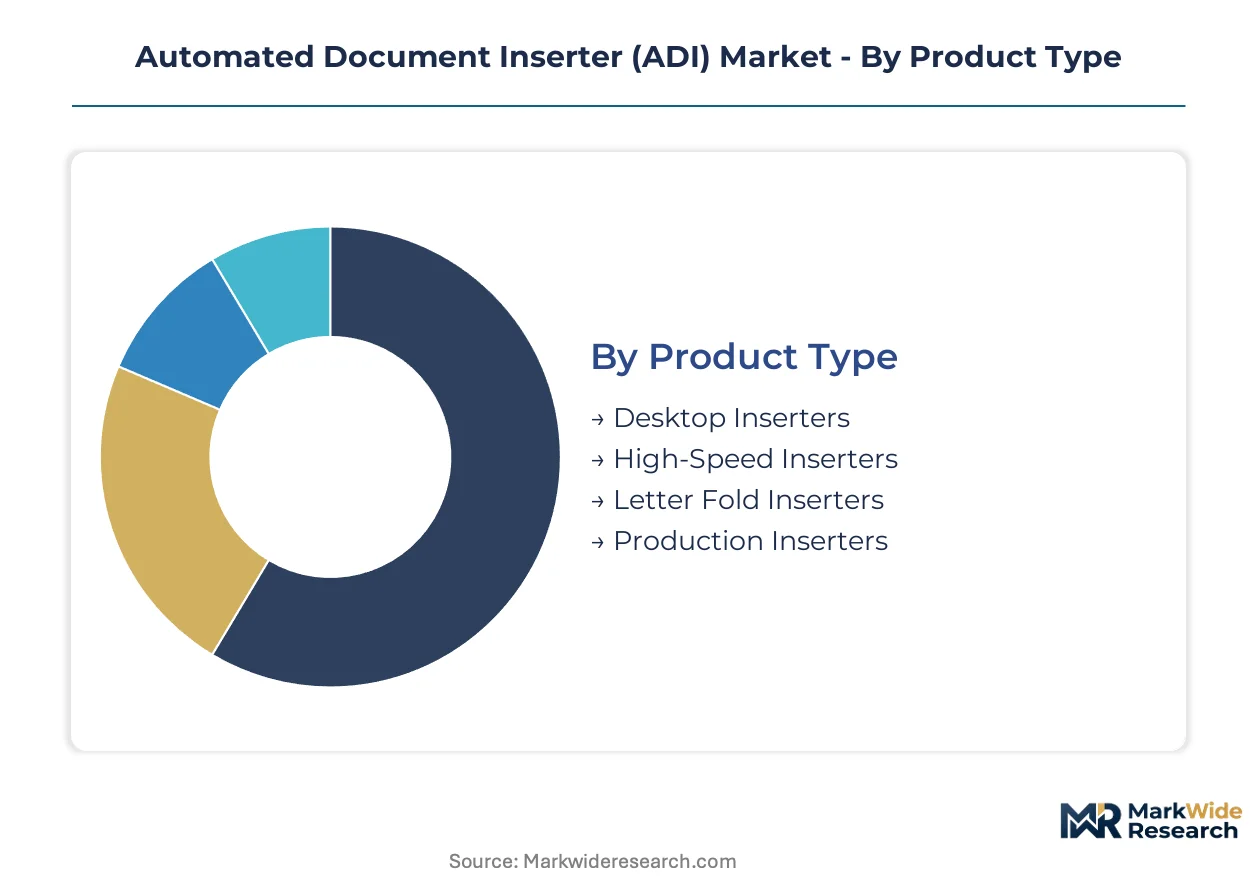
Segmentation in the Automated Document Inserter market determines procurement specifications, regulatory compliance pathways, and service contract structures. Equipment buyers match product categories to throughput requirements, document security standards, and integration complexity with existing workflow platforms.
Product Type:
Certification burdens vary sharply across product tiers: FCC electromagnetic compatibility governs networked high-speed and production units, while desktop models face lighter conformity requirements; REACH substance compliance affects sealing mechanisms universally.
- Production Inserters:These systems process over twenty thousand pieces per hour with multi-station folding, insertion, and sealing modules. Direct mail providers in Germany and the UK concentrate procurement here to consolidate campaign volumes into centralized high-capacity hubs.
- High-Speed Inserters:Line-speed optimization drives replacement of redundant mid-speed fleets across European print service networks. Tier-one banks in France pilot machine-learning verification modules at eighteen thousand envelopes per hour, pulling software-integrated platforms ahead of mechanical-only alternatives.
- Desktop Inserters:Compact units serve municipal billing departments and small government field offices with stable replacement demand.
- Letter Fold Inserters:Specialized folding mechanisms handle statement formats common in financial-sector correspondence.
Leading the category by volume: Production Inserters. Growing fastest: High-Speed Inserters.
End User:
Customer type dictates margin structure and contract duration, with financial institutions commanding premium pricing for document integrity features.
- Direct Mail Providers:Variable-data print runs require dynamic document matching at line speed. These buyers scale ADI fleets fastest, prioritizing throughput over unit economics as postal rate structures reward volume density.
- Financial Institutions:Statement integrity requirements and FDA 21 CFR Part 11 traceability for pharmaceutical billing extend commissioning timelines. Tier-one banks in Germany and France pay premiums for AI-powered optical character recognition verification.
- Government Agencies:Municipal billing departments maintain stable desktop inserter replacement cycles with limited service-contract penetration.
- Print Services:Consolidation shifts procurement from distributed regional fleets toward centralized production-grade lines with redundant backup.
Dominating procurement value: Financial Institutions. Expanding most quickly: Direct Mail Providers.
Technology:
Technology choice determines integration complexity with upstream document generation systems and downstream postal sorting infrastructure.
- Digital:Native connectivity to warehouse management platforms and variable-data workflows positions this technology for software-integrated control convergence.
- Laser:Precision imaging supports high-resolution optical character recognition modules for document verification applications.
- Inkjet:Cost-effective variable printing for marketing correspondence with lower capital barriers.
- Offset:Legacy installations in high-volume static document production with slower replacement cycles.
Capturing replacement demand: Digital. Facing longest replacement cycles: Offset.
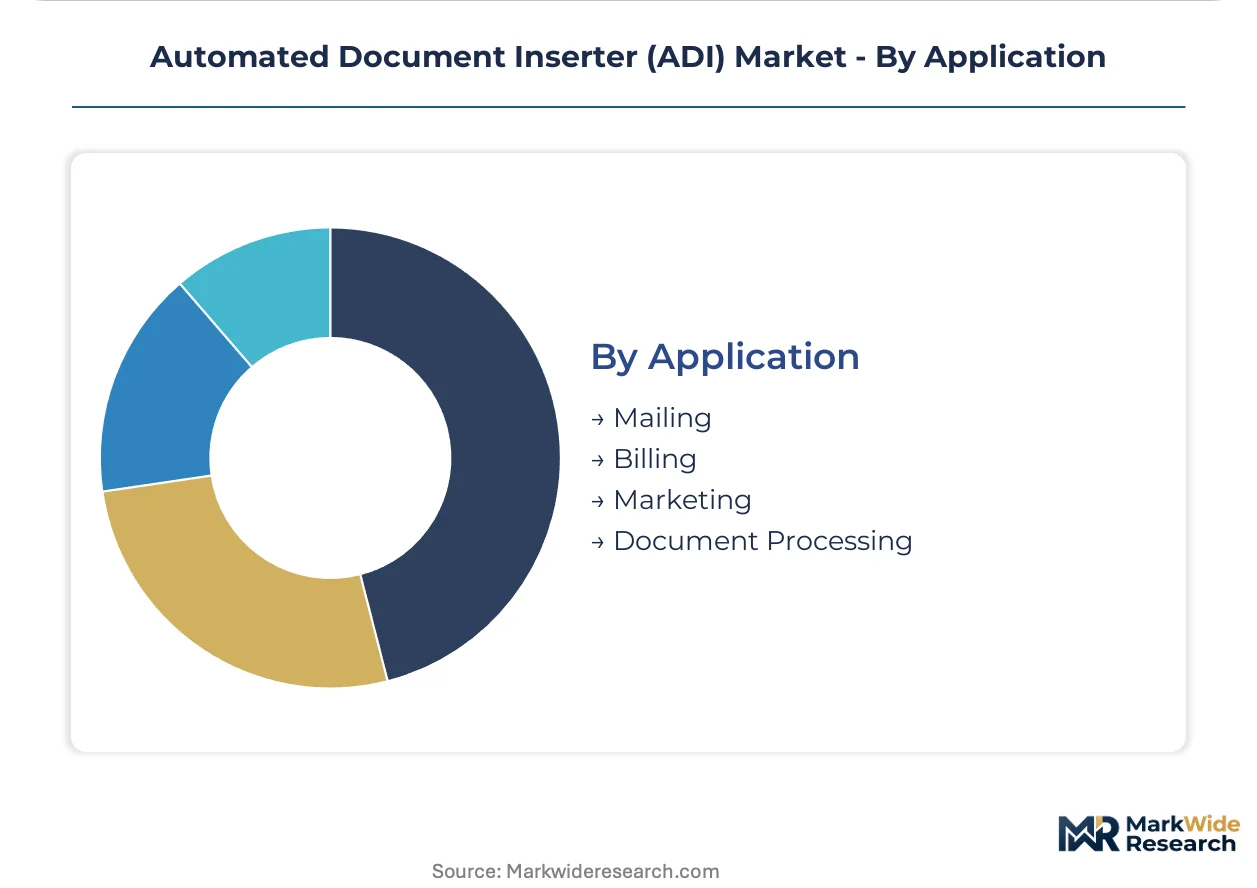
Application:
Application scope determines regulatory exposure, with billing applications triggering pharmaceutical traceability requirements and marketing driving personalization complexity.
- Billing:Pharmaceutical mail houses in the Netherlands and Belgium prioritize REACH-compliant adhesive formulations to avoid production-line shutdowns under ECHA substance restrictions.
- Marketing:Personalized direct mail campaigns demand dynamic document matching capabilities, concentrating investment in high-speed platforms with machine-vision verification.
- Mailing:General correspondence applications face standard mechanical safety and electromagnetic compatibility requirements.
- Document Processing:Secure distribution applications in financial and government sectors emphasize audit trails and integrity verification.
Highest compliance burden: Billing. Steepest expansion trajectory: Marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's postal corridor concentrate ADI procurement incentives, drawing equipment investment toward centralized high-capacity hubs serving pan-European direct mail networks.
Germany
Postal automation infrastructure upgrades accelerate demand for production-grade inserter lines. The EU Green Deal compresses capital planning horizons toward energy-efficient equipment refresh cycles. High-throughput facilities in the Rhine-Ruhr metropolitan region consolidate previously distributed regional fleets into three-line centralized hubs.
United States
Direct mail providers scale variable-data print capacity requiring dynamic document matching at line speed. FDA 21 CFR Part 11 shapes pharmaceutical billing traceability requirements for secure mail distribution. Distribution centers in the Chicago and Dallas-Fort Worth corridors anchor aftermarket service revenue for high-throughput installations.
France
Tier-one banks pilot machine-learning verification modules at eighteen thousand envelopes per hour, pulling premium software-integrated platforms ahead of mechanical alternatives. REACH substance restrictions from ECHA disqualify legacy adhesive formulations. Pharmaceutical mail houses in the Île-de-France cluster prioritize pre-certified compliant materials to avoid production-line shutdowns.
United Kingdom
Print service consolidation shifts procurement from twelve mid-speed inserters toward three production-grade lines with redundant backup. Postal rate structures reward volume density, concentrating investment in high-capacity equipment. Direct mail operations in the Midlands and Greater Manchester regions drive replacement demand for REACH-compliant sealing mechanisms.
Netherlands
Pharmaceutical billing applications trigger extended commissioning timelines for traceability-compliant platforms. ECHA's 2023 candidate substance updates accelerate adhesive reformulation requirements. Mail houses in the Randstad conurbation lead procurement of pre-certified REACH-compliant ADI systems to maintain continuous production schedules.
Automated Document Inserter (ADI) Market Competitive Environment
German and Dutch producers anchor one tier; North American specialists hold aftermarket service positions across distribution center networks. The vendor base organizes around three strategic archetypes: software-integrated control vendors, mechanical precision specialists, and service-contract incumbents. Consolidation pressure favors scale-driven equipment platforms over distributed regional fleets. Competitive moves concentrate on M&A for technology integration and geographic expansion into underpenetrated municipal billing segments.
Within the software-integrated tier, The Numina Group and Bastian Solutions exemplify convergence strategies between machine-vision verification and warehouse management platforms. KAS Paper Systems occupies a specialized position serving document integrity requirements in financial-sector applications. These three anchors represent divergent competitive vectors: platform synchronization, aftermarket service density, and sector-specific engineering depth.
| Leading Market Players |
|---|
| Inther |
| Bastian Solutions |
| The Numina Group |
| KAS Paper Systems |
| Neopost |
| SI Systems |
| FP Mailing |
| Integrated Systems Design |
| Formax |
| Others |
Value Chain & Pricing Dynamics
Specialty-grade aluminum framing and precision servo motors from concentrated Asian metal suppliers feed through three-tier pricing structures across premium, standard, and economy levels, with REACH-compliant adhesive formulations commanding premiums that compress margins for mechanical-only vendors.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with premium tiers capturing buyers requiring sub-quarter delivery schedules while spot inventory discounts attract cost-conscious municipal billing departments. Price differentiation rests on certification grade and after-sales service bundling. Pricing pressure intensifies as pharmaceutical mail houses demand pre-certified REACH-compliant materials. Government agencies exhibit highest price sensitivity; tier-one banks in Germany and France show lowest.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing patterns for energy-efficient component assemblies across German and Dutch production facilities. Supply concentration centers on Germany, China, and Japan for precision servo motors, optical sensors, and control-system electronics. Raw material dependencies include specialty aluminum alloys, rare-earth magnets, and pressure-sensitive adhesives. Single-source vulnerability in precision timing-belt components creates exposure. Distribution runs through direct OEM channels and specialized industrial equipment distributors serving print service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automated Document Inserter market sits in a technology-transition phase where machine-learning-based document verification modules are displacing legacy mechanical-only platforms, compressing viable equipment lifespans and reshaping competitive positioning.
For Market Incumbents: Deepen software-integrated control capabilities to defend against pure-mechanical competitors. Invest in EU AI Act certification for optical character recognition modules before enforcement hardens. Anchor aftermarket service contracts across high-throughput distribution centers in the Chicago and Dallas-Fort Worth corridors to lock in recurring revenue streams.
For New Entrants and Emerging Players: Municipal billing departments in small government field offices represent an underserved buyer archetype with stable replacement demand and limited service-contract penetration. Target desktop inserter segments with outcome-based maintenance offerings. Pursue direct sales partnerships with regional postal automation integrators to bypass established distributor relationships.
For Investors and Strategic Acquirers: Early EU AI Act compliance certification for machine-learning verification modules is the leading indicator that software-integrated vendors will capture disproportionate compliance budgets. Over the medium-term horizon, prioritize acquisition targets with established machine-vision engineering teams and pre-certified REACH-compliant material supply chains. Watch for consolidation signals among mid-speed inserter fleets being retired in favor of centralized high-capacity hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Integrated Control Development | Machine-vision verification synchronized with warehouse management platforms commands premium pricing from tier-one banks. |
| EU AI Act Pre-Certification | Early compliance for optical character recognition modules captures pharmaceutical billing budgets before enforcement hardens. |
| Aftermarket Service Contract Expansion | Maintenance agreements across high-throughput distribution centers generate recurring revenue insulated from equipment cycles. |
| REACH-Compliant Material Integration | Pre-certified adhesive formulations prevent production-line shutdowns for pharmaceutical mail houses in the Netherlands and Belgium. |
| Centralized Hub Consolidation | Three-line production-grade configurations replace twelve mid-speed fleets, concentrating procurement with scale vendors. |
Study Parameters
Independent corroboration across primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads, combined with secondary validation through customs records, SEC filings, and postal automation infrastructure disclosures, underwrites the qualitative findings. Bottom-up equipment shipment data triangulates against top-down addressable market estimates derived from direct mail campaign volume trends and print service consolidation patterns.
Comparable historical reference periods spanning equipment refresh cycles and regulatory implementation timelines anchor the forecast window across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, and application scope, with additional granularity on regulatory compliance tier. CAGRs derive from installed base evolution, replacement demand elasticity, and penetration rates for software-integrated platforms. Industry-specific inputs encompass postal rate structure changes and REACH substance restriction timelines.
Revisions become necessary when EU AI Act enforcement timelines accelerate, REACH candidate substance listings expand unexpectedly, or print service consolidation pauses due to postal rate volatility. Forecasts reflect documented assumptions about technology adoption curves and regulatory compliance cost pass-through. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Card Printers Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Print Equipment Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Printing Machinery Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Digital Paper System Market
Printing Technology
Professional Printers Market
Printing Technology
Variable Data Printing Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Digital Production Printer Market
Printing Technology
Large Format Printer Market
Printing Technology
Global Microprinting Market