
 Digital Printing on Wood Market | 2026-2036
Digital Printing on Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Printing on Wood Market Outlook
High-definition grain-matching and premium finish tiers is rotating demand toward digitally printed wood surfaces that replicate exotic species without raw material constraints. Hewlett-Packard Development Company, L.P. leverages its thermal inkjet architecture to dominate wide-format wood decoration lines. Roland DG Corporation specializes in compact UV flatbed systems for custom furniture workshops. Durst anchors industrial-scale production with single-pass inkjet engines for flooring and panel manufacturers.
Digital printing on wood applies UV-curable, solvent-based, or latex inks through inkjet or laser systems onto veneers, plywood, MDF, or solid wood substrates at resolutions typically exceeding 600 dpi for decorative fidelity. The process eliminates conventional rotary printing cylinders, enabling lot-size-one production for furniture and interior applications. Ink type segmentation shows UV-curable formulations capturing margin pools due to instant curing and low-VOC compliance, while MDF substrates lead volume given their uniform surface and cost efficiency in flat-panel furniture. Technology segmentation reveals inkjet systems sustaining the broadest end-user penetration across furniture manufacturers and signage companies.
EPA regulates volatile organic compound emissions from wood coating operations under NESHAP standards, while REACH restricts hazardous substances in imported decorative wood products within Europe. FDA indirect food-contact guidelines additionally shape ink selection for printed wood surfaces used in kitchen and hospitality environments. Stakeholders must monitor evolving chemical compliance frameworks alongside print-head reliability advances to secure positioning in customized wood decoration value chains.
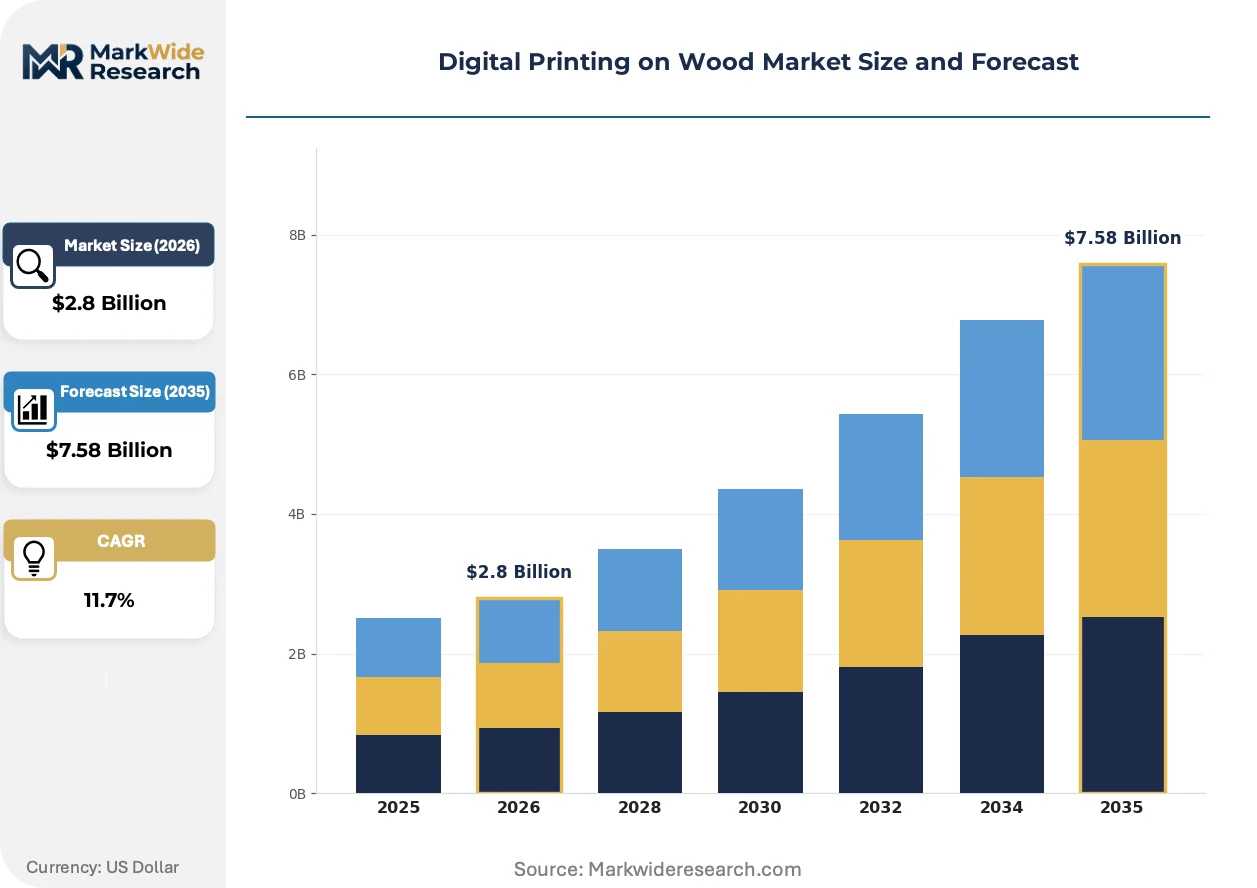
Market Dynamics
UV-curable ink chemistry is compressing production cycles while EPA NESHAP compliance requirements force solvent-based system retirements across North American furniture manufacturing clusters.
Growth Catalysts
- EPA NESHAP Subpart QQQQ:Emissions caps on wood coating operations accelerate UV inkjet retrofits in US cabinetry plants seeking permit compliance without abatement equipment.
- Mass-customization workflows:German industrial furniture clusters in Baden-Württemberg deploy single-pass inkjet engines enabling lot-size-one decorative panel production at throughput parity with rotary systems.
- Exotic species replication:High-definition grain-matching algorithms satisfy architect-specified aesthetics while eliminating CITES-restricted raw material procurement.
Market Restraints
- Photoinitiator supply concentration:European chemical manufacturers control 70% of acylphosphine oxide photoinitiator output, creating formulation cost volatility during feedstock disruptions.
- Substrate dimensional instability:Solid wood expansion-contraction cycles exceed ink film elasticity limits, restricting warranty coverage for flooring applications below engineered substrates.
- REACH SVHC notification:Bisphenol A derivatives in certain UV ink formulations trigger downstream communication obligations, complicating EU decorative wood product exports.
Strategic Opportunities
- India furniture export corridors:Moradabad and Jodhpur handicraft clusters present untapped demand for digital veneer decoration serving hospitality procurement specifications.
- LEED v5 materials credit:Low-VOC digital printing pathways satisfy embodied carbon thresholds for commercial interior fit-out specifications.
- AI-driven color matching:Machine vision convergence with spectrophotometric calibration reduces make-ready waste in custom color-matching workflows.
Industry Challenges
- Print-head maintenance specialization:Piezoelectric nozzle recovery protocols demand technicians trained in MEMS cleaning chemistry, a skill scarce outside OEM service networks.
- Legacy finishing line integration:Sanding and sealer stations designed for rotary print cylinders require mechanical reconfiguration to accept inkjet-deposited film thickness profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Printing on Wood Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Veneers, Plywood, MDF, Solid Wood Ink Type: UV-Curable, Solvent-Based, Eco-Solvent, Latex Technology: Inkjet, Laser, Sublimation, Digital Transfer End User: Furniture Manufacturers, Interior Designers, Signage Companies, Retail Stores |
| Companies Covered | Hewlett-Packard Development Company, L.P., Roland DG Corporation, Canon, Inc., Ricoh Company, Ltd., Mimaki Engineering Co., Ltd., Electronics For Imaging Inc., Barberán, S.A., Durst, Cefla Finishing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Printing on Wood Market Strategic Shifts
Digital wood decoration is splitting into two velocity tiers: industrial single-pass systems achieving rotary-equivalent throughput versus compact flatbed units serving workshop-scale customization.
Single-pass inkjet architecture is bifurcating the installed base. Flooring manufacturers in Austria and panel producers in Italy adopt 1.6-meter-wide single-pass engines achieving 150 linear meters per minute. This velocity tier is compressing rotary screen printing equipment residual values while creating secondary market opportunities for refurbished wide-format flatbed systems.
REACH Annex XVII restrictions on formaldehyde emissions from wood-based panels are tightening substrate specifications. German MDF producers now certify E1-E0 emission classes through third-party validation, forcing ink suppliers to reformulate primers that do not compromise substrate certification. Italian kitchen cabinetry exporters face heightened documentation requirements for US and Middle East destinations.
Architectural specification libraries are consolidating purchasing authority. Large hospitality and workplace design firms in London and New York now mandate digital print samples with batch-traceable color data, displacing traditional millwork showroom selection processes. This procurement compression favors decoration providers with cloud-based specification tools and same-day physical sample dispatch capabilities.
Digital Printing on Wood Market Segmentation
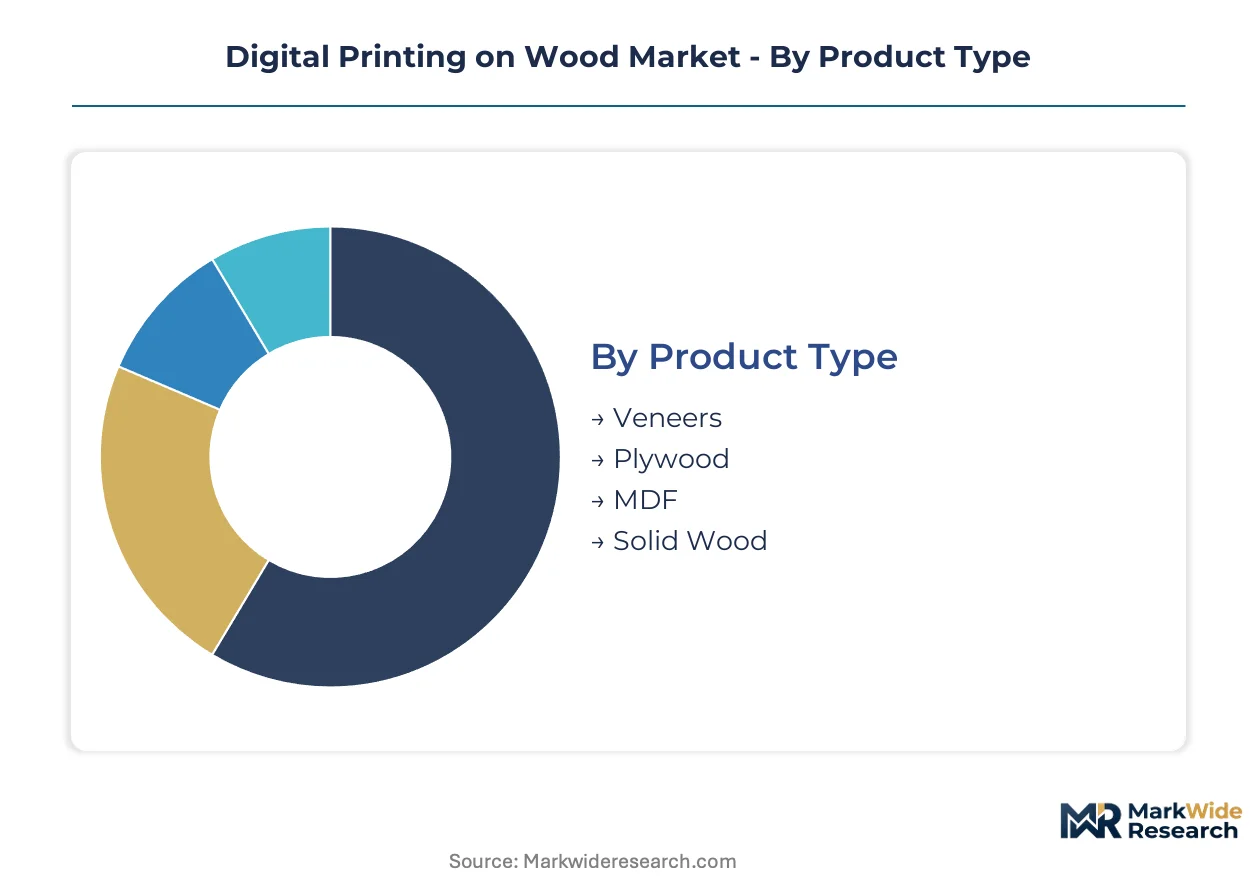
Segmentation in digital wood printing reveals how substrate compatibility, ink chemistry, and production velocity determine equipment selection and margin capture. Each dimension carries distinct regulatory and technical constraints that shape vendor positioning across furniture, interior, and commercial display applications.
Product Type:
Margin pools concentrate in engineered substrates where surface uniformity enables high-throughput single-pass printing without defect rates that erode profitability.
- MDF:Uniform density and absence of grain variation allow 600+ dpi resolution at production speeds exceeding 100 linear meters per minute. German flat-panel furniture manufacturers in North Rhine-Westphalia specify E1-E0 emission-certified MDF for kitchen cabinetry exports to the Middle East, where REACH-aligned documentation requirements filter out uncertified suppliers.
- Veneers:Thin decorative layers bonded to engineered cores enable exotic species replication without CITES-restricted raw material procurement. Austrian flooring producers leverage digitally printed veneers for architect-specified walnut and teak aesthetics at 40% lower material cost than solid alternatives.
- Plywood:Cross-laminated construction provides dimensional stability for large-format decorative panels in hospitality fit-outs.
- Solid Wood:Expansion-contraction cycles exceeding 8% moisture content variation restrict ink film warranty coverage below engineered substrates.
The dominant share belongs to MDF, while veneers are closing the gap fastest.
Ink Type:
Formulation chemistry determines compliance pathways across EPA NESHAP-regulated US facilities and REACH-governed European exports.
- UV-Curable:Photoinitiator-triggered polymerization enables instant curing without thermal drying, compressing production cycles from hours to seconds. North American cabinetry plants in Michigan and North Carolina retrofit solvent-based lines with UV inkjet to meet Subpart QQQQ emissions caps without capital-intensive abatement equipment.
- Solvent-Based:Higher volatile organic compound content triggers NESHAP permitting requirements that accelerate system retirements across US manufacturing clusters.
- Eco-Solvent:Reduced VOC formulations occupy a transitional niche for mid-volume workshops lacking UV curing infrastructure.
- Latex:Water-based chemistry serves indoor air quality specifications for healthcare and education environments where odor and off-gassing constraints apply.
UV-curable formulations command premium positioning, with latex gaining share fastest in institutional segments.
Technology:
Velocity tiers separate industrial-scale production from workshop customization, with throughput determining equipment residual values and secondary market liquidity.
- Inkjet:Piezoelectric drop-on-demand systems sustain broadest end-user penetration across furniture manufacturers and signage companies. Drop volumes ranging 6-80 picoliters enable grain-matching algorithms that replicate exotic wood aesthetics at resolutions exceeding 1200 dpi for architect library submissions.
- Laser:Ablation-based decoration achieves permanent surface marking without consumable inks, serving outdoor signage and marine applications where UV degradation resistance is paramount.
- Sublimation:Heat-transfer chemistry requires polyester-coated substrates, limiting applicability in natural wood decoration.
- Digital Transfer:Intermediate film-based processes bridge rotary screen legacy workflows with digital flexibility for short-run decorative panel production.
Inkjet systems anchor installed capacity, while laser technology is climbing fastest in exterior durability applications.
End User:
Procurement authority consolidation among specification-driven buyers favors decoration providers with cloud-based color libraries and same-day physical sample dispatch.
- Furniture Manufacturers:Mass-customization workflows in Baden-Württemberg industrial clusters deploy single-pass engines enabling lot-size-one production at rotary-equivalent throughput. Batch-traceable color data satisfies architect-mandated documentation for hospitality procurement.
- Interior Designers:London and New York design firms now mandate digital print samples with spectrophotometric calibration certificates, displacing traditional millwork showroom selection processes.
- Signage Companies:Retail brand identity programs drive demand for weather-resistant wood displays in outdoor environments.
- Retail Stores:Point-of-sale fixture programs require rapid turnaround on seasonal decorative panel refreshes.
Furniture manufacturers retain volume leadership, with interior designers expanding share fastest through specification authority consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German furniture exports to Middle Eastern hospitality projects drive cross-border specification of digitally printed wood surfaces. Italian flooring manufacturers supply architect-specified decorative panels to London and New York commercial fit-outs. Indian handicraft clusters in Moradabad and Jodhpur export digitally enhanced veneer products to European boutique hotel procurement programs.
United States
EPA NESHAP Subpart QQQQ emissions caps force solvent-based system retirements across Michigan and North Carolina cabinetry plants. Michigan furniture manufacturers retrofit production lines with UV inkjet systems to avoid capital-intensive abatement equipment. North Carolina's industrial furniture corridor integrates high-speed inkjet for mass-customization workflows serving domestic hospitality procurement.
Germany
REACH SVHC notification requirements for Bisphenol A derivatives complicate UV ink formulation exports. Baden-Württemberg industrial furniture clusters deploy single-pass inkjet engines enabling lot-size-one decorative panel production. North Rhine-Westphalia flat-panel furniture manufacturers specify E1-E0 emission-certified MDF for kitchen cabinetry exports to Middle East destinations.
Italy
Architectural specification libraries in Milan and Florence consolidate purchasing authority for decorative wood surfaces. Italian kitchen cabinetry exporters face heightened documentation requirements for US and Middle East destinations under evolving chemical compliance frameworks. Veneto flooring producers adopt digitally printed veneers for architect-specified walnut aesthetics at reduced material cost.
Austria
Formaldehyde emission standards under REACH Annex XVII tighten substrate specifications for decorative panel exports. Flooring manufacturers in Upper Austria adopt 1.6-meter-wide single-pass engines achieving rotary-equivalent throughput. Salzburg-region panel producers integrate cloud-based specification tools for same-day physical sample dispatch to London and New York design firms.
India
BIS certification requirements for wood-based panels shape substrate selection for export-oriented production. Moradabad and Jodhpur handicraft clusters present demand for digital veneer decoration serving hospitality procurement specifications. Gujarat furniture exporters adopt UV-curable ink formulations to meet EPA-aligned documentation for North American buyer compliance.
Digital Printing on Wood Market Competitive Environment
Listed leaders compete with private specialists across technology velocity tiers and geographic reach. The vendor base separates into consolidated equipment manufacturers with full portfolio coverage and focused specialists dominating narrow application segments. Three archetypes define competitive positioning: thermal inkjet architects with wide-format dominance, compact flatbed specialists serving workshop-scale customization, and single-pass engine builders anchoring industrial-scale production. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players retrofit solvent-based installed bases.
Within the wide-format industrial tier, Hewlett-Packard Development Company, L.P. and Durst occupy positions exemplifying scale-driven thermal inkjet and single-pass architectures respectively. Roland DG Corporation represents the compact specialist archetype serving custom furniture workshops. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Hewlett-Packard Development Company, L.P. |
| Roland DG Corporation |
| Canon, Inc. |
| Ricoh Company, Ltd. |
| Mimaki Engineering Co., Ltd. |
| Electronics For Imaging Inc. |
| Barberán, S.A. |
| Durst |
| Cefla Finishing |
| Others |
Value Chain & Pricing Dynamics
EPA NESHAP Subpart QQQQ compliance gates both equipment supplier qualification and price differentiation between UV-curable and solvent-based system tiers. Furniture manufacturers in Michigan and North Carolina face permit-driven procurement decisions where certified UV inkjet retrofits command 15-25% capital premiums over uncertified alternatives, compressing margin pools for non-compliant vendors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in digital wood printing equipment. Price differentiation separates single-pass industrial engines from compact flatbed systems based on throughput certification and geographic service coverage. Cost compression in mid-volume UV flatbed tiers intensifies because photoinitiator supply concentration in European chemical manufacturers creates formulation cost volatility. Small custom furniture workshops exhibit highest price sensitivity, while flooring manufacturers with architect-specified contracts demonstrate lowest sensitivity to capital equipment premiums.
Supply Chain Analysis
Strategic stockpiling of photoinitiators and print-head consumables dominates inventory strategy over just-in-time approaches due to supply concentration risks. Manufacturing concentration centers on Germany, Italy, and Japan for precision inkjet components and UV curing systems. Raw material dependencies include acylphosphine oxide photoinitiators, piezoelectric MEMS print-heads, and E1-E0 certified MDF substrates. Single-source vulnerability in European photoinitiator production creates exposure to feedstock disruption. Distribution runs through OEM-direct channels for industrial-scale buyers and specialized dealer networks serving workshop-scale customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Architectural specification library consolidation in London and New York design firms concentrates buyer power, fragmenting negotiating leverage among smaller decoration providers. This shift favors vendors with cloud-based color tools and rapid sample fulfillment capabilities.
For Market Incumbents: Secure print-head maintenance specialization capabilities before MEMS cleaning chemistry expertise scarcity deepens outside OEM service networks. Defend margin position by acquiring E1-E0 substrate certification capabilities that satisfy REACH Annex XVII documentation requirements for Middle East export corridors. Capacity addition in Baden-Württemberg industrial clusters anchors rotary-equivalent throughput positioning against emerging single-pass competitors. For New Entrants and Emerging Players: Cloud-based specification tool under-investment by legacy vendors creates entry opportunity for same-day physical sample dispatch capabilities. Target Moradabad and Jodhpur handicraft clusters where digital veneer decoration penetration remains below 15% for hospitality procurement. Deploy AI-driven color matching as differentiated go-to-market angle reducing make-ready waste for custom furniture workshops. For Investors and Strategic Acquirers: EPA NESHAP Subpart QQQQ enforcement timeline reshapes the acquisition landscape toward UV-curable ink formulation specialists with proven compliance documentation. Long-term viability hinges on positioning within mass-customization workflow value chains rather than rotary screen legacy equipment residual values. Monitor REACH SVHC notification expansion for Bisphenol A derivative restrictions as inflection indicator for formulation reformulation costs. Acquisition target archetype: compact flatbed specialists with installed base in underserved regional furniture clusters.| Strategic Initiative | Industry Significance |
|---|---|
| UV Inkjet Retrofit Program | EPA NESHAP compliance without capital-intensive abatement equipment secures permit continuity for Michigan cabinetry plants. |
| Single-Pass Engine Deployment | Rotary-equivalent throughput in Baden-Württemberg clusters enables lot-size-one production at mass-customization scale. |
| Photoinitiator Backward Integration | Captive supply of acylphosphine oxide formulations reduces European chemical manufacturer dependency and cost volatility. |
| E1-E0 Certification Investment | Third-party validated MDF emission classes satisfy REACH Annex XVII requirements for Middle East kitchen cabinetry exports. |
| Cloud-Based Specification Platform | Same-day physical sample dispatch capabilities align with London and New York design firm procurement compression trends. |
Study Parameters
Cross-validation between primary interviews with inkjet equipment OEMs and secondary analysis of EPA NESHAP enforcement disclosures anchors the qualitative findings. Stakeholder input sources include plant engineers at North Carolina furniture manufacturers, procurement leads at Austrian flooring producers, technical R&D directors at UV ink formulators, and aftermarket service heads at wide-format equipment distributors. Secondary data draws from EPA regulatory filings, REACH SVHC candidate list updates, E1-E0 emission certification databases, and customs records for wood-based panel trade flows. Bottom-up equipment installation tracking triangulates against top-down furniture production capacity estimates.
Sensitivity analysis around photoinitiator price volatility and REACH regulatory expansion scenarios shapes the analytical framework. Segmentation dimensions modeled include substrate type, ink chemistry class, production velocity tier, and end-user procurement authority level. CAGRs derive from equipment replacement cycle analysis and mass-customization workflow adoption curves. Industry-specific forecast inputs incorporate single-pass inkjet penetration rates in German industrial furniture clusters and UV retrofit timelines in US cabinetry plants.
Forecasts assume regulatory continuity in EPA NESHAP Subpart QQQQ and REACH Annex XVII regimes; material policy shifts would require re-modeling. Photoinitiator supply disruption or REACH SVHC notification expansion for additional UV ink constituents represent specific risk factors. Revision becomes warranted when single-pass inkjet residual value compression accelerates beyond rotary screen equipment depreciation curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Book Printing Service Market
Printing Technology
Cloud Print Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Commercial Printer Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Managed Print Services Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
Digital Presses Market
Printing Technology
Retail Printers Market
Printing Technology
Print on Demand Software Market
Printing Technology
Large Character Printers Market
Printing Technology
ID Card Printers Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Global Wireless Printers Market