
 US Print on Demand Market | 2026-2036
US Print on Demand Market Size, Share, and Industry Trends Forecast 2026-2036
US Print on Demand Market Insights
Premium fabric-grade specifications across heavyweight cotton and tri-blend substrates is unwinding the commodity perception that long dominated the space. Printful leverages vertically integrated production facilities across North Carolina and Texas to control fulfillment velocity. Gooten anchors its competitive stance through a distributed partner network that reduces shipping zones for domestic orders. VistaPrint sustains brand strength among small business purchasers seeking unified branding across merchandise and marketing materials.
US Print on Demand denotes a digitally intermediated production model where individual orders trigger automated manufacturing workflows—typically DTG printing, dye sublimation, or UV-cured flatbed processes—without holding finished inventory, with output specifications ranging from 180 gsm ring-spun cotton to ceramic-grade mug coatings. The primary commercial purpose centers on enabling zero-inventory commerce for creators, brands, and enterprises requiring customized physical goods at lot sizes of one. T-Shirts and phone cases within the product type dimension capture divergent margin structures, with apparel commanding higher average order values but facing steeper return rates than hard accessories. Online stores and social media channels within the sales channel split are pulling volume from marketplace aggregators as platform-native checkout tools reduce friction.
Federal Trade Commission guidelines on advertising claims and substantiation shape how platforms present product quality descriptors to end consumers. State-level extended producer responsibility frameworks emerging in California and New York are pressuring fulfillment networks to document textile waste streams and packaging recyclability. The Consumer Product Safety Commission maintains flammability and chemical content standards for children's merchandise categories that several POD suppliers now avoid entirely. Stakeholders must monitor how state sales tax nexus rules continue fragmenting compliance obligations as economic presence thresholds tighten.
Market Dynamics
DTG ink chemistry advances and automated pre-treatment workflows are compressing unit economics for short-run apparel production, enabling single-item fulfillment at price points previously reserved for bulk screen printing.
Growth Catalysts
- Creator economy density:Independent artists and micro-brands in California and Texas leverage platform-native design tools to launch merchandise lines without inventory risk, pulling volume from traditional wholesale channels.
- FTC substantiation guidelines:Clearer advertising claim standards reduce consumer disputes over fabric quality descriptors, lowering return processing costs for platforms.
- Same-day fulfillment infrastructure:Vertically integrated production facilities in North Carolina and Texas compress delivery windows to under 24 hours for domestic orders.
Market Restraints
- Pigment ink cost volatility:Water-based DTG formulations depend on petroleum-derived binders and specialty dyes, exposing margins to petrochemical price swings.
- Regional production concentration:Heavy reliance on Texas and California fulfillment nodes creates weather and grid vulnerability for national delivery promises.
- Children's merchandise liability:CPSC flammability and chemical content standards deter many suppliers from youth categories entirely, shrinking addressable SKU ranges.
Strategic Opportunities
- Midwestern fulfillment gaps:Ohio and Illinois present underpenetrated zones where distributed partner networks could reduce shipping zones for Great Lakes and Plains orders.
- Extended producer responsibility frameworks:California's emerging textile waste documentation requirements favor platforms with granular supply chain tracking, creating compliance-based differentiation.
- UV-cured flatbed convergence:Hybrid UV-DTG systems enable rigid substrate production alongside apparel, allowing creators to unify hard accessories and soft goods under single storefronts.
Industry Challenges
- Color management expertise scarcity:DTG output consistency demands specialized RIP software proficiency and substrate-specific ICC profiling that outpaces available technician training pipelines.
- State sales tax nexus fragmentation:Economic presence thresholds tightening across jurisdictions multiply compliance obligations for platforms serving creators nationwide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Print on Demand Market |
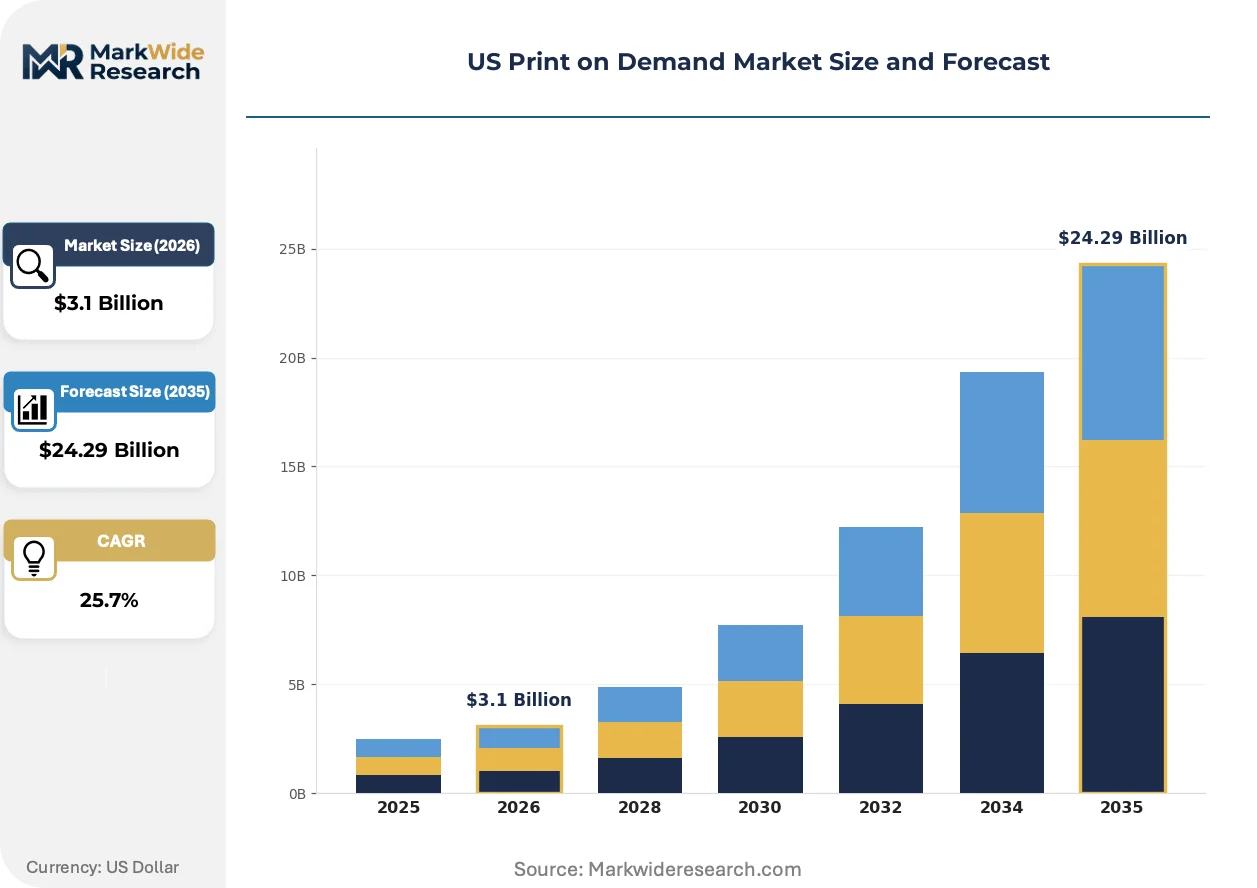
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $24.29 Billion |
| CAGR (2026 – 2036) | 25.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Mugs, Phone Cases, Posters Sales Channel: Online Stores, Marketplaces, Social Media, Retail Shops End User: Consumers, Businesses, Artists, Designers Application: Custom Merchandise, Branding, Promotions, Gifting |
| Companies Covered | Printful, Printify, Gelato, CustomCat, Gooten, VistaPrint (Cimpress), Redbubble, Zazzle, Spreadgroup, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Print on Demand Market Trends and Innovations
Automated pre-treatment and AI-driven design generation are compressing the time from concept to shipped unit, shifting competitive advantage from scale economies to workflow velocity and substrate versatility.
DTG printhead technology is miniaturizing. Precision droplet control now enables photographic reproduction on 180 gsm ring-spun cotton at resolutions rivaling offset lithography. Boutique fashion labels and independent musicians adopt these systems for limited drops of under 100 units. The technology is miniaturizing production minimums, collapsing the economic rationale for overseas bulk manufacturing on short-run orders.
California's extended producer responsibility frameworks are mandating textile waste stream documentation and packaging recyclability disclosures. Fulfillment networks must now track post-consumer garment flows and virgin versus recycled fiber inputs. Hard accessories and ceramic substrates face lighter reporting burdens, pushing some suppliers toward mug and phone case specialization.
Social commerce checkout tools are displacing marketplace aggregators as the primary demand capture channel. TikTok Shop and Instagram native purchasing compress the path from content discovery to order confirmation, reducing platform switching. Independent artists in Texas and Florida report higher conversion rates from platform-native storefronts than from redirected e-commerce sites, reshaping where creators invest design and marketing resources.
US Print on Demand Market Segmentation
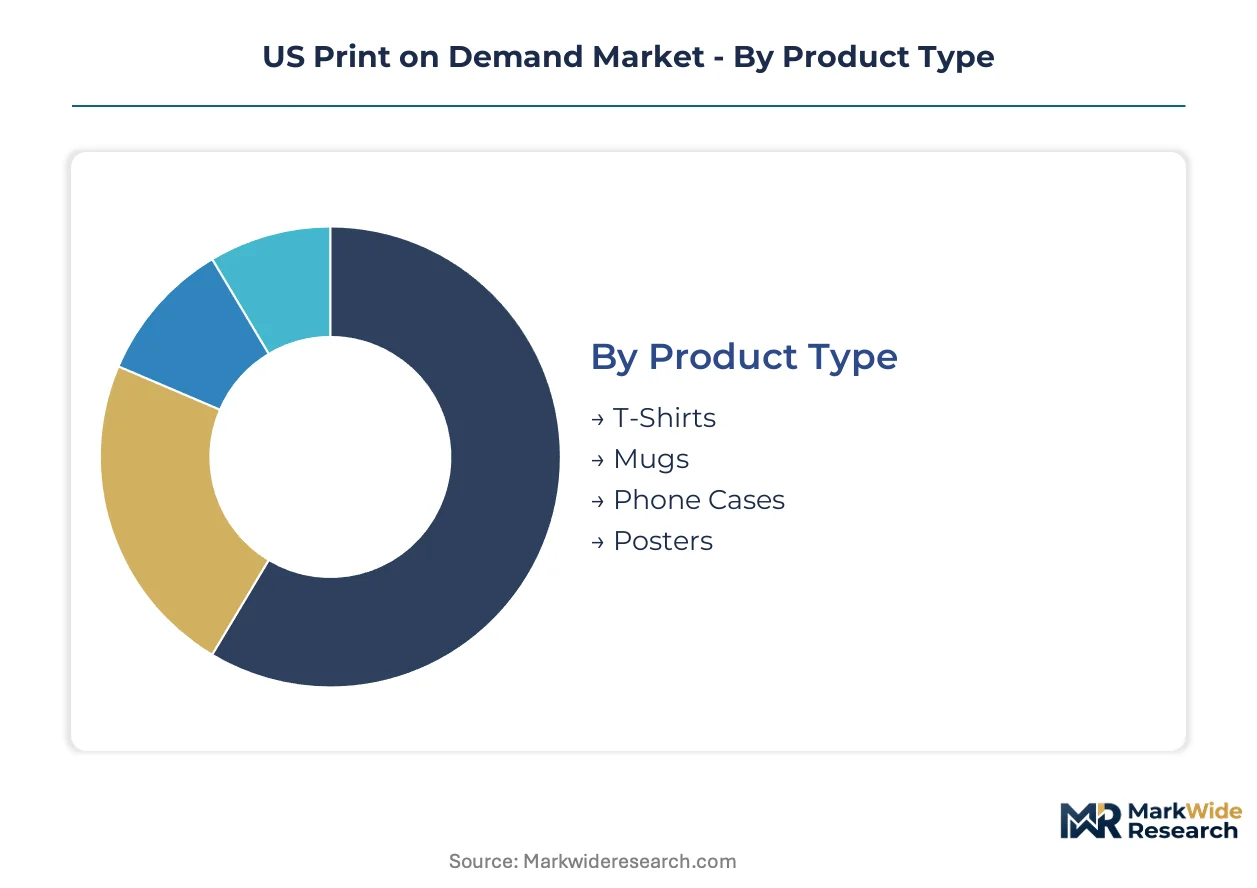
Segmentation in US Print on Demand reveals how margin pools shift across substrate types, fulfillment channels, and creator workflows. Each dimension carries distinct logistics profiles and customer acquisition economics that shape platform strategy.
Product Type:
Margin concentration sits with apparel substrates where DTG chemistry advances compress unit costs for single-item fulfillment.
- T-Shirts:180 gsm ring-spun cotton and tri-blend substrates command premium positioning through fabric-grade specifications. California and Texas creators drive volume via platform-native design tools that collapse concept-to-ship timelines. Return rates run higher than hard accessories, compressing net margins despite elevated average order values.
- Mugs:Ceramic-grade coatings with UV-cured durability standards carry lower return incidence and lighter regulatory burdens under California textile waste frameworks. Demand clusters among small business purchasers seeking unified branding across merchandise and marketing materials.
- Phone Cases:Rigid substrate production via hybrid UV-DTG systems enables photographic reproduction at sub-millimeter tolerances.
- Posters:Dye sublimation on synthetic papers serves artist communities with archival-grade output specifications.
The dominant share belongs to T-Shirts, while Mugs is closing the gap fastest as creators diversify into hard accessories with lighter compliance obligations.
Sales Channel:
Demand capture is shifting from marketplace aggregators toward platform-native checkout tools that reduce friction in the purchase path.
- Online Stores:Independent storefronts built on Shopify and WooCommerce retain customer data ownership and enable subscription merchandising models. Texas and Florida artists report stronger lifetime value metrics here than through redirected e-commerce paths.
- Social Media:TikTok Shop and Instagram native purchasing compress discovery-to-confirmation windows. Conversion rates for independent creators in California run highest where content discovery and checkout share platform infrastructure.
- Marketplaces:Aggregator platforms like Etsy and Amazon Merch on Demand still capture volume but face margin compression from fee stacking.
- Retail Shops:Physical pickup nodes in creator-dense urban corridors offer same-day fulfillment for local demand.
Online Stores holds the largest volume position, though Social Media is expanding most quickly as native commerce tools mature.
End User:
Creator economy density is pulling volume from traditional wholesale channels toward individual producers with zero-inventory requirements.
- Artists:Independent visual creators leverage automated fulfillment software to launch limited drops under 100 units. DTG miniaturization collapses the economic rationale for overseas bulk manufacturing on short-run orders.
- Businesses:Small enterprises seek unified branding across merchandise, marketing materials, and promotional items with consistent color management.
- Consumers:Individual purchasers drive one-off gifting and personalization demand with lower repeat rates.
- Designers:Micro-brands and boutique fashion labels adopt precision droplet control systems for photographic reproduction on premium substrates.
Artists command the deepest engagement with platform tools, while Businesses is gaining share fastest as brand merchandising standardizes.
Application:
Workflow velocity and substrate versatility determine competitive positioning across use cases with divergent design-to-ship requirements.
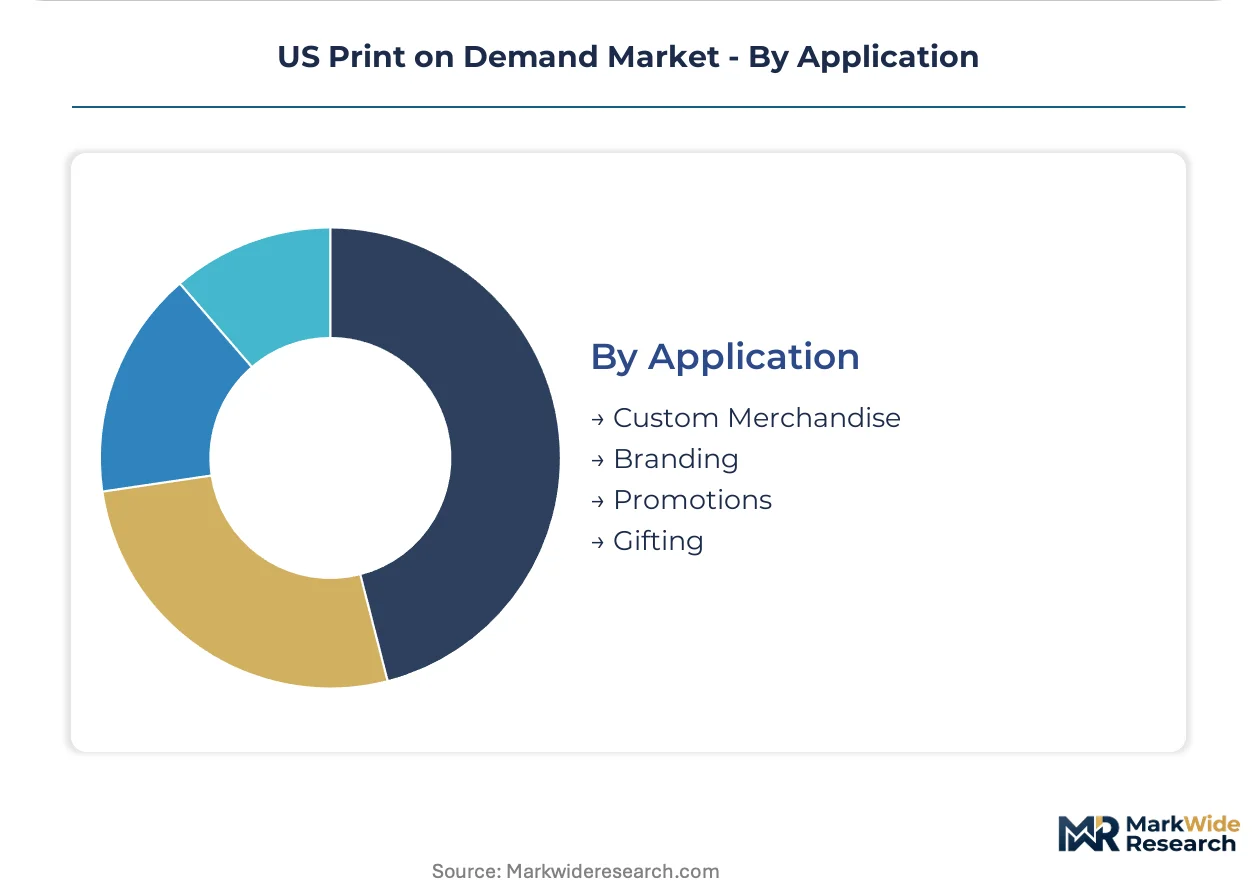
- Custom Merchandise:Limited drops for musicians, podcasters, and content creators demand rapid turnaround on mixed soft and hard goods. Hybrid UV-DTG systems enable unified storefronts across substrate types.
- Branding:Corporate identity programs require color consistency across apparel, drinkware, and stationery with ICC profiling rigor.
- Promotions:Event-driven and campaign-based orders concentrate volume in compressed windows, stressing fulfillment node capacity.
- Gifting:Personalization at lot size one drives seasonal demand spikes with higher margin tolerance but lower repeat purchase probability.
Custom Merchandise generates the highest platform engagement, while Branding is climbing the fastest as small business merchandising professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertically integrated production facilities cluster heavily in Texas and North Carolina, with California and Florida serving as dense creator economy demand nodes. Geographic concentration creates both fulfillment velocity advantages and weather-related vulnerability for national delivery commitments.
California
Creator economy density in Los Angeles and San Francisco drives platform-native merchandise launches with same-day fulfillment expectations. Extended producer responsibility frameworks from the California Department of Resources Recycling and Recovery mandate textile waste stream documentation and packaging recyclability disclosures. San Diego and Oakland host specialized DTG production clusters where independent artists leverage automated design-to-ship workflows.
Texas
Dallas-Fort Worth and Austin anchor the largest vertically integrated fulfillment footprint, with production nodes enabling under-24-hour delivery windows for domestic orders. ERCOT grid instability and hurricane exposure create operational vulnerability during peak seasonal demand. Houston's e-commerce logistics corridor supports distributed partner networks that reduce shipping zones for Great Plains orders.
North Carolina
Charlotte and Raleigh-Durham production facilities serve as secondary fulfillment anchors for East Coast delivery compression. State workforce development programs through the North Carolina Community College System address technician training gaps in RIP software proficiency and ICC profiling. The Research Triangle hosts emerging hybrid UV-DTG system deployments enabling rigid substrate diversification.
Florida
Miami and Tampa creator communities report higher social commerce conversion rates from platform-native storefronts than redirected e-commerce paths. State sales tax nexus thresholds tightened in 2021, multiplying compliance obligations for platforms serving creators nationwide. Orlando's tourism-adjacent gifting demand drives seasonal volume spikes in personalized merchandise categories.
Illinois
Chicago represents an underpenetrated Midwestern fulfillment gap where distributed partner networks could reduce shipping zones for Great Lakes orders. Illinois Environmental Protection Agency emerging frameworks on packaging waste documentation lag California's stringency, creating regulatory arbitrage opportunities. The city's logistics infrastructure supports hybrid models combining in-house production with partner network overflow capacity.
US Print on Demand Market Competitive Landscape
Concentration sits with vertically integrated specialists controlling captive production facilities, while distributed partner network operators occupy a secondary tier. The market structure fragments across three strategic archetypes: fulfillment-integrated platforms, technology-layer intermediaries, and creative marketplace aggregators. M&A activity concentrates on acquiring regional production capacity, while portfolio diversification moves target hybrid substrate capabilities spanning soft goods and hard accessories.
Among vertically integrated operators, Printful exemplifies the captive production archetype with North Carolina and Texas facility control, while Gooten anchors the distributed partner network model. VistaPrint occupies a position bridging small business merchandising with unified branding services. These three represent divergent competitive vectors: velocity-through-capture, zone-reduction-through-partners, and brand-consistency-through-consolidation.
| Leading Market Players |
|---|
| Printful |
| Printify |
| Gelato |
| CustomCat |
| Gooten |
| VistaPrint (Cimpress) |
| Redbubble |
| Zazzle |
| Spreadgroup |
| Others |
Pricing and Supply Chain Analysis
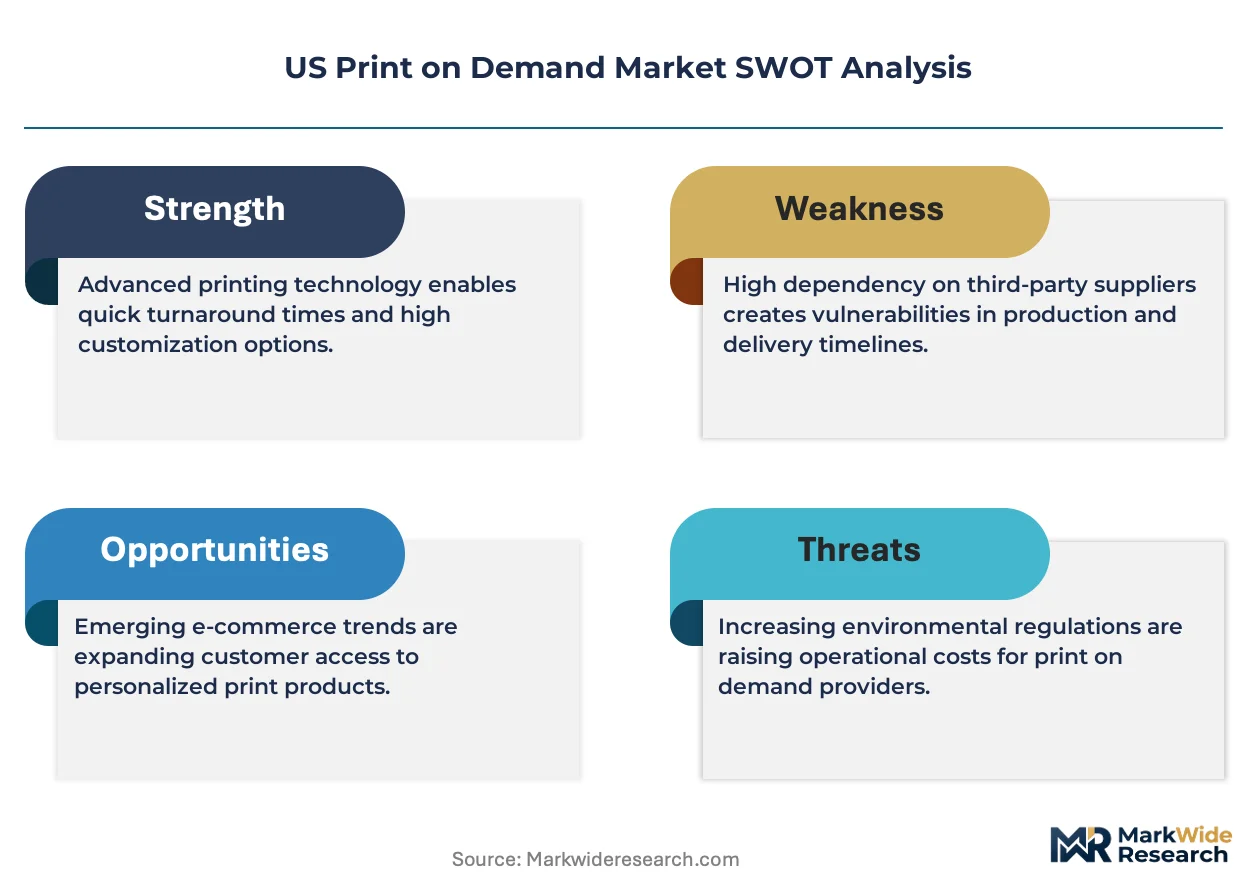
Capacity reservation contracts with DTG ink suppliers lock in pigment access and buffer Printful against petrochemical price swings while fixing unit economics for California and Texas fulfillment nodes. These arrangements tether price visibility to supply security across the forecast window.
Pricing Analysis
FTC substantiation guidelines dictate the pricing tier structure across platform-native storefronts and marketplace aggregators. Three-tier pricing structure across premium, standard, and economy levels separates ring-spun cotton substrates from tri-blend fabrics and basic cotton blends. Cost compression in economy tiers is intensifying because water-based DTG formulations depend on petroleum-derived binders. Small business purchasers seeking unified branding show least price sensitivity, while individual consumers drive gifting demand with highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes fluctuate with container availability at Los Angeles and Long Beach ports, compressing margin buffers for platforms dependent on imported blank apparel. Manufacturing concentrates in China, Bangladesh, and Vietnam for raw textile inputs, while domestic fulfillment clusters in Texas and North Carolina. The supply chain rests on specialty dye and pigment ink sources from Germany and Japan. Single-source vulnerability sits with DTG printhead suppliers. Distribution runs through vertically integrated production facilities and distributed partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as creator economy density in California and Texas accelerates zero-inventory merchandise adoption beyond traditional wholesale channels.
For Market Incumbents: Secure captive production capacity in Ohio and Illinois to close Midwestern fulfillment gaps before distributed partner networks establish zone-reduction advantages. Harden Texas facilities against ERCOT grid instability through backup power infrastructure. Invest in RIP software training pipelines to address color management expertise scarcity threatening output consistency. For New Entrants and Emerging Players: Anchor in ceramic-grade mug and phone case specialization to sidestep California textile waste documentation burdens while capturing hard accessory margin pools. Target social commerce checkout tools as the most penetrable channel, where TikTok Shop and Instagram native purchasing compress discovery-to-confirmation windows for independent artists. For Investors and Strategic Acquirers: Distributed partner network operators with granular supply chain tracking capabilities represent the most attractive acquisition archetype as extended producer responsibility frameworks favor compliance-based differentiation. Watch California Department of Resources Recycling and Recovery enforcement patterns as the signal indicating when textile waste documentation requirements will tighten economic presence thresholds for smaller platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Midwestern Fulfillment Node Expansion | Ohio and Illinois capacity reduces shipping zones for Great Lakes orders. |
| Hybrid UV-DTG System Deployment | Research Triangle installations enable rigid substrate diversification beyond apparel. |
| Social Commerce Platform Integration | TikTok Shop and Instagram native checkout tools displace marketplace aggregators. |
| Textile Waste Documentation Infrastructure | Granular supply chain tracking creates compliance-based differentiation under CalRecycle frameworks. |
| Technician Training Pipeline Investment | North Carolina Community College System partnerships address RIP software proficiency gaps. |
Research Methodology
A spread of perspectives from platform operations directors, DTG production technicians, independent artist-creators, and e-commerce logistics coordinators converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from SEC filings of publicly listed fulfillment platforms, US Census Bureau e-commerce data, and FTC advertising substantiation guidance documents. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type, sales channel, end user archetype, and application use case across the projection horizon. CAGRs derived from historical volume trajectories and penetration rate assumptions. Forecast inputs incorporated DTG ink chemistry advancement curves and creator economy platform adoption metrics throughout the forecast period.
Underlying assumptions cover stable petrochemical input costs and continued FTC enforcement patterns, with deviation risk concentrated in California extended producer responsibility framework acceleration and ERCOT grid instability events. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Card Printers Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Book Printing Service Market
Printing Technology
Web to Print Market
Printing Technology
Digital Paper System Market
Printing Technology
Managed Print Services Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Large Format Printer Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Global Wireless Printers Market
Printing Technology
ID Card Printers Market
Printing Technology
Printing Machinery Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Automated Document Inserter (ADI) Market