
 Ultraviolet Data Logger Market | 2026-2036
Ultraviolet Data Logger Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraviolet Data Logger Market Insights
Equipment-as-a-service leasing for precision UV monitoring instrumentation is reconfiguring competitive entry barriers across the sector. Thermo Fisher Scientific leverages captive service networks to sustain recurring revenue streams in pharmaceutical validation. Shimadzu Corporation anchors Asian supply through spectroscopy manufacturing depth. Onset Computer Corporation specializes in compact portable designs that compete on deployment flexibility for field environmental audits.
An ultraviolet data logger measures electromagnetic radiation intensity across the UVA, UVB, and UVC spectrum bands, typically employing silicon photodiode or gallium nitride sensors with calibrated responsivity curves traceable to NIST standards. These instruments archive irradiance data against timestamped intervals to verify germicidal efficacy, polymer curing exposure, or occupational safety limits. Portable and wireless product categories lead volume shipments due to distributed deployment across pharmaceutical cleanrooms and food processing lines. Cloud-based technology segments attract the fastest upgrade cycles as facilities integrate real-time UV dose tracking into centralized quality management systems. Analog technology persists in cost-sensitive industrial settings where legacy calibration protocols remain entrenched.
FDA 21 CFR Part 11 electronic records requirements shape software architecture decisions for pharmaceutical end users seeking audit-ready data trails. EMA Annex 15 qualification guidelines and EU MDR device traceability rules extend compliance burdens across European laboratory and healthcare installations. Stakeholders must weigh sensor calibration frequency against cloud subscription economics when specifying next-generation UV monitoring infrastructure.
Market Dynamics
Cloud-based UV dose tracking is virtualizing data infrastructure across pharmaceutical cleanrooms, compressing hardware refresh cycles while elevating software subscription economics above standalone instrument sales.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in US pharmaceutical manufacturing force validation-grade UV logger deployments with audit-ready data trails.
- Photodiode sensor miniaturization:Silicon and gallium nitride responsivity improvements enable palm-sized wireless units for distributed food processing line monitoring.
- Germicidal efficacy verification:Hospital HVAC systems and water treatment facilities deploy timestamped irradiance logging to prove UVC sterilization compliance.
Market Restraints
- NIST-traceable calibration costs:Annual recertification expenses for silicon photodiode arrays burden small environmental audit firms with limited capital reserves.
- Gallium nitride wafer supply:Sensor-grade substrate manufacturing concentrates among specialized semiconductor foundries, creating input bottlenecks for high-precision UVC detection.
- Legacy analog persistence:Cost-sensitive industrial settings retain entrenched calibration protocols, slowing digital logger penetration in mature manufacturing regions.
Strategic Opportunities
- Equipment-as-a-service leasing:Recurring revenue models reduce upfront capital barriers for mid-sized pharmaceutical validation laboratories seeking precision instrumentation.
- EU MDR device traceability:European medical device marking requirements create upgrade demand across German and Swiss healthcare installations for qualified UV monitoring systems.
- Real-time cloud integration:Centralized quality management system convergence enables subscription-based analytics layers atop hardware deployments.
Industry Challenges
- Metrology talent scarcity:Specialized UV spectroscopy calibration expertise remains concentrated among aging technician pools in national standards laboratories.
- Legacy system integration:Pharmaceutical facilities face complex middleware requirements when connecting wireless loggers to existing SCADA and LIMS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraviolet Data Logger Market |
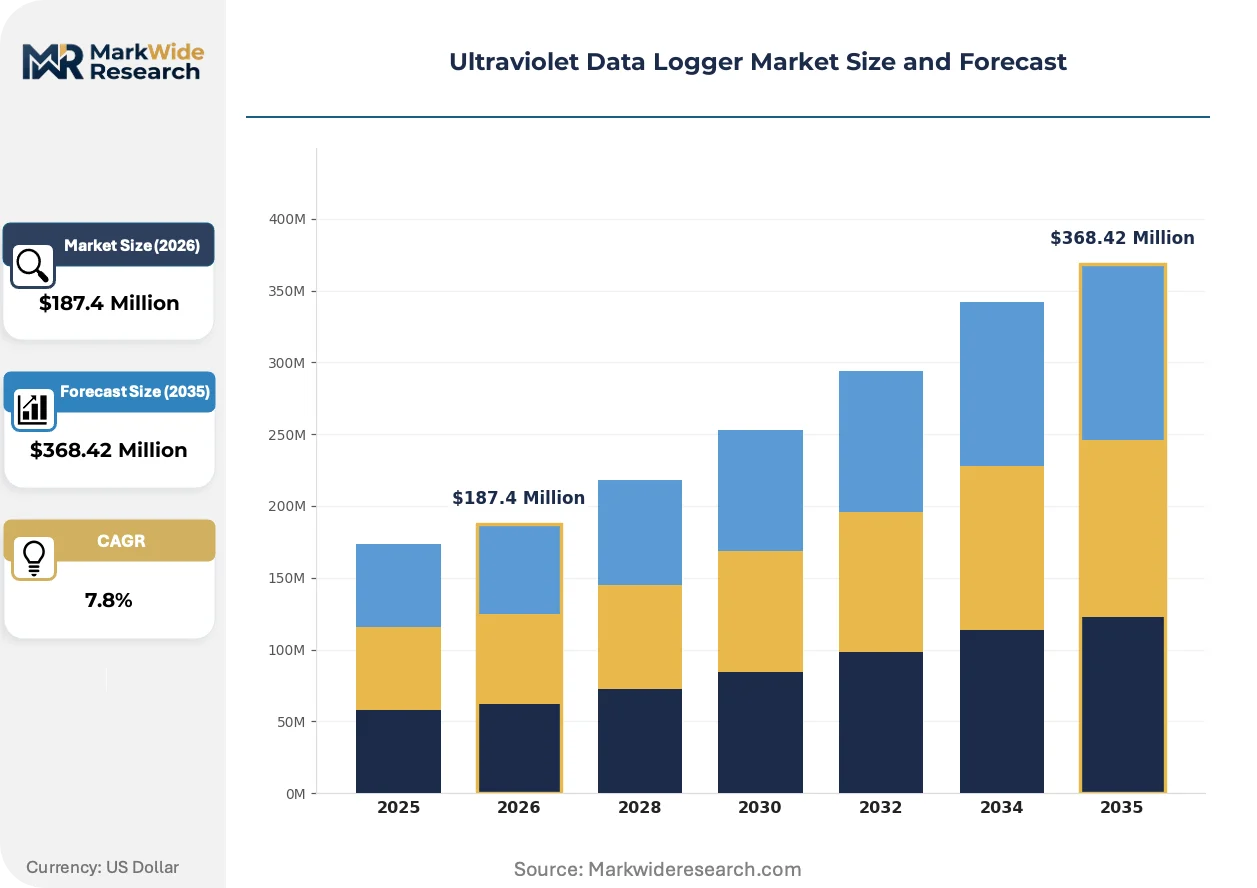
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $368.42 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
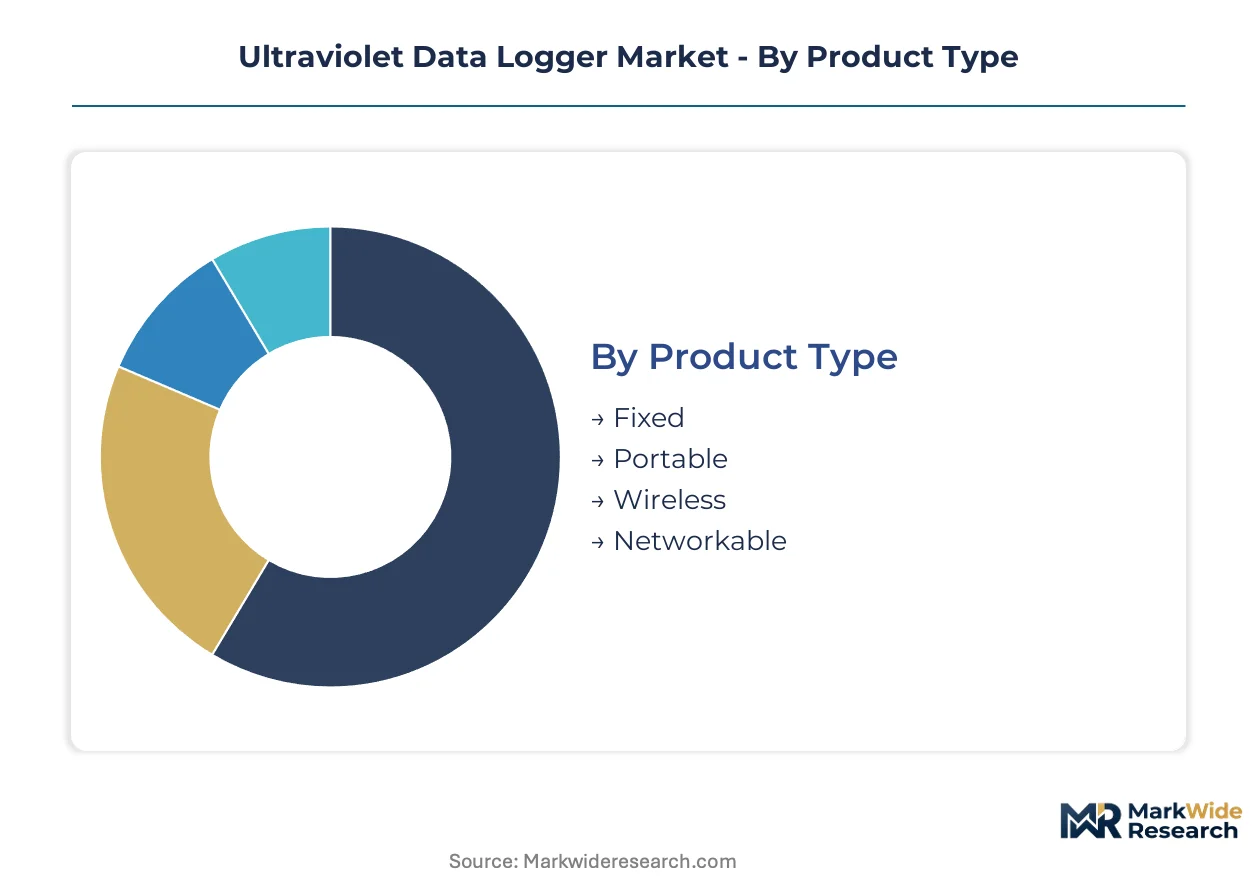
| Segmentation | Product Type: Fixed, Portable, Wireless, Networkable Technology: Analog, Digital, Hybrid, Cloud-Based Application: Food Safety, Environmental Monitoring, Pharmaceutical, Industrial End User: Agriculture, Healthcare, Laboratories, Manufacturing |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Shimadzu Corporation, PerkinElmer, Inc., Hamamatsu Photonics K.K., Solar Light Company, LLC, MadgeTech, Inc., Onset Computer Corporation, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraviolet Data Logger Market Trends and Innovations
Spectroscopy manufacturing depth and captive service networks are reconfiguring competitive positioning, as hardware commoditization pressures force differentiation through software analytics and validation support ecosystems.
Silicon photodiode arrays with integrated analog-to-digital conversion are virtualizing the signal processing chain that previously demanded external conditioning hardware. Pharmaceutical manufacturers in Bavaria and Baden-Württemberg adopt these compact modules for cleanroom validation protocols, collapsing deployment timelines from weeks to days while shifting value capture toward firmware and cloud analytics layers.
EMA Annex 15 qualification guidelines extend GMP documentation burdens across European laboratory installations, mandating IQ/OQ/PQ protocols for UV sterilization equipment. Medical device manufacturers in Switzerland and Germany respond by specifying loggers with embedded electronic signature capabilities, compressing vendor qualification cycles and elevating software architecture decisions in procurement evaluations.
Validation service unbundling from hardware sales is fragmenting buyer-supplier relationships across the sector. Mid-sized environmental consultancies in industrial clusters now procure portable units through distributor channels while sourcing calibration and compliance documentation separately, a pattern most visible in German chemical safety audits where ECHA reporting requirements demand specialized documentation support beyond standard manufacturer offerings.
Ultraviolet Data Logger Market Segmentation
UV data logger procurement varies sharply by deployment context, with calibration service contracts and firmware update subscriptions creating divergent lifetime cost structures across product categories. Pharmaceutical validation workflows demand NIST-traceable documentation packages that reshape vendor selection criteria beyond hardware specifications alone.
Product Type:
After-sales calibration intensity separates fixed installations from distributed field deployments, with service contract economics dictating total cost of ownership calculations across buyer segments.
- Fixed:Permanent installations integrate with facility SCADA architectures through hardwired 4-20mA or Modbus outputs. Bavarian pharmaceutical manufacturers specify these for cleanroom ceiling-mounted UVC sterilization monitoring where FDA 21 CFR Part 11 compliance documentation bundles into multi-year service agreements.
- Portable:Battery-powered handheld units with local LCD readouts serve environmental audit firms conducting spot-check irradiance surveys. German chemical safety inspectors under ECHA reporting mandates favor these for rapid deployment across multiple industrial sites without infrastructure dependencies.
- Wireless:Bluetooth and WiFi-enabled loggers transmit timestamped readings to mobile applications for distributed food processing line monitoring.
- Networkable:Ethernet-connected devices stream data directly into centralized LIMS or quality management databases for continuous compliance verification.
Fixed installations hold the largest share; momentum sits with wireless configurations.
Technology:
Cost tier stratification separates legacy analog persistence from premium digital architectures, with subscription economics creating distinct buyer segments.
- Analog:Voltage-output photodiode circuits without onboard processing persist in cost-sensitive industrial curing applications. Mature manufacturing regions retain these where legacy calibration protocols and technician familiarity outweigh digital upgrade incentives.
- Digital:Integrated analog-to-digital converters with onboard memory and USB data retrieval dominate pharmaceutical validation workflows. Swiss medical device manufacturers specify these for IQ/OQ/PQ qualification packages under EU MDR traceability requirements.
- Hybrid:Local digital storage with optional analog backup outputs bridges transition scenarios in facilities with mixed infrastructure.
- Cloud-Based:Continuous cellular or WiFi connectivity enables real-time dashboard analytics and automated alert generation for critical sterilization processes.
Digital architectures command the dominant position; cloud-based deployments are climbing the fastest.
Application:
Regulatory burden intensity varies by compliance domain, with pharmaceutical and food safety mandates driving precision instrumentation specifications.
- Pharmaceutical:Cleanroom UVC dosage validation requires irradiance mapping across multiple grid points with electronic signature capabilities. FDA sterilization standards and EMA Annex 15 GMP guidelines force redundant sensor configurations and encrypted data trails.
- Food Safety:Conveyor belt sterilization monitoring in dairy and beverage processing demands washdown-rated enclosures and rapid deployment flexibility. HACCP documentation requirements drive timestamped logging with tamper-evident data storage.
- Environmental Monitoring:Atmospheric UV index tracking and ozone layer research applications prioritize spectral accuracy over industrial ruggedization.
- Industrial:Polymer curing and printing press applications emphasize cost minimization over metrological precision.
Pharmaceutical applications hold the largest share; food safety represents the steepest expansion trajectory.
End User:
Customer type determines procurement channel and service bundling preferences, with healthcare and laboratory segments demanding qualified validation support.
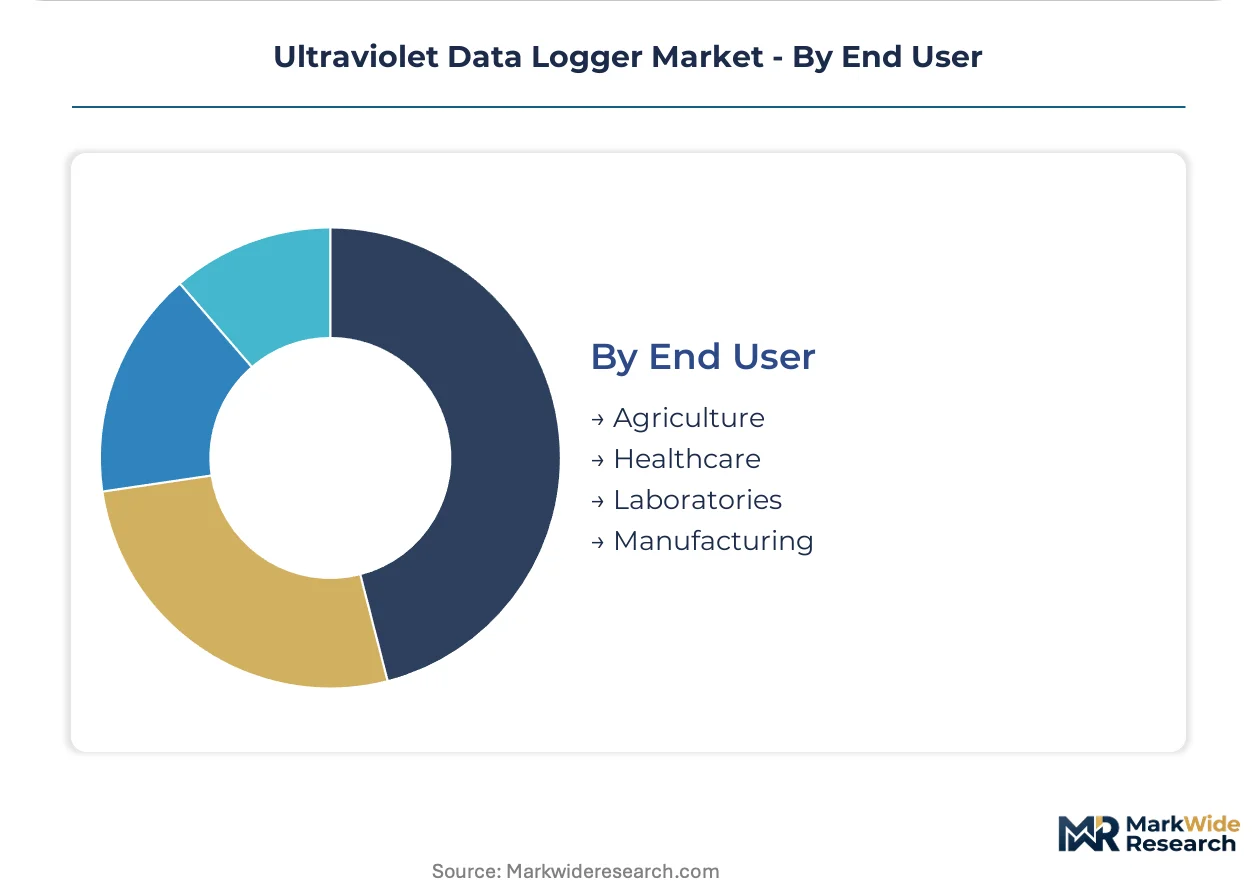
- Healthcare:Hospital HVAC sterilization and surgical suite UVC systems require continuous dose verification with integration into facility management platforms. Joint Commission accreditation standards drive specification of medical-grade enclosures and calibration certificates.
- Laboratories:Research and quality control facilities prioritize spectral resolution and NIST-traceable uncertainty budgets. German and Swiss analytical laboratories under ISO 17025 accreditation mandate documented measurement traceability chains.
- Manufacturing:Industrial processing lines emphasize total cost minimization and rapid deployment turnaround.
- Agriculture:Greenhouse UV supplementation and post-harvest sterilization applications favor ruggedized portable units for seasonal deployment patterns.
Healthcare installations hold the largest share; laboratory procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sterilization mandates in the United States, EMA Annex 15 qualification guidelines across Europe, and China's dual carbon goals are redrawing procurement patterns for precision UV monitoring instrumentation. National regulators now dictate sensor calibration frequencies and data integrity architectures that reshape vendor selection criteria.
United States
Pharmaceutical cleanroom validation and hospital HVAC sterilization verification dominate procurement volumes. FDA 21 CFR Part 11 electronic records requirements force encrypted data trails and audit-ready documentation packages. Massachusetts and North Carolina biotech clusters specify wireless loggers for distributed UVC dosage mapping across multi-site manufacturing networks.
Germany
ECHA chemical safety reporting and EU MDR device traceability rules drive precision instrumentation upgrades. Bavarian and Baden-Württemberg industrial clusters deploy fixed installations with multi-year service agreements for cleanroom ceiling-mounted monitoring. Stuttgart-based analytical laboratories mandate NIST-traceable uncertainty budgets under ISO 17025 accreditation protocols.
Switzerland
Swissmedic medical device regulations and pharmaceutical manufacturing excellence standards elevate software architecture decisions in procurement evaluations. Basel and Zurich healthcare installations specify loggers with embedded electronic signature capabilities for IQ/OQ/PQ qualification packages. The country's precision instrumentation heritage reinforces demand for spectral accuracy in sterilization verification workflows.
China
NMPA pharmaceutical manufacturing standards and MIIT industrial digitalization initiatives accelerate cloud-based logger deployments. Yangtze River Delta pharmaceutical hubs integrate real-time UV dose tracking into centralized quality management systems. Shanghai and Suzhou facilities prioritize domestic sensor-grade substrate sourcing to mitigate gallium nitride wafer supply bottlenecks.
Japan
METI industrial technology roadmaps and PMDA pharmaceutical quality guidelines shape validation-grade instrumentation specifications. Kansai and Chubu manufacturing regions emphasize compact wireless designs for distributed food processing line monitoring. Osaka-based polymer curing operations retain hybrid analog-digital architectures during infrastructure transition phases.
Ultraviolet Data Logger Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified analytical instrumentation conglomerates with captive service networks, specialized spectroscopy manufacturers with semiconductor fabrication depth, and compact portable design specialists competing on deployment flexibility. Strategic archetypes include validation service integrators, sensor technology vertically integrated players, and cloud analytics platform providers. Dominant competitive moves encompass equipment-as-a-service leasing model expansion and strategic partnerships for calibration infrastructure access.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. represent North American conglomerates with established pharmaceutical validation ecosystems. Shimadzu Corporation anchors Japanese spectroscopy manufacturing depth. Among compact portable specialists, Onset Computer Corporation exemplifies deployment flexibility positioning for field environmental audit applications. These named entities occupy positions that reflect broader competitive archetypes rather than discrete strategic actions, with each representing distinct approaches to recurring revenue capture and geographic market access.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| Shimadzu Corporation |
| PerkinElmer, Inc. |
| Hamamatsu Photonics K.K. |
| Solar Light Company, LLC |
| MadgeTech, Inc. |
| Onset Computer Corporation |
| Fluke Corporation |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Suzhou freight corridors absorb gallium nitride wafer import costs that compress margins for domestic UV sensor assembly while amplifying price spreads between NIST-traceable pharmaceutical-grade units and economy analog alternatives across Chinese and German procurement channels.
Pricing Analysis
Certification level (ISO 17025/FDA 21 CFR Part 11/CE-IVD-grade) creates the primary spread between entry-level environmental audit units and validation-grade pharmaceutical installations. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales calibration bundling intensity and firmware subscription attach rates. Cost compression in economy analog tiers is intensifying because legacy industrial curing facilities resist digital upgrade investments. Small environmental consultancies exhibit highest price sensitivity; Swiss medical device manufacturers under Swissmedic regulations demonstrate lowest elasticity due to IQ/OQ/PQ qualification documentation requirements.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic sourcing decisions for silicon photodiode arrays and gallium nitride sensor substrates. Manufacturing concentrates in Japan, Germany, and China, with sensor-grade substrate fabrication anchored in specialized semiconductor foundries across East Asia. Raw material dependencies include high-purity silicon wafers, gallium nitride epitaxial layers, and calibrated optical filter glass. Single-source vulnerability persists for NIST-traceable calibration reference standards. Distribution runs through analytical instrumentation distributors and direct OEM channels serving pharmaceutical validation laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where FDA 21 CFR Part 11 and EMA Annex 15 documentation requirements create switching costs that protect incumbent validation service ecosystems.
For Market Incumbents: Insulate recurring revenue streams by embedding cloud analytics subscriptions into multi-year pharmaceutical service agreements. Deepen captive calibration infrastructure across Bavarian and Baden-Württemberg industrial clusters to preempt third-party validation service unbundling. Counter portable wireless specialist encroachment through firmware-locked sensor ecosystems that complicate customer migration. For New Entrants and Emerging Players: Build out equipment-as-a-service leasing models targeting mid-sized German chemical safety audit firms constrained by NIST-traceable calibration capital requirements. Food safety conveyor belt monitoring in Yangtze River Delta dairy processing represents the most penetrable white-space segment. Pursue distributor channel partnerships with existing environmental instrumentation resellers to bypass direct incumbent field service network disadvantages. For Investors and Strategic Acquirers: EU MDR device traceability implementation reshapes the acquisition landscape toward cloud-native validation software platforms with embedded electronic signature capabilities. Five-to-ten-year viability favors targets combining spectroscopy manufacturing depth with recurring service contract density. Monitor FDA enforcement action intensity against pharmaceutical data integrity violations as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Leasing Expansion | Reduces capital barriers for mid-sized pharmaceutical validation laboratories seeking precision UV monitoring instrumentation. |
| Cloud Analytics Platform Integration | Enables real-time UV dose tracking convergence with centralized quality management systems under FDA 21 CFR Part 11 mandates. |
| Calibration Infrastructure Partnership | Secures NIST-traceable metrology access that differentiates vendor qualification cycles for EMA Annex 15 compliance documentation. |
| Sensor Technology Vertical Integration | Mitigates gallium nitride wafer supply bottlenecks through in-house epitaxial layer production for high-precision UVC detection. |
| Geographic Manufacturing Footprint Expansion | Establishes regional assembly presence in Stuttgart and Suzhou to compress deployment timelines for pharmaceutical cleanroom validation. |
Research Methodology
The analysis maps fixed installation, portable, wireless, and networkable product categories, each validated through plant engineers at pharmaceutical manufacturers, calibration technicians at national standards laboratories, procurement managers at analytical instrumentation distributors, and regulatory affairs specialists at medical device OEMs. Primary interview findings triangulate against FDA 510(k) filings, EMA qualification guideline documentation, ISO 17025 accreditation records, and customs trade data for photodiode sensor imports. Bottom-up shipment estimates reconcile with top-down pharmaceutical capital expenditure patterns across the analysis window.
Forecast assumptions hold regulatory enforcement intensity and sensor miniaturization cost curves fixed while varying pharmaceutical manufacturing expansion rates and cloud infrastructure adoption patterns across regional clusters. Segmentation dimensions modeled include product mobility class, data architecture type, application compliance domain, end-user facility type, and regional regulatory framework cluster. CAGRs derive from installed base growth rates and replacement cycle compression observed across the projection horizon. Industry-specific inputs incorporate gallium nitride substrate supply constraints and ECHA chemical safety audit frequency trends.
Stress conditions across FDA inspection enforcement intensity, gallium nitride wafer pricing volatility, and pharmaceutical manufacturing relocation patterns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and semiconductor supply chain continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market