
 Digital Production Printer Market | 2026-2036
Digital Production Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Production Printer Market Analysis
The capital-intensity divergence between players is rotating competitive advantage toward firms with captive ink and printhead manufacturing. Canon Inc. leverages backward integration into precision printhead fabrication to sustain margin control across high-volume contracts. Fujifilm Business Innovation Corp. anchors its position through proprietary UV ink chemistry that differentiates output durability for commercial packaging clients.
A digital production printer is an industrial-grade output system engineered for continuous or near-continuous operation at speeds exceeding 100 pages per minute, employing either electrophotographic toner transfer or piezoelectric inkjet deposition to render variable-data content onto paper, film, or synthetic substrates. These systems serve commercial print shops and in-house departments requiring on-demand, short-run production without plate-making overhead. Inkjet printers are capturing share fastest as piezoelectric heads achieve photographic resolution at production speeds previously exclusive to electrophotography. High-speed printers retain the largest installed base but face margin compression as laser technology matures across commercial printing applications.
EPA Energy Star specifications and EU Ecodesign Directive thresholds constrain standby power and per-page energy consumption for equipment sold in the United States and European markets. Japan's METI administers Top Runner standards that escalate efficiency benchmarks for production printers manufactured or imported domestically. Buyers must weigh total cost of ownership against regulatory compliance timelines when selecting between electrophotographic and inkjet architectures.
Market Dynamics
Electrophotographic toner systems face margin compression as piezoelectric inkjet architectures achieve photographic resolution at production-line speeds, forcing incumbents to defend installed bases through consumables lock-in strategies.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby-power thresholds for production-class equipment accelerate replacement cycles among European commercial print service providers.
- Short-run packaging:E-commerce fulfillment networks demand variable-data cartons and labels without plate-making overhead, pulling inkjet capacity into corrugated and flexible substrate applications.
- German print consolidation:Capacity rationalization among Mittelstand commercial printers creates demand for fewer, higher-utilization digital production systems.
Market Restraints
- Piezoelectric printhead supply:Precision MEMS fabrication concentrates among Japanese and German component suppliers, exposing buyers to allocation risk during demand surges.
- UV-curable ink input costs:Photoinitiator and oligomer prices track petrochemical feedstock volatility, compressing margins for UV inkjet operators.
- Toner particle engineering:Sub-7-micron polymerization requirements limit qualified chemical suppliers to a handful of specialty resin manufacturers.
Strategic Opportunities
- India corrugated packaging:FMCG sector growth and fragmented flexographic infrastructure create white space for on-demand digital carton production.
- Japan METI Top Runner:Escalating efficiency benchmarks for domestically manufactured equipment reward early movers with procurement preference in public-sector tenders.
- Textile pigment inkjet:Convergence of reactive dye chemistry and high-speed scanning heads enables direct-to-fabric production without water-intensive pretreatment.
Industry Challenges
- Color management expertise:ICC profile optimization and substrate-specific calibration require skilled technicians that commercial print shops struggle to retain.
- EPA Energy Star certification timelines:Third-party verification delays for new electrophotographic architectures extend product launch windows by 8-14 months.
- Legacy prepress integration:MIS-to-press workflow connectivity demands custom API development that fragments across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Production Printer Market |
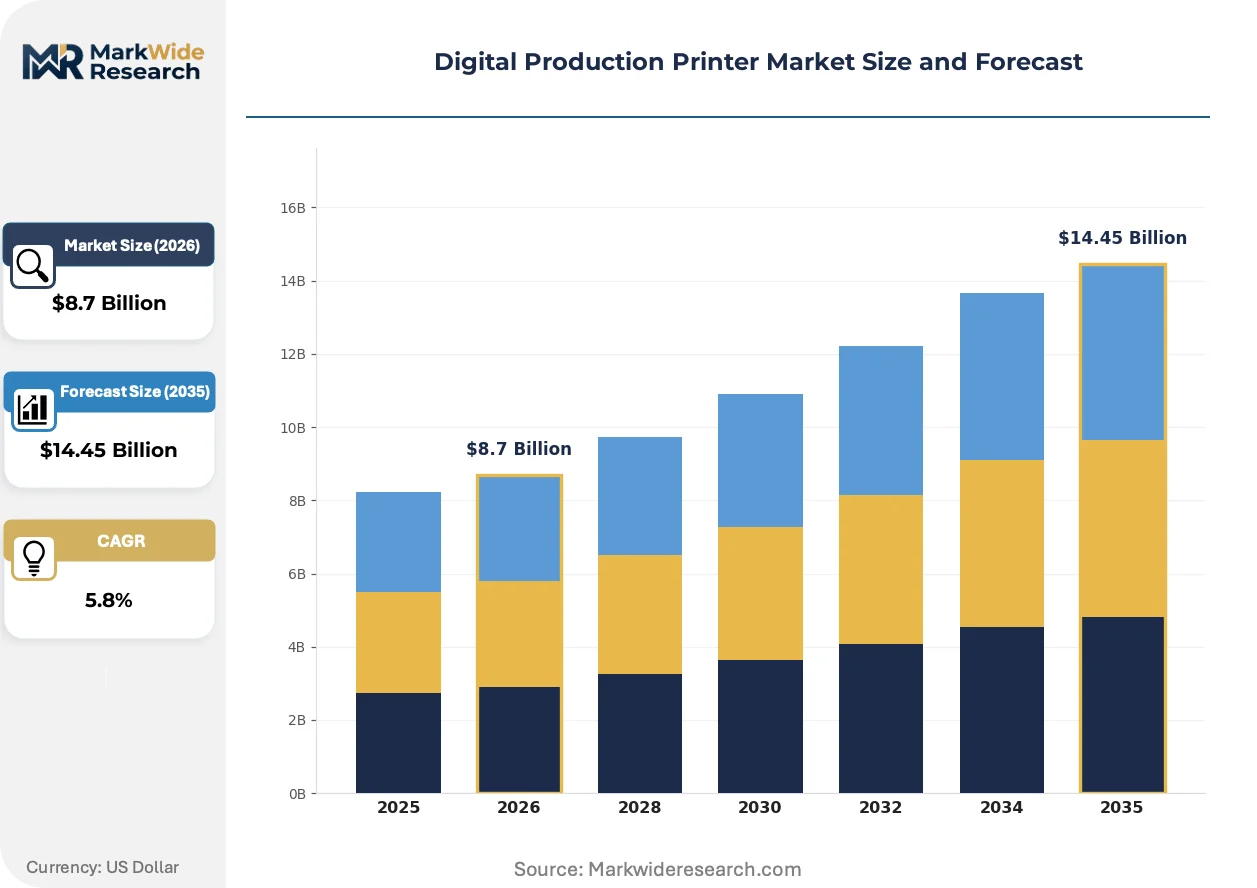
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Printers, Inkjet Printers, Laser Printers, Digital Label Printers Technology: Electrophotography, Piezoelectric, Thermal Inkjet, Continuous Feed Technology Application: Packaging, Commercial Printing, Labeling, Photo Printing End User: Publishing Houses, Printing Services, Advertising Agencies, In-House Print Departments |
| Companies Covered | Ricoh Company Ltd., Fujifilm Business Innovation Corp., Xerox Corporation, Brother Industries Ltd., Seiko Epson Corporation, Canon Inc., Konica Minolta Inc., Ninestar Corporation, HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Production Printer Market Emerging Trajectories
Piezoelectric deposition architectures are fragmenting competitive advantage away from electrophotographic incumbents toward chemistry-captive specialists. Regulatory efficiency mandates and buyer procurement rationalization are compressing technology transition timelines.
Inkjet printhead technology is bifurcating the production printer landscape. Single-pass array architectures now render variable data at 300+ meters per minute on corrugated substrates. Commercial packaging converters in Germany and Japan are retiring flexographic units for these systems. The technology is bifurcating equipment margins: electrophotographic vendors defend toner lock-in while inkjet specialists capture premium through proprietary ink formulations.
EPA Energy Star Version 3.0 specifications impose standby-power ceilings below 30 watts for production-class equipment sold in the United States. Manufacturers must redesign power-supply architectures and fuser subsystems to qualify. High-volume electrophotographic lines face the steepest engineering cost, pushing development resources toward inkjet platforms that naturally achieve lower idle consumption.
Print service providers are consolidating vendor relationships around full-page-cost contracts that bundle hardware, consumables, and remote monitoring. Equipment financiers and managed print service operators displace traditional distributor channels in North American and Western European markets. Germany's consolidated Mittelstand print sector exhibits the most advanced procurement sophistication, with multi-site enterprises negotiating enterprise ink pricing independent of hardware OEMs.
Digital Production Printer Market Segmentation
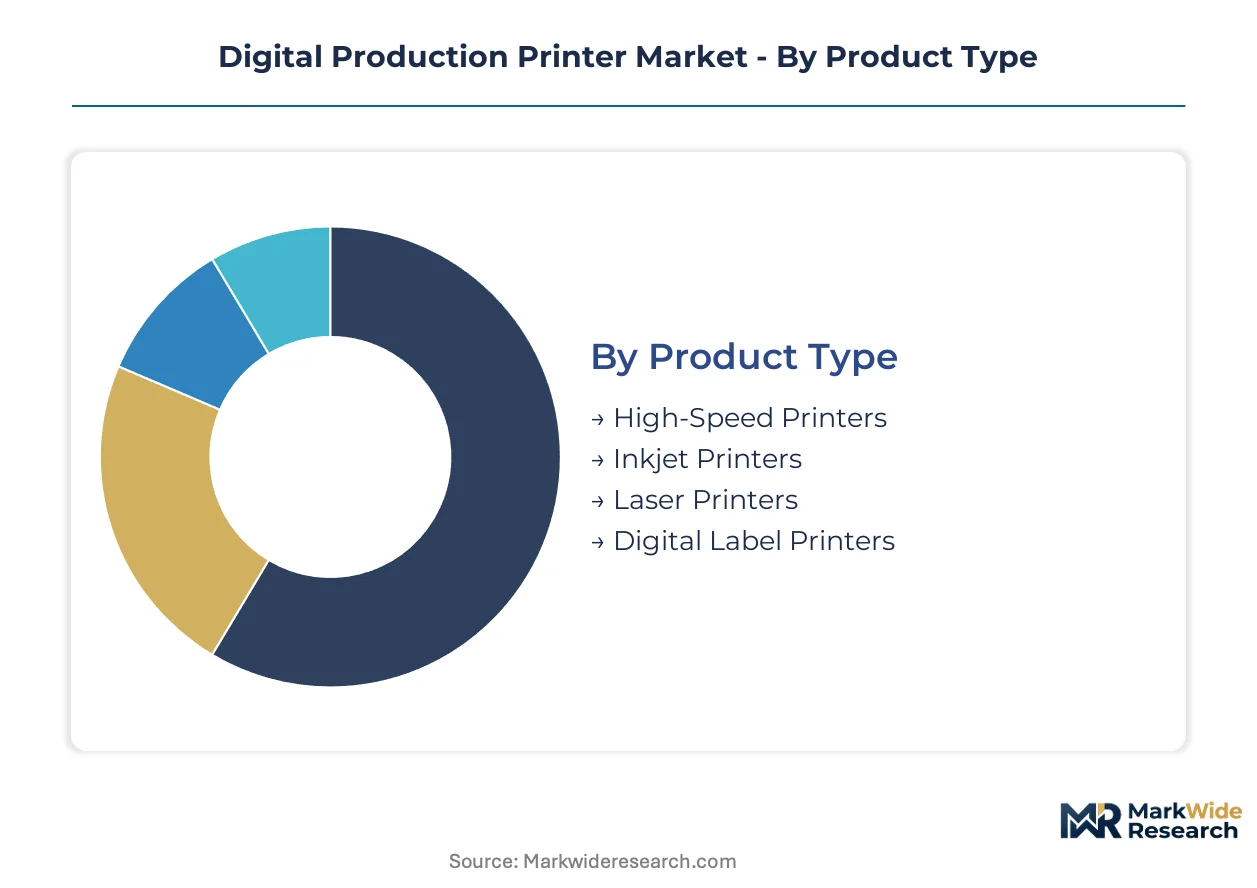
Segmentation in digital production printing reveals how technology choices, application requirements, and customer procurement sophistication distribute margin pools across hardware architectures and service models. Understanding these divisions exposes where equipment vendors can defend pricing power versus where commoditization pressures dominate.
Product Type:
Margin pools concentrate in systems that lock in recurring consumables revenue through proprietary ink or toner formulations, with hardware profitability secondary to lifetime supply contracts.
- Inkjet Printers:Piezoelectric deposition systems achieve photographic resolution at production-line speeds exceeding 300 meters per minute on corrugated substrates. German and Japanese packaging converters are retiring flexographic units for these architectures, pulled by e-commerce demand for variable-data cartons without plate-making overhead.
- High-Speed Printers:Electrophotographic toner systems retain the largest installed base across commercial print shops, though margin compression intensifies as laser technology matures and service providers consolidate vendor relationships around full-page-cost contracts.
- Laser Printers:Sub-7-micron toner particle engineering limits qualified chemical suppliers to specialty resin manufacturers, constraining supply chain flexibility for electrophotographic vendors.
- Digital Label Printers:Narrow-web systems serve short-run flexible packaging and prime label applications where SKU proliferation outpaces conventional press economics.
The dominant share belongs to High-Speed Printers, while Inkjet Printers is closing the gap fastest.
Technology:
Technology selection determines regulatory compliance cost exposure, with architectures varying sharply in their ability to meet tightening energy-efficiency thresholds without fundamental redesign.
- Piezoelectric:MEMS-fabricated printheads from Japanese and German component suppliers enable single-pass array architectures with natural advantages in standby power consumption. EPA Energy Star Version 3.0 specifications favor these systems over electrophotographic alternatives.
- Electrophotography:Toner transfer systems face the steepest engineering cost to redesign power-supply architectures and fuser subsystems for sub-30-watt standby ceilings, pushing development resources toward inkjet platforms.
- Thermal Inkjet:Drop-on-demand deposition serves lower-volume commercial applications where capital constraints outweigh speed requirements.
- Continuous Feed Technology:Web-fed architectures dominate newspaper and book production workflows requiring uninterrupted operation across extended print runs.
Electrophotography holds the largest installed base, though Piezoelectric is expanding most quickly as efficiency mandates accelerate technology transition timelines.
Application:
Application segmentation tracks how substrate versatility and variable-data requirements reshape procurement criteria across end-use verticals.
- Packaging:Corrugated and flexible substrate applications demand UV-curable ink chemistry for durability, with photoinitiator and oligomer prices tracking petrochemical feedstock volatility.
- Commercial Printing:Print service providers in Germany's consolidated Mittelstand sector negotiate enterprise ink pricing independent of hardware OEMs, exhibiting the most advanced procurement sophistication.
- Labeling:Pharmaceutical and food safety regulations drive demand for traceable, variable-data label production with ICC profile optimization requirements.
- Photo Printing:Fine art and photography applications prioritize color gamut and archival stability over speed, sustaining premium pricing for pigment-based ink formulations.
Commercial Printing retains the dominant revenue position, while Packaging is climbing the fastest on e-commerce fulfillment network expansion.
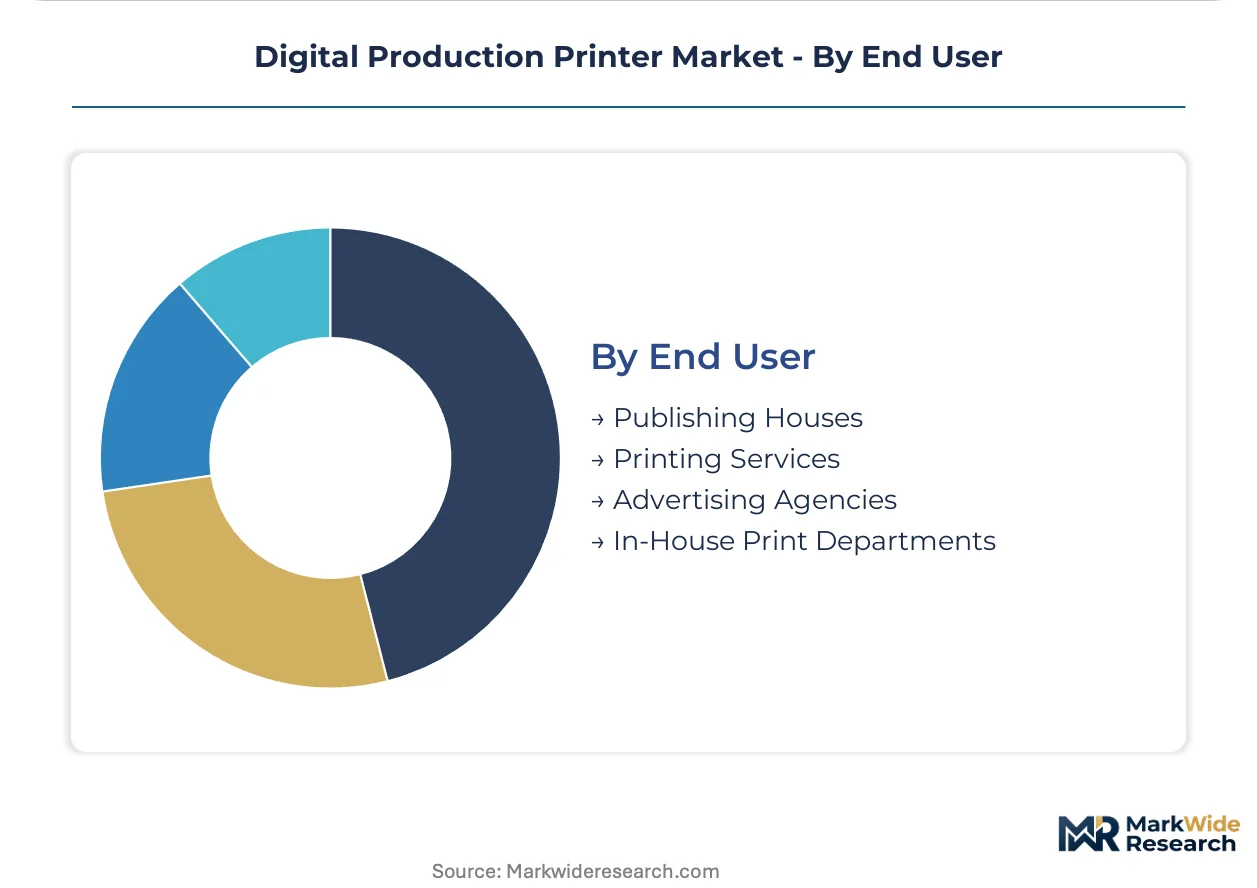
End User:
End user segmentation distinguishes between customers with captive technical expertise and those dependent on vendor-managed service models.
- Printing Services:Commercial print shops consolidate capacity around fewer, higher-utilization digital production systems, with multi-site enterprises in Germany leading procurement rationalization.
- In-House Print Departments:Corporate and institutional facilities favor managed print service contracts bundling hardware, consumables, and remote monitoring, displacing traditional distributor channels.
- Publishing Houses:Book and periodical producers prioritize continuous-feed reliability and MIS-to-press workflow connectivity.
- Advertising Agencies:Creative services demand rapid proofing and short-run campaign materials with substrate flexibility.
Printing Services commands the dominant share, while In-House Print Departments is gaining share fastest as equipment financiers expand managed service penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German print service providers prioritize energy-efficient inkjet replacements for flexographic capacity, while Japanese buyers emphasize domestic MEMS printhead supply security, and US commercial printers consolidate vendor relationships around managed service contracts.
United States
Commercial print shops consolidate capacity around fewer, higher-utilization digital production systems. EPA Energy Star Version 3.0 specifications impose sub-30-watt standby-power ceilings that push development resources toward inkjet architectures. Equipment financiers and managed print service operators displace traditional distributor channels across the Midwest and Southeast printing corridors.
Germany
Mittelstand commercial printers rationalize capacity through multi-site enterprise ink pricing negotiated independent of hardware OEMs. EU Ecodesign Directive tightening of standby-power thresholds accelerates replacement cycles among packaging converters. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia lead adoption of single-pass inkjet arrays for corrugated substrate applications.
Japan
Domestic buyers emphasize supply security for precision MEMS-fabricated printheads concentrated among Japanese component suppliers. METI Top Runner standards escalate efficiency benchmarks for domestically manufactured equipment, rewarding early movers with procurement preference in public-sector tenders. Kanto and Kansai industrial corridors anchor production printer demand from consolidated commercial print service providers.
India
FMCG sector growth and fragmented flexographic infrastructure create white space for on-demand digital carton production in corrugated packaging. Central government efficiency mandates and state-level industrial incentives shape procurement timelines for commercial print investments. Maharashtra and Gujarat manufacturing belts exhibit fastest uptake of inkjet capacity for short-run packaging contracts.
Digital Production Printer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across technology architectures and substrate applications. The upper tier commands advantage through captive ink chemistry and printhead manufacturing, while specialists carve position through proprietary UV formulations or narrow-web label expertise. Two dominant competitive moves define current rivalry: backward integration into consumables production and consolidation of vendor relationships around full-page-cost service contracts.
Within the integrated tier, Canon Inc. and Fujifilm Business Innovation Corp. exemplify chemistry-captive positioning through in-house control over precision fabrication and proprietary formulations. Ricoh Company Ltd. occupies a position bridging electrophotographic installed base defense with selective inkjet portfolio expansion. These three Japanese-origin entities anchor the competitive structure through differentiated approaches to margin capture across hardware and recurring supply revenue streams.
| Leading Market Players |
|---|
| Ricoh Company Ltd. |
| Fujifilm Business Innovation Corp. |
| Xerox Corporation |
| Brother Industries Ltd. |
| Seiko Epson Corporation |
| Canon Inc. |
| Konica Minolta Inc. |
| Ninestar Corporation |
| HP Inc. |
| Others |
Supply Flow & Price Mechanics
UV-curable ink chemistry replacing solvent-based formulations in corrugated packaging is redrawing procurement geography toward Japanese and German photoinitiator suppliers while compressing margins for converters exposed to petrochemical feedstock volatility.
Pricing Analysis
Full-page-cost contracts bundling hardware, consumables, and remote monitoring dominate procurement between commercial print service providers and equipment financiers. Price differentiation separates premium piezoelectric systems with captive ink formulations from standard electrophotographic lines competing on acquisition cost. Cost compression in toner-based equipment intensifies as laser technology matures across commercial applications. Small Mittelstand print shops in Germany exhibit highest price sensitivity, while consolidated multi-site enterprises negotiate enterprise ink pricing independent of hardware OEMs.
Supply Chain Analysis
Inventory lead times for precision MEMS-fabricated printheads stretch 16-24 weeks, exposing buyers to allocation risk during demand surges. Component fabrication concentrates in Japan and Germany, with photoinitiator chemistry drawing from Belgian and Chinese specialty chemical suppliers. Single-source vulnerability pervades sub-7-micron toner resin polymerization, where qualified suppliers number fewer than five globally. Distribution runs through managed print service operators displacing traditional distributor channels across North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital production printer market sits at a cyclical recovery phase driven by EU Ecodesign Directive replacement cycles accelerating equipment refresh timelines among European packaging converters.
For Market Incumbents: Shield installed base revenue by deepening backward integration into printhead MEMS fabrication and proprietary UV ink chemistry. Canon Inc.'s precision fabrication captive supply and Fujifilm Business Innovation Corp.'s proprietary formulations exemplify margin defense against piezoelectric specialists. Prioritize certification investment for EPA Energy Star Version 3.0 compliance to maintain US market access.
For New Entrants and Emerging Players: Anchor in India's corrugated packaging white space where FMCG sector growth and fragmented flexographic infrastructure create demand for on-demand digital carton production. Maharashtra and Gujarat manufacturing belts offer fastest uptake potential for short-run inkjet capacity. Pursue textile pigment inkjet applications where reactive dye chemistry convergence enables direct-to-fabric production without water-intensive pretreatment.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors chemistry-captive specialists over electrophotographic incumbents facing margin compression. Long-term viability through the next decade rests on consumables lock-in rather than hardware shipment volume. Monitor piezoelectric printhead allocation availability as inflection indicator for inkjet capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printhead Fabrication | Canon Inc.'s MEMS captive supply sustains margin control across high-volume contracts. |
| Proprietary UV Ink Chemistry Development | Fujifilm Business Innovation Corp. differentiates output durability for commercial packaging clients. |
| Managed Print Service Contract Expansion | Equipment financiers displace distributor channels across Midwest and Southeast US printing corridors. |
| EPA Energy Star Version 3.0 Certification | Sub-30-watt standby compliance determines US market access for production-class equipment. |
| India Corrugated Packaging Market Entry | FMCG growth and fragmented flexographic infrastructure create white space for on-demand digital production. |
Methodological Framework
The analysis maps inkjet printer, high-speed printer, laser printer, and digital label printer sub-sectors, each validated through plant engineers at commercial print shops, procurement leads at packaging converters, OEM technical R&D directors, and aftermarket service heads. Primary interview intelligence triangulates against customs/trade data, SEC 10-K filings, EPA Energy Star certification databases, and METI efficiency benchmark disclosures. Bottom-up equipment shipment tracking reconciles with top-down consumables revenue analysis.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology architecture, application substrate, end-user procurement sophistication, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth trajectory synthesis. Forecast inputs incorporate EU Ecodesign Directive compliance timelines and India PLI scheme incentive structures.
Material uncertainties — tariff exposure on Japanese MEMS components, photoinitiator price volatility, and EPA certification timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions about technology transition velocity and procurement consolidation patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Managed Print Services Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Large Character Printers Market
Printing Technology
Print on Demand Software Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Print Equipment Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Digital Printing Market
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Industrial Printer Market
Printing Technology
Retail Printers Market