
 Oceania Digital Textile Printer Market | 2026-2036
Oceania Digital Textile Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Oceania Digital Textile Printer Market Analytics
Direct-to-retail distribution channels across Oceania is reshaping how digital textile printers reach end users. Kornit Digital leverages its vertically integrated pigment ink systems to anchor supply relationships with Australasian fashion brands. HP Inc. competes through water-based inkjet platforms optimized for short-run garment production. Mimaki Engineering Co., Ltd. differentiates via dye-sublimation systems that dominate the Sydney and Melbourne home textiles segment.
Oceania digital textile printers employ piezoelectric inkjet heads depositing aqueous or sublimation inks onto natural and synthetic fabrics at resolutions up to 1200 dpi, enabling on-demand color customization without screen-making overhead. Direct-to-garment technology leads the product type landscape due to its penetration among Australian custom apparel studios. Water-based formulations are outpacing solvent alternatives as Australia's chemical safety regulator tightens volatile organic compound thresholds for textile operations.
Australia's Therapeutic Goods Administration and Chemicals Classification frameworks, alongside New Zealand's Environmental Protection Authority, jointly determine permissible ink chemistries and waste disposal protocols for textile printing facilities. Australia's Modern Manufacturing Initiative subsidizes digital adoption while EPA Victoria enforces local air-quality standards on production sites. Stakeholders must monitor evolving state-level chemical registers and align capital planning with anticipated compliance timelines rather than current thresholds alone.
Market Dynamics
Australia's Modern Manufacturing Initiative and New Zealand's Product Stewardship framework are compressing adoption timelines for compliant digital textile systems across the region's fashion and home textile clusters.
Growth Catalysts
- Environmental compliance mandates:Australia's Therapeutic Goods Administration and Chemicals Classification frameworks are phasing out solvent-based chemistries, forcing converters toward aqueous inkjet platforms that reduce volatile organic compound emissions.
- On-demand production economics:Direct-to-garment technology eliminates screen-making overhead and minimum order quantities, enabling Australasian apparel studios to profit from single-unit custom orders.
- Melbourne-Sydney corridor concentration:Manufacturing density across Australia's southeastern states creates localized demand pools that justify dedicated technical service infrastructure and faster equipment deployment cycles.
Market Restraints
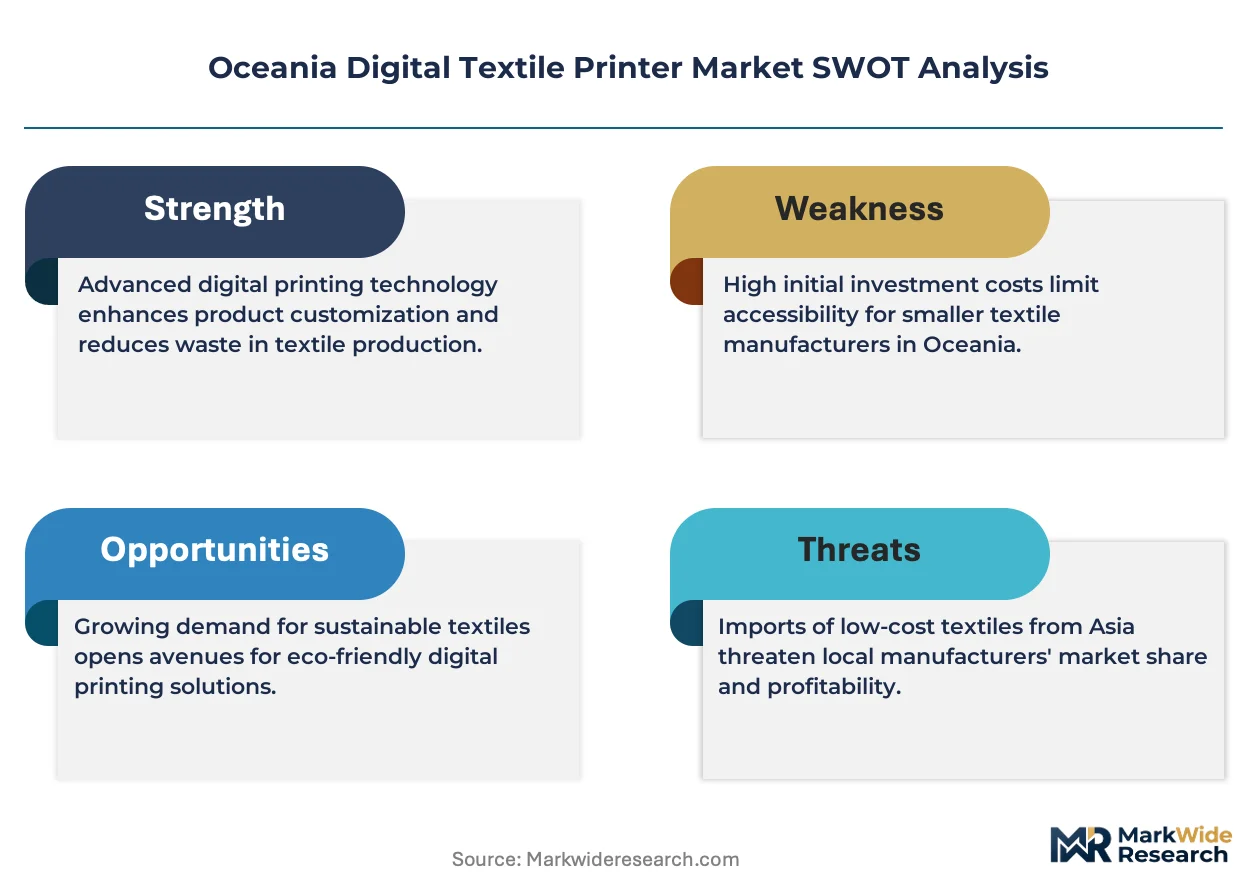
- Piezoelectric head supply concentration:Precision inkjet nozzle manufacturing concentrates among Japanese and European component suppliers, exposing Oceania printer assemblers to extended lead times and currency fluctuation risk.
- Pigment ink formulation costs:Water-based pigment systems require higher-grade dispersants and binders than dye-sublimation alternatives, compressing margins for entry-level equipment vendors.
- Waste disposal protocol fragmentation:EPA Victoria enforces stricter air-quality standards than other Australian states, forcing multi-site operators to maintain heterogeneous compliance procedures.
Strategic Opportunities
- New Zealand home textiles expansion:Auckland's interior design sector shows underpenetrated demand for dye-sublimation printed soft furnishings, with local production capacity lagging behind specification trends.
- Subscription-based equipment access:Leasing models bundled with ink supply and maintenance are displacing outright purchase among Australian custom apparel startups with constrained balance sheets.
- Cross-technology workflow integration:Convergence of direct-to-garment and dye-sublimation systems within single production facilities enables converters to capture both apparel and home textile contracts without redundant capital deployment.
Industry Challenges
- Color management expertise scarcity:ICC profile development and substrate-specific calibration require specialized knowledge that outpaces vocational training output from Australian technical institutes.
- Legacy screen-printing asset stranding:Established converters face write-down pressure on rotary screen equipment while financing digital transition, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oceania Digital Textile Printer Market |
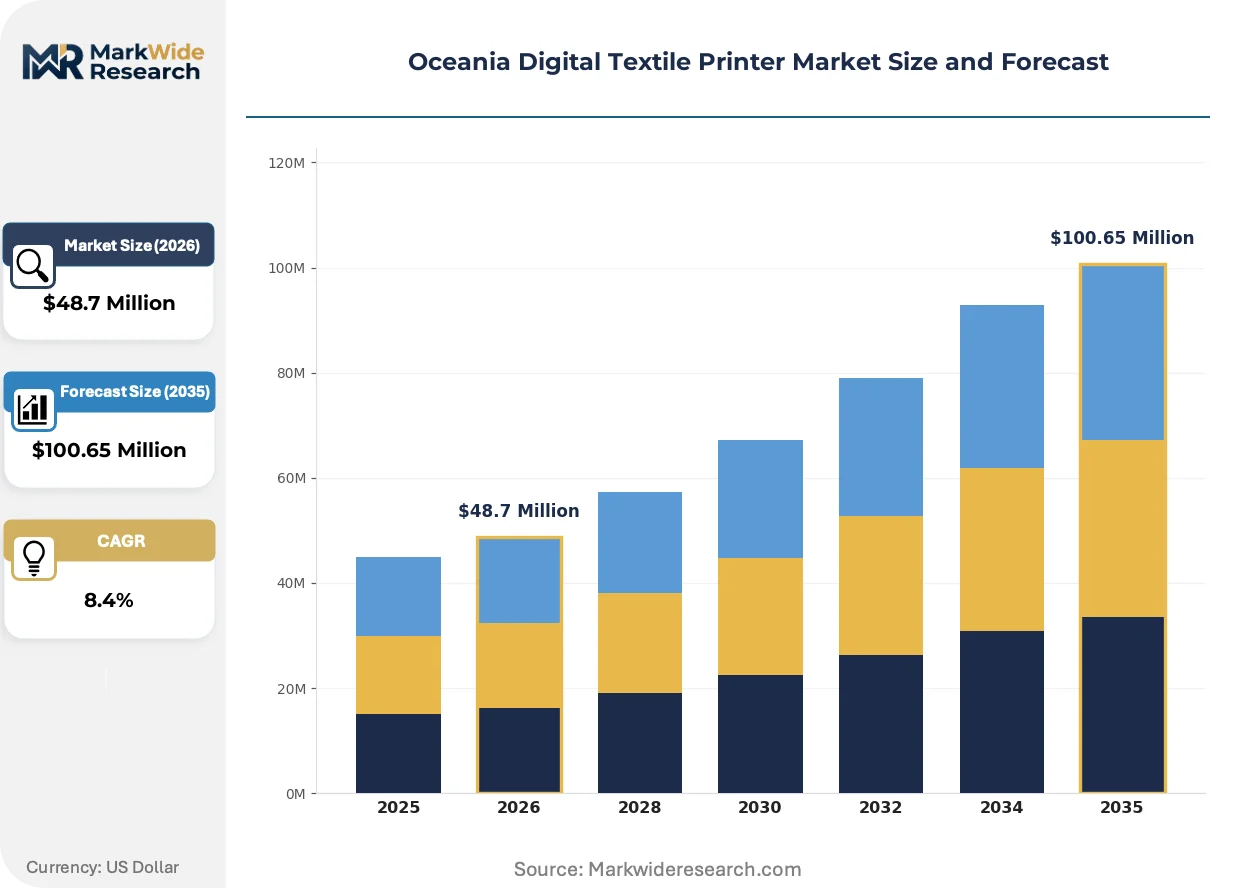
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-to-Garment, Dye Sublimation, Inkjet, Hybrid Technology: UV, Solvent, Eco-solvent, Water-based End User: Fashion, Home Textiles, Advertising, Industrial Application: Custom Printing, Prototype Development, Batch Production, Artistic Designs |
| Companies Covered | Konica Minolta, Inc., Kornit Digital, HP Inc., Durst Phototechnik AG, Ricoh Company, Ltd., Seiko Epson Corporation, Mimaki Engineering Co., Ltd., Electronics For Imaging, Inc., Brother International Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oceania Digital Textile Printer Market Evolving Landscape
Digital textile production in Oceania is pivoting from batch manufacturing to event-triggered fulfillment, with technology and regulatory vectors compressing traditional supply chain stages.
Piezoelectric inkjet deposition systems are digitizing color application workflows across natural and synthetic substrates. Australian custom apparel studios and New Zealand soft furnishings producers are adopting these platforms at accelerating rates to eliminate screen preparation delays. The technology is digitizing order-to-delivery cycles from weeks to hours, collapsing inventory carrying costs for seasonal fashion programs.
Australia's Modern Manufacturing Initiative and EPA Victoria's air-quality enforcement are tightening volatile organic compound thresholds for textile operations. These frameworks are disqualifying solvent-based chemistries from new facility approvals and retrofit incentives. Direct-to-garment and dye-sublimation segments are responding with accelerated water-based ink formulation development to maintain eligibility for state-level subsidies.
Short-run procurement patterns are fragmenting traditional distributor relationships across the region. Australasian fashion brands are contracting directly with equipment-ink integrated vendors, bypassing regional machinery dealers that historically controlled technical service access. This disintermediation is most visible in Sydney and Melbourne, where vertically integrated supply agreements now dominate new equipment placements.
Oceania Digital Textile Printer Market Segmentation
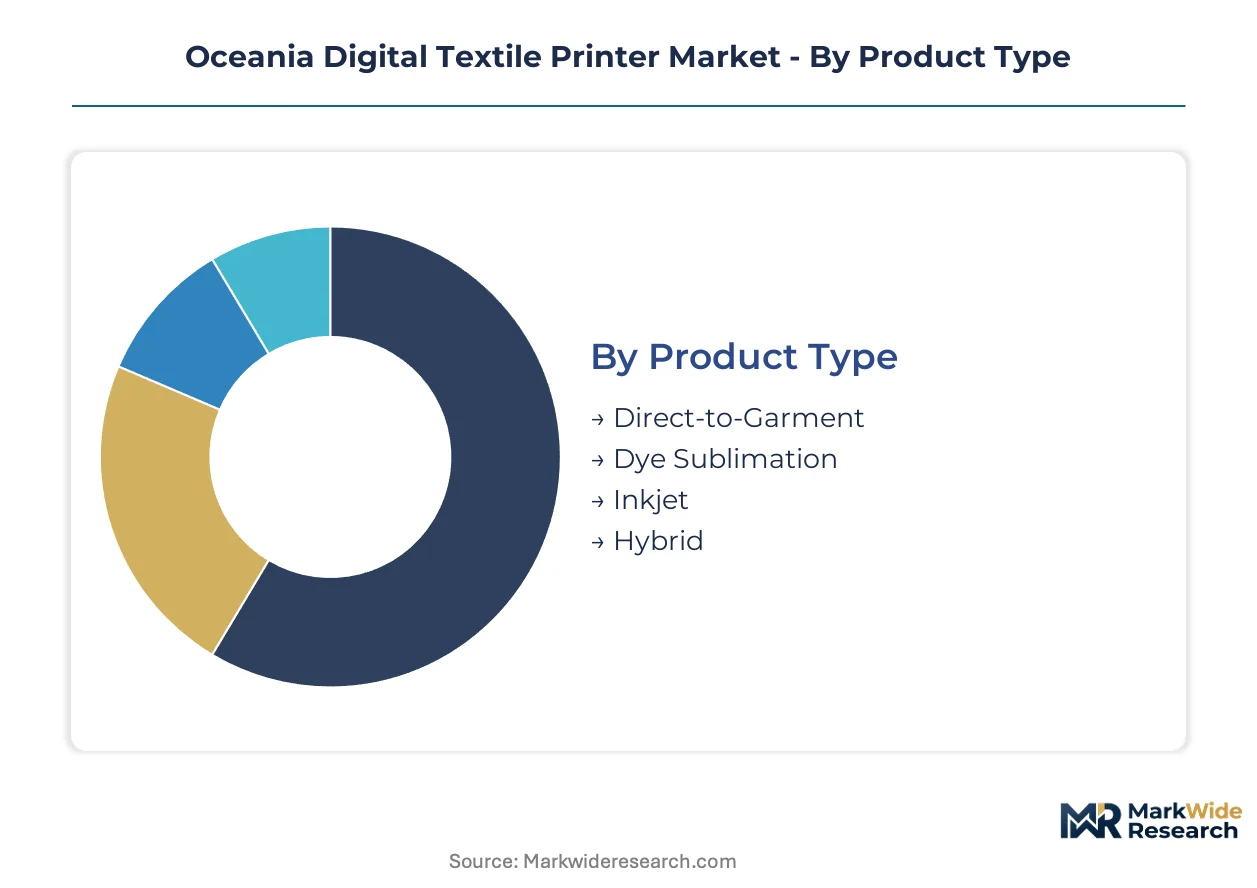
Segmentation reveals how digital textile printer configurations align with distinct operational intensities across Oceania's manufacturing clusters. Equipment selection in this market directly determines service contract structures, consumables replenishment cycles, and technical support staffing requirements.
Product Type:
After-sales-service intensity varies dramatically across product categories, with printhead replacement schedules and ink system maintenance demands creating divergent vendor support obligations.
- Direct-to-Garment:These systems deposit aqueous pigment inks directly onto cotton and cotton-blend apparel using modified inkjet architectures. Australian custom apparel studios in Melbourne and Sydney drive replacement demand as single-unit order economics displace screen-printing minimums. Piezoelectric head wear rates necessitate quarterly service interventions.
- Dye Sublimation:Heat-transfer chemistry enables permanent polyester coloration without hand-feel degradation. Auckland's home textiles sector and Sydney's soft furnishings producers favor these systems for interior décor applications where wash durability specifications exceed garment requirements. Service intensity concentrates on calender maintenance and sublimation paper handling mechanisms.
- Inkjet:Broad-format aqueous systems address signage and display graphics with lower substrate specificity than textile-dedicated platforms.
- Hybrid:Dual-mode architectures switch between direct-to-textile and transfer-based workflows, appealing to converters serving multiple end-use segments from single facilities.
By volume, Direct-to-Garment leads. By growth pace, Dye Sublimation is expanding most quickly.
Technology:
Capital deployment thresholds and operating cost structures segment the installed base across chemistry-dependent technology choices.
- Water-based:Aqueous pigment and dye formulations dominate new Australian facility approvals as EPA Victoria's volatile organic compound enforcement tightens. These systems align with Modern Manufacturing Initiative subsidy eligibility and reduce operator respiratory protection requirements.
- Eco-solvent:Mild-solvent formulations bridge outdoor durability needs with moderated emissions profiles, capturing vinyl banner and flag production where textile substrates require weather resistance.
- UV:Curable ink systems enable immediate finishing on rigid and flexible substrates, serving industrial marking applications with minimal drying infrastructure.
- Solvent:Full-strength solvent chemistries retreat to legacy outdoor graphics installations as environmental compliance costs escalate across Australian states.
Water-based systems command the largest installed base. UV platforms are gaining share fastest among industrial end users.
End User:
Customer-type differentiation shapes equipment specification priorities and financing arrangements across Oceania's textile production landscape.
- Fashion:Apparel houses and contract manufacturers prioritize color consistency across short runs and rapid style turnover. Melbourne's design-led studios and Sydney's fast-fashion suppliers drive specifications for automated pretreatment and inline finishing.
- Home Textiles:Upholstery, curtain, and bedding producers demand wider print widths and repeat-pattern accuracy. Auckland's interior design market shows particular appetite for custom soft furnishings with localized production.
- Advertising:Display graphics and promotional textile producers value substrate versatility and outdoor durability over hand-feel characteristics.
- Industrial:Technical textile marking, safety equipment labeling, and automotive interior applications specify abrasion resistance and chemical compliance certifications.
Fashion end users represent the deepest installed base. Home Textiles demonstrates the steepest expansion trajectory as interior specification trends favor customization.
Application:
Production-mode segmentation distinguishes equipment utilization patterns and revenue model structures across customer operations.
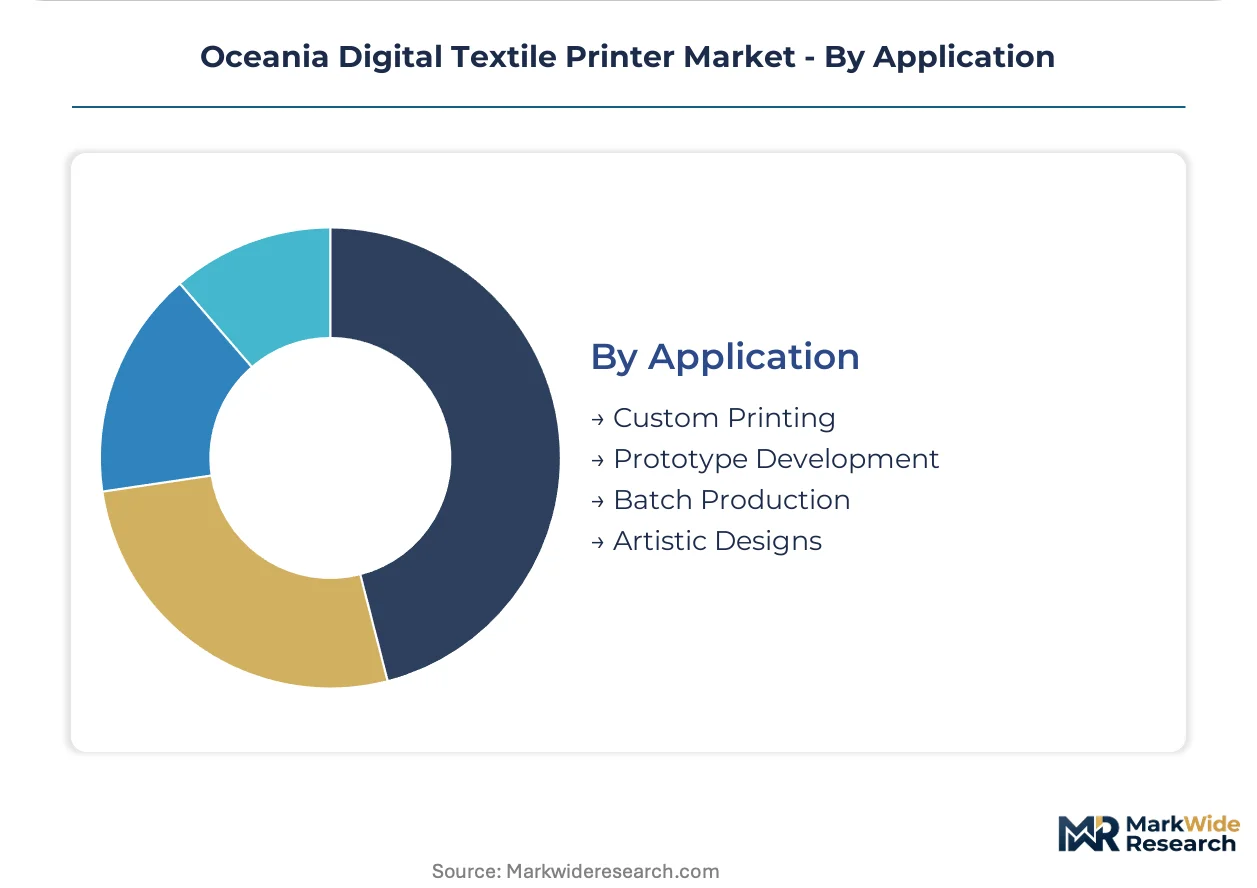
- Custom Printing:Single-unit and micro-batch production for personalized apparel and bespoke interior items. Australian online custom apparel platforms drive demand for gang-sheet optimization software and automated order-to-print workflows.
- Batch Production:Scheduled medium-run manufacturing for seasonal collections and retail replenishment programs.
- Prototype Development:Sampling and pre-production validation for design houses reducing time-to-market for new collections.
- Artistic Designs:Limited-edition prints and gallery-oriented textile art requiring archival pigment specifications and substrate experimentation capabilities.
Custom Printing dominates transaction volume. Prototype Development is climbing the fastest as fashion cycle compression accelerates sampling frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands pricing power over New Zealand through manufacturing scale advantages, while smaller Pacific markets absorb premium equipment costs without reciprocal volume leverage. This asymmetry shapes vendor deployment priorities and service contract structures across the region.
Australia
Melbourne and Sydney anchor demand through fashion house clusters and custom apparel studios. TGA chemical classification frameworks and EPA Victoria air-quality enforcement accelerate aqueous inkjet adoption. The southeastern manufacturing corridor concentrates equipment placements, with technical service infrastructure scaling to match localized demand density.
New Zealand
Auckland's interior design sector drives dye-sublimation uptake for soft furnishings with localized production lagging specification trends. The Product Stewardship framework tightens waste disposal protocols for textile printing facilities. Canterbury and Wellington host smaller converter operations facing higher per-unit equipment costs due to import distance.
Fiji
Tourism-linked promotional textile demand supports limited direct-to-garment installations for resort merchandise and event apparel. The country's environmental regulator applies developing-world chemical thresholds without the enforcement density of Australian counterparts. Suva's small converter base relies on Australian technical service reach for maintenance support.
Papua New Guinea
Mining sector uniform and safety textile printing creates niche industrial demand outside fashion-driven adoption patterns. National environmental regulations remain permissive on solvent chemistries, though Australian-owned facilities often self-impose stricter standards. Port Moresby's limited manufacturing base imports finished printed textiles rather than deploying local digital capacity.
Oceania Digital Textile Printer Market Competitive Landscape
Vertically integrated ink-system vendors and modular equipment specialists split the market through divergent capital-deployment models. The installed base concentrates among three strategic tiers: pigment-ink integrators commanding fashion brand relationships, dye-sublimation platform providers capturing home textile workflows, and aqueous-inkjet generalists serving display graphics crossover demand. Competitive moves center on subscription-based equipment access bundling consumables with maintenance, and cross-technology workflow convergence enabling single-facility apparel and home textile production.
Among the vertically integrated tier, Kornit Digital exemplifies pigment-ink system control anchoring direct brand relationships. HP Inc. occupies a position as aqueous inkjet platform provider with short-run optimization. Mimaki Engineering Co., Ltd. represents dye-sublimation specialization for soft furnishings and technical textile applications. These three archetypes illustrate how chemistry-platform control, print architecture flexibility, and substrate-specific optimization respectively define competitive positioning.
| Leading Market Players |
|---|
| Konica Minolta, Inc. |
| Kornit Digital |
| HP Inc. |
| Durst Phototechnik AG |
| Ricoh Company, Ltd. |
| Seiko Epson Corporation |
| Mimaki Engineering Co., Ltd. |
| Electronics For Imaging, Inc. |
| Brother International Corporation |
| Others |
Value Network & Pricing Analysis
Japanese piezoelectric printhead manufacturers concentrate precision nozzle fabrication, anchoring margin capture upstream while Australian and New Zealand converters absorb currency-adjusted equipment premiums. This concentration pattern distributes pricing power unevenly across the value chain, with ink chemistry vendors capturing recurring revenue pools that offset hardware margin compression.
Pricing Analysis
The customization-premium spread between configured-to-order direct-to-garment systems and standard dye-sublimation platforms runs wide across Oceania. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and printhead replacement schedules. Cost compression in entry-level equipment tiers is intensifying because Australian startups favor subscription-based access over capital deployment. Custom apparel studios show highest price sensitivity, while fashion houses prioritize color consistency over unit economics.
Supply Chain Analysis
Contract manufacturing for digital textile printers concentrates among Japanese and Taiwanese electronics assemblers with specialized cleanroom capabilities for piezoelectric head integration. Component sourcing draws from Japan for precision nozzles, Taiwan for control electronics, and Germany for linear motion systems. Single-source vulnerability around thermal management subassemblies creates exposure to logistics chokepoints through Singapore transshipment hubs. Distribution runs through vertically integrated vendors bypassing traditional machinery dealers in Sydney and Melbourne.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Australia's Modern Manufacturing Initiative and EPA Victoria's enforcement timeline create switching costs that lock compliant vendors into multi-year subsidy eligibility cycles.
For Market Incumbents: Harden service infrastructure density across the Melbourne-Sydney corridor to capture replacement demand from quarterly printhead maintenance schedules. Deepen backward integration into water-based pigment formulation to offset margin pressure from higher-grade dispersant costs. Consolidate technical training partnerships with Australian vocational institutes to address color management expertise scarcity.
For New Entrants and Emerging Players: Establish a beachhead in Auckland's underpenetrated home textiles segment where dye-sublimation capacity lags interior design specification trends. Target subscription-based equipment access models for Australian custom apparel startups with constrained balance sheets. Lead with bundled ink supply and maintenance contracts to bypass entrenched dealer relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated ink-system vendors with captive fashion brand relationships and recurring consumables revenue. Long-term viability hinges on chemistry-platform control rather than hardware differentiation alone. Watch EPA Victoria's air-quality threshold enforcement cadence as the inflection signal for compliance-driven replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Equipment Access | Leasing models bundled with ink supply displace outright purchase among Australian apparel startups. |
| Backward Integration into Pigment Chemistry | In-house formulation control secures margin pools and ensures EPA Victoria compliance eligibility. |
| Cross-Technology Workflow Convergence | Dual-mode direct-to-garment and dye-sublimation systems capture apparel and home textile contracts. |
| Technical Service Infrastructure Scaling | Localized Melbourne-Sydney support density reduces customer downtime and locks in replacement revenue. |
| Vocational Training Partnerships | Color management expertise pipelines address ICC profile development scarcity across Australian institutes. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with digital textile printer OEM product managers, Australian fashion house production directors, New Zealand interior design procurement leads, EPA Victoria compliance officers, and ink chemistry R&D heads informed operational assumptions. Secondary validation drew from TGA chemical classification registers, EPA Victoria air-quality enforcement notices, Modern Manufacturing Initiative subsidy disclosures, and Australian customs import data. Bottom-up equipment placement counts were triangulated against top-down market value estimates.
Calibration against historical installation cycles and subsidy uptake rates shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, ink chemistry technology, end-user industry, and application mode. CAGRs were derived from fitted growth curves applied to equipment replacement cycles and new facility approval pipelines. Forecast inputs incorporated TGA chemical phase-out timelines and EPA Victoria threshold enforcement probability.
Stress conditions across currency fluctuation bands, printhead supply disruption scenarios, and state-level regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts incorporate documented assumptions about subsidy continuity and chemical classification stability. Quarterly review of TGA register updates and EPA Victoria enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Print Equipment Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Printing Machinery Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Digital Production Printer Market
Printing Technology
Print on Demand Market
Printing Technology
Digital Presses Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Digital Paper System Market
Printing Technology
Retail Printers Market
Printing Technology
Global Microprinting Market
Printing Technology
Global Digital Printing Services Market