
 Commercial Printer Market | 2026-2036
Commercial Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Printer Market Outlook
A shift from single-source supply contracts toward multi-vendor equipment portfolios is recalibrating procurement strategies across enterprise print fleets. HP Inc. leverages its PageWide technology leadership to anchor high-speed production inkjet contracts with major publishers. Canon Inc. competes through integrated workflow software that binds hardware to managed print services. Ricoh Company Ltd. differentiates by embedding sustainability metrics into fleet management dashboards, appealing to corporate ESG mandates.
Commercial printers are electro-mechanical devices that deposit ink, toner, or thermal-sensitive pigments onto substrates at resolutions typically ranging from 300 to 2400 dots per inch, serving functions from transactional document production to high-fidelity marketing collateral. Inkjet systems lead technology investments due to their compatibility with diverse substrates and declining per-page costs in production environments. Digital printing segments are expanding fastest in labels and packaging applications, where versioned short runs displace traditional offset plates. Laser platforms sustain dominance in corporate office settings where monochrome speed and duplex reliability remain paramount.
FDA regulations on food-contact packaging materials, EPA emissions standards for print facilities, and EU REACH chemical restrictions collectively shape equipment specifications and consumable formulations across major markets. The EU F-Gas Regulation and evolving ENERGY STAR requirements in the United States are forcing manufacturers to redesign thermal management systems and reduce standby power draw. Stakeholders must monitor how substrate sustainability certifications and chemical disclosure rules reshape total cost of ownership calculations before committing to multi-year fleet investments.
Market Dynamics
Brand owners in Germany and the United States now mandate shorter print runs with variable data capabilities, forcing packaging companies to retire legacy offset fleets and renegotiate multi-year equipment contracts. This demand compression is converging with REACH compliance deadlines and EPA volatile organic compound guidelines to accelerate capital redeployment toward water-based ink systems and low-energy curing technologies.
Growth Catalysts
- EPA emissions guidelines:Print facilities across the United States face escalating compliance costs for solvent-based operations, redirecting capex toward aqueous inkjet architectures and UV-LED curing modules that eliminate thermal oxidizer requirements.
- Corrugated packaging demand in China:Domestic manufacturers capture share in industrial inkjet systems as e-commerce fulfillment networks require versioned box designs with regional language variants and promotional coding.
- Variable data integration:Pharmaceutical serialization mandates and food traceability requirements in the European Union drive replacement cycles for analog presses unable to embed unique identifiers at production speeds.
Market Restraints
- Printhead supply concentration:Precision MEMS fabrication for industrial inkjet arrays concentrates among a limited supplier base in Japan and the Netherlands, exposing OEMs to allocation risk during semiconductor foundry constraints.
- Substrate cost volatility:Coated paper and folding carton board prices fluctuate with pulp futures and energy-intensive drying operations, compressing job-shop margins on fixed-price catalog contracts.
- Offset residual value collapse:Secondary market liquidity for eight-color sheetfed presses has evaporated as trade buyers in Eastern Europe and Southeast Asia suspend import demand.
Strategic Opportunities
- India packaging conversion:Domestic label and flexible packaging converters remain underpenetrated by production inkjet, with import substitution policies and PLI scheme incentives favoring local assembly partnerships.
- Textile pigment inkjet:Direct-to-garment and home furnishing applications are converging with reactive dye substitution, enabling water-based pigment formulations to penetrate cotton and polyester blend markets previously reserved for screen printing.
- EU F-Gas Regulation phase-down:Thermal management redesign requirements for laser printer fusing units create white space for solid-ink and heat-free inkjet alternatives in corporate fleet refresh cycles.
Industry Challenges
- Color science expertise scarcity:ICC profile optimization for expanded gamut ink sets and spot color matching requires specialists whose training pipelines lag hardware deployment timelines.
- Legacy workflow integration:Prepress automation layers from the 2000s resist API connectivity with cloud-native MIS platforms, forcing hybrid architectures that delay real-time job costing visibility.
- Consumables authentication:Third-party ink and toner cartridge remanufacturing triggers firmware lockout disputes and warranty voidance claims that strain dealer relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Printer Market |
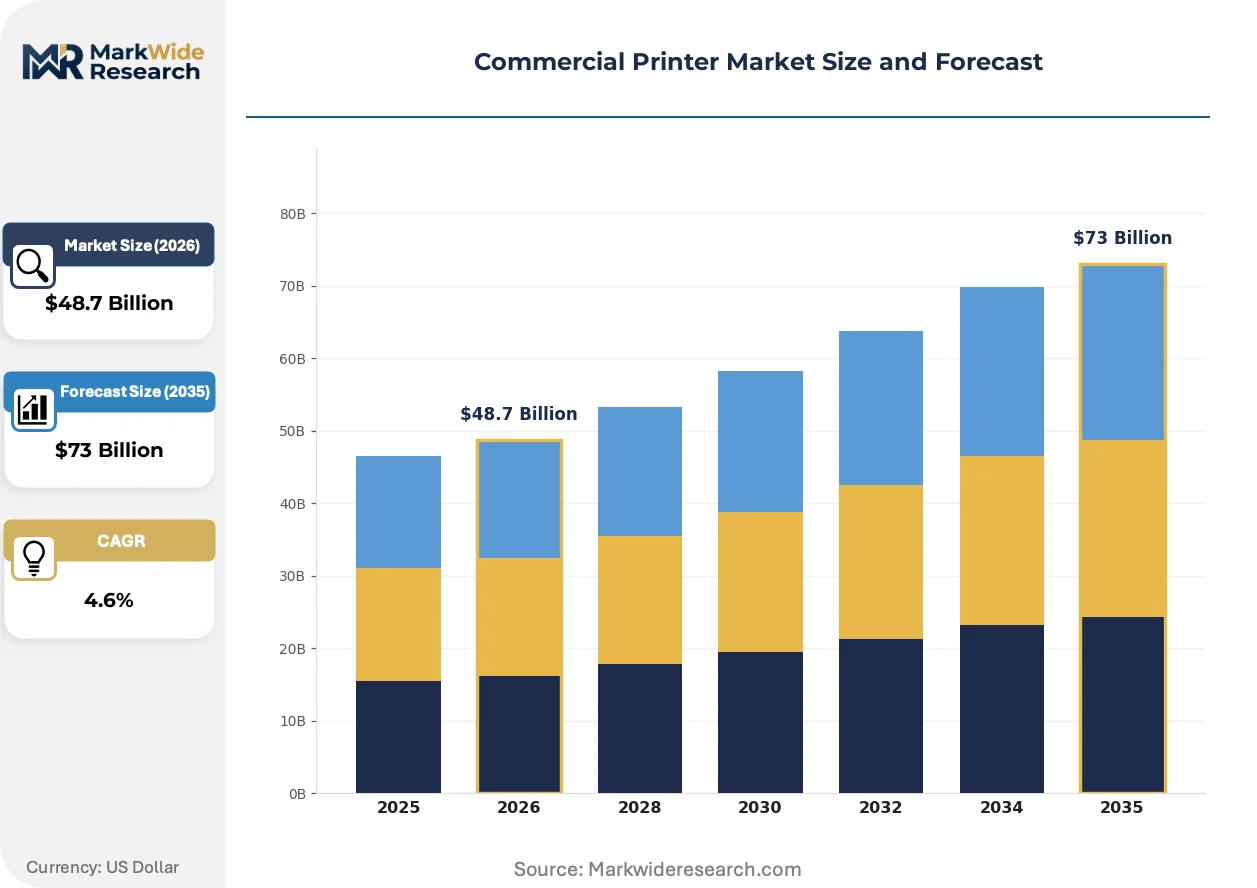
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Printer Type: Inkjet, Laser, Dot Matrix, Thermal End User: Advertising Agencies, Publishers, Corporate Offices, Packaging Companies Technology: Digital Printing, Offset Printing, Screen Printing, Flexographic Printing Application: Billing, Marketing Collateral, Labels, Packaging |
| Companies Covered | Seiko Epson Corporation, Konica Minolta Inc., HP Inc., Kyocera Corporation, Brother Industries Ltd., Canon Inc., Ricoh Company Ltd., Ninestar Corporation, Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Printer Market Strategic Shifts
Production inkjet architectures are converging with single-pass array designs that eliminate scanning carriage mechanics, compressing cost-per-page economics and substrate versatility gaps versus electrophotography. Equipment manufacturers now compete through embedded analytics and predictive service models rather than rated speed specifications alone.
Single-pass inkjet deposition is converging with ceramic and metallic particle ink formulations to enable direct printing on glass, rigid plastics, and heat-sensitive films without intermediate transfer steps. Automotive interior component suppliers and appliance manufacturers in Germany and Japan are piloting these systems for decorative trim and branded control panels. This convergence is compressing the traditional value chain separating printing from thermoforming or injection molding operations.
REACH chemical restrictions and evolving EPA guidelines on volatile organic compound emissions are forcing reformulation of UV-curable oligomers and photoinitiators toward bio-based acrylates with reduced sensitization profiles. Ink manufacturers in the Netherlands and the United States have accelerated registration dossiers for nitrogen-vacancy cleared photoinitiator alternatives. Food-contact packaging segments in the European Union and North America are responding by qualifying water-based flexo and inkjet systems for direct substrate contact applications previously reserved for laminated structures.
Versioned short-run procurement is fragmenting historical volume commitments toward transactional spot-buying platforms where brand owners upload artwork files and receive automated quotes across geographically distributed print service providers. Magazine publishers and specialty retailers in the United Kingdom and Australia have adopted these marketplaces for catalog and direct mail campaigns. This behavioral shift is most visible in metropolitan corridors where same-day or next-day fulfillment expectations compress the traditional sales-to-ship interval from weeks to hours.
Commercial Printer Market Segmentation
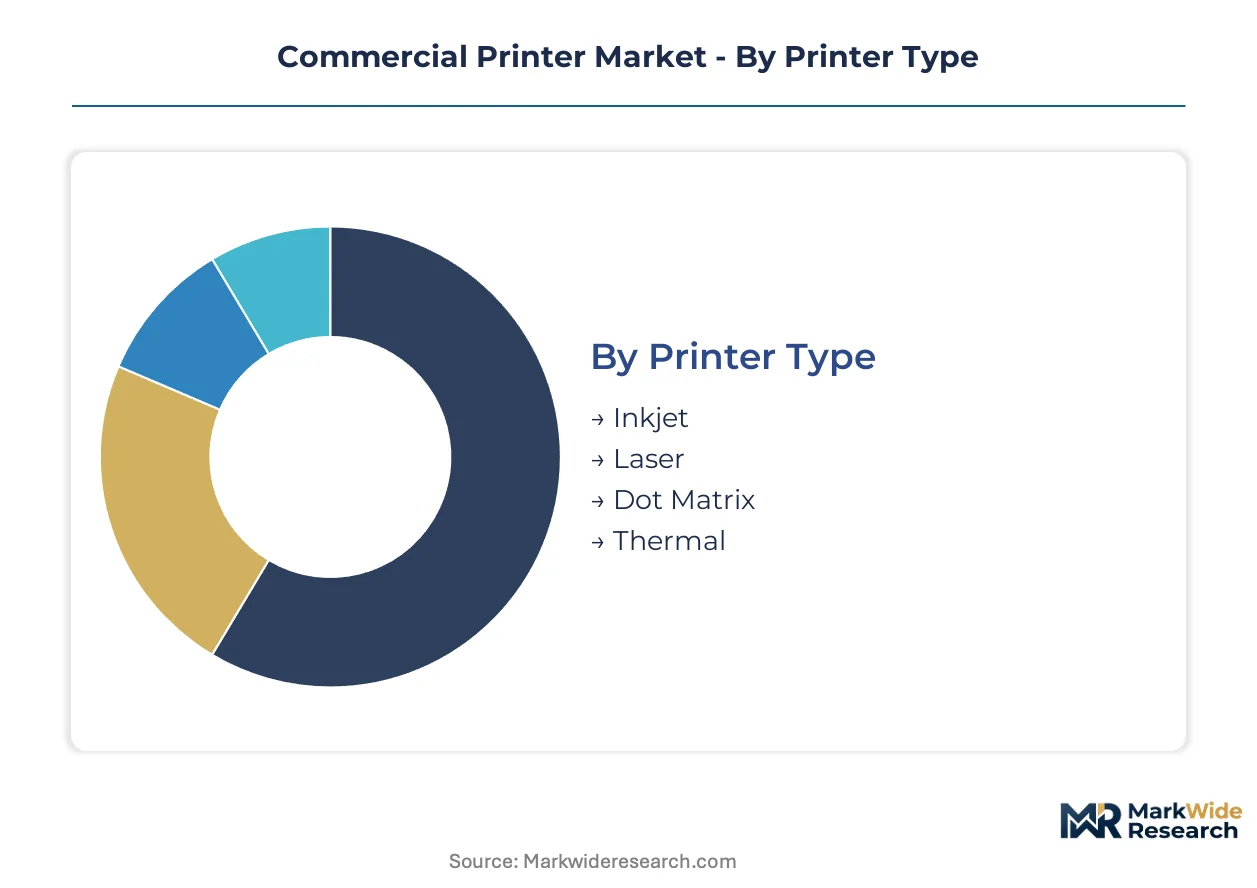
Equipment procurement patterns diverge sharply across printer types and end-use verticals, with packaging converters and corporate fleet managers applying incompatible performance criteria. Understanding these segment boundaries clarifies why inkjet architectures penetrate corrugated production while laser platforms retain office dominance.
Printer Type:
Precision printhead fabrication concentrates among MEMS foundries in Japan and the Netherlands, creating supply bottlenecks that favor OEMs with captive component sourcing.
- Inkjet:Piezoelectric and thermal printhead technologies deposit aqueous, solvent, or UV-curable inks onto porous and non-porous substrates at resolutions reaching 2400 dpi. Packaging companies in Germany and the United States deploy single-pass production inkjet for corrugated versioned runs with variable data. REACH compliance deadlines and EPA volatile organic compound guidelines accelerate water-based formulations and low-energy curing modules.
- Laser:Electrophotographic imaging transfers toner particles via organic photoconductor drums and fusing units operating at 180-220°C. Corporate offices across China sustain demand for monochrome duplex systems where speed and reliability outweigh substrate flexibility. EU F-Gas Regulation phase-down requirements force thermal management redesigns that compress margins on legacy fusing architectures.
- Dot Matrix:Impact printing through wire-pin matrices persists in multi-part form and logistics label applications requiring carbon-copy impressions. Banking and freight operations in India retain installed bases for passbook and bill-of-lading printing where digital alternatives remain cost-prohibitive.
- Thermal:Direct thermal and thermal transfer technologies activate heat-sensitive coatings or wax-resin ribbons for receipt, wristband, and shipping label production. Point-of-sale and healthcare identification systems in Japan leverage compact thermal modules for on-demand output without consumable complexity.
Today's leader: Laser. Tomorrow's challenger: Inkjet.
End User:
Procurement authority fragmentation separates enterprise fleet managers from production print buyers, each applying distinct total-cost-of-ownership models.
- Advertising Agencies:Creative production workflows demand expanded gamut ink sets and spot color matching for high-fidelity marketing collateral. ICC profile optimization requirements strain color science expertise availability in metropolitan design clusters.
- Publishers:Transactional document and book production operations prioritize throughput economics over substrate versatility. Magazine publishers in the United Kingdom adopt versioned short-run marketplaces that compress sales-to-ship intervals from weeks to hours.
- Corporate Offices:Managed print service contracts bundle hardware, consumables, and predictive maintenance into per-page pricing. ESG mandates drive interest in Ricoh's sustainability-embedded fleet dashboards and HP's PageWide heat-free architectures.
- Packaging Companies:Corrugated converters and label manufacturers face brand-owner mandates for shorter runs with regional language variants and promotional coding. Domestic Chinese manufacturers capture share in industrial inkjet systems as e-commerce fulfillment networks expand.
Packaging companies are expanding most quickly; corporate offices offer the deepest installed base refresh potential.
Technology:
Capital redeployment timelines separate digital architectures with sub-24-hour makeready from analog systems requiring plate chemistry and mounting labor.
- Digital Printing:Inkjet and electrophotographic systems eliminate intermediate steps, enabling economically viable runs below 500 impressions. Pharmaceutical serialization mandates in the European Union and food traceability requirements accelerate replacement of analog presses unable to embed unique identifiers at production speeds.
- Offset Printing:Lithographic plate imaging and blanket cylinder transfer deliver superior color consistency and substrate latitude for long-run catalogs and annual reports. Secondary market liquidity for eight-color sheetfed presses has collapsed as trade buyers in Eastern Europe suspend import demand.
- Screen Printing:Mesh stencil and squeegee deposition applies thick ink films to textiles, glass, and rigid plastics. Direct-to-garment inkjet is displacing screen operations in cotton and polyester blend markets through water-based pigment formulations.
- Flexographic Printing:Rotary relief plate systems dominate high-volume flexible packaging and corrugated pre-print with solvent-based or water-based inks. EPA emissions guidelines redirect capital toward aqueous flexo and UV-LED curing configurations.
Digital printing climbs the fastest; offset retains residual dominance in publication-grade long runs.
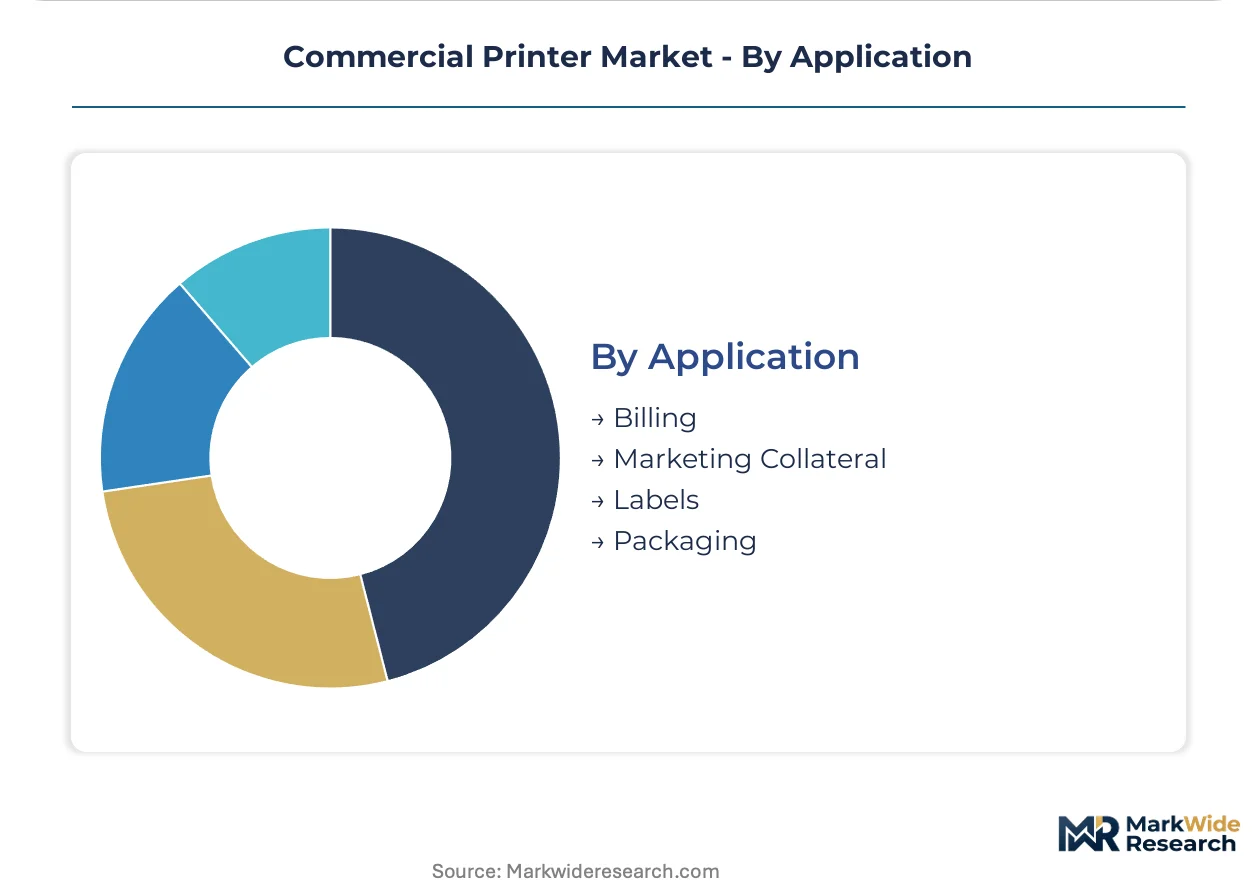
Application:
Versioning intensity and regulatory marking requirements determine whether static or variable-data-capable architectures achieve equipment selection.
- Billing:Transactional document production demands MICR encoding and postal optimization for financial statements and utility invoices. Laser platforms sustain dominance where monochrome speed and duplex reliability remain paramount.
- Marketing Collateral:Brochure, catalog, and direct mail production requires color consistency across distributed print service providers. Specialty retailers in Australia adopt automated quotation platforms for same-day fulfillment expectations.
- Labels:Pressure-sensitive and shrink-sleeve applications integrate serialization, security, and promotional variable data. Domestic Indian converters remain underpenetrated by production inkjet despite PLI scheme incentives favoring local assembly partnerships.
- Packaging:Folding carton, corrugated, and flexible structures face FDA food-contact material regulations and substrate sustainability certifications. Water-based flexo and inkjet systems qualify for direct substrate contact applications previously reserved for laminated structures.
Labels show the steepest expansion trajectory; billing provides the most predictable replacement cycle visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping equipment procurement patterns as compliance cost differentials between jurisdictions accelerate production migration toward jurisdictions with streamlined chemical approval pathways and consolidated environmental permitting.
United States
Packaging converters in Wisconsin and Ohio are retiring solvent-based flexo fleets as EPA volatile organic compound guidelines escalate thermal oxidizer compliance costs. The agency's evolving emissions standards redirect capital toward aqueous inkjet architectures and UV-LED curing modules. Domestic manufacturers in the Great Lakes industrial corridor capture replacement demand from brand owners mandating shorter print runs with variable data capabilities.
Germany
Automotive interior suppliers in Stuttgart and Munich pilot single-pass inkjet systems for decorative trim and branded control panels on glass and rigid plastics. REACH compliance deadlines force reformulation of UV-curable oligomers and photoinitiators toward bio-based acrylates with reduced sensitization profiles. The Baden-Württemberg manufacturing cluster leads qualification of water-based systems for food-contact packaging applications previously reserved for laminated structures.
China
E-commerce fulfillment networks in Shanghai and Shenzhen drive versioned corrugated box demand with regional language variants and promotional coding. Domestic manufacturers capture share in industrial inkjet systems as MIIT standards align equipment specifications with dual carbon goals for energy-intensive production. The Yangtze River Delta concentration of packaging converters accelerates import substitution in production inkjet hardware.
Japan
Precision MEMS fabrication for industrial inkjet arrays concentrates in Nagoya and Kyoto foundries, exposing OEMs to allocation risk during semiconductor supply constraints. METI efficiency standards force thermal management redesigns for laser printer fusing units. The Chubu industrial corridor sustains captive printhead supply relationships that insulate integrated manufacturers from external component volatility.
India
Domestic label and flexible packaging converters in Maharashtra and Gujarat remain underpenetrated by production inkjet despite PLI scheme incentives favoring local assembly partnerships. BIS certification requirements for imported equipment create procedural friction for foreign OEMs. The Mumbai-Pune manufacturing belt attracts joint venture proposals from inkjet system providers seeking tariff-advantaged production platforms.
Commercial Printer Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue heat-free architectures and substrate-agnostic deposition systems. The vendor base stratifies across integrated conglomerates with captive component sourcing, specialized inkjet array fabricators, and regional assemblers serving price-sensitive fleet replacement cycles. Three archetypes dominate: diversified electronics conglomerates leveraging semiconductor adjacencies, precision mechanics specialists controlling printhead supply, and workflow software integrators binding hardware to managed service contracts. Competitive intensity concentrates on M&A activity targeting color science talent pools and strategic partnerships securing MEMS foundry allocation.
Among diversified technology conglomerates, HP Inc., Canon Inc., and Ricoh Company Ltd. exemplify contrasting strategic positions. HP Inc. anchors high-speed production inkjet contracts through PageWide technology leadership. Canon Inc. competes through integrated workflow software that binds hardware to managed print services. Ricoh Company Ltd. differentiates by embedding sustainability metrics into fleet management dashboards, appealing to corporate ESG mandates.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| Konica Minolta Inc. |
| HP Inc. |
| Kyocera Corporation |
| Brother Industries Ltd. |
| Canon Inc. |
| Ricoh Company Ltd. |
| Ninestar Corporation |
| Xerox Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up print service providers in the United States and Germany are consolidating fragmented regional operations, concentrating procurement volumes to extract multi-year equipment discounts from OEMs while locking in consumable supply agreements that buffer against resin and pigment cost volatility. This ownership pattern tightens pricing discipline across enterprise fleet contracts and production print agreements, compressing margins for independent job shops unable to match scale-based rebates.
Pricing Analysis
Distributor margins on production inkjet systems typically range from twelve to eighteen percent, with direct-to-OEM discounts available only to buyers committing to fleet-wide standardization. Three-tier pricing structure across premium, standard, and economy levels separates high-speed single-pass arrays from refurbished electrophotographic units and entry-level aqueous inkjet modules. Cost compression in the standard tier is intensifying because MEMS printhead allocation constraints force OEMs to prioritize premium contract attach rates. Corporate fleet managers exhibit the highest price sensitivity, while packaging converters prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Precision MEMS fabrication for industrial inkjet arrays rests on Japanese and Dutch specialty foundries, with secondary dependencies on German precision optics and South Korean semiconductor packaging. Raw material inputs include silicon wafers, piezoelectric ceramics, UV-curable oligomers, and aqueous pigment dispersions. Single-source vulnerability concentrates in MEMS printhead supply, where foundry allocation decisions during semiconductor constraints cascade into OEM delivery delays. Distribution runs through authorized dealer networks for enterprise fleets and direct OEM relationships for production print installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial printer market functions as a regulatory compounder, with EPA volatile organic compound guidelines and EU REACH compliance deadlines forcing capital redeployment cycles that refresh installed bases regardless of mechanical service life.
For Market Incumbents: Acquire color science talent pools to secure ICC profile optimization capabilities for expanded gamut ink sets. Secure captive MEMS foundry allocation through equity partnerships with Japanese or Dutch precision fabricators, insulating against printhead supply constraints that threaten delivery commitments to packaging converters. For New Entrants and Emerging Players: EPA emissions guidelines in the United States open a window for aqueous inkjet system providers to displace solvent-based flexo operations in Wisconsin and Ohio packaging corridors. Target underpenetrated domestic Indian label converters through local assembly partnerships that satisfy PLI scheme incentives and BIS certification requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap workflow software integrators lacking captive hardware supply. Long-term viability hinges on recurring revenue attachment rates for predictive maintenance and cloud-native MIS platforms. Watch for inflection when brand-owner versioned-short-run procurement crosses fifty percent of corrugated packaging volume.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Captive printhead supply insulates HP and Canon from allocation risk during semiconductor constraints. |
| Water-Based Ink Formulation | REACH-compliant bio-acrylate registrations enable direct food-contact packaging applications in Germany. |
| Predictive Service Platform | Embedded analytics bind corporate fleet customers to Ricoh and Xerox through per-page pricing contracts. |
| Local Assembly Joint Venture | PLI-advantaged production in Maharashtra and Gujarat circumvents BIS friction for foreign OEMs. |
| Single-Pass Array Deployment | Elimination of scanning mechanics compresses cost-per-page economics versus electrophotography in corrugated. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market combining structured interviews with plant managers at packaging converters, procurement leads at corporate fleet operators, aftermarket service heads at dealer networks, and technical R&D directors at ink manufacturers. Secondary validation draws from EPA emissions filings, ECHA REACH registration dossiers, MIIT equipment standard disclosures, SEC 10-K equipment revenue breakdowns, and customs trade data on printhead component flows. Bottom-up equipment shipment tallies triangulate against top-down consumable volume estimates.
Granularity-level modeling disaggregates revenue and unit forecasts across printer type, end-user vertical, technology architecture, and application segment, with additional dimensioning by regional regulatory cluster and substrate compatibility tier. CAGRs derive from fitted growth curves applied to equipment replacement cycles and consumable attach rate assumptions. Key inputs include pharmaceutical serialization mandate deadlines, e-commerce corrugated demand trajectories, and MEMS foundry capacity expansion announcements.
Revisions become necessary when semiconductor foundry allocation constraints intensify, REACH chemical restrictions expand beyond current photoinitiator categories, or brand-owner versioned-run procurement accelerates faster than analog press retirement timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Global Web to Print Software Market
Printing Technology
Professional Printers Market
Printing Technology
Digital Printing Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Variable Data Printing Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Print on Demand Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Card Printers Market
Printing Technology
ID Card Printers Market
Printing Technology
Large Character Printers Market