
 Output Management Software Market | 2026-2036
Output Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Output Management Software Market Intelligence
Enterprise print infrastructure is fragmenting across hybrid cloud and edge deployments as organizations decouple document generation from monolithic on-premise systems. HP Inc. dominates hardware-integrated output management through its embedded software stack across printer fleets. Oracle Corporation leverages its database and application ecosystem to anchor enterprise document workflows within broader cloud suites. Lexmark International specializes in secure print management for regulated industries, competing on compliance-ready feature sets rather than breadth of platform services.
Output management software encompasses the systems that control, format, deliver, and archive business documents across digital and physical channels, typically integrating with ERP, CRM, and core banking platforms through APIs and print description languages such as AFP, PostScript, and PDF. Its primary purpose is ensuring reliable, auditable, and cost-efficient document output at enterprise scale while supporting channel diversity from email and portals to printers and mobile devices. The cloud-based delivery model captures the fastest expansion as organizations retire legacy print servers, though on-premise deployments sustain significant revenue in financial services and government sectors where data sovereignty requirements limit off-premises processing. Workflow automation represents a concentrated margin pool because these implementations embed deeply into operational processes, creating switching costs that subscription pricing models capture over multi-year engagements.
FDA 21 CFR Part 11 requirements shape output management demand in life sciences by mandating electronic signatures and audit trails on all system-generated records, pushing vendors to embed compliant logging and validation documentation. The EU AI Act and GDPR collectively constrain automated document classification and cross-border data flows, forcing European deployments toward region-specific cloud instances with granular retention controls. Stakeholders must monitor how emerging sustainability disclosure rules under CSRD expand the scope of mandatory reporting outputs, reshaping both document templates and archival retention policies.
Market Dynamics
Cloud migration is fragmenting enterprise print infrastructure as organizations decouple document generation from monolithic on-premise systems, forcing vendors to rearchitect around hybrid and edge deployments.
Growth Catalysts
- Healthcare digitization:Hospital systems deploy automated document workflows to manage patient records and billing outputs, reducing manual processing errors.
- GDPR data residency mandates:European enterprises invest in region-specific cloud instances with granular retention controls to satisfy cross-border transfer restrictions.
- API-first integration:Banking and insurance platforms embed output management through RESTful interfaces, replacing legacy print description languages.
Market Restraints
- Input cost volatility:Specialized printer hardware and secure consumables face supply concentration from East Asian component manufacturers.
- Technical debt burden:AFP and PostScript legacy formats persist in financial services, blocking seamless cloud transitions.
- Regulatory friction:FDA 21 CFR Part 11 validation requirements extend procurement cycles for life sciences deployments by 12-18 months.
Strategic Opportunities
- Underpenetrated mid-market:Regional healthcare networks in Germany and France lack dedicated output infrastructure, creating whitespace for managed service models.
- CSRD sustainability reporting:Mandatory disclosure rules expand document template complexity, driving demand for automated generation and archival systems.
- Edge-AI convergence:On-device document classification combines with local processing to enable real-time redaction without cloud transmission.
Industry Challenges
- Skill scarcity in legacy formats:Expertise in AFP and IPDS programming languages ages out of the workforce faster than training programs replace it.
- Integration complexity:SAP and Oracle ERP environments require bespoke connector development, inflating implementation timelines and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Output Management Software Market |
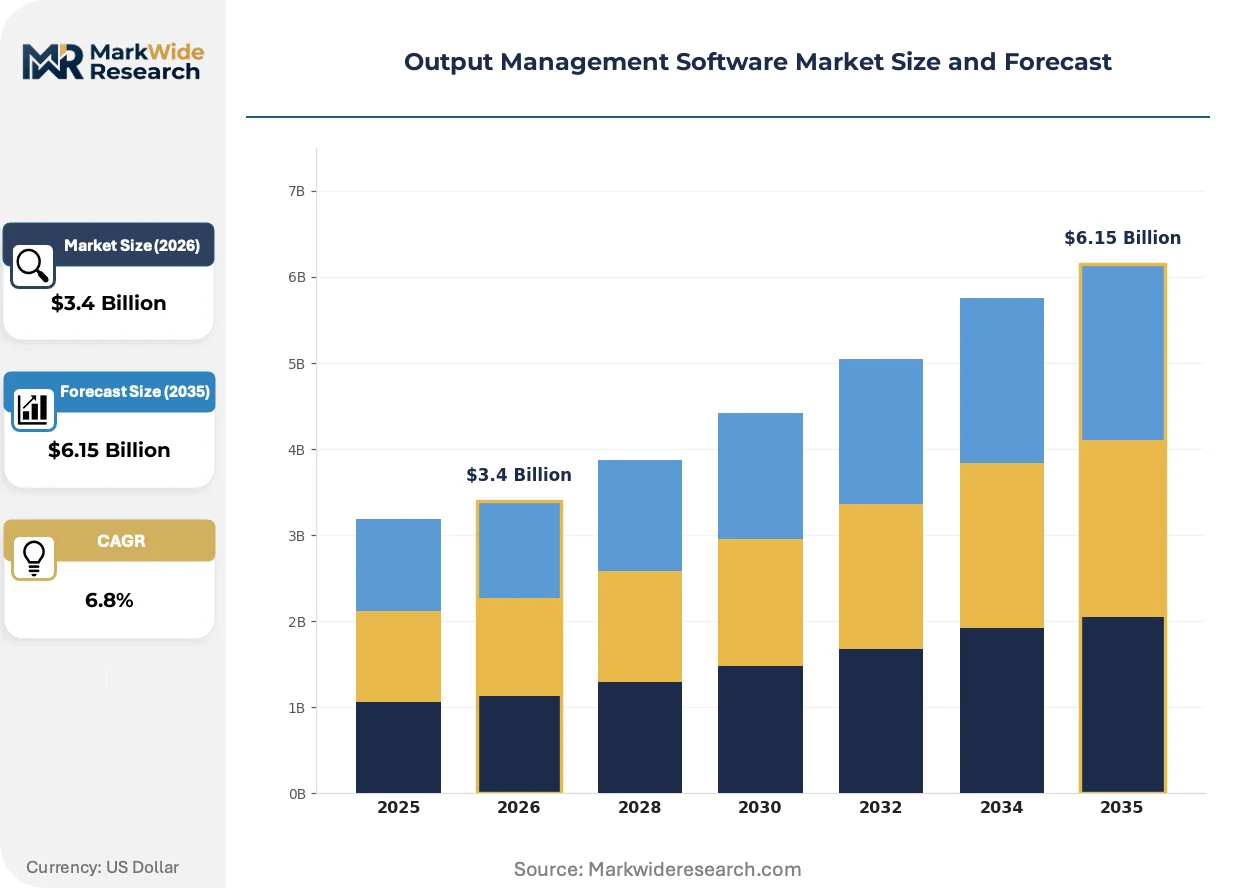
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Generation, Print Management, Archiving, Workflow Automation Delivery Model: On-Premise, Cloud-Based, Hybrid, Subscription Customer Type: Enterprises, Small Businesses, Government Agencies, Educational Institutions End User: Healthcare, Retail, Finance, Telecommunications |
| Companies Covered | Ricoh Company, Microsoft Corporation, OpenText Corporation, Lexmark International, HP Inc., Kofax Inc., IBM Corporation, Oracle Corporation, Xerox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Output Management Software Market Strategic Shifts & Innovations
Document infrastructure is converging with compliance automation and sustainability mandates, reshaping how enterprises architect output systems.
Containerized microservices architectures are digitizing document generation by breaking monolithic print servers into API-driven components. Large enterprises in the United States federal sector pilot these deployments to enable elastic scaling during tax season peaks. This modular approach is digitizing procurement patterns as buyers evaluate vendors on integration flexibility rather than bundled hardware.
CSRD disclosure requirements are forcing template redesign across European manufacturing and energy sectors. The mandate expands audit trail granularity for sustainability reports, pushing output vendors to embed carbon footprint tracking into document metadata. German industrial conglomerates now require suppliers to demonstrate CSRD-ready archival retention policies.
Subscription pricing models are compressing traditional perpetual license cycles in North American financial services. Buyers unbundle implementation from ongoing support, demanding consumption-based billing tied to document volumes. This shift is most visible among mid-tier insurers replacing five-year hardware refresh contracts with monthly SaaS arrangements.
Output Management Software Market Segmentation
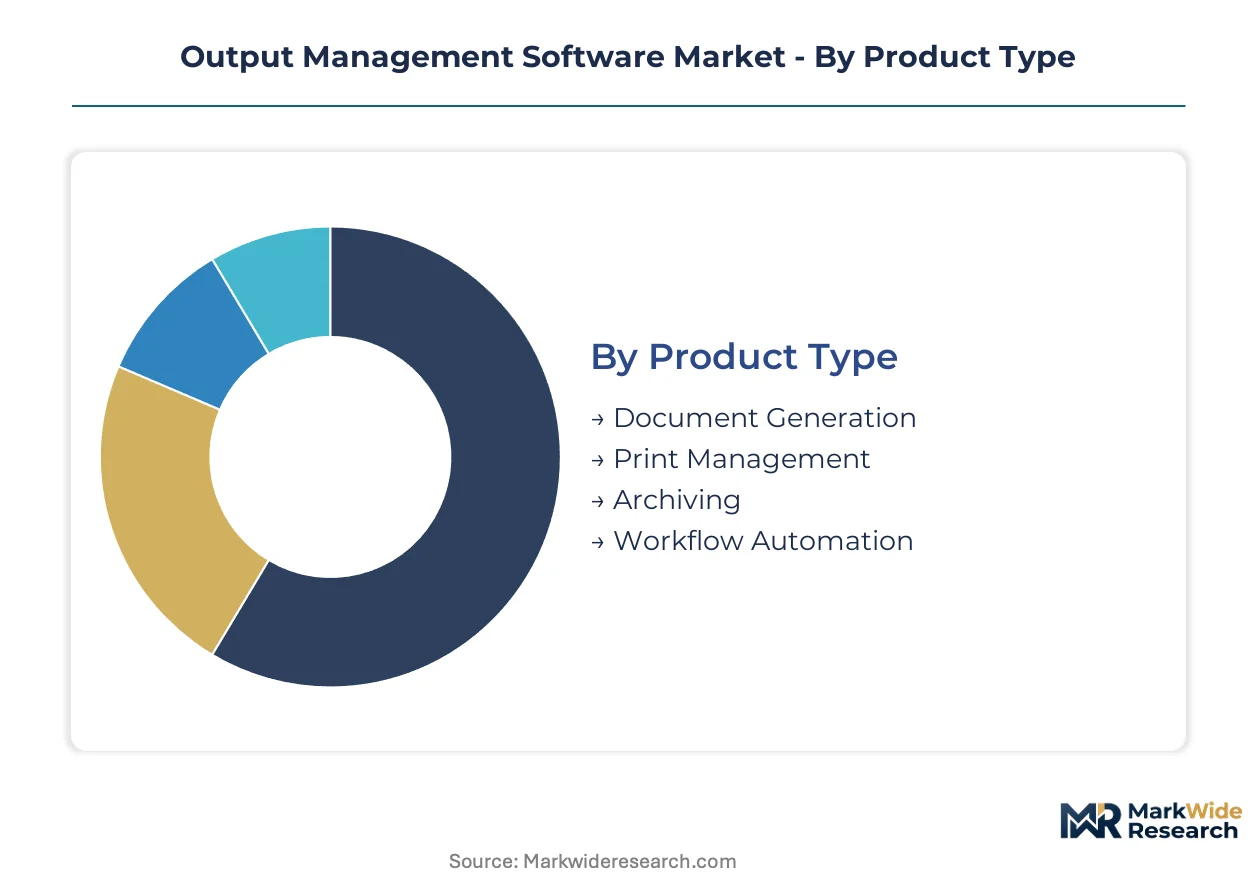
Output management software segments by technical function, deployment architecture, and customer scale. Each dimension shapes procurement cycles and margin structures differently.
Product Type:
Workflow Automation turns over fastest as organizations pilot and expand process digitization. Archiving moves slowest due to decades-long retention mandates and migration inertia.
- Workflow Automation:Orchestrates document routing, approval chains, and exception handling across ERP systems. Hospital systems in the United States deploy these tools to streamline patient discharge paperwork and reduce administrative bottlenecks.
- Print Management:Governs device fleets, secure release printing, and cost allocation across distributed locations. Retail chains with thousands of storefronts prioritize centralized print governance to control consumable spend and reduce helpdesk tickets.
- Document Generation:Renders high-volume transactional outputs from templates and data feeds. Banks embed this capability within core banking platforms to produce statements and regulatory notices.
- Archiving:Provides long-term storage, retrieval, and legal hold capabilities with audit trails. Financial services firms in Germany maintain these systems to satisfy GDPR retention requirements and tax authority documentation demands.
Print Management dominates installed base. Workflow Automation is where expansion concentrates.
Delivery Model:
Cost tiers stratify sharply: perpetual on-premise licenses carry heavy upfront capital requirements while subscription models spread expenditure across operating budgets.
- Cloud-Based:Delivers document infrastructure through multi-tenant SaaS with elastic scaling. French healthcare networks adopt these deployments to avoid data center capital expenditure while maintaining CNIL-compliant data residency.
- Subscription:Bundles software, maintenance, and managed services into recurring payments. Mid-market insurers in North America favor this structure to align costs with document volumes and eliminate hardware refresh cycles.
- Hybrid:Combines on-premise document generation with cloud archival and analytics. German manufacturers deploy this architecture to keep sensitive production data local while leveraging cloud-based sustainability reporting tools.
- On-Premise:Runs entirely within customer data centers with direct hardware integration. Federal agencies in the United States mandate these deployments for classified document processing under FISMA requirements.
On-Premise retains the largest revenue base. Cloud-Based climbs the fastest as legacy print servers retire.
Customer Type:
Volume concentration varies by procurement sophistication: enterprises negotiate enterprise-wide agreements while government agencies fragment purchasing across departments.
- Enterprises:Deploy integrated platforms spanning multiple business units and geographies. Large banks in the United States consolidate vendor relationships to reduce integration complexity and capture volume discounts.
- Government Agencies:Require FedRAMP, FISMA, or equivalent certifications with extended validation cycles. Federal procurement offices prioritize vendors with existing blanket purchase agreements to compress sourcing timelines.
- Small Businesses:Adopt lightweight, browser-based tools without dedicated IT staff. Regional medical practices select managed print services to outsource device maintenance and supplies management.
- Educational Institutions:Balance tight budgets against high-volume student-facing document needs. University systems deploy secure print release to reduce unclaimed output and recover costs through student fees.
Enterprises command the deepest vendor relationships. Government Agencies present the longest sales cycles.
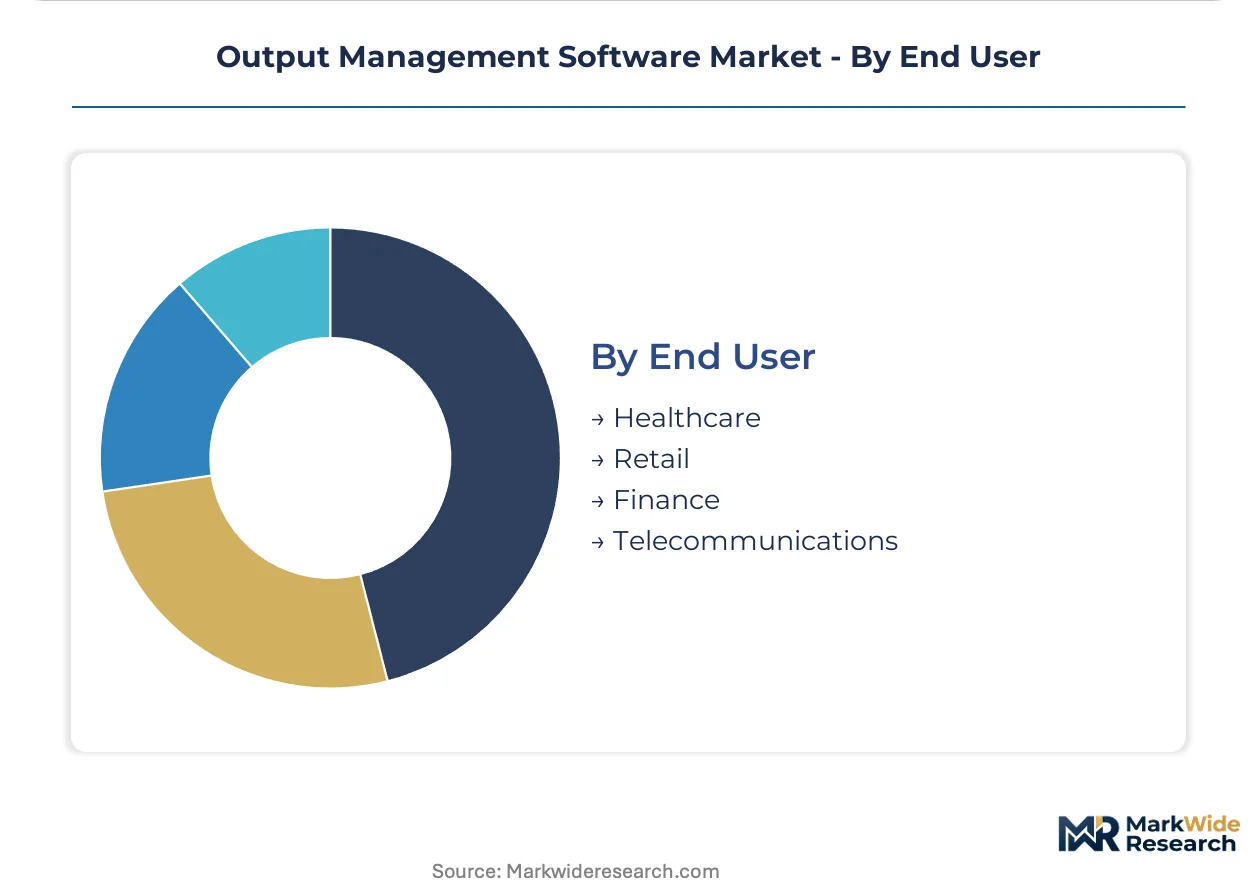
End User:
Application intensity differs by regulatory exposure: finance and healthcare face mandatory audit trails while retail prioritizes cost efficiency.
- Healthcare:Manages patient records, billing outputs, and clinical documentation with HIPAA compliance. Hospital systems automate prior authorization letters and explanation-of-benefits documents to reduce denial rates.
- Finance:Generates statements, trade confirmations, and regulatory filings with immutable audit trails. Investment banks in the United States embed output management within SEC reporting workflows to ensure timestamp accuracy.
- Telecommunications:Produces high-volume billing and contract documentation across multilingual markets. Mobile operators in France localize invoice templates to satisfy consumer protection requirements.
- Retail:Handles promotional materials, inventory labels, and customer communications across distributed locations. Grocery chains optimize label printing for perishable goods to reduce waste and improve stock rotation.
Finance leads in compliance-driven spending. Healthcare shows the steepest expansion trajectory as digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large enterprises and federal agencies in the United States drive the deepest investment in secure output platforms, while European healthcare networks and German industrial conglomerates reshape procurement around data residency mandates and sustainability disclosure rules.
United States
Hospital systems automate patient discharge workflows and prior authorization letters to reduce administrative bottlenecks and denial rates. HIPAA compliance requirements shape vendor selection criteria for cloud archival deployments. Federal agencies in Washington D.C. and defense contractors in Northern Virginia mandate FISMA-compliant on-premise installations for classified document processing.
Germany
Industrial conglomerates in the Ruhr and Bavaria demand CSRD-ready archival retention policies with embedded carbon footprint tracking in document metadata. GDPR data residency mandates push manufacturing firms toward region-specific cloud instances with granular retention controls. Frankfurt's financial services cluster maintains legacy AFP systems for tax authority documentation while piloting hybrid architectures.
France
Healthcare networks adopt cloud-based delivery to avoid data center capital expenditure while satisfying CNIL-compliant data residency requirements. The EU AI Act constrains automated document classification, forcing Paris-based insurers toward edge-AI deployments with local redaction capabilities. Mobile operators localize invoice templates to satisfy consumer protection requirements.
United Kingdom
Investment banks in London embed output management within SEC reporting workflows to ensure timestamp accuracy on trade confirmations. The Financial Conduct Authority's operational resilience requirements extend procurement validation cycles for core banking integrations. Edinburgh's insurance sector consolidates vendor relationships to reduce integration complexity across multi-line operations.
Japan
Manufacturers in the Kanto region deploy hybrid architectures to keep sensitive production data local while leveraging cloud-based sustainability reporting tools. METI's digital transformation incentives accelerate retirement of legacy print servers in favor of API-driven microservices. Osaka's banking sector pilots containerized document generation for elastic scaling during fiscal year-end peaks.
Output Management Software Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where hardware-integrated vendors anchor the installed base and pure-software specialists capture cloud migration spend. The market stratifies between scale-driven platform consolidators, compliance-focused niche vendors, and enterprise software incumbents bundling output capabilities into broader suites. Dominant competitive moves include strategic partnerships with ERP providers and geographic expansion through managed service models.
Within the hardware-integrated tier, HP Inc. and Lexmark International exemplify channel-controlling archetypes that embed software stacks across printer fleets. Oracle Corporation occupies a position among enterprise software incumbents leveraging database and application ecosystems to anchor document workflows within cloud suites. These three companies represent distinct strategic postures: hardware dominance, compliance specialization, and platform bundling.
| Leading Market Players |
|---|
| Ricoh Company |
| Microsoft Corporation |
| OpenText Corporation |
| Lexmark International |
| HP Inc. |
| Kofax Inc. |
| IBM Corporation |
| Oracle Corporation |
| Xerox Corporation |
| Others |
Cost & Logistics Intelligence
East Asian component concentration for secure printer hardware and specialized consumables anchors margin capture in the hardware-integrated tier, while downstream buyers in North American financial services and European healthcare networks extract value through subscription pricing models that eliminate capital refresh cycles.
Pricing Analysis
Cost-plus contracts with hardware vendors index to semiconductor and memory component spot markets, creating margin volatility for printer fleet operators. Three-tier pricing structure across premium compliance-ready, standard enterprise, and economy mid-market levels differentiates by certification depth and integration complexity. Pricing pressure stems from cloud-native entrants unbundling document generation from legacy print infrastructure. Mid-market insurers exhibit highest price sensitivity, while federal agencies prioritize FISMA certification over cost minimization.
Supply Chain Analysis
Supplier-financing facilities from East Asian contract manufacturers extend 90-120 day payment terms to downstream hardware-integrated vendors, compressing working capital cycles. Component sourcing concentrates in Taiwan, South Korea, and Japan for print controller chipsets, secure toner formulations, and precision imaging drums. Single-source vulnerability persists for FDA-validated archival media substrates. Distribution runs through authorized reseller networks and direct enterprise sales forces, with managed service providers capturing growing share in European healthcare and German industrial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment architectures and compliance requirements creates specialist opportunities as healthcare digitization and CSRD disclosure mandates splinter demand into segment-specific niches.
For Market Incumbents: Entrench platform positions through backward integration into containerized microservices architectures that decouple document generation from legacy print servers. Deepen FedRAMP and FISMA certification moats to defend against cloud-native challengers targeting federal procurement. Prioritize API-first connector development for SAP and Oracle ERP environments where integration complexity blocks competitor entry. For New Entrants and Emerging Players: Establish a beachhead in mid-market healthcare networks across Germany and France, where managed service models address whitespace in dedicated output infrastructure. Target CNIL-compliant cloud archival deployments with consumption-based billing that eliminates data center capital expenditure. Lead with edge-AI document classification capabilities that satisfy EU AI Act constraints on cross-border data flows. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-specialist vendors with embedded FDA 21 CFR Part 11 validation documentation and existing life sciences customer bases. Long-term viability hinges on regulatory certification durability rather than feature velocity. Monitor CSRD implementation timelines across European manufacturing as inflection indicator for sustainability-reporting automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first ERP connectors reduce implementation failure rates in Oracle and SAP environments. |
| Strategic Partnership | FedRAMP authorization accelerates federal procurement cycles for classified document processing. |
| Acquisition of Specialist Firm | CSRD-ready archival capabilities capture German industrial sustainability disclosure mandates. |
| Geographic Expansion | CNIL-compliant cloud instances unlock French healthcare network procurement. |
| Product Launch | Edge-AI redaction tools satisfy EU AI Act constraints without cloud transmission. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with output management software vendors, healthcare IT procurement officers, federal agency contracting specialists, and ERP integration consultants; and secondary validation against SEC filings, FedRAMP authorization databases, hospital procurement records, and GPO contract repositories. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Forecast inputs encompassed deployment model migration rates, regulatory validation cycle durations, and vertical-specific digitization trajectories across the projection horizon. Segmentation dimensions modeled included product type, delivery architecture, customer scale, and end-use vertical with regional adoption pattern overlays. CAGRs derived from slope-intercept analysis of historical substitution curves and forward-looking procurement intention surveys.
Stress conditions across cloud migration velocity, GDPR enforcement intensity, and legacy format skill scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and enterprise IT budget allocation. Macroeconomic contraction, accelerated data sovereignty fragmentation, or breakthrough generative document automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Animation Design Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Resonator Design Software Market
Software & Services
Global Document Control Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Online Donation Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Projector Software Market
Software & Services
Stock Control Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Global PEO Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Data Conversion Services Market
Software & Services
B2B Price Optimization and Management Software Market