
 Recycled Construction Aggregates Market | 2026-2036
Recycled Construction Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Construction Aggregates Market Intelligence
The gap between premium-certified recycled aggregates and untreated commodity fill is expanding. CRH Plc. leverages its vertically integrated quarry networks to secure consistent feedstock quality across multiple processing sites. LafargeHolcim Ltd. anchors its competitive stance through proprietary crushing and screening protocols that meet structural concrete specifications. HeidelbergCement AG competes on geographic density, operating recycling clusters near major European demolition corridors to minimize haul costs.
Recycled construction aggregates consist of processed inert waste materials—primarily crushed concrete, brick, glass, and reclaimed asphalt—graded to specific particle size distributions for engineered fill and base course applications. These materials substitute virgin rock in load-bearing layers, reducing extraction pressure and landfill burden while meeting compressive strength and permeability thresholds. Crushed concrete commands the largest volume share as demolition feedstock availability rises and processing technology improves gradation control. Crushed brick occupies a narrower niche in non-structural fill and landscaping where color consistency and lower density prove advantageous. Glass aggregate represents the fastest-growing product type, driven by municipal bottle recycling mandates and its utility in decorative and drainage applications where chemical inertness matters.
EPA landfill diversion targets in the United States, the EU Green Deal circular economy action plan, and China's MEE construction waste management rules collectively reshape compliance thresholds for aggregate sourcing. REACH and RoHS frameworks in Europe further restrict hazardous substance migration from contaminated demolition debris into recycled streams. Stakeholders must monitor regulatory divergence between jurisdictions as certification requirements for structural-grade recycled aggregates tighten unevenly, creating trade friction and sourcing arbitrage opportunities.
Market Dynamics
Landfill diversion mandates across major economies are compressing virgin aggregate supply while demolition waste volumes surge, forcing processors to scale purification capacity faster than feedstock sorting infrastructure can match.
Growth Catalysts
- EU Green Deal circular economy action plan:Binding construction waste recycling targets in member states are mandating minimum recycled content thresholds for public infrastructure tenders, redirecting procurement flows toward certified processors.
- Glass aggregate drainage applications:Municipal bottle recycling mandates in North American and European cities are generating chemically inert feedstock for high-value decorative and filtration end-uses where color consistency commands price premiums.
- India's western processing corridors:Dedicated demolition contractor networks feeding centralized crushing facilities in Maharashtra and Gujarat are achieving economies of scale unmatched by fragmented eastern state operations.
Market Restraints
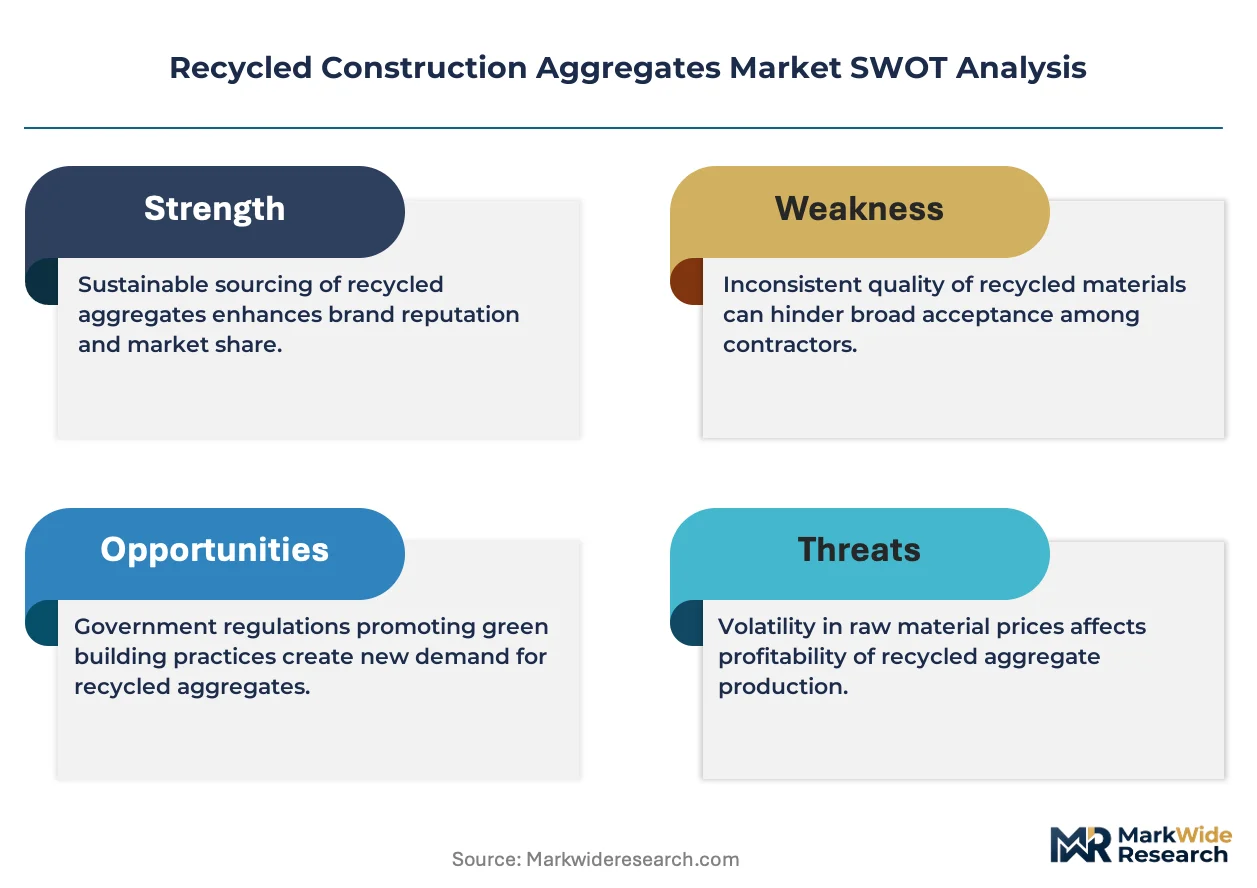
- Contaminated feedstock variability:Heterogeneous demolition debris containing plaster, wood, and hazardous coatings requires capital-intensive sensor-based sorting that smaller processors cannot finance.
- REACH hazardous substance migration rules:European regulators are tightening leachate testing protocols for structural-grade certification, extending compliance timelines and freezing spot-market liquidity for uncertified stockpiles.
- Natural aggregate price volatility:Diesel and explosives costs for virgin quarrying fluctuate with energy markets, creating intermittent price compression that erodes recycled product margin advantages.
Strategic Opportunities
- China's MEE construction waste management rules:Megacity mandates for 70% recycling rates by 2025 are creating procurement vacuums that foreign equipment suppliers and process licensors can fill through joint ventures.
- Reclaimed asphalt pavement (RAP) warm-mix integration:Binder rejuvenation chemistry advances are enabling higher RAP percentages in surface course specifications previously reserved for virgin bitumen.
- Direct-to-contractor digital platforms:Bypassing traditional aggregate trader intermediaries through mobile-graded inventory matching is compressing fulfillment cycles for mid-sized demolition contractors.
Industry Challenges
- Gradation control technician shortage:Skilled operators capable of calibrating multi-stage crushing circuits to tight particle distribution curves command wage premiums that erode processor margins.
- Multi-jurisdictional certification stacking:Road builders requiring both state DOT approval and federal highway administration validation face 18-24 month qualification timelines that freeze working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Construction Aggregates Market |
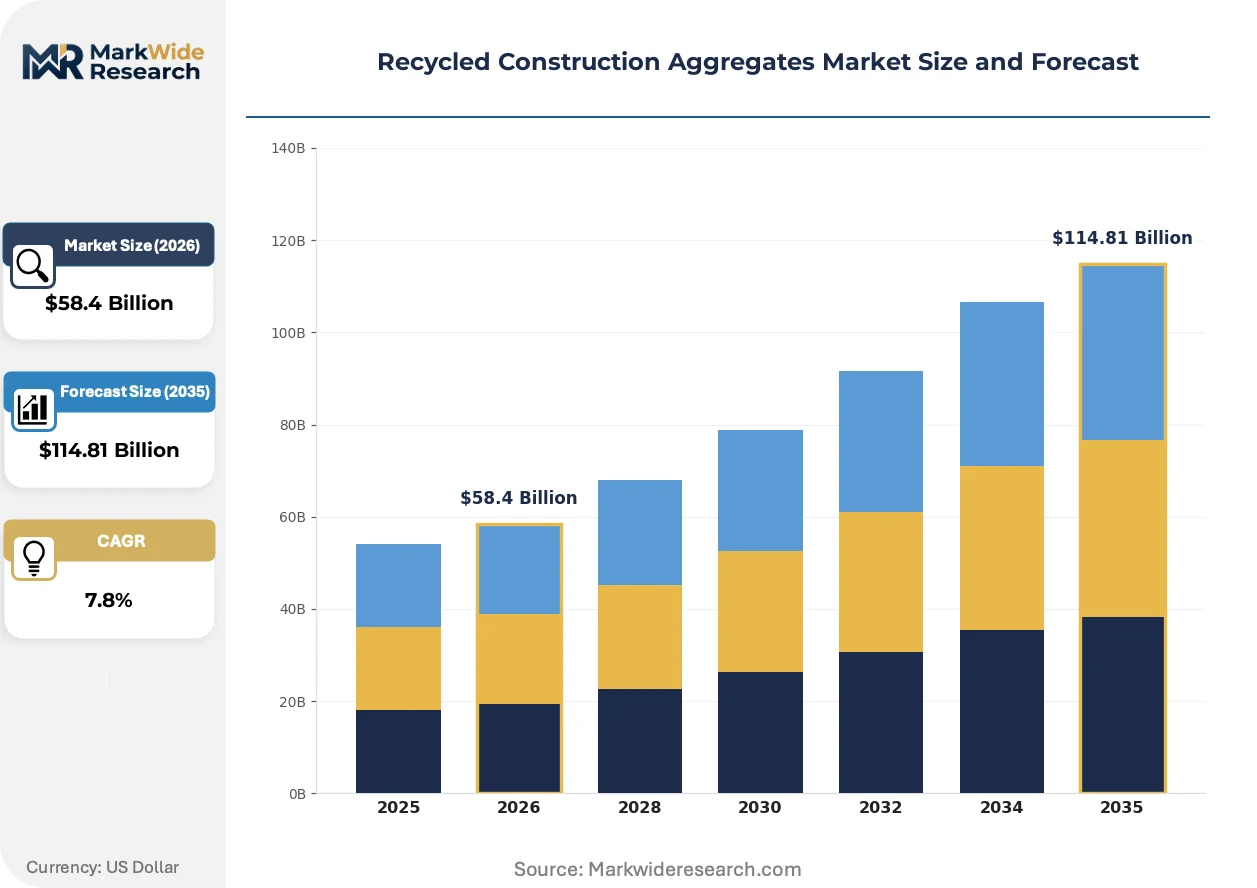
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $114.81 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Concrete, Crushed Brick, Glass Aggregate, Asphalt Millings End User: Construction Companies, Road Builders, Landscaping Firms, Demolition Contractors Application: Subbase Material, Landfill Cover, Drainage, Fill Material Distribution Channel: Direct Sales, Wholesale Dealers, Online Retail, Auctions |
| Companies Covered | CRH Plc., Tarmac, LafargeHolcim Ltd., CESPA, Aggregate Industries Management Inc., CEMEX, HeidelbergCement AG, Delta Sand & Gravel Co., Vulcan Materials Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Construction Aggregates Market Strategic Shifts & Innovations
Processing technology advances are fragmenting the historical concentration of high-volume recycled aggregate production in quarry-adjacent facilities, enabling smaller-scale distributed operations to meet engineered specifications previously requiring centralized capital investment.
Mobile sensor-based sorting systems using near-infrared and X-ray transmission are decentralizing quality control away from fixed-plant installations. Regional demolition contractors in Germany and the Netherlands are deploying containerized processing units directly at demolition sites, reducing haul distances and enabling real-time gradation adjustments. This distributed model is compressing the historical advantage of vertically integrated quarry operators that relied on captive feedstock monopolies.
REACH and RoHS frameworks are tightening hazardous substance migration thresholds for construction products containing recycled content. The European Chemicals Agency's expanded testing requirements for polycyclic aromatic hydrocarbons and heavy metals are disqualifying legacy demolition stockpiles from structural applications. Processors with in-house laboratory certification capabilities are capturing premium pricing tiers while commodity traders face inventory stranding.
Certification-driven procurement preferences are displacing price-first aggregate sourcing among tier-one infrastructure contractors. French and British road builders now require Environmental Product Declarations and recycled content traceability for public tender eligibility, forcing material traders to invest in chain-of-custody documentation systems. This behavioral shift is most visible in federal highway programs where compliance documentation now precedes price negotiation in vendor selection workflows.
Recycled Construction Aggregates Market Segmentation
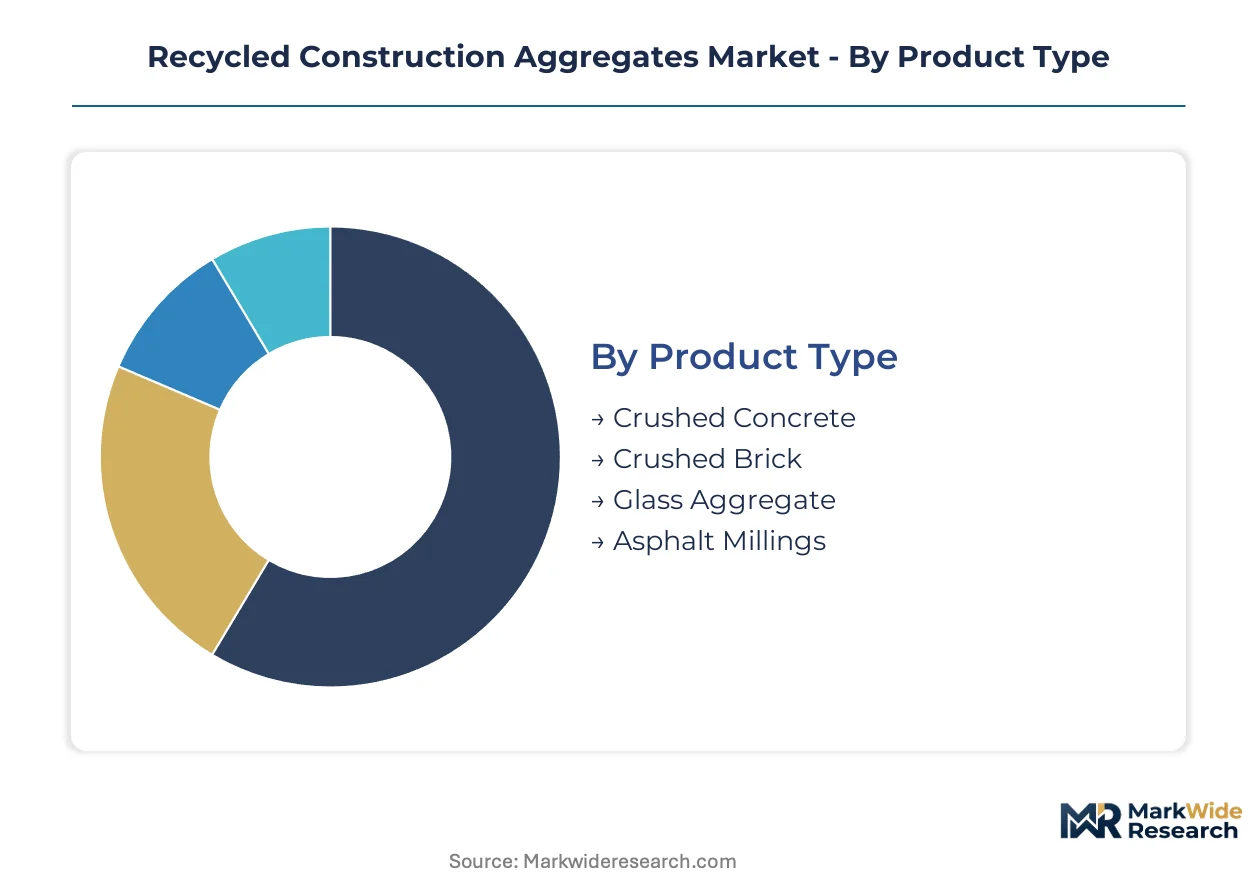
Segmentation in recycled construction aggregates reveals how material specifications, procurement channels, and end-use requirements fragment what appears to be a commodity market. Each dimension carries distinct margin profiles, certification burdens, and logistics constraints that reshape competitive positioning across the value chain.
Product Type:
Integration depth varies sharply across product types, with some serving as standalone engineered materials while others require blending with virgin aggregates to meet structural specifications.
- Crushed Concrete:Processed demolition concrete graded to specific particle size distributions for load-bearing subbase and structural fill applications. Road builders in Germany now specify this material for federal highway subbase layers under stricter EPA and EU landfill diversion rules, though REACH hazardous substance migration testing extends compliance timelines.
- Glass Aggregate:Chemically inert crushed glass produced from municipal bottle recycling streams, valued for decorative surfaces and high-permeability drainage layers where color consistency commands price premiums. Municipal mandates in North American and European cities are expanding feedstock availability fastest here.
- Crushed Brick:Lower-density material suited to non-structural fill and landscaping applications where aesthetic color variation proves advantageous rather than problematic.
- Asphalt Millings:Reclaimed asphalt pavement processed for base course or warm-mix recycling, with binder rejuvenation chemistry now enabling higher percentages in surface course specifications.
Crushed concrete leads volumes today; glass aggregate is gaining share fastest.
End User:
Customer sophistication and certification requirements create distinct service tiers, with infrastructure-grade buyers demanding chain-of-custody documentation that commodity traders cannot supply.
- Construction Companies:General contractors sourcing engineered fill for commercial and residential foundations, increasingly requiring Environmental Product Declarations for public tender eligibility under EU Green Deal procurement rules.
- Road Builders:Specialized infrastructure contractors facing the most stringent qualification timelines, with state DOT and federal highway administration validation processes freezing working capital for 18-24 months.
- Landscaping Firms:Smaller-scale buyers prioritizing color consistency and aesthetic gradation over compressive strength metrics.
- Demolition Contractors:Feedstock originators now deploying mobile processing units directly at demolition sites to capture value upstream, compressing traditional trader margins.
Road builders command premium pricing tiers; demolition contractors are integrating downstream fastest.
Application:
Performance thresholds and regulatory scrutiny intensify with structural load-bearing requirements, creating sharp price stratification across use cases.
- Subbase Material:Load-bearing layer beneath pavements and foundations requiring strict gradation control and compressive strength verification, with China's MEE mandating recycled content minimums in megacity infrastructure.
- Drainage:High-permeability applications including French drains and stormwater management where glass aggregate's chemical inertness and predictable void ratios prove superior to traditional rock.
- Landfill Cover:Daily and intermediate cover layers subject to environmental containment regulations but lower structural performance requirements.
- Fill Material:General engineered fill for site grading and elevation adjustments, the most price-sensitive segment with highest contamination tolerance.
Subbase material commands the steepest price premiums; drainage applications are climbing the fastest.
Distribution Channel:
Channel selection reflects shipment scale, certification documentation requirements, and the buyer's technical capability to assess material quality independently.
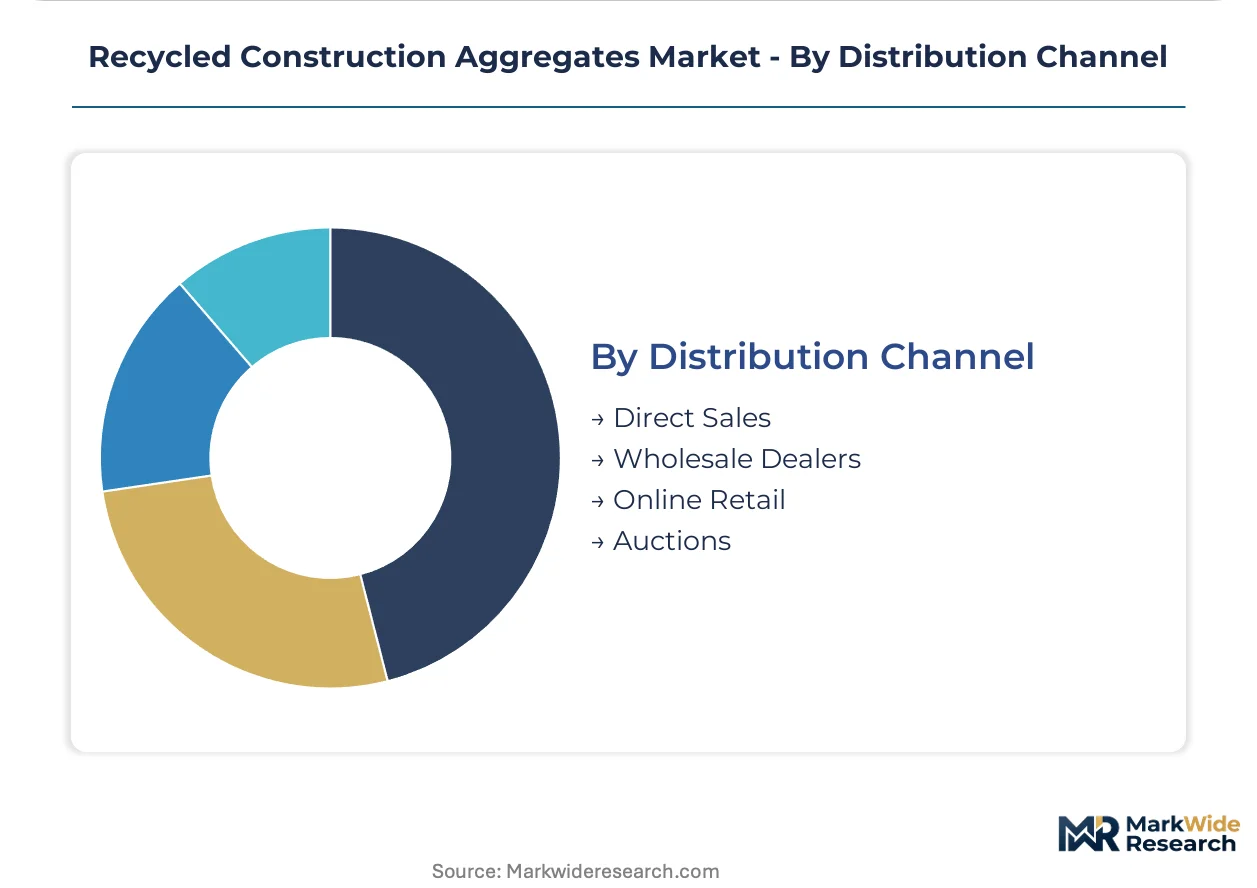
- Direct Sales:Large-volume contracts between processors and tier-one infrastructure contractors, capturing margin through long-term supply agreements with embedded quality assurance protocols.
- Wholesale Dealers:Regional traders aggregating uncertified stockpiles from multiple processors, facing inventory stranding as certification-driven procurement displaces price-first sourcing.
- Online Retail:Emerging platforms matching mobile-graded inventory to mid-sized demolition contractors, compressing fulfillment cycles and bypassing traditional intermediaries.
- Auctions:Spot-market liquidation of uncertified or surplus stockpiles, increasingly constrained by REACH and RoHS testing requirements that freeze liquidity for non-compliant material.
Direct sales dominate value capture; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled demolition contractors and aggregate technicians concentrate in Germany, China, India, and the United States, anchoring regional processing capacity and quality control standards.
Germany
Federal highway subbase specifications now mandate recycled crushed concrete under stricter landfill diversion rules. The EU Green Deal circular economy action plan binds member states to minimum recycled content thresholds for public infrastructure tenders. Processing corridors in North Rhine-Westphalia and Bavaria feed dedicated federal highway projects with certified material.
China
MEE construction waste recycling mandates in megacities are compressing virgin aggregate procurement channels. The Ministry of Ecology and Environment enforces construction waste management rules requiring recycling rates in Beijing, Shanghai, and Shenzhen. Yangtze River Delta demolition contractors are consolidating feedstock supply to centralized crushing facilities.
India
Mumbai and Pune demolition networks are achieving economies of scale unmatched by fragmented eastern state operations. Maharashtra state regulations incentivize construction waste diversion from landfills through tax rebates for certified processors. Western processing corridors in Gujarat are expanding capacity to serve Ahmedabad and Surat infrastructure projects.
United States
EPA landfill diversion targets are reshaping aggregate sourcing for state DOT projects. Federal highway administration validation processes require 18-24 month qualification timelines that freeze working capital for new entrants. Texas and California processing clusters near major metropolitan demolition corridors dominate certified supply.
United Kingdom
Environmental Product Declarations and recycled content traceability are now prerequisites for public tender eligibility under EU-derived procurement rules. WRAP certification protocols govern structural-grade recycled aggregate quality. London and Southeast England recycling clusters serve Crossrail and highway maintenance programs with documented chain-of-custody systems.
Recycled Construction Aggregates Market Key Industry Players
Top-tier vendors anchor premium-certified supply tiers, while commodity traders face inventory stranding as certification-driven procurement displaces price-first sourcing. The vendor base clusters around three strategic archetypes: vertically integrated quarry operators with captive demolition networks, specialized recycling pure-plays with laboratory certification capabilities, and equipment suppliers licensing mobile processing technology. Dominant competitive moves include backward integration into demolition contracting and geographic clustering near major metropolitan feedstock corridors.
Among Ireland-based building materials conglomerates, CRH Plc. exemplifies vertical integration through quarry-adjacent processing networks. LafargeHolcim Ltd. and HeidelbergCement AG represent European-headquartered cement majors competing on proprietary crushing protocols and recycling cluster density. These three anchors illustrate how scale and certification infrastructure separate premium-tier positioning from commodity trading margins.
| Leading Market Players |
|---|
| CRH Plc. |
| Tarmac |
| LafargeHolcim Ltd. |
| CESPA |
| Aggregate Industries Management Inc. |
| CEMEX |
| HeidelbergCement AG |
| Delta Sand & Gravel Co. |
| Vulcan Materials Company |
| Others |
Cost & Logistics Intelligence
Captive demolition-to-processing networks anchor supply positioning and pricing power for tier-one operators, with backward integration into feedstock sourcing enabling margin capture that spot-market traders cannot replicate under REACH certification mandates.
Pricing Analysis
Bundled certification-plus-delivery contracts command premiums over unbundled commodity spot sales, with three-tier pricing structure across premium, standard, and economy levels separating road builders requiring Environmental Product Declarations from fill-grade buyers. Price differentiation hinges on REACH hazardous substance testing completion and volume scale, with certified structural-grade material carrying 40-60% markups over uncertified stockpiles. Pricing pressure stems from natural aggregate price volatility driven by diesel and explosives cost fluctuations, eroding recycled product margin advantages intermittently. Road builders show lowest price sensitivity due to tender compliance requirements, while general fill contractors remain highly price-elastic.
Supply Chain Analysis
Regional distribution centers in Germany, China, and India form hub-and-spoke patterns feeding dedicated processing corridors, with containerized mobile units now bypassing fixed-plant bottlenecks. Feedstock draws from demolition concrete, reclaimed asphalt, and municipal glass streams, with sensor-based sorting equipment resting on near-infrared and X-ray transmission technology imports. Single-source vulnerability concentrates in specialized sorting equipment supply, where European and Asian equipment licensors control deployment. Distribution runs through direct sales contracts for infrastructure-grade volumes, with wholesale dealers facing inventory stranding as certification requirements tighten.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward premium-certified structural grades displace price-first sourcing among tier-one infrastructure contractors.
For Market Incumbents: Extend laboratory certification capabilities to capture premium pricing tiers as REACH testing requirements disqualify legacy stockpiles, while adding mobile processing capacity in Maharashtra and Gujarat to defend feedstock access against emerging demolition contractor integrators. Backward integration into demolition contracting anchors supply security. For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms targeting mid-sized demolition operators in India's western states, where fragmented eastern competition leaves procurement vacuums. White-space exists in glass aggregate drainage applications and warm-mix RAP binder rejuvenation chemistry, with lowest entry barriers in non-structural fill segments lacking DOT certification requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized recycling pure-plays with in-house laboratory capabilities because certification-driven procurement is displacing commodity traders and concentrating margin capture among documented quality providers. Target processors holding WRAP or state DOT approvals with demonstrated chain-of-custody systems. Watch for inflection when federal highway administration validation timelines compress below 12 months, signaling working capital release and scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Demolition Contracting | Secures captive feedstock supply for CRH and LafargeHolcim processing clusters near European urban corridors. |
| Laboratory Certification Capability Investment | Enables premium pricing capture under ECHA expanded polycyclic aromatic hydrocarbon testing protocols. |
| Mobile Processing Unit Deployment | Compresses haul distances for German and Dutch demolition contractors operating containerized sorting systems. |
| Direct-to-Contractor Digital Platform Launch | Bypasses wholesale dealer intermediaries for mid-sized contractors in Maharashtra processing corridors. |
| Joint Venture in Chinese Megacity Markets | Positions foreign equipment suppliers to capture procurement vacuums from MEE 70% recycling mandates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with demolition contractors, aggregate plant managers, state DOT procurement officers, and road builder project engineers alongside secondary validation through EPA landfill diversion reports, EU Green Deal circular economy action plan documentation, China MEE construction waste management filings, and customs trade data on crushing equipment imports. Bottom-up feedstock volume estimates and top-down infrastructure spending projections were triangulated to anchor market sizing.
Historical reference periods established baseline recycling rates and virgin aggregate price relationships across the modeling period, with segmentation dimensions including product type, end user sophistication tier, application performance threshold, and distribution channel structure. CAGRs were derived from demand elasticity modeling against public infrastructure tender flows and demolition waste generation forecasts, incorporating binder rejuvenation chemistry adoption curves for RAP surface course integration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios where certification requirements tighten unevenly between jurisdictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Gravity Retaining Wall Market
Building Materials
China Architectural Coatings Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Building Asphalt Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Blind Bolts Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Natural Stone Slab Market
Building Materials
Basalt Rock Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Steel Products Market