
 Drain Cleaning Equipment Market | 2026-2036
Drain Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Drain Cleaning Equipment Market Intelligence
ISO 9001 certification is bifurcating the competitive landscape into qualified OEM suppliers and unverified regional assemblers. RIDGID leverages its captive distribution network across North American plumbing supply houses to sustain premium positioning. Spartan Tool anchors its presence through specialized drum machine engineering for municipal contractors. Kärcher competes on manufacturing scale in water jetting systems for European facility management channels.
Drain cleaning equipment encompasses powered and manual devices designed to clear blockages from pipes, drains, and sewer lines, typically operating at pressures from 1,500 to 4,000 PSI for hydro-jetters and employing flexible cables up to 200 feet for mechanical augers. These systems serve plumbing contractors, utility providers, and industrial plants by restoring flow capacity without excavation. Hydro-jetters command the largest revenue pool due to higher unit costs and replacement frequency, while robotic cleaning systems represent the fastest-expanding technology segment as municipalities seek to inspect and clear lines simultaneously. Drum machines retain dominant volume share among plumbing contractors for residential call-outs where portability and lower capital outlay matter most.
EPA enforcement under the Clean Water Act shapes municipal procurement standards for wastewater discharge compliance, while EU F-Gas Regulation and CE marking requirements filter which equipment configurations enter European utility fleets. OSHA lockout/tagout protocols influence electric drain cleaner design specifications for commercial plumbing crews. Stakeholders must weigh regulatory compliance timelines against equipment replacement cycles when allocating capital across mechanical and automated cleaning platforms.
Market Dynamics
Municipal procurement departments face compressed replacement cycles as EPA Clean Water Act enforcement intensifies discharge monitoring requirements, forcing simultaneous upgrades across mechanical auger fleets and inspection technologies.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Revised discharge standards in Germany and France mandate higher cleaning frequency, expanding hydro-jetter deployment across utility networks.
- Robotic inspection convergence:Municipal contractors adopt combined camera-jetting units that clear blockages while documenting pipe condition, reducing repeat truck rolls.
- Aging cast-iron sewer inventory:Pre-1970 infrastructure in US Northeast and Midwest cities requires gentler hydro-jetting methods that preserve deteriorating lines.
Market Restraints
- High-pressure pump supply concentration:German and Italian pump specialists control core hydro-jetter component supply, creating vulnerability for North American assemblers.
- Steel and aluminum price volatility:Drum machine frames and cable assemblies face input cost swings that compress margin on entry-grade contractor equipment.
- Manual auger residual demand:Residential plumbing contractors in price-sensitive markets continue specifying hand-crank units for routine sink and tub calls.
Strategic Opportunities
- India urban sanitation expansion:Smart Cities Mission funding creates first-time demand for powered drain cleaning in municipal maintenance departments previously reliant on manual labor.
- CE marking as competitive filter:EU equipment certification requirements block unverified Asian assemblers, opening share for ISO 9001-qualified suppliers.
- Rental channel development:Equipment rental networks in Australia and Canada expand contractor access to high-cost hydro-jetters without capital outlay.
Industry Challenges
- Technician certification requirements:OSHA lockout/tagout training and high-pressure water safety credentials extend hiring timelines for commercial plumbing crews.
- Legacy fleet integration:Municipal departments struggle to synchronize new robotic inspection data formats with decades-old GIS mapping systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drain Cleaning Equipment Market |
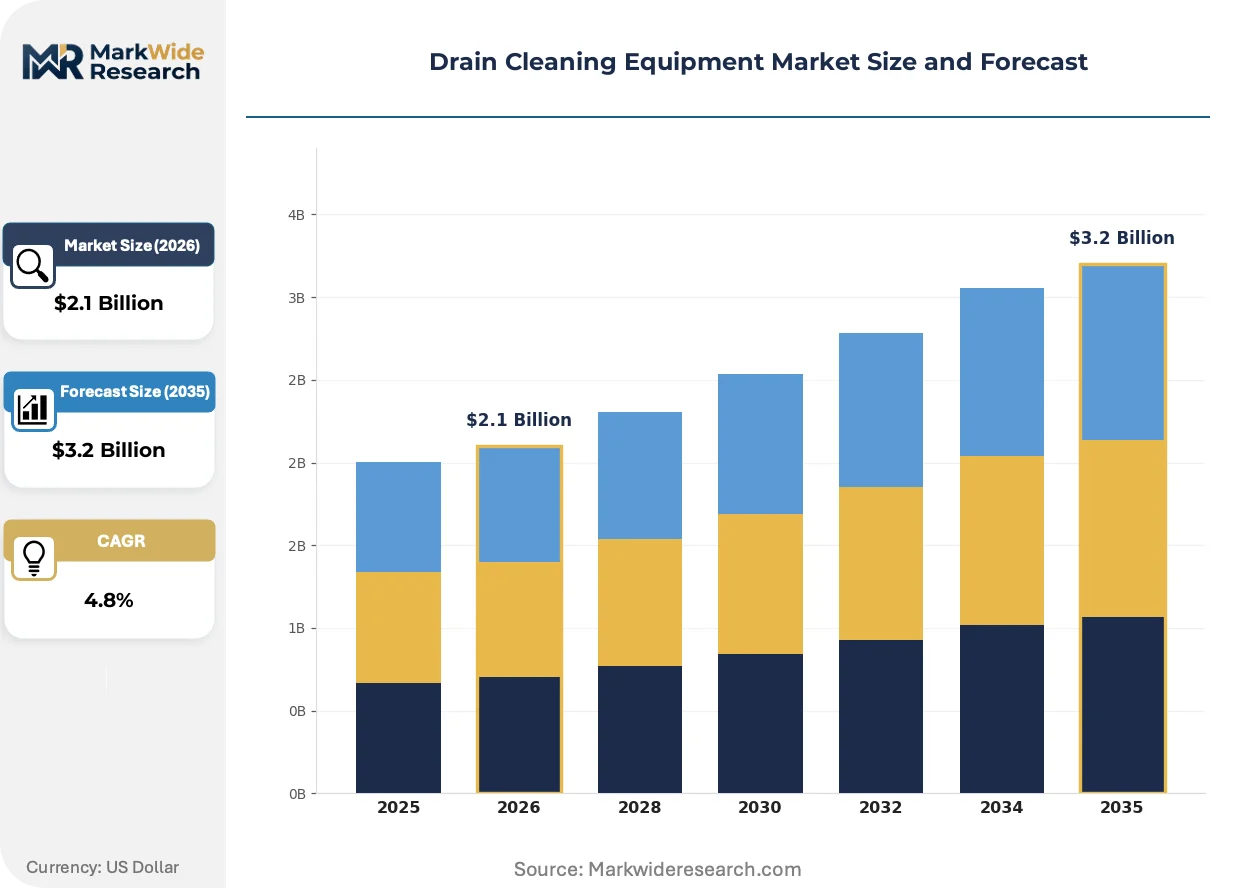
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Drain Cleaners, Manual Drain Augers, Hydro-Jetters, Drum Machines, Pneumatic Drain Cleaners Technology: Mechanical, Water Jetting, Robotic, High-Pressure Air, Chemical Cleaning Application: Residential Plumbing, Commercial Sewage, Municipal Maintenance, Industrial Waste Management End User: Plumbing Contractors, Facility Management, Utility Providers, Industrial Plants |
| Companies Covered | RIDGID, Spartan Tool, General Pipe Cleaners, General Wire Spring, DURACABLE, Gorlitz Sewer & Drain, Electric Eel Manufacturing, Kärcher, ROTHENBERGER Werkzeuge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drain Cleaning Equipment Market Strategic Shifts & Innovations
Water jetting systems are integrating sensor feedback and automated pressure modulation, compressing the skill gap between veteran operators and entry-level technicians while expanding addressable contract scope.
Robotic crawler systems with integrated jetting heads are displacing separate inspection-and-clearing workflows that required multiple truck deployments. Municipal sewer departments in Germany and the Netherlands adopt these units for preventive maintenance contracts where single-pass efficiency determines bid competitiveness. The technology is displacing standalone CCTV inspection contracts that previously dominated municipal procurement specifications.
EPA enforcement of the Clean Water Act is tightening municipal discharge permit monitoring, forcing wastewater utilities to document pipe cleaning frequency and method. This industrial consequence accelerates replacement of undocumented manual clearing with logged powered equipment. Hydro-jetter configurations with automated cycle counters and GPS logging see preferential specification in US municipal RFPs.
Equipment-as-service models are emerging in European facility management channels, where building maintenance contractors rent hydro-jetters by the hour rather than owning depreciating assets. This channel disruption favors manufacturers with captive rental fleets or distributor partnerships over traditional sales-dependent suppliers. The shift is most visible in German commercial property management, where bundled cleaning service contracts now specify equipment provision by the vendor.
Drain Cleaning Equipment Market Segmentation
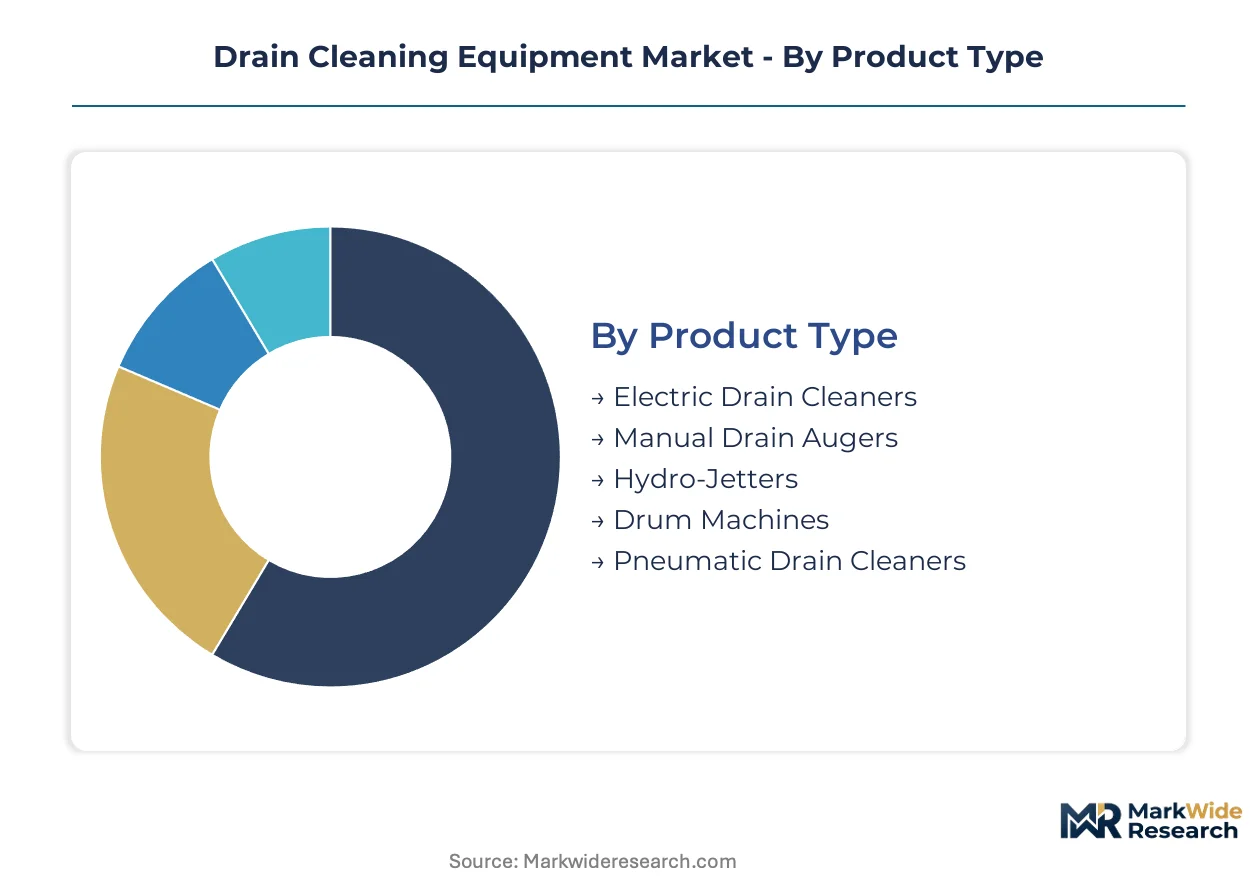
Drain cleaning equipment manufacturers route distinct product configurations through specialized channels. Municipal procurement departments favor high-capital systems with documented compliance features, while residential contractors prioritize portable units available through plumbing supply distributors.
Product Type:
Channel mix varies sharply by product category. Hydro-jetters and drum machines flow through municipal fleet distributors and rental networks, while manual augers concentrate in retail plumbing supply houses serving residential contractors.
- Hydro-Jetters:These systems generate water pressure between 1,500 and 4,000 PSI through gasoline or diesel engines, requiring trailer or truck mounting for field deployment. Demand concentrates in Germany and France where EU Urban Wastewater Treatment Directive revisions mandate higher cleaning frequency across utility networks.
- Drum Machines:Spring-steel cables wound on motorized drums clear blockages in pipes up to 200 feet from the access point, balancing portability with reach. Plumbing contractors in the US Northeast specify these for residential call-outs where aging cast-iron infrastructure demands gentler mechanical methods than hydro-jetting.
- Electric Drain Cleaners:Compact units with flexible auger cables powered by 110V or 240V motors serve commercial building maintenance crews.
- Manual Drain Augers:Hand-cranked snake tools remain the entry specification for price-sensitive residential plumbers in emerging markets.
- Pneumatic Drain Cleaners:Compressed-air burst systems clear grease blockages in commercial kitchen drain lines without cable abrasion.
By volume, drum machines lead. By growth pace, hydro-jetters are expanding most quickly.
Technology:
Cost tiers separate these technologies. Robotic and water jetting systems command premium pricing with specialized maintenance contracts, while mechanical and chemical methods occupy economy positioning.
- Water Jetting:High-pressure pump systems with specialized nozzles cut through tree roots and grease deposits without mechanical abrasion. Municipal sewer departments in the Netherlands adopt these for preventive maintenance contracts where single-pass efficiency determines bid competitiveness.
- Robotic:Crawler-mounted camera and jetting combinations inspect and clear lines simultaneously, eliminating repeat truck rolls. German utility providers facing F-Gas Regulation compliance timelines specify these units to replace older mechanical systems with documented cleaning logs.
- Mechanical:Cable-and-auger methods retain volume leadership among residential plumbing contractors.
- High-Pressure Air:Pneumatic burst technology clears localized blockages in commercial settings.
- Chemical Cleaning:Caustic and enzymatic formulations serve as maintenance supplements rather than primary clearing methods.
Mechanical systems retain the largest installed base. Robotic configurations are gaining share fastest.
Application:
Customer type dictates specification requirements. Municipal maintenance demands integrated logging and GPS tracking, while residential applications prioritize speed and portability.
- Municipal Maintenance:City sewer departments require equipment with automated cycle counters and GPS logging to satisfy EPA Clean Water Act discharge permit documentation. US municipalities specify these features in formal RFPs.
- Commercial Sewage:Property management firms and facility contractors need rapid-response systems for multi-tenant buildings.
- Residential Plumbing:Independent contractors favor drum machines and manual augers for single-family service calls.
- Industrial Waste Management:Manufacturing plants specify explosion-proof electric units or pneumatic systems for hazardous environments.
Residential plumbing generates the highest call volume. Municipal maintenance shows the steepest equipment upgrade trajectory.
End User:
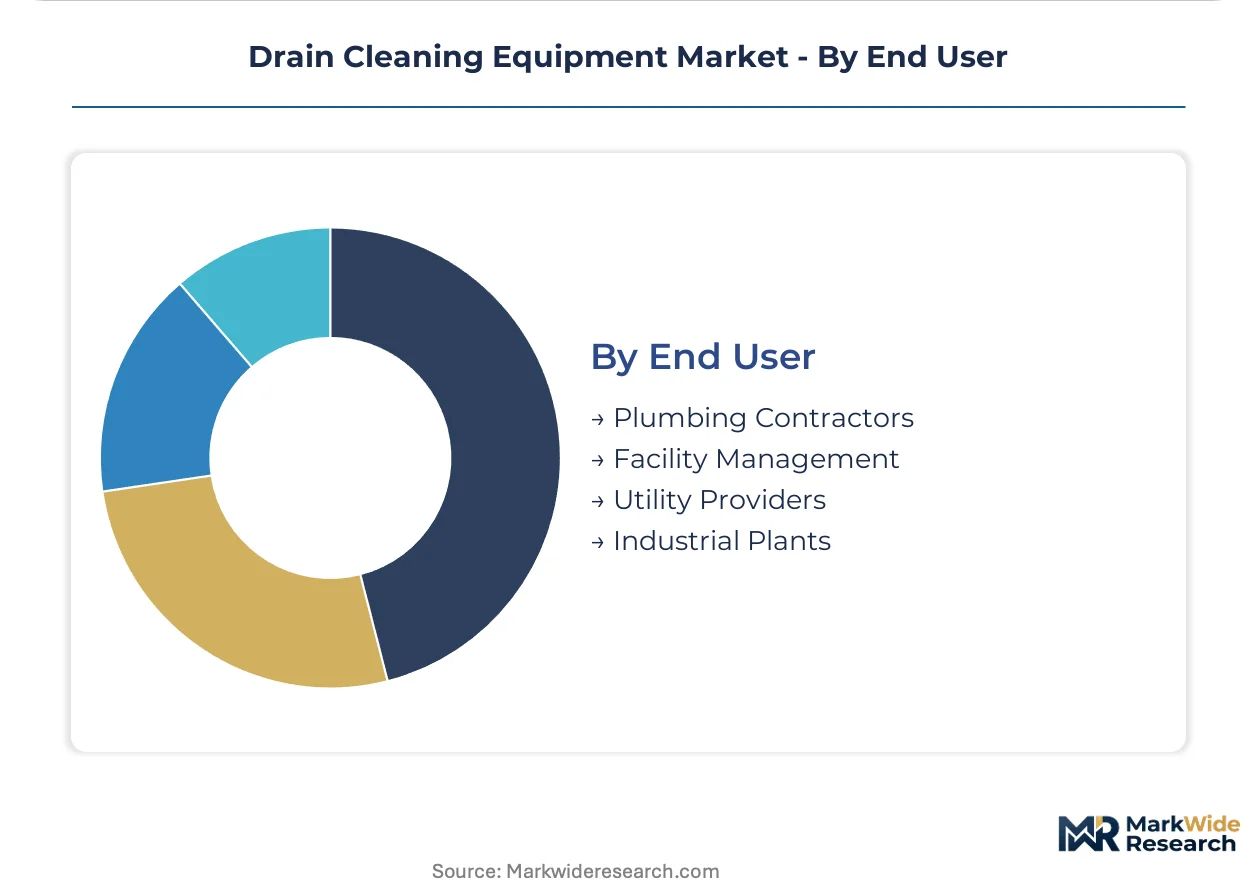
Procurement authority varies by end user type. Utility providers issue multi-year fleet contracts with compliance specifications, while plumbing contractors make discretionary spot purchases.
- Utility Providers:Municipal wastewater authorities in Germany and France deploy hydro-jetters and robotic crawlers under preventive maintenance contracts with performance-based payment terms.
- Plumbing Contractors:Independent service companies in the US Midwest specify drum machines for residential cast-iron sewer calls.
- Facility Management:European commercial property managers increasingly specify equipment-as-service rental arrangements rather than capital purchases.
- Industrial Plants:Refinery and chemical facility maintenance departments require certified explosion-proof configurations.
Plumbing contractors represent the broadest customer base. Utility providers drive the fastest technology upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Water Act enforcement and EU Urban Wastewater Treatment Directive revisions are accelerating municipal procurement cycles across multiple jurisdictions. Utility providers face compressed replacement timelines as discharge monitoring requirements tighten. Equipment manufacturers route compliance-certified configurations through specialized fleet distributors in each major market.
United States
Municipal sewer departments in the US Northeast and Midwest specify hydro-jetters with automated cycle counters for aging pre-1970 cast-iron infrastructure. EPA enforcement intensifies discharge permit documentation requirements. Boston and Chicago utility fleets drive demand for GPS-logged equipment that satisfies formal RFP specifications.
Germany
Utility providers face stricter F-Gas Regulation compliance timelines and are replacing older mechanical systems with water jetting and robotic technologies. EU Urban Wastewater Treatment Directive revisions mandate higher cleaning frequency across utility networks. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate preventive maintenance contract awards.
France
Revised discharge standards expand hydro-jetter deployment across municipal utility networks. CE marking requirements filter equipment configurations entering French utility fleets. Paris and Lyon metropolitan authorities specify combined camera-jetting units for single-pass efficiency in preventive maintenance contracts.
India
Smart Cities Mission funding creates first-time demand for powered drain cleaning in municipal maintenance departments previously reliant on manual labor. Central government urban sanitation programs accelerate procurement of mechanical and water jetting systems. Maharashtra and Gujarat state municipal corporations lead equipment deployment in western industrial corridors.
Canada
Equipment rental networks expand contractor access to high-cost hydro-jetters without capital outlay. Municipal procurement departments synchronize fleet upgrades with federal infrastructure funding cycles. Ontario and Alberta utility providers specify hydro-jetter configurations for cold-weather operational reliability.
Drain Cleaning Equipment Market Key Industry Players
Player mix skews toward specialized industrial equipment manufacturers with captive distribution networks and regional assemblers serving price-sensitive segments. Market structure concentrates around three tiers: premium OEMs with ISO 9001 certification, mid-scale specialists with regional channel depth, and unverified local assemblers competing on entry-grade pricing. Dominant competitive moves include strategic partnerships with municipal fleet distributors and geographic expansion through rental channel development.
Among North American equipment specialists, RIDGID and Spartan Tool exemplify the premium-tier archetype with established supply house presence. Kärcher represents the European manufacturing-scale segment with facility management channel penetration. These three anchors demonstrate how certification status and distribution architecture separate qualified OEM suppliers from unverified regional competitors in municipal procurement specifications.
| Leading Market Players |
|---|
| RIDGID |
| Spartan Tool |
| General Pipe Cleaners |
| General Wire Spring |
| DURACABLE |
| Gorlitz Sewer & Drain |
| Electric Eel Manufacturing |
| Kärcher |
| ROTHENBERGER Werkzeuge |
| Others |
Cost & Logistics Intelligence
ISO 9001 certification gates both supplier qualification and price differentiation in municipal procurement, separating premium OEMs from unverified regional assemblers across North American and European utility fleets. This bifurcation concentrates pricing power with certified manufacturers while compressing margins for uncertified competitors excluded from formal RFP channels.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate drum machine procurement, tying unit prices to commodity volatility on entry-grade contractor equipment. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified hydro-jetters from CE-marked mid-tier units and unverified manual augers. Cost compression in entry-grade mechanical equipment is intensifying because steel price swings transmit directly to cable assembly costs. Residential plumbing contractors in price-sensitive markets exhibit highest price sensitivity, while municipal fleet managers prioritize compliance documentation over unit cost.
Supply Chain Analysis
German and Italian high-pressure pump specialists constitute a chokepoint that constrains hydro-jetter production capacity for North American assemblers. Manufacturing gravity centers on Germany for precision pump components, Italy for specialized nozzles, and China for steel cable assemblies. Raw material dependencies span spring steel for drum cables, aluminum for portable frames, and precision-machined pump heads. Single-source vulnerability concentrates in German pump supply, where limited qualified alternatives extend lead times during demand surges. Distribution runs through captive rental networks in Canada and Australia, municipal fleet distributors in the US and Germany, and plumbing supply houses serving residential contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-service rental models and chemical-free clearing technologies threaten traditional capital-sales incumbents with asset-light substitution. Incumbents must defend installed base relationships while building service revenue streams that resist displacement.
For Market Incumbents: Consolidate aftermarket service capabilities to lock in municipal fleet relationships against rental-channel disruption. Deepen backward integration into high-pressure pump supply through partnerships with German specialists, reducing exposure to single-source component risk. Anchor recurring revenue through preventive maintenance contracts that bundle equipment provision with documented compliance logging.
For New Entrants and Emerging Players: Anchor in India's Smart Cities Mission procurement channels, where first-time powered equipment demand outpaces established supplier presence. Target state municipal corporations in Maharashtra and Gujarat with drum machine configurations priced below European OEM tiers. Pursue equipment-as-service partnerships with facility management contractors in German commercial property markets, bypassing capital-sales competition with incumbent manufacturers.
For Investors and Strategic Acquirers: EPA Clean Water Act enforcement milestones reshape the acquisition landscape by accelerating municipal fleet replacement cycles and elevating compliance-technology valuations. Five-to-ten year viability favors targets with ISO 9001 certification and captive distribution in North American plumbing supply channels. Monitor F-Gas Regulation compliance timelines in Germany as signal for robotic cleaning system demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU certification unlocks municipal procurement in Germany, France, and Netherlands utility networks. |
| Backward Integration | In-house pump production reduces exposure to German and Italian component supply concentration. |
| Rental Fleet Expansion | Equipment-as-service contracts in Canada and Australia capture contractors avoiding capital outlay. |
| Robotic Technology Licensing | Camera-jetting combinations displace separate inspection workflows in German preventive maintenance. |
| Smart Cities Partnership | Central government funding in Maharashtra and Gujarat creates first-time municipal demand channels. |
Research Approach
A standing panel of municipal fleet managers, plumbing supply house category buyers, aftermarket service directors, and utility procurement officers provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA enforcement disclosures, EU Urban Wastewater Treatment Directive revision texts, F-Gas Regulation compliance timelines, and municipal RFP documentation. Customs records for steel and aluminum trade flows, SEC filings from listed equipment manufacturers, and rental network expansion announcements furnished quantitative anchors. Bottom-up equipment deployment estimates triangulated against top-down municipal capital expenditure budgets.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated product type, technology tier, application intensity, and end-user procurement authority. CAGRs derived from equipment replacement cycle analysis, regulatory compliance timeline compression, and rental channel penetration curves. Forecast inputs included municipal fleet age profiles, pre-1970 sewer infrastructure inventory assessments, and technician certification requirement expansions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation in steel input costs or EPA inspection frequency would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation compliance deadlines and Smart Cities Mission funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Drill Bit Market
Tools
Global Scarifiers Market
Tools
Lathe Machines Market
Tools
Grabber Pole Market
Tools
Global Electric Portable Drill Market
Tools
Overload Protection Tools Market
Tools
Tool Hammer Market
Tools
Belt File Sander Market
Tools
Power Tool Accessories Market
Tools
Striking Tools Market
Tools
Water Pump Pliers Market
Tools
2D Laser Cutting Machine Market
Tools
Cutting Tool Inserts Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Global Construction Camera Market
Tools
Leather Embossing Machine Market