
 Southern Africa Construction Equipment Rental Market | 2026-2036
Southern Africa Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Southern Africa Construction Equipment Rental Market Intelligence
ISO 4309 crane rope inspection certification is bifurcating the competitive landscape into compliant fleet operators and informal providers. Barloworld leverages its southern African dealership network to sustain maintenance capabilities across multiple jurisdictions. Goscor Group anchors its position through specialized material handling distribution in South Africa's industrial heartland. Babcock International competes on operator training and technical service bundling rather than pure asset rental.
Construction equipment rental denotes the short-to-medium-term provision of heavy machinery—typically diesel-powered assets with operating weights exceeding five tonnes—without transfer of ownership, serving project-based demand cycles in capital-constrained environments. Earthmoving machines generate the largest revenue pool due to persistent mining and infrastructure earthworks, while lifting equipment records faster expansion driven by renewable energy installation projects across the subcontinent. Rental duration structures reveal project-based leasing as the margin-dense segment, though short-term contracts dominate transaction volume among building contractors managing cash-flow volatility.
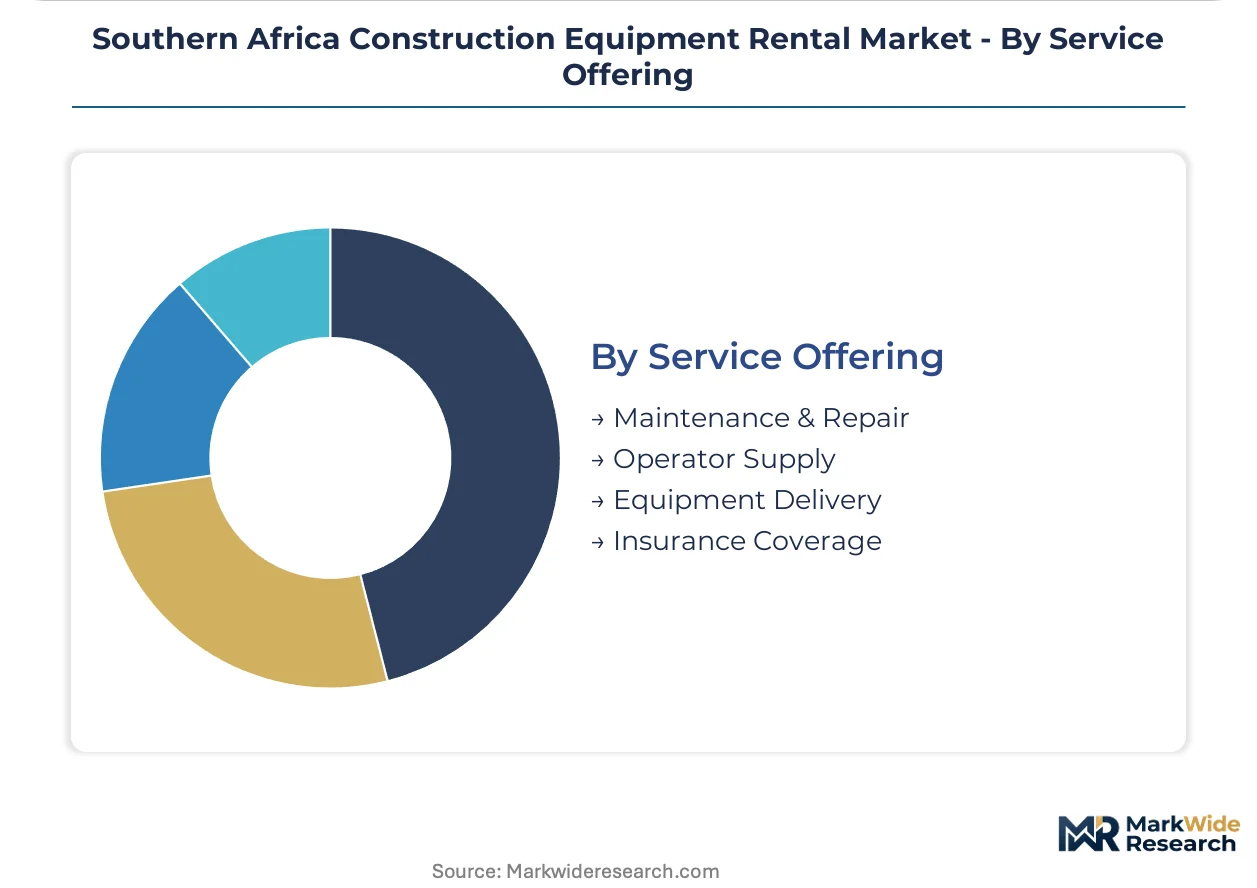
South Africa's Department of Labour Construction Regulations and Zambia's Mines Safety Department equipment standards collectively elevate compliance costs for independent fleet owners. The Occupational Health and Safety Act inspection regimes in South Africa and Botswana's Department of Roads equipment certification requirements restrict market access to capitalized players with in-house technical audit capacity. Stakeholders must monitor harmonization pressures between SADC member state equipment standards and the emerging AfCFTA technical barriers-to-trade protocols.
Market Dynamics
Capital discipline among mining houses is fundamentally restructuring equipment access models across the subcontinent, as balance-sheet optimization overrides traditional ownership preferences for long-life earthmoving assets.
Growth Catalysts
- ISO 4309 crane rope inspection certification:South Africa's Department of Labour Construction Regulations mandate certified equipment inspections, pushing contractors toward rental providers with established compliance infrastructure.
- Copperbelt mining expansion:Zambia's Copperbelt Province and Botswana's Kalahari copper belt are driving fleet utilization rates as exploration activity intensifies.
- Renewable energy installation surge:Wind and solar projects across Namibia and South Africa's Northern Cape are accelerating demand for specialized lifting equipment with rapid deployment requirements.
Market Restraints
- Diesel price volatility:Fuel represents 35-45% of operating costs for rental fleet operators, with South Africa's regulated fuel pricing creating margin compression during price adjustment cycles.
- Import dependency for specialized components:Hydraulic systems and electronic control modules concentrate supply from European and Asian manufacturing hubs, exposing operators to extended lead times.
- SADC regulatory fragmentation:Non-harmonized equipment certification requirements between South Africa, Zambia, and Botswana force redundant compliance expenditure for cross-border fleet deployment.
Strategic Opportunities
- Mozambique LNG corridor infrastructure:Northern Mozambique's emerging energy province remains underpenetrated by established rental networks, creating first-mover positioning for compliant operators.
- Telematics-integrated predictive maintenance:Convergence of IoT sensors and machine learning is enabling outcome-based uptime guarantees that differentiate premium fleet operators.
- Angola reconstruction phase:Post-conflict infrastructure rehabilitation presents channel innovation potential through project-specific joint ventures with local construction consortia.
Industry Challenges
- Certified technician scarcity:South Africa's Department of Higher Education trade certification bottlenecks constrain fleet maintenance capacity expansion.
- Cross-border equipment recovery:Contract enforcement heterogeneity across SADC jurisdictions complicates asset repatriation from defaulting lessees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southern Africa Construction Equipment Rental Market |
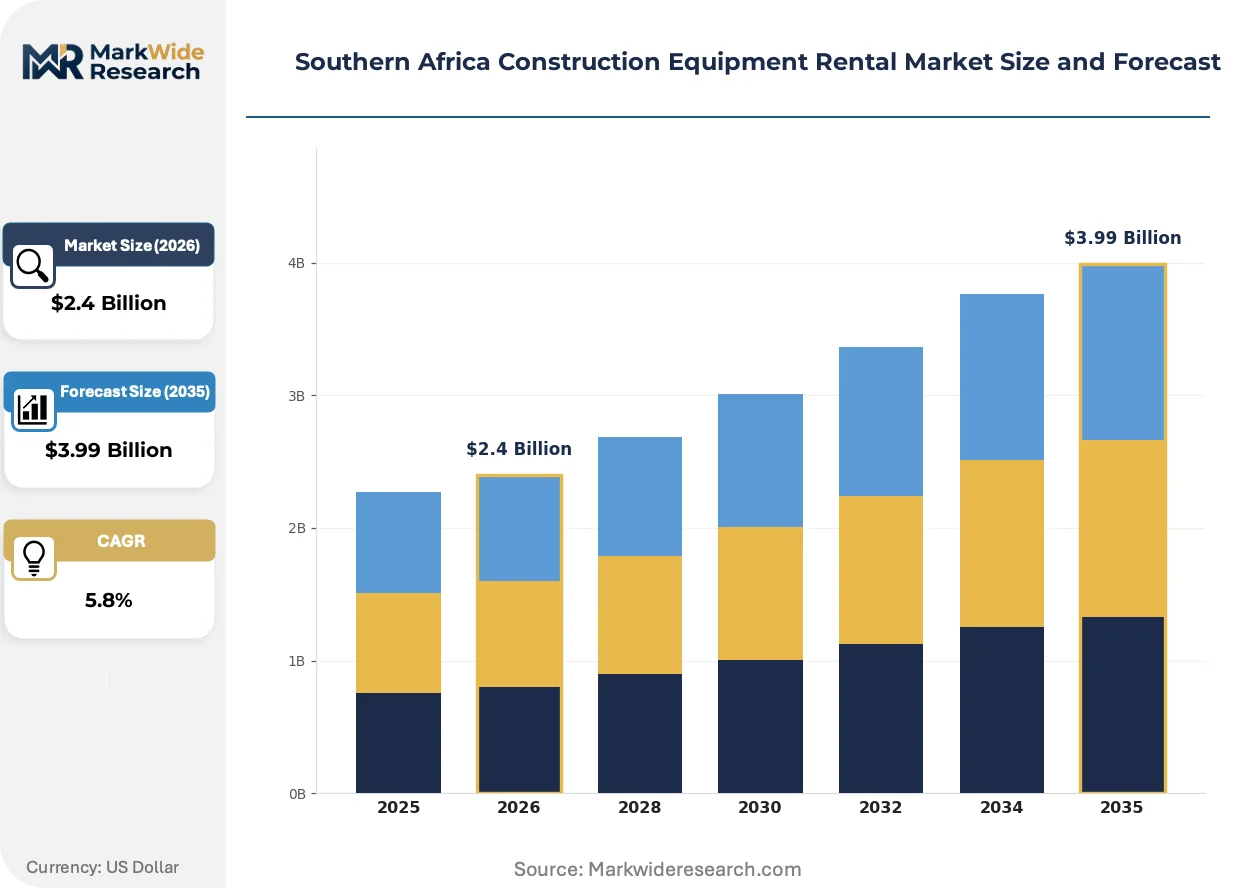
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Earthmoving Machines, Lifting Equipment, Material Handling Devices, Concrete Equipment, Compaction Machinery Rental Duration: Short-Term, Medium-Term, Long-Term, Project-Based Leasing Customer Category: Building Contractors, Civil Engineers, Infrastructure Developers, Mining Firms Service Offering: Maintenance & Repair, Operator Supply, Equipment Delivery, Insurance Coverage |
| Companies Covered | Barloworld, Alistair Group, Adima Hire, Atlas Crane Hire, Anglo V3 Crane Hire, Coastal Hire, Goscor Group, enX Equipment, Babcock International, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southern Africa Construction Equipment Rental Market Strategic Shifts & Innovations
Digital fleet management systems are compressing equipment utilization transparency gaps, while regulatory compliance automation is separating capitalized operators from informal competitors.
Telematics-enabled utilization monitoring is bifurcating the competitive landscape between data-driven fleet optimizers and traditional rate-based competitors. Mining contractors in Botswana's Mowana copper operations and South Africa's Bushveld platinum belt are mandating real-time equipment telemetry as a contract precondition. This capability compression is forcing mid-tier rental providers toward technology partnerships or market exit.
South Africa's updated Construction Regulations under the Department of Labour require documented crane rope inspection records traceable to ISO 4309 standards. The industrial consequence is a compliance cost barrier that informal operators cannot absorb. Gauteng province's logistics corridor contractors are responding by consolidating procurement relationships with certified fleet providers possessing in-house technical audit capacity.
Project-based leasing structures are displacing traditional dry-hire arrangements as the preferred contracting mechanism for renewable energy EPC contractors. This model bundles operator certification, maintenance liability, and fuel management into single-source accountability. The shift is most visible in South Africa's Northern Cape solar installations and Namibia's wind development zones, where developer risk transfer preferences favor comprehensive service integration over asset-only provision.
Southern Africa Construction Equipment Rental Market Segmentation
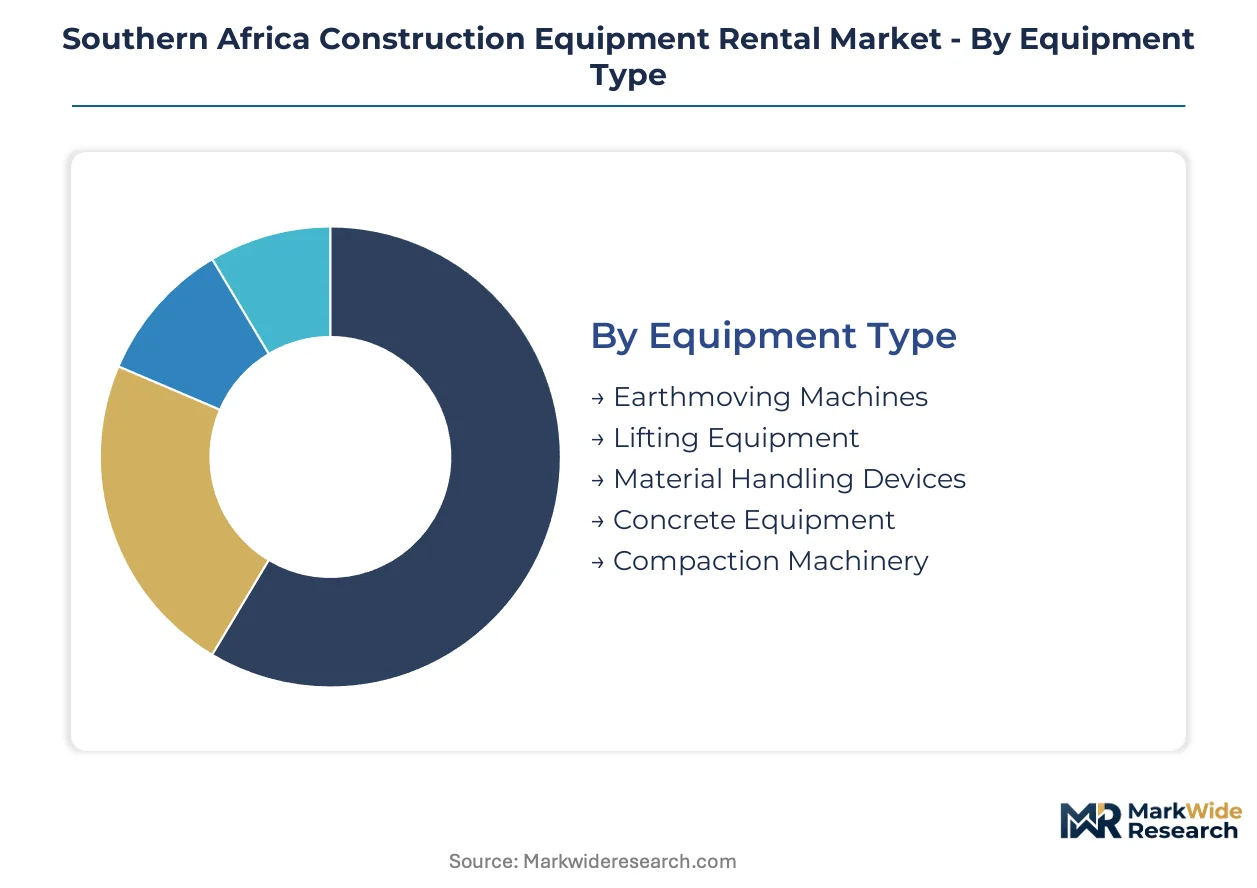
Equipment rental segmentation in Southern Africa reflects divergent capital intensity across mining, infrastructure, and building verticals. Rental providers structure fleet composition and service bundling around project duration risk and regulatory compliance burdens specific to each customer category.
Equipment Type:
Earthmoving machines dominate cross-border deployment between South Africa, Zambia, and Botswana due to copperbelt mining concentration, while lifting equipment serves concentrated renewable energy clusters in Namibia and South Africa's Northern Cape.
- Earthmoving Machines:Diesel-powered assets exceeding five tonnes operating weight, comprising excavators, bulldozers, and motor graders. Demand concentrates in Botswana's Kalahari copper belt and Zambia's Copperbelt Province, where mining houses favor rental over ownership for balance-sheet optimization.
- Lifting Equipment:Mobile cranes, tower cranes, and telehandlers with ISO 4309 rope inspection certification requirements. South Africa's Northern Cape solar installations and Namibia's wind zones drive utilization, with project-based leasing displacing dry-hire arrangements.
- Material Handling Devices:Forklifts and warehouse equipment serving Gauteng province's logistics corridor distribution centers.
- Concrete Equipment:Batch plants, pumps, and mixers deployed for infrastructure rehabilitation in Angola and Mozambique LNG corridor projects.
- Compaction Machinery:Rollers and plate compactors supporting road construction across SADC member states with varying certification standards.
Earthmoving machines hold the largest share; momentum sits with lifting equipment as renewable energy installation accelerates.
Rental Duration:
Duration structures align with customer cash-flow volatility, with short-term contracts dominating transaction volume among building contractors while project-based leasing captures premium margins from infrastructure developers.
- Short-Term:Daily to weekly arrangements for building contractors managing cash-flow volatility in South Africa's residential construction sector.
- Medium-Term:Monthly contracts serving civil engineering projects with defined but extended timelines.
- Long-Term:Multi-year fleet deployments for mining operations in Botswana and Zambia with predictable extraction schedules.
- Project-Based Leasing:Comprehensive bundles integrating operator certification, maintenance liability, and fuel management. Renewable energy EPC contractors in Namibia and South Africa's Northern Cape mandate this structure for risk transfer.
Short-term contracts generate highest transaction frequency; project-based leasing delivers superior margin capture.
Customer Category:
Customer segmentation reveals divergent compliance sophistication, with mining firms and infrastructure developers demanding certified fleet providers while building contractors prioritize rate competitiveness.
- Building Contractors:Residential and commercial construction operators in Gauteng province selecting rental providers based on rate competitiveness and equipment availability.
- Civil Engineers:Road, bridge, and water infrastructure specialists requiring cross-border fleet mobility between South Africa, Botswana, and Zambia.
- Infrastructure Developers:Large-scale project sponsors in Mozambique's LNG corridor and Angola's reconstruction phase demanding comprehensive service integration.
- Mining Firms:Copper and platinum operators in Zambia's Copperbelt Province and South Africa's Bushveld belt mandating real-time equipment telemetry as contract precondition.
Mining firms command premium fleet allocation; infrastructure developers are expanding most quickly as energy corridor investments mature.
Service Offering:
Service bundling separates capitalized operators from informal competitors, with compliance infrastructure becoming the decisive procurement criterion under evolving SADC regulatory frameworks.
- Maintenance & Repair:Predictive maintenance enabled by telematics-integrated IoT sensors, with uptime guarantees differentiating premium operators.
- Operator Supply:Certified technician provision addressing South Africa's Department of Higher Education trade certification bottlenecks.
- Equipment Delivery:Logistics coordination for cross-border deployment, complicated by non-harmonized equipment certification requirements.
- Insurance Coverage:Liability bundling covering asset damage and operator risk, increasingly required under South Africa's Occupational Health and Safety Act inspection regimes.
Maintenance & repair anchors customer retention; operator supply faces steepest expansion constraints from technician scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining houses and infrastructure developers dominate procurement across Southern Africa, with fleet deployment patterns tracking copperbelt expansion and renewable energy corridors rather than population density.
South Africa
Gauteng province's logistics corridor concentrates material handling demand from distribution centers and last-mile fulfillment networks. The Department of Labour Construction Regulations mandate ISO 4309 crane rope inspection certification, elevating compliance costs for independent operators. Johannesburg and Pretoria anchor the premium fleet segment where certified providers capture procurement consolidation from risk-averse contractors.
Zambia
Copperbelt Province drives earthmoving utilization as mining houses expand exploration activity across the Kalahari copper belt. The Mines Safety Department equipment standards restrict market access to capitalized players with technical audit infrastructure. Kitwe and Ndola host the densest equipment clusters where rental providers coordinate cross-border fleet mobility with Botswana operations.
Botswana
Kalahari copper belt exploration is restructuring equipment access models as balance-sheet optimization overrides traditional ownership preferences. The Department of Roads equipment certification requirements create redundant compliance expenditure for cross-border deployment from South Africa. Gaborone and Francistown serve as logistics nodes for fleet rotation between mining camps and maintenance facilities.
Namibia
Northern Cape-adjacent wind development zones and domestic solar installations accelerate demand for specialized lifting equipment with rapid deployment requirements. The country's national mining and energy regulator enforces equipment safety protocols aligned with South African standards. Walvis Bay and Windhoek concentrate project-based leasing activity where renewable energy EPC contractors mandate comprehensive service integration.
Mozambique
Northern Mozambique's emerging LNG corridor remains underpenetrated by established rental networks despite infrastructure investment acceleration. The national petroleum regulator and construction safety authority are developing equipment certification frameworks for foreign operator entry. Pemba and Palma present first-mover positioning opportunities for compliant operators with cross-border logistics capabilities.
Southern Africa Construction Equipment Rental Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive maintenance infrastructure, creating tiered competition between capitalized fleet operators and regional specialists. Market structure concentrates around three archetypes: dealership-networked providers leveraging southern African parts distribution, mining-focused operators with telemetry-integrated fleet management, and project-based lessors bundling compliance and operator certification. Dominant competitive moves include geographic expansion into underpenetrated energy corridors and technology partnerships for predictive maintenance capabilities.
Among South Africa-anchored conglomerates, Barloworld occupies a position exemplifying dealership-networked scale, while Goscor Group represents specialized material handling distribution within the industrial heartland. Babcock International sits within the service-bundling archetype, anchoring competitive differentiation through operator training integration rather than pure asset provision. These three entities collectively illustrate the compliance-infrastructure barrier that separates formal operators from informal competitors across SADC jurisdictions.
| Leading Market Players |
|---|
| Barloworld |
| Alistair Group |
| Adima Hire |
| Atlas Crane Hire |
| Anglo V3 Crane Hire |
| Coastal Hire |
| Goscor Group |
| enX Equipment |
| Babcock International |
| Others |
Cost & Logistics Intelligence
Diesel-to-electric fleet substitution is redrawing procurement geography across Southern Africa, compressing fuel-linked pricing models while elevating capital recovery premiums for compliant battery-electric earthmovers. Mining houses in Botswana's Kalahari copper belt and Zambia's Copperbelt Province now demand ISO 4309-certified lifting equipment with telematics integration, bifurcating rate structures between data-enabled providers and rate-based competitors.
Pricing Analysis
Cost-plus contracts with diesel price indexation dominate long-term mining fleet arrangements, though project-based leasing for renewable energy EPC contractors bundles operator certification and maintenance liability into fixed-price accountability. Price differentiation hinges on ISO 4309 compliance grade and real-time telemetry capability, with certified providers commanding premium positioning over informal operators. Cost compression in short-term dry-hire segments is intensifying because building contractors in Gauteng province prioritize rate competitiveness over service bundling. Mining firms exhibit least price sensitivity, accepting premium rates for uptime guarantees and cross-border logistics coordination.
Supply Chain Analysis
Strategic stockpiling of hydraulic systems and electronic control modules supersedes just-in-time preferences, as extended lead times from European and Asian manufacturing hubs expose fleet operators to utilization risk. Supply concentrates in Germany, Japan, and China for precision-engineered components, while South Africa anchors regional assembly and aftermarket service infrastructure. Raw material dependencies span high-grade steel for crane structures, specialized hydraulic fluids, and semiconductor modules for telematics integration. Single-source vulnerability for electronic control systems creates procurement fragility. Distribution runs through Barloworld's southern African dealership network and Goscor Group's industrial heartland logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southern Africa's construction equipment rental market sits in early-cycle expansion, with copperbelt mining activity and renewable energy corridor investments driving penetration gains ahead of traditional ownership models.
For Market Incumbents: Fortify compliance infrastructure investments against ISO 4309 certification mandates from South Africa's Department of Labour, while deepening captive maintenance capabilities to offset technician scarcity bottlenecks. Expand cross-border fleet mobility coordination between Botswana and Zambia to capture Copperbelt Province utilization growth. Backward integration into predictive maintenance technology partnerships will differentiate uptime guarantees from rate-based competitors. For New Entrants and Emerging Players: ISO 4309 fast-track certification programs offer market entry acceleration, particularly for telematics-integrated lifting equipment serving Namibia's wind development zones and South Africa's Northern Cape solar installations. Northern Mozambique's LNG corridor presents the most penetrable geography, with underdeveloped rental networks and emerging equipment certification frameworks from the national petroleum regulator. Joint venture structures with local construction consortia provide the strongest go-to-market angle for project-specific fleet deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mining-focused operators possessing telemetry-integrated fleet management platforms but limited cross-border logistics scale. Long-term viability over a multi-year horizon rests on SADC regulatory harmonization progress and AfCFTA technical barriers-to-trade protocol alignment. Acquisition targets should demonstrate in-house technical audit capacity and certified technician pipelines. The signal to watch is harmonization pressure between SADC member state equipment standards and emerging continental trade protocols; acceleration would warrant portfolio rebalancing toward compliant fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time equipment telemetry from Barloworld and Babcock International satisfies mining contract preconditions across Botswana's Mowana operations. |
| ISO 4309 Certification Investment | Crane rope inspection compliance separates formal operators from informal competitors under South Africa's Department of Labour Construction Regulations. |
| Cross-Border Logistics Expansion | Fleet mobility coordination between Kitwe, Ndola, and Gaborone captures copperbelt utilization concentration across Zambia and Botswana. |
| Predictive Maintenance Partnership | IoT sensor convergence with machine learning enables outcome-based uptime guarantees that differentiate premium fleet operators from rate-based rivals. |
| Renewable Energy Service Bundling | Project-based leasing integrating operator certification and fuel management displaces dry-hire arrangements in Namibia's wind zones and South Africa's Northern Cape. |
Research Approach
The analysis maps earthmoving machines, lifting equipment, material handling devices, concrete equipment, and compaction machinery segments, each validated through fleet managers, maintenance directors, mining procurement officers, and EPC contractor equipment planners. Primary interviews with rental provider executives, OEM aftermarket service heads, and SADC regulatory affairs specialists combined with secondary validation from customs and trade data, Department of Labour enforcement records, Mines Safety Department equipment standard filings, and copperbelt mining project development databases. Bottom-up equipment utilization modeling and top-down market sizing triangulated against cross-border fleet deployment patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning equipment type, rental duration structure, customer category sophistication, and service offering bundling. CAGRs derived from equipment replacement cycles, mining capital expenditure trajectories, and renewable energy installation pipelines. Forecast inputs incorporated copper price volatility effects on fleet access model preferences and diesel price regulatory adjustment cycles in South Africa.
Decision-makers should treat outputs as directional under stable SADC regulatory fragmentation and copperbelt exploration continuity assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without certainty guarantees. Revision becomes warranted when AfCFTA technical barriers-to-trade protocol harmonization crosses implementation thresholds or when copper price movements alter mining house balance-sheet optimization preferences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Snow Removal Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Draw Heat Setting Winder Market