
 Excavation Equipment Market | 2026-2036
Excavation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Excavation Equipment Market Analytics
Modular attachment bundling is consolidating buyer preference around versatile base machines rather than purpose-built units. Caterpillar leverages its proprietary hydraulic architecture to anchor premium positioning in large-scale mining contracts. Komatsu sustains technology leadership through integrated machine control and telematics platforms. JCB specializes in compact excavator configurations for constrained European construction sites.
Excavation equipment comprises heavy-duty earthmoving machinery employing hydraulic systems, boom-arm assemblies, and rotating house structures to dig, lift, and load materials across variable terrain and depth specifications. Hydraulic excavators dominate volume shipments due to their power density and attachment versatility in pipeline trenching and foundation work. The technology dimension shows electric-powered and hybrid configurations gaining traction as site-level emissions restrictions tighten, while the rental market segment expands as contractors prioritize fleet flexibility over capital commitment.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by national type-approval authorities mandate particulate matter and nitrogen oxide reductions, compelling engine redesigns and after-treatment investments. China's MIIT enforces GB standards on non-road mobile machinery, creating divergent compliance pathways for multinational manufacturers. Equipment purchasers must weigh total cost of ownership implications across regulatory jurisdictions when standardizing fleet specifications.
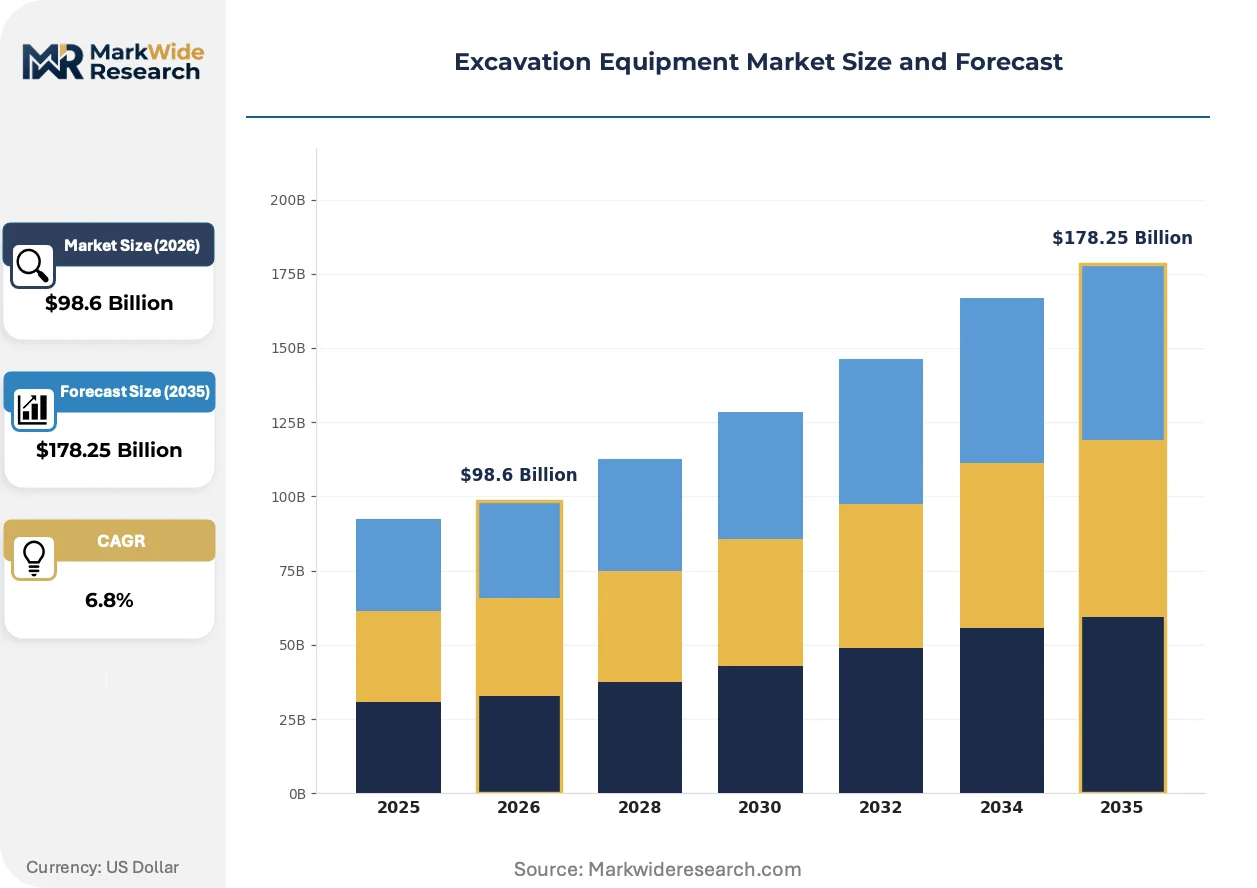
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing engine architecture choices while accelerating electric and hybrid platform development across manufacturer lineups.
Growth Catalysts
- Urban Renewal Infrastructure:China's high-speed rail extensions and metropolitan corridor densification are pulling crawler and long-reach excavator deployments into sustained procurement cycles.
- Emissions Compliance Deadlines:EPA Tier 4 Final enforcement in the United States is forcing fleet replacement decisions that favor compliant Tier 4 Final and Stage V machines over grandfathered equipment.
- Telematics Integration:Machine control platforms embedding GPS grading and fuel telemetry are reducing site labor hours and improving earthwork precision for pipeline contractors.
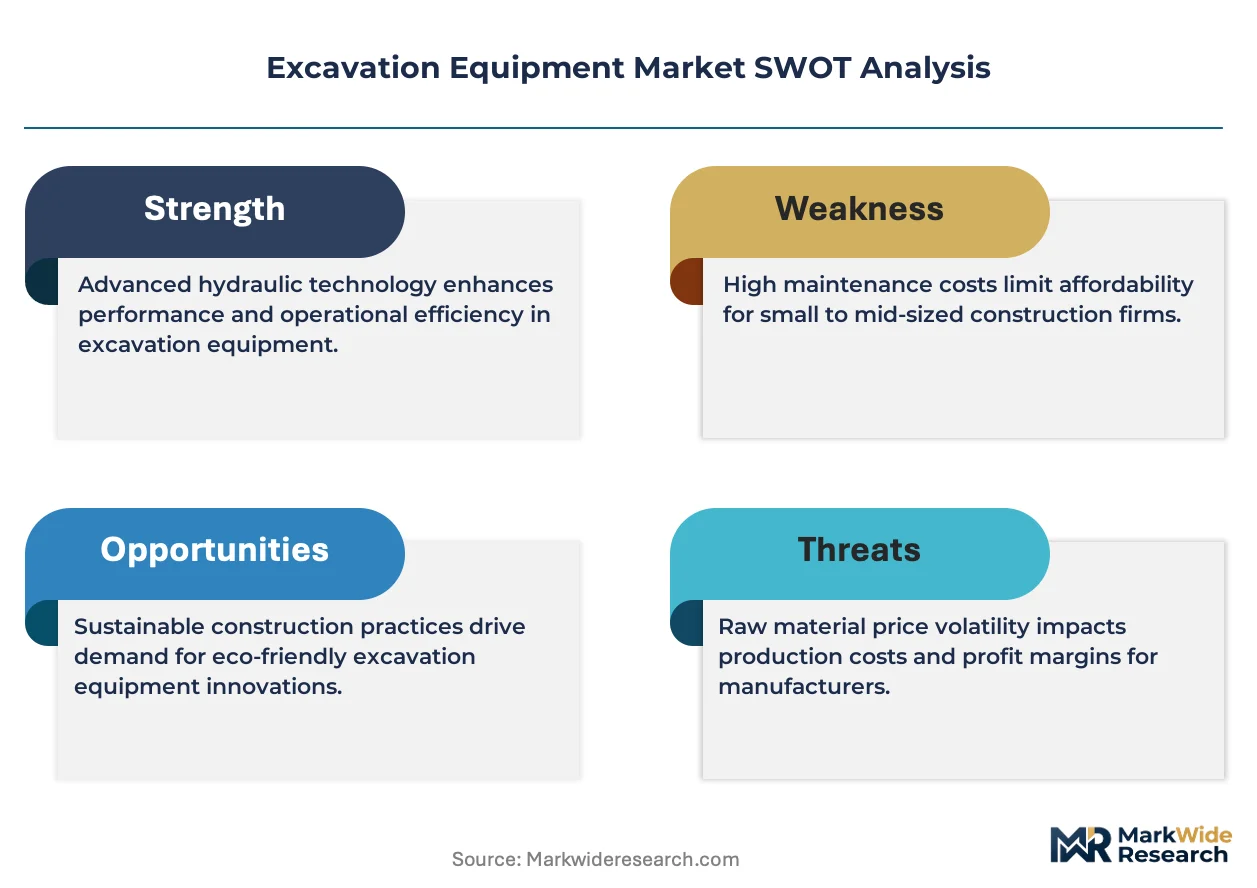
Market Restraints
- Engine Redesign Costs:After-treatment systems for particulate matter and nitrogen oxide reduction add material cost layers that compress margin structures for mid-tier manufacturers.
- Steel Input Volatility:Boom-arm fabrication and undercarriage components depend on structural steel pricing that fluctuates with scrap and iron ore indices.
- Skilled Operator Scarcity:GPS-integrated machine control requires certified operators, and training pipeline gaps in North America and Europe constrain fleet utilization rates.
Strategic Opportunities
- Rental Channel Expansion:Equipment-as-a-service models allow contractors in Germany and France to access Tier 4 Final-compliant fleets without capital commitment.
- Battery-Electric Trenching:Zero-emission compact excavators unlock urban construction sites with noise ordinances and indoor demolition applications.
- Modular Attachment Ecosystems:Quick-coupler standardization across hydraulic architectures lets base machines serve multiple work functions, reducing total fleet counts.
Industry Challenges
- Cross-Border Certification Timelines:GB standard approval from China's MIIT runs parallel to EPA and EU type-approval processes, fragmenting product launch synchronization.
- Legacy Fleet Integration:Telematics retrofitting for pre-Tier 4 Final machines faces CAN bus protocol incompatibilities that limit data uniformity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excavation Equipment Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Excavators, Mini Excavators, Crawler Excavators, Wheeled Excavators End User: Construction, Mining, Landscaping, Demolition Technology: Remote-Controlled, Automated, Electric-Powered, Hybrid Market Segment: New Equipment, Used Equipment, Rental, Aftermarket |
| Companies Covered | Caterpillar, Komatsu, Hitachi Construction Machinery, Volvo Construction Equipment, Liebherr Group, Doosan Infracore, Hyundai Construction Equipment, JCB, Sany Heavy Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excavation Equipment Market Evolving Landscape
Electrification is compressing powertrain development cycles while regulatory deadlines force simultaneous compliance across multiple emissions jurisdictions. Manufacturers are embedding connectivity as a baseline feature rather than premium tier.
Battery-electric excavator platforms are electrifying compact and mid-size machine categories first. Urban contractors in London and Amsterdam are adopting 10-15 ton electric units for foundation work and utility trenching where diesel bans apply. This shift is electrifying equipment specification criteria for municipal procurement departments that now weight emissions performance alongside operating cost.
EU Stage V standards enforced by national type-approval authorities mandate real-driving emissions verification for non-road mobile machinery. Engine manufacturers must redesign combustion chambers and deploy selective catalytic reduction systems. Mining contractors in Sweden and quarry operators in Spain face the steepest retrofit costs for legacy fleets operating beyond 8,000 annual hours.
Short-term rental and subscription-based fleet access are displacing traditional equipment financing among mid-size European contractors. Rental companies in France and the United Kingdom are expanding telematics-enabled fleets that bill by engine hour and GPS-verified productivity. This model concentrates most visibly in urban renewal corridors where project duration uncertainty makes ownership risk prohibitive.
Excavation Equipment Market Segmentation
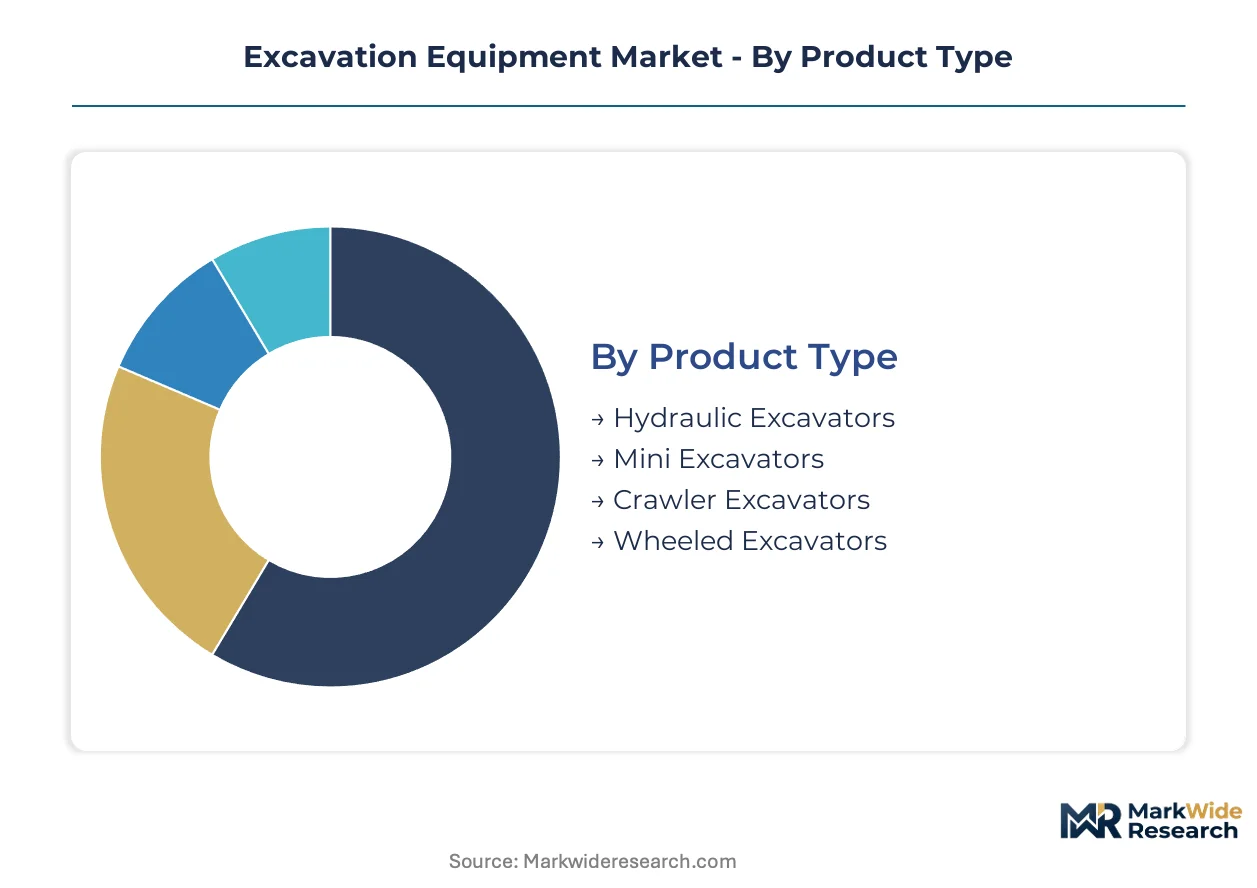
Excavation equipment segmentation reveals divergent compliance burdens across product configurations, with emissions standards fragmenting procurement criteria by machine size and powertrain architecture. Understanding these divides allows manufacturers to align R&D spending with regulatory enforcement timelines and end-use concentration patterns.
Product Type:
EPA Tier 4 Final certification applies universally across this category, though engine displacement thresholds create divergent after-treatment cost structures that reshape competitive positioning by size class.
- Hydraulic Excavators:Standard-configuration machines employing piston-pump hydraulic circuits and boom-arm kinematics rated above 20 metric tons. Fleet procurement in China's high-speed rail corridors sustains demand for 30-40 ton units with extended reach configurations, though Tier 4 Final after-treatment systems add material cost premiums that compress mid-tier manufacturer margins.
- Mini Excavators:Compact units under 6 metric tons operating on zero-tail-swing or conventional house designs. Urban renewal projects in London and Amsterdam are electrifying specification criteria for 1.5-3.5 ton electric units where diesel bans apply, making this segment the fastest-climbing category by unit volume in European municipal procurement.
- Crawler Excavators:Tracked undercarriage systems for uneven terrain applications.
- Wheeled Excavators:Rubber-tired configurations for paved surface mobility and rapid site relocation.
Leading the category by volume: Hydraulic Excavators. Expanding most quickly: Mini Excavators.
End User:
Cost tier segmentation separates capital-intensive mining procurement from rental-dependent construction contracting, with total cost of ownership calculations varying dramatically across ownership models.
- Construction:General contracting, infrastructure, and commercial building applications. Pipeline trenching contractors in the United States prioritize telematics-integrated units with GPS grading to reduce labor hours and improve earthwork precision, concentrating demand in the 20-30 ton hydraulic class for foundation and utility work.
- Mining:Surface extraction and quarry operations requiring continuous-duty cycles. Swedish mining contractors face the steepest Stage V retrofit costs for legacy fleets operating beyond 8,000 annual hours, forcing replacement decisions toward compliant new equipment rather than grandfathered machines.
- Landscaping:Residential and commercial grounds maintenance with compact machine requirements.
- Demolition:Structural teardown applications with specialized attachment needs.
Construction commands the largest revenue share. Mining shows the steepest expansion trajectory for compliant fleet replacement.
Technology:
Volume concentration favors conventional configurations, though regulatory deadlines are accelerating electric and hybrid platform development across manufacturer lineups.
- Remote-Controlled:Operator-removed systems for hazardous environment entry. Demolition contractors in Japan deploy these units for unstable structure work where collapse risk prohibits cab occupancy, with METI safety standards driving specification requirements.
- Automated:GPS-integrated machine control with semi-autonomous grading and trenching functions. North American pipeline contractors adopt these platforms to offset skilled operator scarcity, though training pipeline gaps constrain fleet utilization rates despite technology availability.
- Electric-Powered:Battery-electric powertrains with zero tailpipe emissions.
- Hybrid:Diesel-electric architectures optimizing fuel consumption across variable load cycles.
Automated systems lead by installed base growth. Electric-Powered configurations gain share fastest in urban emission-restricted zones.
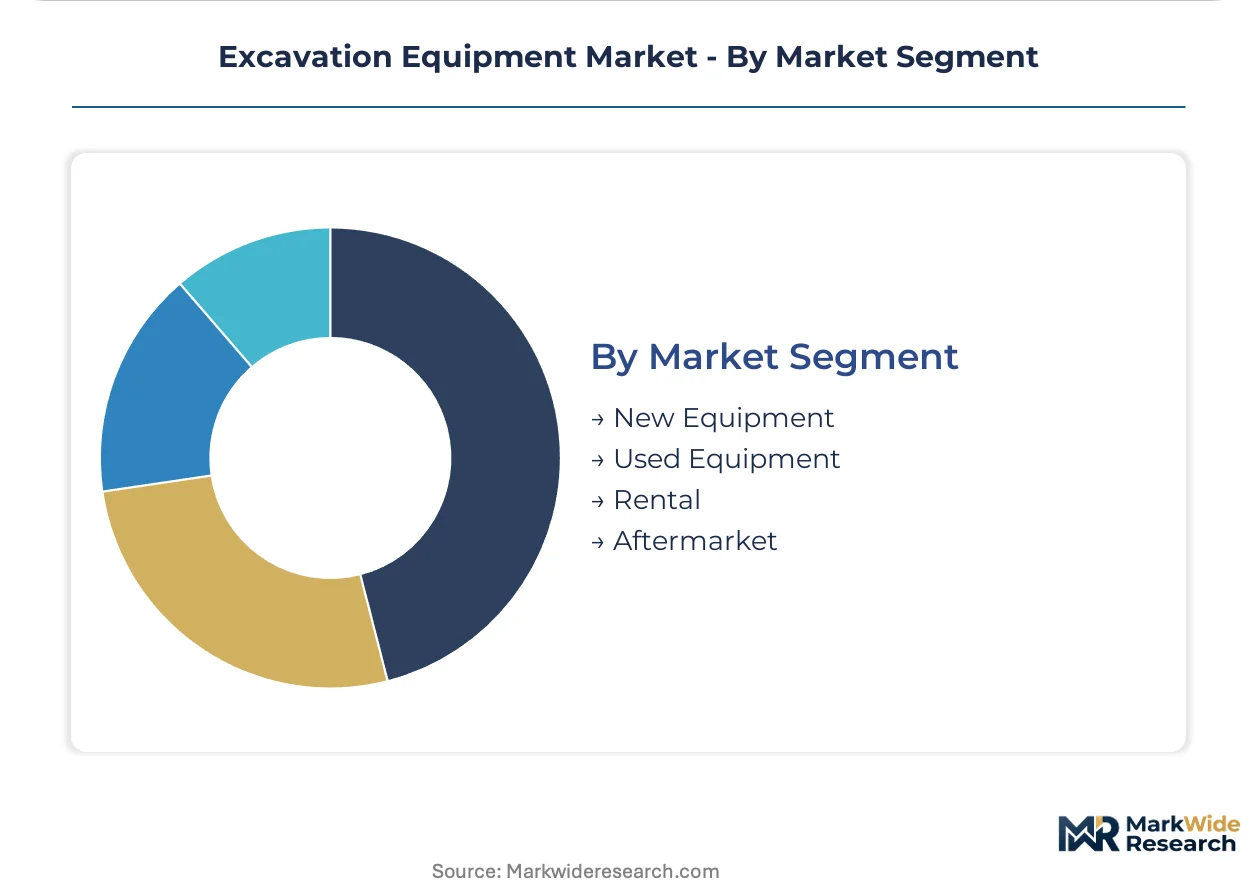
Market Segment:
Customer type segmentation distinguishes capital ownership from operational expenditure models, with rental channel expansion displacing traditional financing among mid-size European contractors.
- New Equipment:Factory-delivered machines with full warranty and latest emissions compliance. OEMs in Germany and France anchor premium positioning through telematics-enabled fleets that bill by engine hour and GPS-verified productivity, concentrating in urban renewal corridors where project duration uncertainty makes ownership risk prohibitive.
- Rental:Short-term and subscription-based fleet access without capital commitment. Equipment-as-a-service models allow contractors to access Tier 4 Final-compliant fleets while preserving balance sheet flexibility, with rental companies expanding most visibly in France and the United Kingdom.
- Used Equipment:Pre-owned machines trading in secondary markets.
- Aftermarket:Parts, service, and maintenance revenue streams.
Rental leads by transaction velocity. New Equipment retains the highest revenue concentration per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global excavation equipment output while the United States and Germany absorb premium-tier imports for infrastructure renewal and mining applications. Domestic production in Japan and South Korea supplies regional demand with technology-integrated platforms. Regulatory divergence across EPA, EU Stage V, and China's MIIT GB standards fragments certification pathways for multinational suppliers.
China
Urban renewal corridors in Beijing, Shanghai, and Guangzhou drive crawler excavator procurement for high-speed rail extensions and metro densification. MIIT enforces GB standards on non-road mobile machinery, compelling engine redesigns for domestic and export-bound equipment. The Yangtze River Delta cluster concentrates manufacturing capacity for 30-40 ton hydraulic units serving Belt and Road infrastructure contracts.
United States
Pipeline trenching contractors across Texas, Pennsylvania, and North Dakota prioritize telematics-integrated excavators with GPS grading capabilities. EPA Tier 4 Final enforcement compresses replacement cycles for aging construction fleets in the Midwest and Southeast. The Permian Basin oil patch sustains demand for 20-30 ton units in energy infrastructure development despite commodity price volatility.
Germany
Rental channel expansion in Bavaria and North Rhine-Westphalia displaces traditional equipment financing among mid-size contractors. EU Stage V standards mandate selective catalytic reduction systems, elevating after-treatment costs for quarry operators in the Ruhr industrial zone. Stuttgart-based engineering clusters anchor precision manufacturing for compact excavators serving constrained European construction sites.
Japan
Demolition contractors in Tokyo and Osaka deploy remote-controlled excavators for unstable structure work where collapse risk prohibits cab occupancy. METI safety standards drive specification requirements for operator-removed systems in seismic retrofit projects. The Chubu region around Nagoya maintains component supply chains for hydraulic architecture and machine control platforms.
India
Highway construction and urban metro projects in Maharashtra, Gujarat, and Karnataka pull excavator deployments into sustained procurement cycles. The Ministry of Road Transport and Highways accelerates infrastructure spending through Bharatmala and Sagarmala corridor programs. The Delhi-Mumbai Industrial Corridor concentrates equipment demand for freight corridor earthworks and smart city development.
Excavation Equipment Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive engine and hydraulic component capabilities. Tier 1 positions concentrate among North American, European, and Japanese manufacturers with integrated technology platforms and established rental channel partnerships. Three archetypes dominate: full-line diversified industrials, specialized compact equipment specialists, and emerging Asia-Pacific scale players. Consolidation pressure manifests through strategic partnerships for electric powertrain development and geographic expansion into emission-restricted urban markets.
Among the full-line diversified tier, Caterpillar, Komatsu, and Hitachi Construction Machinery occupy positions defined by proprietary hydraulic architecture and integrated telematics ecosystems. These manufacturers anchor premium positioning in large-scale mining and infrastructure contracts through technology bundling rather than equipment-only sales. JCB exemplifies the compact specialization archetype with zero-tail-swing configurations engineered for European urban constraints. Sany Heavy Industry represents the scale-driven Asia-Pacific vector, leveraging domestic production cost structures for export market penetration.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| Liebherr Group |
| Doosan Infracore |
| Hyundai Construction Equipment |
| JCB |
| Sany Heavy Industry |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Germany and Japan anchor boom-arm and undercarriage component supply, translating captive engineering expertise into pricing discipline that resists commoditization despite steel input volatility. Their ownership structures favor long-term supplier relationships over spot-market procurement, embedding cost stability into Tier 4 Final after-treatment system pricing.
Pricing Analysis
Margin tightening in mid-tier hydraulic excavators reflects Tier 4 Final after-treatment system premiums that OEMs struggle to pass through to price-sensitive municipal contractors. Three-tier pricing structure across premium telematics-integrated, standard compliant, and economy grandfathered tiers separates Caterpillar and Komatsu from regional challengers. Pricing pressure stems from EPA enforcement compressing replacement windows for aging fleets. Rental channel buyers exhibit highest price sensitivity; mining contractors with 8,000-plus annual hour operations show lowest.
Supply Chain Analysis
Dual-sourcing mandates from Volvo Construction Equipment and Hitachi Construction Machinery require qualified suppliers for hydraulic pumps across Germany, Japan, and South Korea. Boom-arm fabrication draws from Swedish structural steel and Chinese castings, with engine blocks sourced from Japanese and US foundries. Single-source vulnerability concentrates in selective catalytic reduction catalyst substrates. Distribution runs through OEM-owned dealer networks and independent rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engine redesign capacity for Tier 4 Final and Stage V compliance operates at effective constraint, propping aftermarket pricing for retrofit kits and compliant new equipment through the projection horizon.
For Market Incumbents: Acquire electric powertrain engineering capabilities to neutralize battery-electric entrant threat in compact excavator categories. Backward integration into hydraulic pump manufacturing secures margin against Bosch Rexroth and Kawasaki supply allocation. Priority lever: captive telematics platform development locking pipeline contractors into subscription ecosystems. For New Entrants and Emerging Players: Digital rental platform routes through equipment-as-a-service aggregators in France and the United Kingdom bypass capital-intensive dealer network buildout. White-space targets include 1.5-3.5 ton electric units for Amsterdam and London diesel-ban corridors, plus telematics retrofit kits for pre-Tier 4 Final legacy fleets. Go-to-market: municipal procurement direct sales bypassing established OEM channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier hydraulic component specialists in China's Yangtze River Delta with GB standard certification and Belt offtake relationships. Long-term viability hinges on electrification R&D spend ratios and MIIT compliance track records. Signal to watch: MIIT acceleration of GB Stage IV-equivalent timelines forcing premature legacy fleet obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Platform Development | Battery-electric compact excavators unlock Amsterdam and London municipal procurement where diesel bans apply. |
| Telematics Integration Partnership | GPS grading and fuel telemetry subscriptions reduce pipeline contractor labor hours while locking recurring revenue. |
| Backward Integration into Hydraulics | In-house piston-pump production insulates margin from Kawasaki and Bosch Rexroth allocation constraints. |
| Rental Channel Expansion | Equipment-as-a-service models in Germany and France displace capital ownership among mid-size contractors. |
| Cross-Border Certification Investment | Parallel EPA, EU Stage V, and MIIT GB approval accelerates product launch synchronization across jurisdictions. |
Research Methodology
Document review covered SEC 10-K filings, EU type-approval authority registers, and MIIT GB standard publications, complemented by interviews with equipment procurement managers at pipeline contractors, aftermarket service directors at rental fleet operators, and hydraulic systems engineers at component suppliers. Secondary validation drew from customs trade data, OEM dealer sales reports, and construction equipment auction transaction records. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending allocations.
Installed base projections across the analysis window segmented by powertrain architecture, machine size class, end-use application, and ownership model. CAGRs derived from regression against historical replacement cycles, regulatory enforcement timelines, and steel price index correlations. Industry-specific inputs included EPA Tier 4 Final compliance cost curves and high-speed rail construction procurement schedules from China's National Railway Administration.
The model holds under stable regulatory enforcement timelines and intact steel supply chains; deviation in MIIT acceleration of emission standards or prolonged iron ore price spikes would shift replacement cycle assumptions and margin projections materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Grader Blades Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Truck Crane Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Global Light Towers Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Hydraulic Breaker for Excavator Market